
 Single Blood Drop Analysis Market | 2026-2036
Single Blood Drop Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
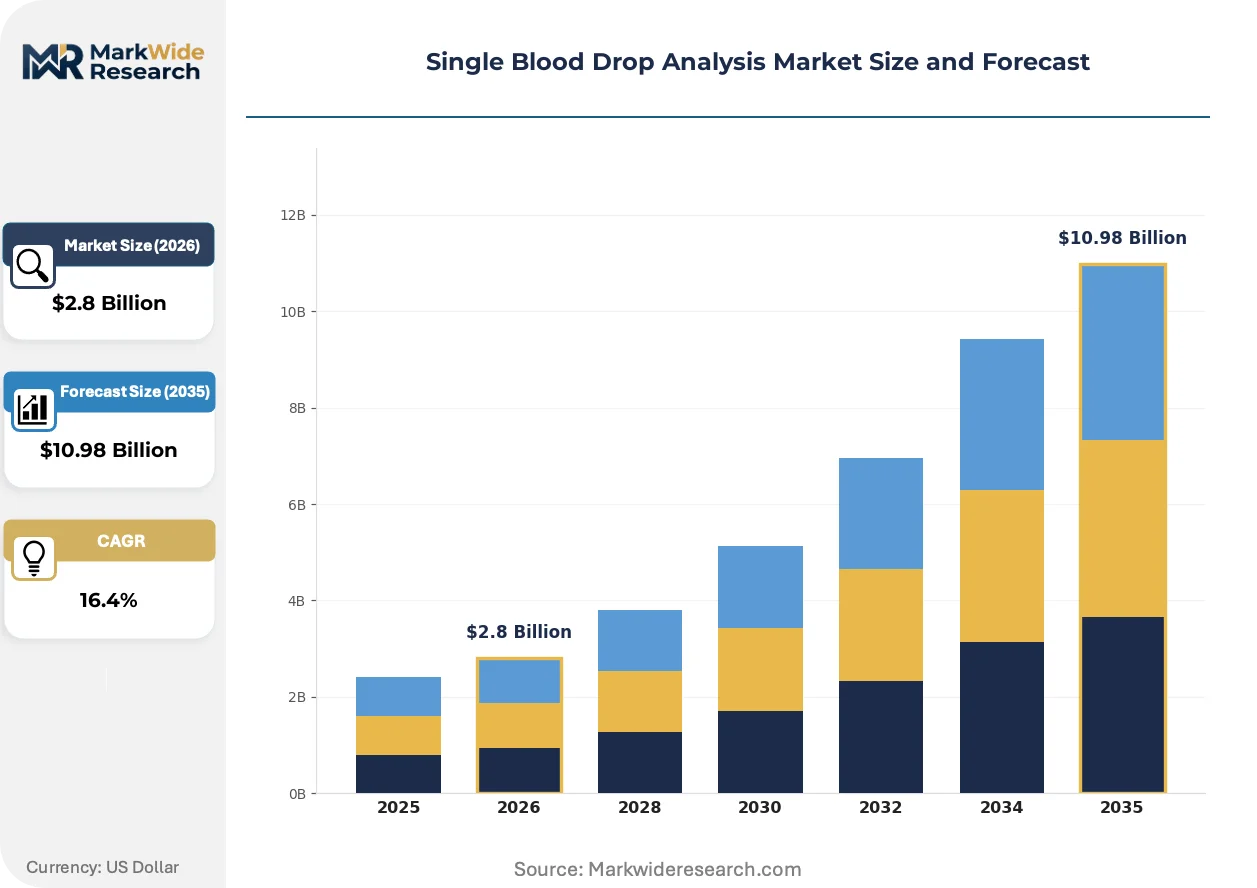
Single Blood Drop Analysis Market Outlook
The capability gap between integrated diagnostic platforms and standalone sensor developers is collapsing as microfluidic manufacturing scales. Abbott Laboratories leverages vertically integrated consumable production to sustain margin control across home care channels. Roche Diagnostics anchors European regulatory positioning through extensive clinical validation programs. Danaher Corporation competes on precision manufacturing scale, extending its dominance in analyzer device assembly.
Single blood drop analysis encompasses micro-volume hematological and biochemical testing using sub-50 microliter samples processed through integrated sensor arrays. Optical detection modules employing fluorescence resonance energy transfer achieve picomolar sensitivity for biomarker quantification in portable formats. Microfluidics technology leads commercial deployment due to established fabrication protocols and reproducible channel geometries. Electrochemical sensors represent the fastest-expanding segment, driven by enzymatic glucose and lactate applications where electrode miniaturization reduces per-test costs. Home care end users command expanding share as Bluetooth-enabled readers integrate with remote monitoring platforms.
FDA premarket notification pathways and CLIA waiver standards shape product development priorities for US market entry. The EU In Vitro Diagnostic Regulation imposes clinical evidence requirements that filter out lower-capability developers before CE marking. Stakeholders must monitor evolving interoperability mandates between point-of-care devices and electronic health record systems as reimbursement increasingly ties to data integration rather than test accuracy alone.
Market Dynamics
Microfluidic manufacturing scale-up is collapsing the cost barrier between centralized laboratory analyzers and portable single-drop platforms, compressing development cycles and redrawing competitive boundaries across diagnostic value chains.
Growth Catalysts
- CLIA Waiver Expansion:FDA streamlined premarket pathways for waived-complexity devices accelerate home care deployment timelines and reduce clinical validation burdens for novel sensor formats.
- Bluetooth-Enabled Remote Monitoring:Home care patients demand seamless data integration with telehealth platforms, pulling decentralized testing adoption beyond traditional facility boundaries.
- Enzymatic Electrochemistry:Electrode miniaturization for glucose and lactate quantification cuts per-test consumable costs, opening chronic disease management to price-sensitive health systems.
Market Restraints
- Polymer Substrate Volatility:Specialized cyclic olefin copolymer prices fluctuate with petrochemical feedstock markets, squeezing consumable margins for microfluidic cartridge producers.
- Reagent Supply Concentration:High-purity enzyme and antibody sourcing clusters in German and Swiss chemical manufacturing corridors, creating single-point vulnerability for electrochemical sensor developers.
- Picomolar Detection Limits:Optical fluorescence resonance energy transfer systems face fundamental signal-to-noise constraints at sub-nanomolar biomarker concentrations without thermal stabilization.
Strategic Opportunities
- Rural India Penetration:Ayushman Bharat digital health infrastructure creates channel access for portable hematology platforms in primary health centers lacking cold-chain logistics.
- EU MDR Clinical Evidence Harmonization:Standardized post-market surveillance requirements reduce redundant studies across member states, lowering regulatory entry costs for mid-cap device developers.
- AI-Assisted Pattern Recognition:Machine learning integration with electrochemical sensor arrays enables multiplexed biomarker panels from single-drop inputs without additional hardware complexity.
Industry Challenges
- Microfabrication Talent Scarcity:Cleanroom process engineering expertise concentrates in semiconductor hubs, forcing diagnostic firms to compete for photolithography specialists against chip manufacturers.
- EHR Interoperability Certification:Health Level Seven International and IEEE 11073 standards compliance adds 12-18 month integration timelines before reimbursement eligibility.
- Patent Thicket Navigation:Dense intellectual property holdings around electrochemical mediator chemistries complicate freedom-to-operate analyses for novel electrode formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Blood Drop Analysis Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microfluidics, Optical Sensors, Electrochemical Sensors, Lab-on-a-Chip End User: Clinics, Hospitals, Home Care, Research Laboratories Application: Diabetes Monitoring, Infectious Disease Testing, Genetic Testing, Lipid Profiling Product Type: Consumables, Analyzer Devices, Software Solutions, Others |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Becton Dickinson, Roche Diagnostics, Philips, Blusense Diagnostics, 1drop Diagnostics, Toray Industries, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Blood Drop Analysis Market Strategic Shifts
Convergence of miniaturized sensing hardware with cloud-native data architectures is reconfiguring how diagnostic value gets captured, shifting revenue models from device sales toward longitudinal patient monitoring subscriptions.
Photonic ring resonator biosensors is fragmenting the incumbent optical detection landscape by enabling label-free biomarker quantification through silicon nitride waveguide structures. Chronic disease management programs in Nordic health systems adopt these platforms for home-based inflammatory marker tracking. The technology is fragmenting traditional fluorescence-based instrument markets by eliminating conjugate reagent costs and reducing calibration frequency.
EU In Vitro Diagnostic Regulation clinical evidence requirements filter lower-capability developers before CE marking authorization. Extensive performance evaluation and post-market surveillance obligations favor firms with dedicated regulatory affairs infrastructure. European reference laboratories accelerate validation partnerships to secure notified body approval ahead of 2027 certificate renewal deadlines.
Hospital procurement departments consolidate point-of-care testing contracts under centralized laboratory governance models. Integrated delivery networks in Texas and Florida negotiate multi-year sole-source agreements covering analyzers, consumables, and informatics integration. This concentration shifts vendor selection criteria toward total cost of ownership calculations rather than per-test pricing alone.
Single Blood Drop Analysis Market Segmentation
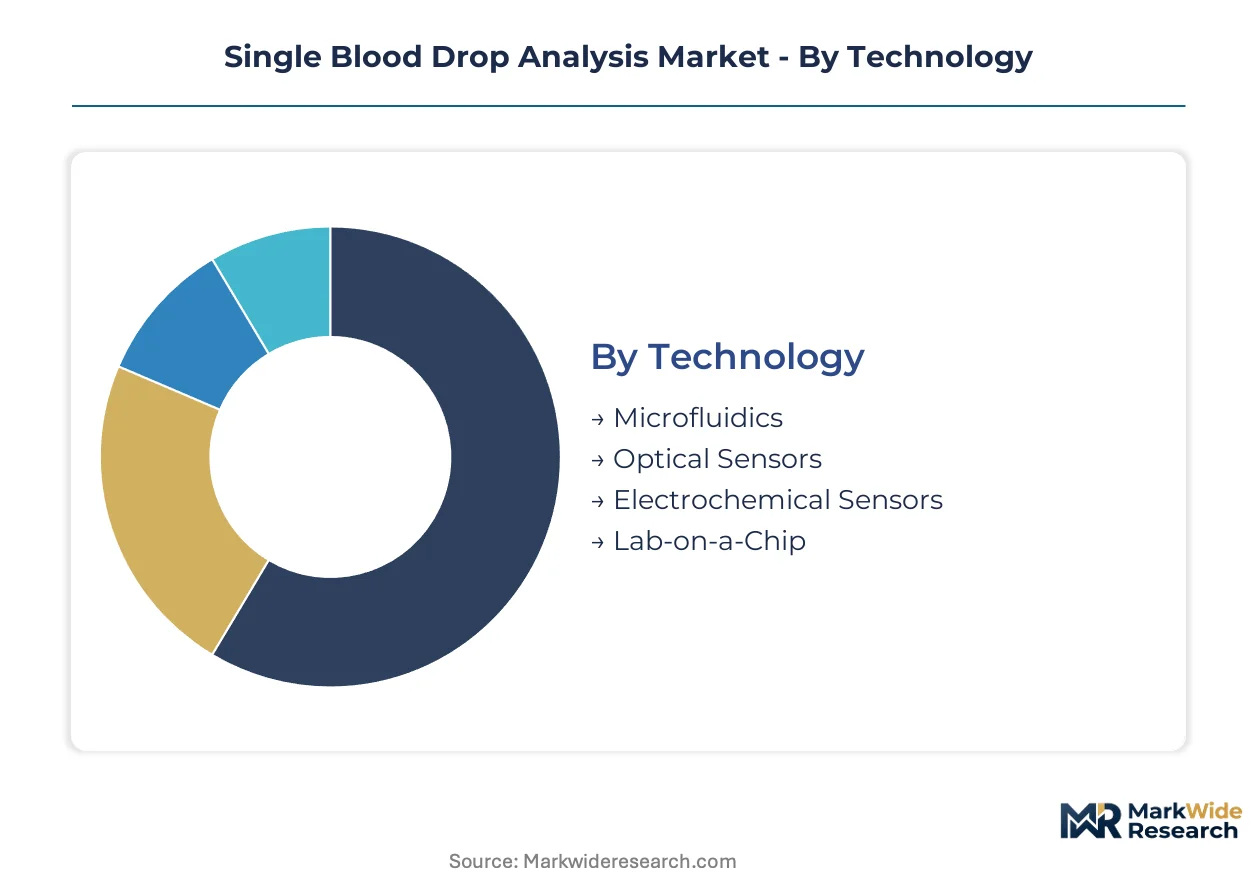
Technology choice determines regulatory pathway complexity and manufacturing capital intensity for single blood drop platforms. End user concentration shapes reimbursement negotiation leverage and service model design across decentralized diagnostic networks.
Technology:
FDA premarket notification requirements and EU MDR clinical evidence standards create divergent approval economics across detection modalities.
- Microfluidics:Established fabrication protocols using cyclic olefin copolymer substrates enable reproducible channel geometries at scale. Home care deployments in the United States favor this technology for its CLIA waiver compatibility and established supply chains.
- Electrochemical Sensors:Enzymatic electrode miniaturization cuts per-test consumable costs for glucose and lactate quantification. German and Swiss chemical corridors concentrate high-purity enzyme sourcing, creating supply vulnerability for developers lacking backward integration.
- Optical Sensors:Fluorescence resonance energy transfer achieves picomolar sensitivity in portable formats. Signal-to-noise constraints at sub-nanomolar concentrations limit expansion beyond inflammatory marker panels.
- Lab-on-a-Chip:Silicon nitride waveguide structures enable label-free biomarker detection through photonic ring resonators. Nordic health systems adopt these for home-based chronic disease tracking.
Microfluidics handles the majority of throughput; electrochemical sensors are climbing the fastest on share.
End User:
Procurement centralization under integrated delivery networks restructures vendor selection criteria toward total cost of ownership calculations.
- Hospitals:Texas and Florida delivery networks negotiate multi-year sole-source agreements covering analyzers, consumables, and informatics integration. Laboratory governance models consolidate point-of-care contracts under centralized procurement.
- Home Care:Bluetooth-enabled readers integrate with remote monitoring platforms as patients seek decentralized diagnostics outside traditional facilities. Reimbursement frameworks in the United States favor portable testing modalities for chronic disease management.
- Clinics:Primary health centers in rural India leverage Ayushman Bharat digital infrastructure for portable hematology platforms lacking cold-chain logistics.
- Research Laboratories:European reference laboratories accelerate validation partnerships to secure notified body approval ahead of certificate renewal deadlines.
Hospitals command the dominant procurement volume; home care is expanding most quickly on addressable population.
Application:
Chronic disease management program design determines test panel breadth and monitoring frequency requirements.
- Diabetes Monitoring:Enzymatic glucose detection drives electrode miniaturization investment and consumable cost reduction. Price-sensitive health systems expand access through per-test economics optimization.
- Infectious Disease Testing:Picomolar sensitivity requirements push optical detection toward thermal stabilization modules. FDA streamlined pathways accelerate deployment for waived-complexity formats.
- Lipid Profiling:Multiplexed biomarker panels from single-drop inputs benefit from AI-assisted pattern recognition with electrochemical sensor arrays.
- Genetic Testing:Label-free quantification through photonic ring resonators eliminates conjugate reagent costs for nucleic acid detection.
Diabetes monitoring carries the highest test frequency; infectious disease testing shows the steepest expansion trajectory.
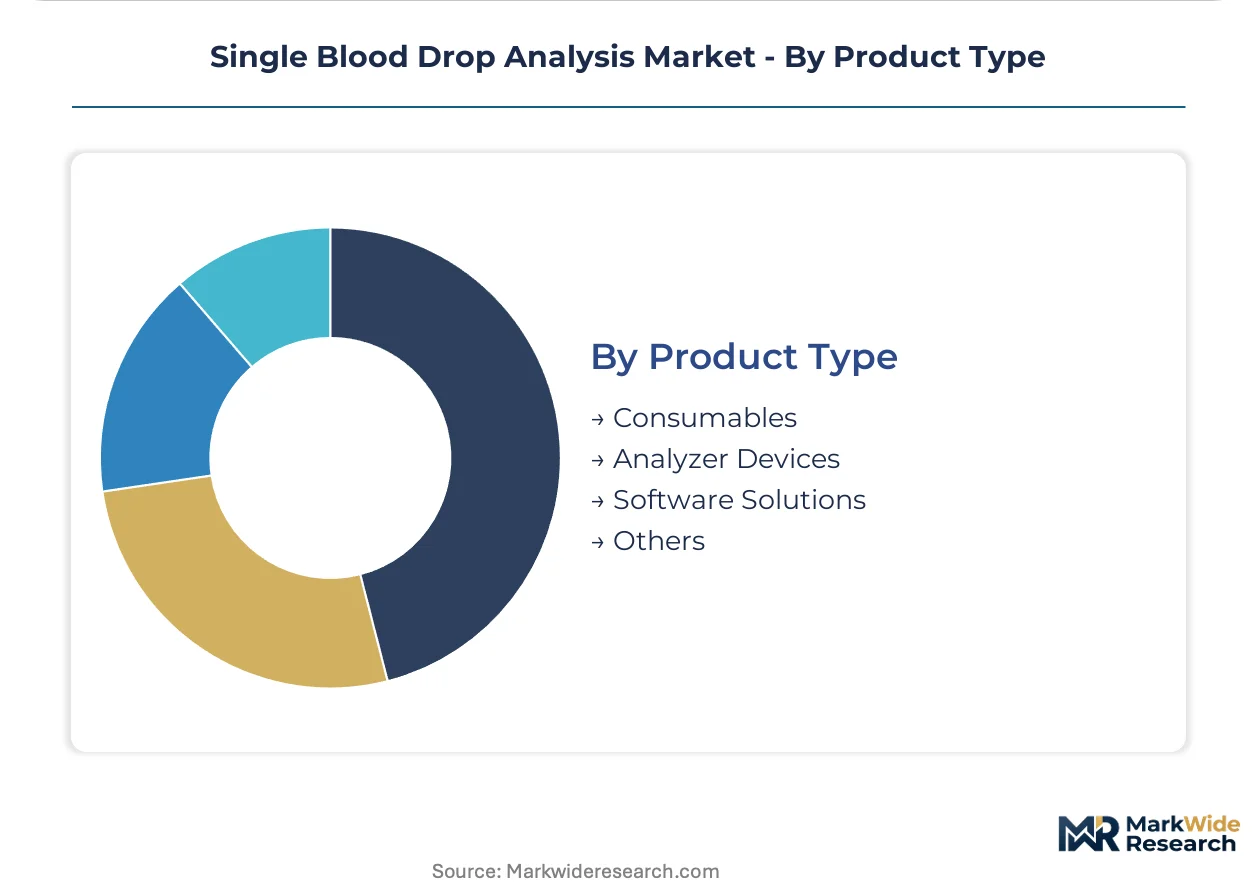
Product Type:
Margin structure diverges sharply between recurring consumable revenue and capital equipment sales with extended replacement cycles.
- Consumables:Microfluidic cartridge production concentrates manufacturing expertise in semiconductor hubs, forcing diagnostic firms to compete for photolithography specialists. Polymer substrate volatility squeezes margins when petrochemical feedstock prices fluctuate.
- Analyzer Devices:Precision manufacturing scale determines competitive positioning for instrument assembly. Danaher Corporation extends dominance through captive production of optical and electromechanical components.
- Software Solutions:Health Level Seven International and IEEE 11073 standards compliance adds integration timelines before reimbursement eligibility. Cloud-native architectures shift revenue models toward longitudinal monitoring subscriptions.
- Others:Calibration standards and quality control materials complete testing workflows for CLIA-certified environments.
Consumables generate the recurring revenue base; software solutions are gaining share fastest on platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium pricing for CLIA-waived home care devices. Indian primary health centers demand sub-dollar per-test economics. European hospitals negotiate total-cost-of-ownership contracts that compress consumable margins.
United States
Chronic disease management programs and Medicare reimbursement frameworks favor portable testing modalities. FDA streamlined premarket pathways for waived-complexity devices accelerate home care deployment timelines. Texas and Florida integrated delivery networks negotiate multi-year sole-source agreements covering analyzers, consumables, and informatics integration.
Germany
High-purity enzyme and antibody sourcing clusters in German chemical manufacturing corridors, creating supply concentration for electrochemical sensor developers. EU In Vitro Diagnostic Regulation clinical evidence requirements filter lower-capability developers before CE marking. Bavarian reference laboratories accelerate validation partnerships to secure notified body approval ahead of 2027 certificate renewal deadlines.
India
Ayushman Bharat digital health infrastructure creates channel access for portable hematology platforms in primary health centers lacking cold-chain logistics. CDSCO regulatory pathways for point-of-care devices are compressing approval timelines for novel sensor platforms. Maharashtra and Karnataka host emerging microfluidic manufacturing clusters serving domestic and export markets.
Japan
Home care patients seek decentralized diagnostics outside traditional facilities, pulling adoption beyond hospital boundaries. PMDA guidance on point-of-care devices emphasizes clinical validation for elderly populations. Tokyo-Osaka corridor concentrates precision manufacturing expertise for optical detection module assembly.
Switzerland
Swissmedic regulatory positioning anchors European clinical validation programs for premium diagnostic platforms. Basel-Zurich corridor concentrates pharmaceutical and diagnostic R&D infrastructure. Swiss chemical manufacturers supply high-purity reagents for enzymatic electrochemistry applications across European markets.
Single Blood Drop Analysis Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated conglomerates dominate precision manufacturing scale and consumable production. Specialized sensor developers compete on detection sensitivity and miniaturization speed. Strategic moves concentrate on backward integration into reagent supply and forward integration into software platforms for remote monitoring.
Among the vertically integrated tier, Abbott Laboratories and Roche Diagnostics represent archetypes of regulatory infrastructure depth and clinical validation scale. Danaher Corporation exemplifies precision manufacturing dominance through captive component production. Siemens Healthineers occupies a position spanning both diagnostic hardware and healthcare IT integration. These anchors demonstrate how competitive positioning depends on controlling consumable economics rather than device margins alone.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Becton Dickinson |
| Roche Diagnostics |
| Philips |
| Blusense Diagnostics |
| 1drop Diagnostics |
| Toray Industries |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
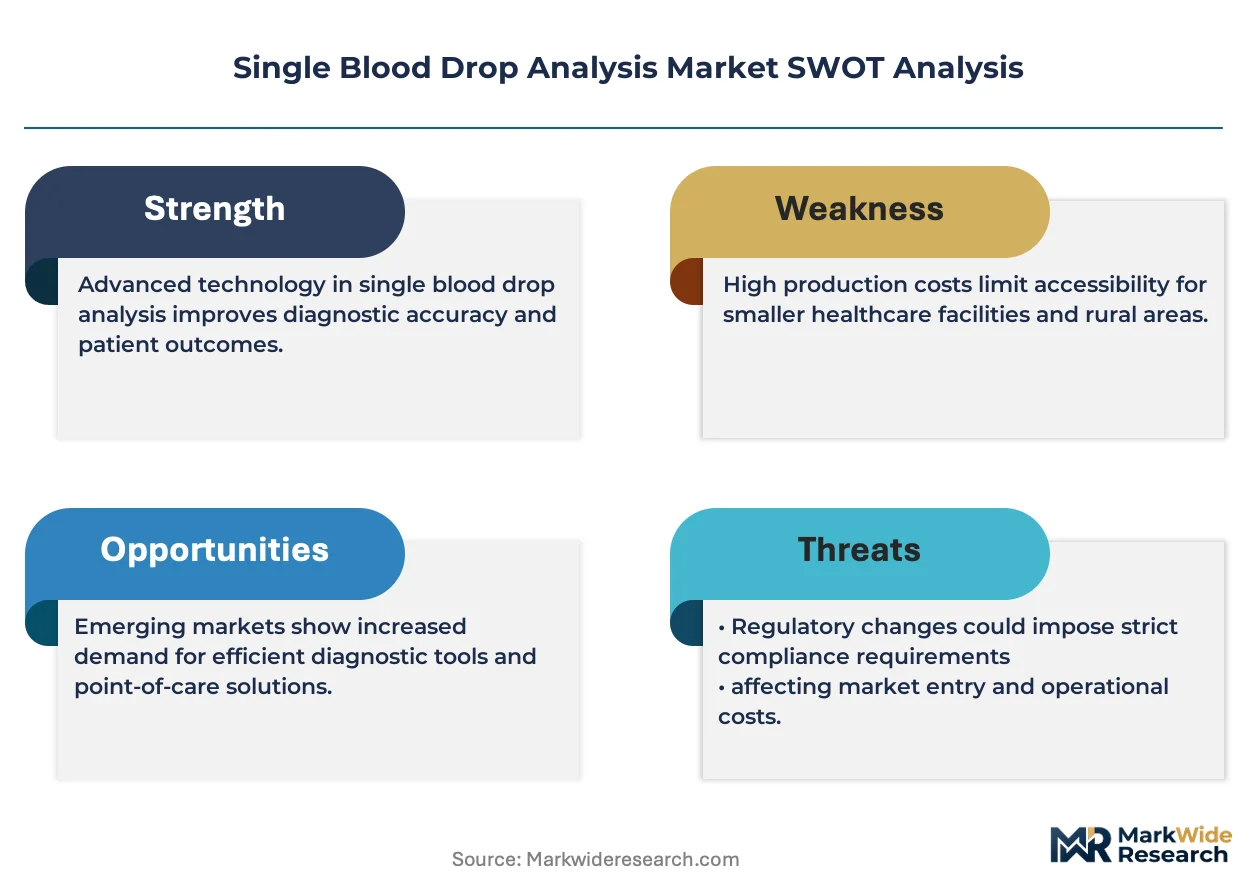
FDA CLIA waiver standards gate both supply qualification and price differentiation simultaneously, as manufacturers must demonstrate clinical validation rigor to access premium reimbursement tiers while polymer substrate volatility squeezes consumable economics across all certification levels.
Pricing Analysis
Consumable cartridge revenue drives lifetime value across analyzer install bases, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA clearance status and thermal stabilization module inclusion. Price differentiation rests on CLIA waiver certification and Bluetooth-enabled data integration capabilities. Cost compression in economy tiers intensifies as Indian primary health centers demand sub-dollar per-test economics. United States home care buyers absorb premium pricing for waived-complexity devices with telehealth platform connectivity.
Supply Chain Analysis
Strategic stockpiling of high-purity enzymes dominates inventory strategy given Swiss and German chemical corridor concentration for electrochemical sensor reagents. Manufacturing draws from Taiwan for photolithography equipment, Germany for cyclic olefin copolymer substrates, and Japan for precision optical components. Single-source vulnerability clusters around enzymatic mediator chemistries. Distribution runs through integrated delivery network procurement departments consolidating multi-year sole-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in rural diagnostics infrastructure, where Ayushman Bharat digital health deployment creates niches for portable hematology platforms outside incumbent channel control.
For Market Incumbents: Secure backward integration into cyclic olefin copolymer substrate production to defend consumable margins against petrochemical feedstock volatility. Anchor CLIA waiver certification pipelines for next-generation electrochemical sensor formats before FDA streamlining pathways attract mid-cap competitors. Channel control through integrated delivery network sole-source agreements blocks price erosion in Texas and Florida procurement consolidation. For New Entrants and Emerging Players: Anchor in rural India primary health centers where cold-chain logistics gaps exclude centralized laboratory competitors. Target photonic ring resonator biosensor development for Nordic chronic disease management programs seeking label-free inflammatory marker tracking. Go-to-market leverage through Ayushman Bharat digital infrastructure partnerships bypasses incumbent hospital procurement gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrochemical sensor manufacturing as electrode miniaturization scales reduce cleanroom process engineering requirements. Five-to-ten year viability favors mid-cap developers with dedicated EU MDR regulatory affairs infrastructure and notified body validation partnerships. Signal to monitor: FDA premarket notification pathway compression timelines for novel sensor platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Certification Pipeline | FDA streamlined pathways accelerate home care deployment timelines for enzymatic electrochemistry formats. |
| Backward Integration into Polymer Substrates | Cyclic olefin copolymer captive supply insulates margins from petrochemical feedstock volatility. |
| Bluetooth-Enabled Data Platform Development | Remote monitoring integration pulls reimbursement eligibility toward longitudinal subscription models. |
| EU MDR Notified Body Partnership | Clinical evidence harmonization reduces redundant studies across member states for CE marking. |
| Photonic Ring Resonator Biosensor Launch | Label-free detection eliminates conjugate reagent costs for Nordic inflammatory marker tracking programs. |
Study Parameters
A spread of perspectives from regulatory affairs directors, hospital procurement committee members, microfluidic manufacturing engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up test volume modeling and top-down market sizing triangulated on segment-level outputs.
Segmentation dimensions modeled span detection modality, end user procurement centralization, chronic disease application, and product type margin structure across the projection horizon. CAGRs derive from install base expansion rates and per-test consumable attach rates. Forecast inputs incorporate CLIA waiver approval velocity and Bluetooth-enabled reader adoption curves in home care settings.
Material uncertainties — regulatory pathway delays, polymer substrate price spikes, and EHR interoperability certification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about FDA streamlining continuity and EU MDR certificate renewal timelines. Revision becomes warranted when electrochemical sensor enzyme supply disruption crosses sustained shortage thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Global Immunohematology Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Hemoglobin Analyzer Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Myelofibrosis Treatment Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Idiopathic Thrombocytopenic Purpura Market