

Medical Cart Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Cart Battery Market Insights
Subscription-based battery health monitoring is realigning how medical cart power systems get monetized, shifting vendors toward recurring revenue models tied to uptime guarantees. Ultralife Corporation leverages its military-grade lithium expertise to dominate high-reliability hospital deployments. Capsa Healthcare anchors its position through integrated cart-battery ecosystems that reduce procurement complexity for health systems. Ergotron competes on ergonomic design interoperability, extending battery compatibility across multiple cart generations.
A medical cart battery is a rechargeable electrochemical power source, typically 12V to 24V DC with 20Ah to 100Ah capacity, engineered for continuous deep-cycle discharge in mobile healthcare equipment. These batteries employ sealed lead-acid, lithium-ion, or lithium-polymer chemistries with integrated battery management systems to prevent thermal runaway and ensure patient safety during bedside care. Lithium-ion chemistry leads product type value contribution due to superior energy density and cycle life, while lithium-polymer variants represent the fastest-growing subsegment as thin-form designs enable slimmer cart profiles. Mobile computing anchors application demand through nurse workstation electrification, though surgical support applications command premium pricing for redundant power architectures.
FDA 21 CFR Part 820 quality system regulations and IEC 60601-1 third-edition safety standards govern battery integration into medical electrical equipment, compelling manufacturers to validate electromagnetic compatibility and risk management files. UN 38.3 lithium battery transport testing and OSHA workplace safety directives further shape supply chain logistics and hospital fleet handling protocols. Stakeholders must monitor solid-state battery commercialization timelines and evolving EU MDR substance restrictions as these forces will reshape supplier qualification criteria and replacement cycle economics.
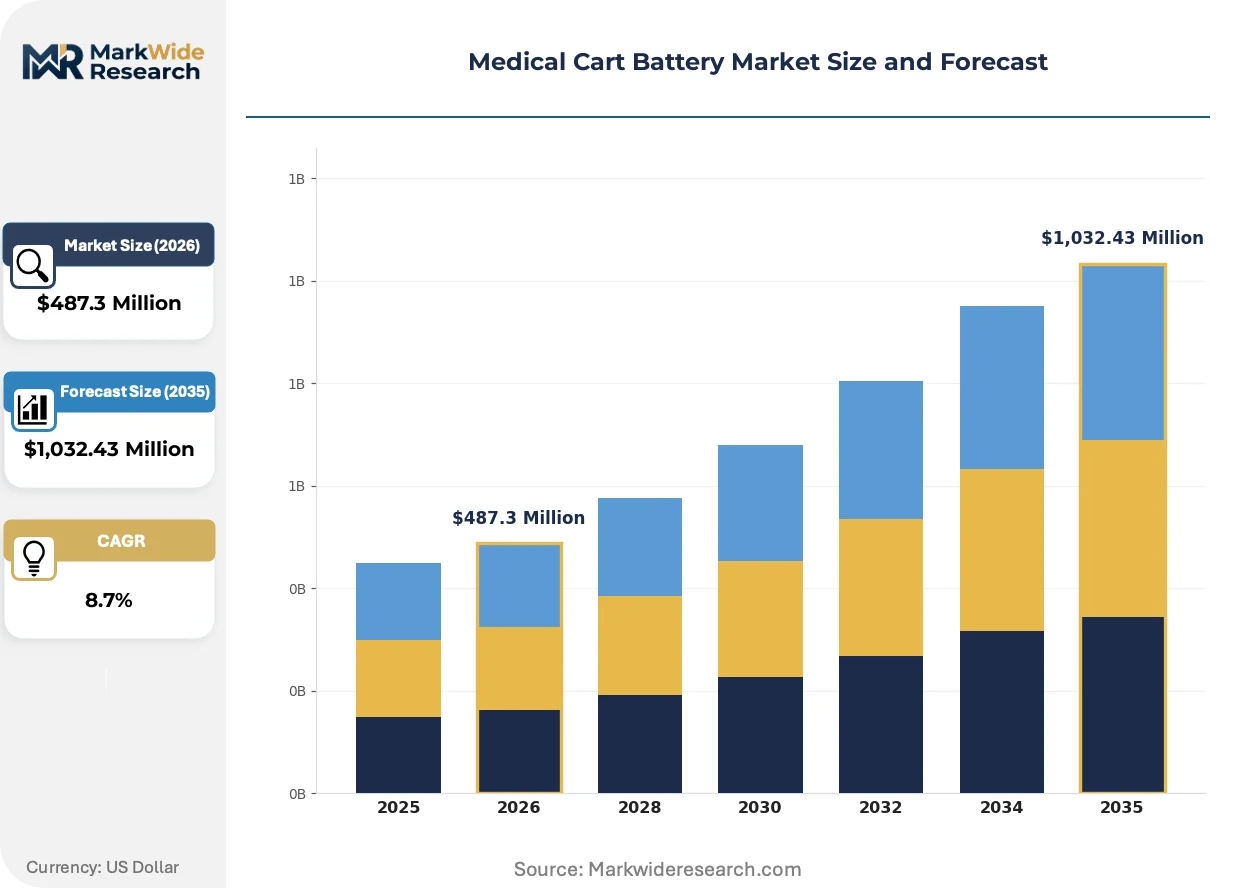
Market Dynamics
Hospital fleet electrification is compressing replacement cycles as aging lead-acid inventories phase out under Joint Commission infection control mandates. This structural shift forces battery vendors to align warranty terms with cart OEM refresh schedules rather than standalone cell longevity.
Growth Catalysts
- FDA 21 CFR Part 820 enforcement:Quality system mandates for battery-integrated medical devices accelerate validated supplier consolidation among hospital procurement teams.
- Lithium-ion energy density gains:Deep-cycle architectures now support 12-hour nursing shifts without mid-shift swaps, reducing cart downtime in emergency departments.
- German hospital infrastructure modernization:Federal Klinikbau funding programs prioritize mobile workstation electrification in aging acute care facilities.
Market Restraints
- Cobalt and lithium carbonate volatility:Cathode material cost swings compress gross margins for mid-tier battery assemblers lacking long-term offtake agreements.
- UN 38.3 certification bottlenecks:Transport testing backlogs at third-party laboratories extend new product introduction timelines by four to eight weeks.
- Sealed lead-acid residual demand:Budget-constrained long-term care facilities delay lithium conversions, fragmenting vendor SKU requirements.
Strategic Opportunities
- Subscription-based battery health monitoring:Recurring revenue models tied to uptime guarantees realign vendor incentives toward predictive maintenance rather than unit sales.
- Solid-state chemistry commercialization:Elimination of liquid electrolytes enables thinner form factors for endoscopy and anesthesia cart applications.
- Japan's 2025 medical device subsidy expansion:METI-directed funding for smart hospital infrastructure creates preferential procurement channels for connected power systems.
Industry Challenges
- IEC 60601-1 third-edition electromagnetic compatibility validation:Battery management system firmware revisions trigger full recertification cycles for cart-integrated configurations.
- Legacy fleet interoperability:Retrofit battery packs must accommodate proprietary connector architectures from defunct cart manufacturers without electrical redesign.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Cart Battery Market Trends and Innovations
Battery intelligence is migrating from passive power provision to active fleet orchestration, with embedded diagnostics now standard in premium configurations. This shift redefines vendor value propositions around operational continuity rather than amp-hour specifications.
Lithium-polymer thin-form cells are rewriting industrial design constraints for mobile medical equipment. Surgical support cart manufacturers in the United States adopt sub-20mm battery profiles to maximize under-cart storage volume for sterile supplies. This chemistry is compressing the premium-midrange price gap as Korean cell suppliers scale polymer electrodeposition capacity.
EU MDR substance restrictions are tightening supply chain qualification protocols for battery recyclers and second-life material processors. REACH Annex XVII candidate list expansions now cover nickel and cobalt compounds at trace thresholds, compelling Asian cell manufacturers to establish European dismantling partnerships. German hospital groups are responding by demanding full material passports for replacement battery procurements.
Health system consolidation is compressing vendor rationalization timelines as integrated delivery networks centralize fleet standardization. United States-based IDNs now mandate single-source battery contracts across 50-plus facility footprints, displacing fragmented cart-by-cart purchasing. This concentration is most visible in Texas and Florida markets where hospital merger activity has accelerated since 2023.
Medical Cart Battery Market Segmentation
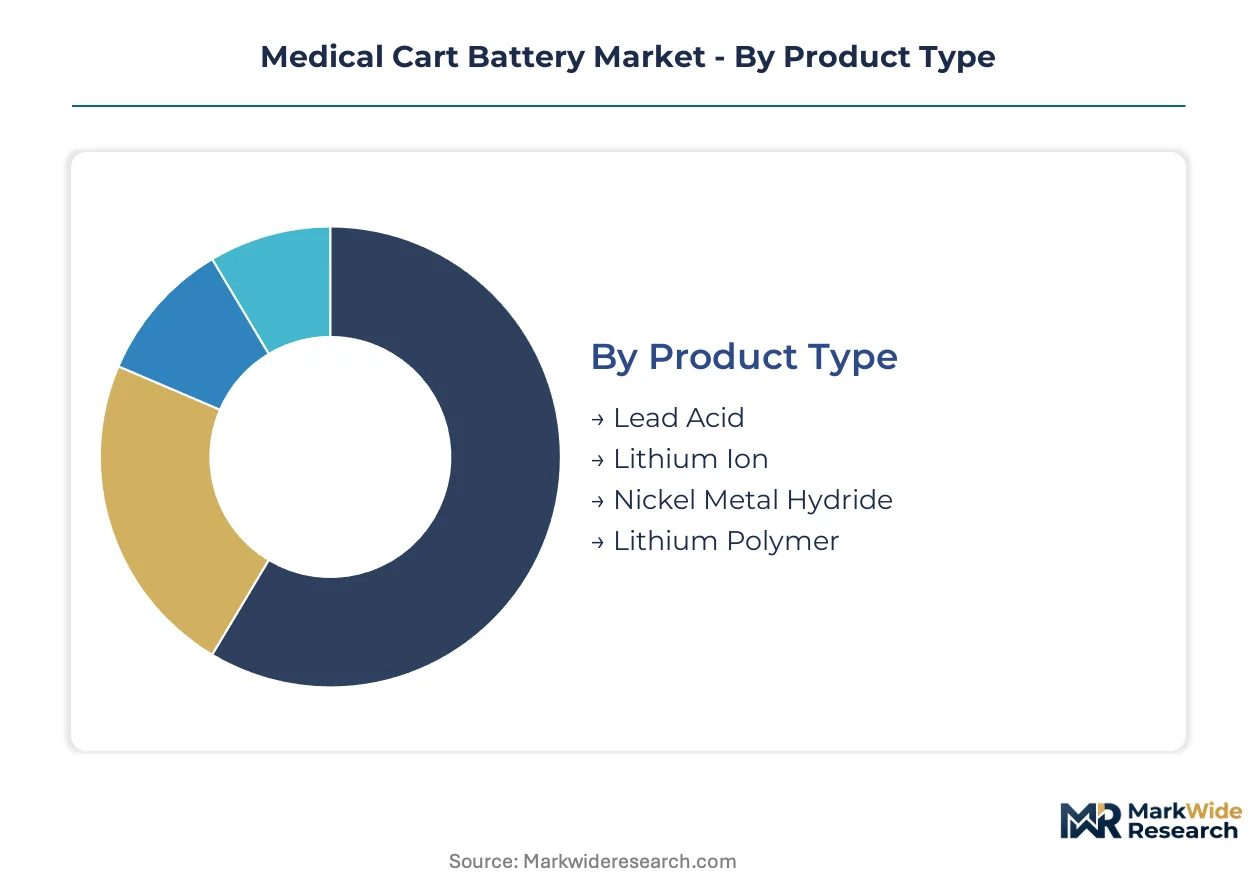
Medical cart battery procurement decisions hinge on upgrade-cycle timing, with hospital fleet managers balancing chemistry migration against cart OEM refresh schedules. Segmentation reveals how end-use specialization and deployment architecture reshape vendor qualification criteria across acute and ambulatory settings.
Product Type:
Replacement-cycle compression favors chemistries that align with Joint Commission infection control mandates and cart OEM warranty terms.
- Lithium Ion:Deep-cycle architectures with integrated battery management systems dominate hospital fleet electrification. United States acute care facilities concentrate procurement around 12-hour shift-capacity configurations to eliminate mid-shift swaps in emergency departments.
- Lithium Polymer:Thin-form electrodeposition enables sub-20mm profiles that maximize under-cart storage volume for surgical supplies. Korean cell suppliers are scaling polymer capacity, compressing the premium-midrange price gap for United States surgical support cart manufacturers.
- Lead Acid:Sealed variants persist in budget-constrained long-term care facilities, fragmenting vendor SKU requirements with residual demand outside hospital procurement channels.
- Nickel Metal Hydride:Legacy deployments in older medication dispensing carts sustain niche replacement demand where lithium retrofits require electrical redesign.
Lithium Ion sits at the top of the volume ranking, with Lithium Polymer climbing the fastest.
Application:
Application-specific power architectures command pricing differentiation tied to redundancy requirements and shift-length demands.
- Mobile Computing:Nurse workstation electrification anchors baseline demand, with 24V DC configurations supporting continuous medication access documentation across 12-hour shifts.
- Surgical Support:Redundant power architectures with hot-swap capability command premium positioning. German hospital infrastructure modernization programs prioritize these configurations in aging acute care facilities.
- Patient Monitoring:Continuous telemetry integration requires stable voltage output during transport between units.
- Medication Dispensing:Automated cabinet mobility drives mid-tier capacity requirements with moderate cycle depth.
- Diagnostic Equipment:Portable imaging and point-of-care testing need rapid recharge compatibility with limited dwell time between procedures.
Surgical Support carries the steepest pricing tier, while Mobile Computing delivers the broadest volume base.
End User:
Procurement centralization across integrated delivery networks concentrates vendor selection power in multi-facility contracting.
- Hospitals:Fleet standardization mandates from United States-based IDNs now span 50-plus facility footprints, displacing fragmented cart-by-cart purchasing. Texas and Florida merger activity since 2023 accelerates this concentration.
- Ambulatory Surgery Centers:Same-day discharge protocols demand rapid turnaround power systems with minimal charging infrastructure.
- Diagnostic Laboratories:Specimen transport cart electrification follows hospital procurement patterns with lower redundancy requirements.
- Specialty Clinics:Cardiology and oncology infusion centers prioritize quiet operation and compact form factors.
- Rehabilitation Centers:Extended discharge timelines permit longer charging windows, accommodating lower-cost chemistries.
Hospitals dominate procurement volume, with Ambulatory Surgery Centers expanding most quickly.
Deployment:
Deployment architecture selection depends on cart mobility patterns and charging infrastructure density within facility layouts.
- Plug-in:Tethered charging stations suit fixed workstation configurations with predictable duty cycles.
- Wireless:Inductive charging pads embedded in corridor flooring enable continuous power for high-mobility medication rounds.
- Hybrid:Dual-mode systems bridge infrastructure gaps during phased electrification rollouts.
- Swappable:Hot-swap battery cassettes eliminate downtime for 24/7 surgical and emergency applications.
Swappable systems command the highest unit economics, with Wireless gaining share fastest in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany channels federal Klinikbau funding into acute care mobile workstation electrification at double the per-facility rate of Japan's METI-directed programs, though both lag the procurement velocity of United States-based integrated delivery networks.
United States
Hospital merger activity in Texas and Florida since 2023 compresses vendor rationalization timelines across 50-plus facility footprints. FDA 21 CFR Part 820 enforcement accelerates validated supplier consolidation among procurement teams. The Dallas-Fort Worth medical corridor concentrates fleet standardization mandates for connected power systems.
Germany
Federal infrastructure modernization programs prioritize mobile workstation deployment in aging acute care facilities across North Rhine-Westphalia. EU MDR substance restrictions and REACH Annex XVII protocols tighten supply chain qualification for battery recyclers. The Rhine-Ruhr industrial cluster anchors European demand for redundant surgical support power architectures.
Japan
METI's 2025 medical device subsidy expansion creates preferential procurement channels for smart hospital infrastructure in the Kanto region. JIS standards compliance requirements shape domestic battery management system specifications. Osaka-based surgical equipment manufacturers drive thin-form lithium-polymer adoption for endoscopy cart applications.
United Kingdom
NHS fleet electrification targets accelerate replacement cycles for lead-acid inventories in London and Southeast England. MHRA alignment with IEC 60601-1 third-edition standards compels electromagnetic compatibility validation for cart-integrated configurations. The Cambridge-Oxford health tech corridor attracts battery intelligence startups targeting predictive maintenance platforms.
South Korea
Korean cell suppliers scale lithium-polymer electrodeposition capacity to serve United States surgical cart manufacturers seeking sub-20mm profiles. MFDS battery safety regulations govern domestic medical device power system certifications. The Seoul Capital Area concentrates electronics manufacturing partnerships for thin-form medical power modules.
Medical Cart Battery Market Competitive Landscape
Top-tier vendors anchor hospital fleet electrification contracts, while mid-tier assemblers compete on price for long-term care residual demand. The vendor base stratifies across military-grade reliability specialists, integrated cart-battery ecosystem providers, and ergonomic design interoperability competitors. Three archetypes dominate: chemistry-agnostic system integrators, lithium-focused deep-cycle engineers, and subscription-based uptime guarantee platforms. Consolidation pressures intensify through IDN single-source contracting and cart OEM refresh schedule alignment.
Within the military-grade reliability tier, Ultralife Corporation exemplifies defense-to-healthcare technology transfer. Capsa Healthcare and Ergotron occupy positions at the integrated ecosystem and ergonomic interoperability vectors respectively. These three entities represent contrasting strategic postures—captive chemistry expertise versus cart-battery bundling versus cross-generational compatibility—without any single approach commanding decisive share.
| Leading Market Players |
|---|
| Capsa Healthcare |
| Ergotron |
| TouchPoint Medical |
| JACO |
| Enovate Medical |
| Advantech |
| Ultralife Corporation |
| DTG |
| Scott-Clark Medical |
| Others |
Pricing and Supply Chain Analysis
Cobalt and lithium carbonate spot prices transmit directly through cathode material costs to compress gross margins for mid-tier battery assemblers lacking long-term offtake agreements, forcing three-tier pricing stratification across premium FDA-validated, standard IEC-certified, and economy lead-acid residual tiers.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for lithium-polymer cells serving United States surgical cart manufacturers. Premium-mid-economy pricing differentiation rests on UN 38.3 certification status and battery management system firmware validation depth. Cost compression in the standard tier intensifies because Korean electrodeposition scale is eroding Japanese cell premiums. Long-term care facilities exhibit highest price sensitivity, while emergency departments prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Trans-Pacific freight rate volatility alters landed cost calculations for cell imports from South Korea and Japan to United States cart OEMs. Cathode active material production concentrates in China, South Korea, and Japan, drawing from Australian hard-rock spodumene and Chilean brine lithium feedstocks. Single-source vulnerability runs through Chinese cobalt hydroxide refining. Distribution runs through cart OEM captive channels and hospital GPO contracts rather than open distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through solid-state chemistry premiumization and subscription monitoring revenue, with lithium-polymer thin-form adoption compressing the premium-midrange gap and enabling tier ascension.
For Market Incumbents: Cement fleet standardization contracts across United States integrated delivery networks before cart OEM refresh cycles consolidate supplier panels. Invest in IEC 60601-1 third-edition electromagnetic compatibility pre-certification to accelerate procurement velocity. Acquire battery management system firmware capabilities to defend against pure-play diagnostics entrants. For New Entrants and Emerging Players: Launch via direct hospital contracting in German Klinikbau-funded facilities bypassing established cart OEM channels. Target long-term care lead-acid replacement demand where incumbent lithium specialists ignore residual price-sensitive volume. Position on REACH Annex XVII material passport compliance to capture EU MDR-driven procurement shifts. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital IDN single-source mandates eliminate fragmented cart-by-cart purchasing. Five-to-ten-year viability favors chemistry-agnostic system integrators with captive battery management software. Watch solid-state commercialization timelines as the inflection signal for replacement cycle compression and premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Health Monitoring Launch | Recurring revenue models align vendor incentives with hospital uptime guarantees across IDN footprints. |
| Solid-State Chemistry Investment | Thin-form designs unlock endoscopy and anesthesia cart applications with sub-20mm battery profiles. |
| FDA 21 CFR Part 820 Pre-Validation | Accelerated supplier qualification shortens procurement cycles for hospital fleet electrification mandates. |
| EU MDR Material Passport Compliance | REACH Annex XVII alignment secures German hospital group replacement battery contracts. |
| Cart OEM Refresh Cycle Alignment | Warranty term synchronization with cart replacement schedules locks in multi-year revenue visibility. |
Research Methodology
Direct dialogue with hospital biomedical engineers, GPO contracts managers, cart OEM procurement leads, and lithium cell technical directors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, UN 38.3 test laboratory disclosures, hospital procurement databases, and IEC standards committee documentation. Bottom-up cell demand modeling and top-down hospital fleet electrification spend analysis enabled cross-verification.
Bottom-up volume estimates triangulated against top-down healthcare capital equipment expenditure patterns across the projection horizon. Segmentation dimensions spanned chemistry type, application power architecture, end-user facility class, and deployment modality. CAGRs emerged from replacement cycle compression rates and lithium conversion penetration curves. Forecast inputs incorporated Joint Commission infection control mandate timelines and cart OEM warranty term structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt price spike scenarios or UN 38.3 laboratory capacity constraints. Forecasts reflect assumptions about hospital merger velocity and federal infrastructure funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.