
 Medical Ultrasonic Baths Market | 2026-2036
Medical Ultrasonic Baths Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Ultrasonic Baths Market Analysis
Hospital-grade specification tiers is bifurcating the competitive landscape into premium validated systems and cost-optimized alternatives. Elma Schmidbauer GmbH leverages German engineering credentials to dominate high-frequency precision cleaning for surgical instruments. Thermo Fisher Scientific Inc. sustains laboratory channel control through integrated workflow solutions. L & R Manufacturing Company anchors the North American dental segment with specialized compact units for practice-scale sterilization.
Medical ultrasonic baths are stainless-steel vessels employing piezoelectric transducers to generate cavitation bubbles in aqueous or enzymatic solutions, typically operating at frequencies between 25 kHz and 130 kHz to dislodge bioburden from complex instrument geometries without surface abrasion. Tabletop configurations command the volume base in dental clinics and small laboratories where space constraints limit floor-model deployment, while floor-model systems capture margin pools in central sterile supply departments requiring 20-liter-plus capacities and validated cycle documentation. Laboratory use applications are expanding fastest as genomic and proteomic workflows multiply precision cleaning steps for glassware and analytical components.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device validation for medical ultrasonic baths marketed in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for systems entering European clinical settings. The Environmental Protection Agency's reprocessing guidance and REACH chemical restrictions further shape detergent formulation and wastewater handling protocols. Stakeholders must monitor evolving harmonization between FDA and EU MDR technical documentation requirements to avoid dual-track compliance costs.
Market Dynamics
Hospital sterile processing departments now face simultaneous pressure from FDA validation tightening and surgical volume recovery, forcing capital allocation toward traceable high-frequency systems over unvalidated legacy units.
Growth Catalysts
- Surgical instrument reprocessing mandates:The Joint Commission's infection control standards now require documented cavitation performance for reusable device cleaning, compelling US hospital procurement of validated baths.
- EU MDR conformity assessment:European notified body scrutiny of cleaning validation data is accelerating replacement cycles for pre-2017 installed base units.
- Genomic workflow expansion:Proteomics laboratories in Germany and Japan are adding dedicated ultrasonic cleaning stations for mass spectrometry sample preparation glassware.
Market Restraints
- Piezoelectric transducer supply concentration:Japanese and German ceramic substrate manufacturers control 80% of high-frequency transducer output, creating input bottlenecks.
- Stainless steel alloy volatility:316L surgical-grade steel price swings directly compress margins on floor-model vessel fabrication.
- Single-use instrument substitution:Ambulatory surgery centers in the United States are shifting toward disposable laparoscopic tools, reducing reprocessing equipment need.
Strategic Opportunities
- India hospital infrastructure buildout:NABH accreditation requirements for 600+ new tertiary care facilities create first-time demand for ISO 13485-compliant cleaning systems.
- Automated loading integration:Robotic transfer systems from washer-disinfector lines into ultrasonic baths are opening retrofit service contracts.
- Brazil ANVISA harmonization:Alignment with ISO 17664 cleaning validation standards is creating regulatory tailwind for imported validated equipment.
Industry Challenges
- Metrology technician scarcity:Cavitation meter calibration and frequency validation require specialized biomedical engineering skills concentrated in Germany and the United States.
- Legacy DICOM integration:Older central sterile supply IT infrastructure lacks API connectivity for automated cycle documentation upload.
- Enzymatic detergent chemistry IP:Proprietary surfactant formulations from chemical suppliers create locked-in consumable revenue streams that resist switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Ultrasonic Baths Market |
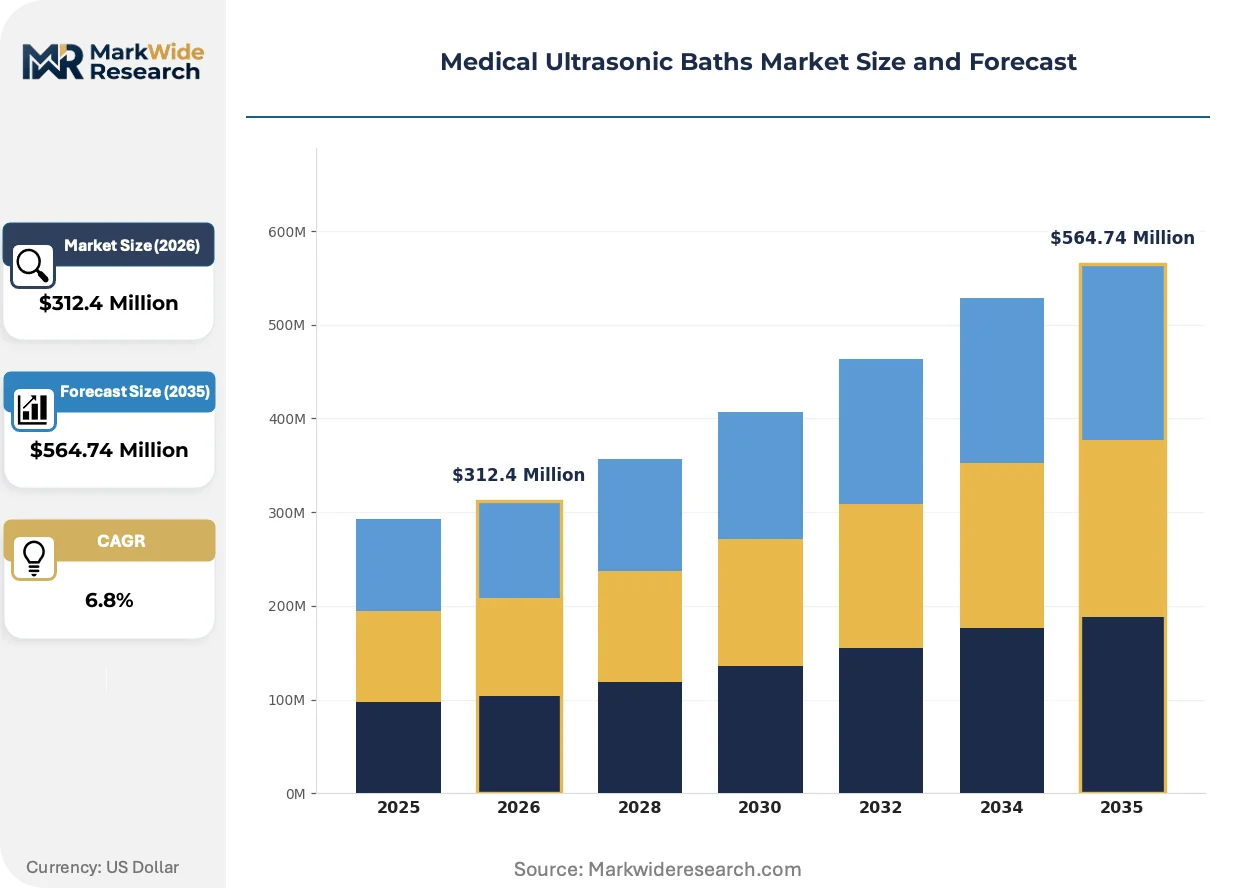
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Floor Model, Portable, Industrial Application: Dental Cleaning, Instrument Sterilization, Laboratory Use, Jewelry Cleaning End User: Hospitals, Dental Clinics, Laboratories, Veterinary Clinics Capacity: 1 Liter, 5 Liters, 10 Liters, 20 Liters |
| Companies Covered | Blue Wave Ultrasonics, Steris Plc, Kemet International Ltd., Heidolph Instruments GmbH & CO. KG, Steelco S.p.A., Elma Schmidbauer GmbH, Thermo Fisher Scientific Inc., L & R Manufacturing Company, SharperTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Ultrasonic Baths Market Emerging Trajectories
Ultrasonic cleaning technology is bifurcating between precision high-frequency systems for complex geometries and simplified lower-cost units for basic dental instrument batches, with software-defined validation emerging as the decisive differentiator.
Variable-frequency sweep technology is fragmenting the traditional fixed-frequency market by enabling real-time resonance adjustment across 25-130 kHz bands. Central sterile supply departments in US academic medical centers are adopting these systems to handle mixed instrument loads without batch segregation. The capability is compressing demand for multiple single-frequency baths and favoring consolidated capital purchases.
EU MDR Article 10 technical documentation requirements now mandate lifetime performance data for cleaning equipment marketed as medical devices. German manufacturers are restructuring quality management systems to capture continuous cavitation monitoring logs. The burden falls heaviest on mid-tier suppliers lacking established post-market surveillance infrastructure.
Hospital procurement committees are unbundling after-sales service from equipment purchase, demanding itemized calibration and preventive maintenance contracts. Group purchasing organizations in the United States are negotiating three-year service agreements separate from capital lease terms. The shift is most pronounced in multi-hospital systems standardizing across California and Texas facilities.
Medical Ultrasonic Baths Market Segmentation
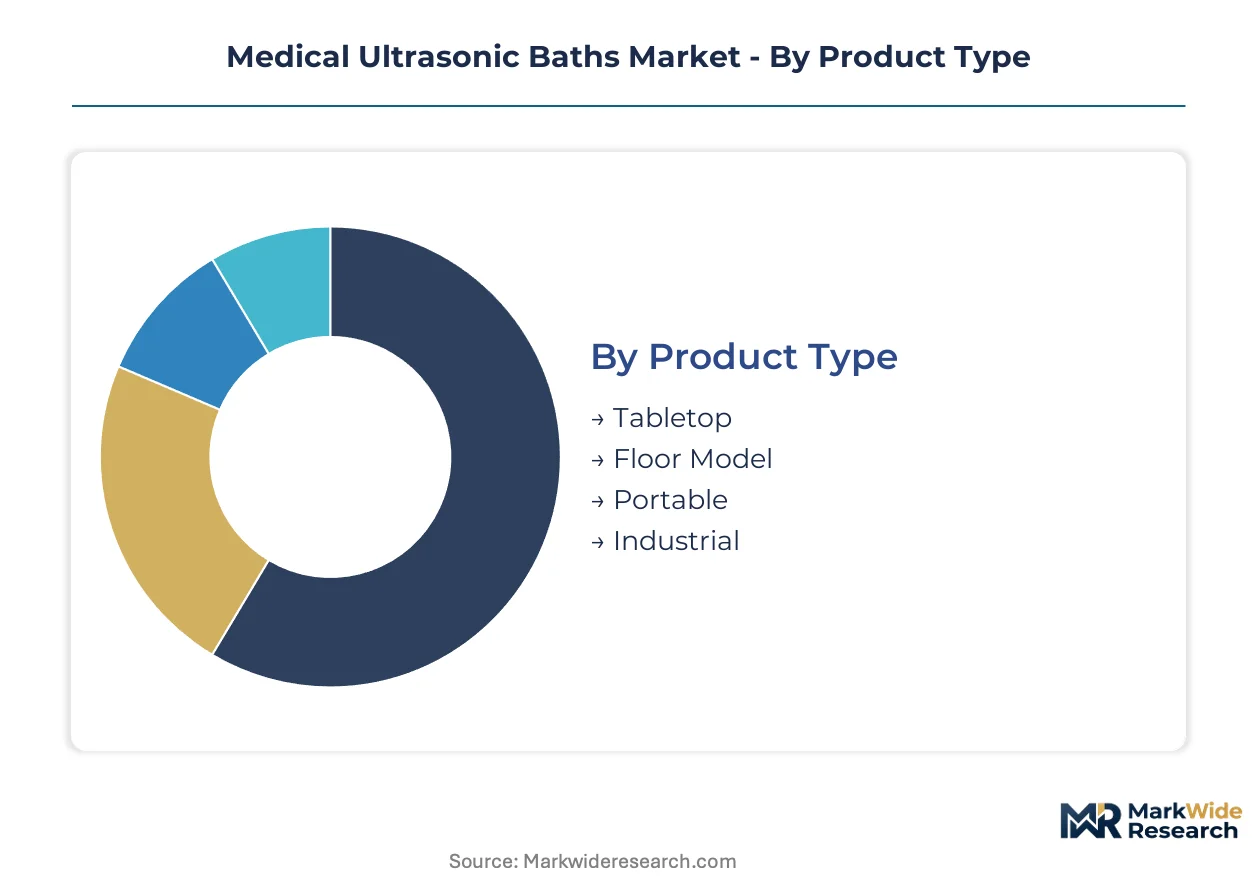
Ultrasonic bath procurement decisions diverge sharply across clinical settings. Validation requirements, space constraints, and reprocessing volumes create distinct specification tiers that vendors must address separately.
Product Type:
Single-use instrument substitution pressures tabletop and portable segments hardest, while floor-model systems retain defensive positioning through regulatory validation depth.
- Tabletop:Compact stainless-steel vessels under 10 liters dominate dental clinics and small laboratories where counter space limits deployment. German and Japanese manufacturers concentrate supply here, with FDA 510(k) clearance becoming the decisive procurement filter.
- Floor Model:High-capacity systems exceeding 20 liters anchor central sterile supply departments in US academic medical centers. The Joint Commission's cavitation documentation mandates protect this segment from disposable instrument substitution.
- Portable:Battery-operated field units serve veterinary outreach and military surgical teams. Limited validation data restricts penetration into regulated hospital environments.
- Industrial:Heavy-gauge vessels for manufacturing-scale cleaning lack medical-grade traceability. ISO 13485 certification gaps exclude this segment from clinical procurement.
Floor model retains volume leadership; portable holds the steepest expansion curve.
Application:
Cost tier stratification separates precision-validated clinical applications from price-sensitive non-medical uses.
- Dental Cleaning:Compact enzymatic cleaning of handpieces and burs requires 25-40 kHz frequency bands. North American dental service organizations are consolidating purchases across multi-practice networks.
- Instrument Sterilization:Pre-sterilization cleaning of laparoscopic and orthopedic instruments demands validated cavitation mapping. EU MDR Article 10 technical documentation requirements are accelerating replacement of legacy units.
- Laboratory Use:High-frequency 80-130 kHz systems for genomic glassware and mass spectrometry components are expanding fastest. Proteomics workflows in Germany and Japan multiply precision cleaning stations.
- Jewelry Cleaning:Unregulated consumer and retail applications compete on price alone. Medical-grade suppliers exit this segment to avoid channel conflict.
Laboratory use climbs the fastest; instrument sterilization commands margin concentration.
End User:
Customer type determines service contract structure and validation burden intensity.
- Hospitals:Central sterile supply departments in US multi-hospital systems demand three-year preventive maintenance contracts unbundled from capital purchases. Group purchasing organizations in California and Texas drive standardization.
- Dental Clinics:Practice-scale procurement favors tabletop units with bundled enzymatic detergent programs. Locked-in consumable revenue streams resist vendor switching.
- Laboratories:Academic and commercial research facilities prioritize frequency precision over capacity. METI-funded proteomics centers in Japan specify sweep-capable systems.
- Veterinary Clinics:Lower regulatory scrutiny permits cost-optimized alternatives. NABH-equivalent accreditation in India is tightening standards for 600+ new tertiary facilities.
Hospitals retain volume leadership; laboratories gain share fastest.
Capacity:
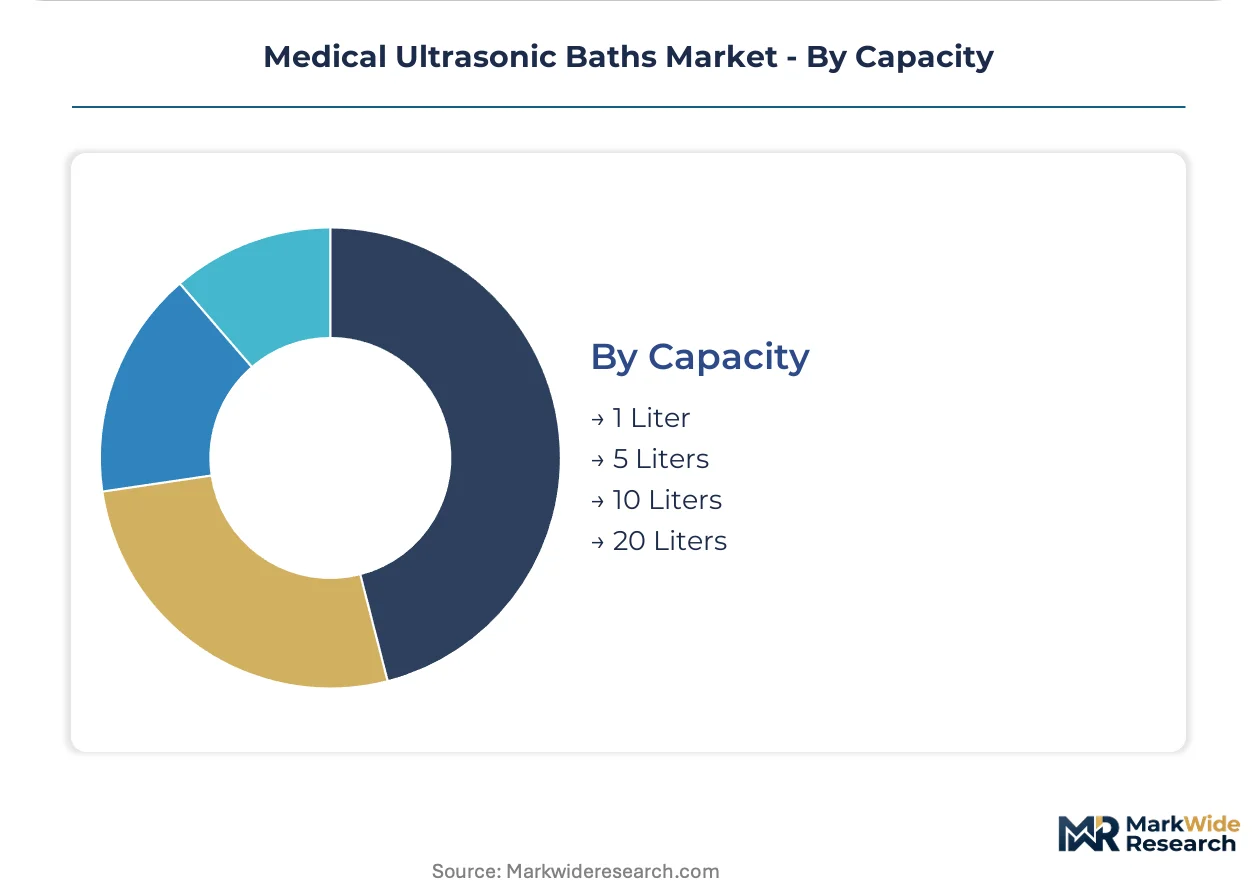
Volume tier alignment with facility scale creates distinct margin pools.
- 1 Liter:Single-instrument cleaning for high-value surgical tools. Precision frequency control justifies premium pricing in ophthalmic and microsurgical settings.
- 5 Liters:Standard dental batch size for handpiece sets. Space-constrained Japanese clinics favor this specification.
- 10 Liters:Mid-tier laboratory and small hospital department sweet spot. 316L steel price volatility compresses margins here.
- 20 Liters:Minimum viable scale for central sterile supply validation. Robotic loading integration from washer-disinfector lines opens retrofit service contracts.
20 liter retains volume leadership; 1 liter shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German ceramic substrate manufacturers control the majority of high-frequency piezoelectric transducer output, creating input bottlenecks that ripple through downstream bath assembly. Demand concentrates where surgical volume and infection control investment remain elevated.
United States
Academic medical centers in California and Texas are consolidating procurement across multi-hospital systems, with group purchasing organizations negotiating unbundled three-year service agreements. FDA 510(k) clearance requirements and The Joint Commission's cavitation documentation mandates protect validated floor-model sales from disposable instrument substitution. The Boston-Cambridge corridor anchors proteomics laboratory expansion driving high-frequency system demand.
Germany
Notified body scrutiny under EU MDR Article 10 technical documentation requirements is accelerating replacement cycles for pre-2017 installed base units. Elma Schmidbauer GmbH leverages domestic engineering credentials to dominate precision cleaning for surgical instruments. The Stuttgart-Karlsruhe industrial corridor concentrates metrology technician expertise for cavitation meter calibration services.
Japan
METI-funded proteomics centers specify sweep-capable systems for mass spectrometry sample preparation workflows. Domestic ceramic substrate manufacturers control transducer supply, creating vertical integration advantages for local bath assemblers. The Osaka-Kobe manufacturing belt houses specialized 316L surgical-grade steel fabricators serving medical device OEMs.
India
NABH accreditation requirements for 600-plus new tertiary care facilities are creating first-time demand for ISO 13485-compliant cleaning systems. CDSCO import regulations are tightening quality verification protocols for foreign-manufactured equipment. The Delhi-Mumbai industrial corridor is attracting contract manufacturers establishing localized bath assembly capacity.
Brazil
ANVISA harmonization with ISO 17664 cleaning validation standards is creating regulatory tailwind for imported validated equipment. Ambulatory surgery centers in São Paulo and Rio de Janeiro are shifting capital allocation toward traceable systems over unvalidated legacy units. The São Paulo state medical device distribution hub is consolidating regional supply chain logistics.
Medical Ultrasonic Baths Market Vendor Landscape
Concentration sits with German-engineered precision specialists and North American laboratory channel controllers. The vendor base stratifies across three tiers: premium validated systems for central sterile supply, mid-tier enzymatic-integrated units for dental networks, and cost-optimized alternatives for veterinary and emerging market entry. Dominant competitive moves include backward integration into transducer ceramic sourcing and geographic expansion through notified body certification stacking for EU MDR compliance.
Among German GmbH-structured specialists, Elma Schmidbauer GmbH and Heidolph Instruments GmbH & CO. KG exemplify the engineering-credentials archetype, while Thermo Fisher Scientific Inc. represents the integrated workflow solutions tier. L & R Manufacturing Company occupies a position within the North American dental segment specialist archetype. Steelco S.p.A. and Kemet International Ltd. sit within the European diversified industrial equipment tier, with Steris Plc exemplifying the infection control conglomerate structure that spans multiple reprocessing modalities.
| Leading Market Players |
|---|
| Blue Wave Ultrasonics |
| Steris Plc |
| Kemet International Ltd. |
| Heidolph Instruments GmbH & CO. KG |
| Steelco S.p.A. |
| Elma Schmidbauer GmbH |
| Thermo Fisher Scientific Inc. |
| L & R Manufacturing Company |
| SharperTek |
| Others |
Supply Flow & Price Mechanics
Ninety-day ceramic substrate lead times from Japanese and German transducer manufacturers compress margin flexibility for bath assemblers, concentrating pricing power upstream while forcing equipment vendors to absorb steel alloy volatility through contract terms.
Pricing Analysis
FDA 510(k) clearance dictates the pricing tier structure across the Medical Ultrasonic Baths Market, separating validated floor-model systems for central sterile supply from unvalidated tabletop alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO 13485 certification depth and cavitation documentation capability. Cost compression in mid-tier 10-liter laboratory units is intensifying because 316L surgical-grade steel price swings directly feed vessel fabrication costs. Dental clinics exhibit highest price sensitivity due to locked-in enzymatic detergent programs, while US academic medical centers prioritize validation depth over unit economics.
Supply Chain Analysis
Ninety-day ceramic substrate lead times tether bath assembly output to Japanese and German piezoelectric transducer manufacturers controlling high-frequency component supply. The supply chain draws from 316L surgical-grade steel fabricators in Japan, precision vessel welders in Germany, and enzymatic detergent formulators in the United States. Single-source vulnerability concentrates in ceramic substrate production, where two domestic Japanese suppliers feed METI-funded proteomics center procurement. Distribution runs through medical device distributors serving hospital GPOs, dental service organization networks, and laboratory supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Ultrasonic Baths Market functions as a regulatory-moat defensive story. Switching costs lock hospital sterile processing departments into validated equipment ecosystems through FDA documentation requirements and The Joint Commission audit trails.
For Market Incumbents: Compound regulatory entrenchment by stacking notified body certifications for EU MDR Article 10 compliance alongside existing FDA 510(k) clearances. Deepen backward integration into ceramic substrate sourcing to offset Japanese supplier concentration. Capture robotic loading integration retrofit contracts as US academic medical centers automate washer-disinfector line transfers. For New Entrants and Emerging Players: Differentiate on sweep-capable frequency technology for mixed-instrument laboratory workflows. Target India's NABH-accredited tertiary hospital buildout with ISO 13485-compliant tabletop units priced below German-engineered alternatives. Enter through veterinary clinic channels where lower regulatory scrutiny permits faster market access before climbing into hospital validation tiers. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-attachment play because locked-in enzymatic detergent revenue streams generate recurring cash flows resistant to vendor switching. Target mid-tier European manufacturers lacking post-market surveillance infrastructure for EU MDR compliance but possessing established notified body relationships. Monitor ANVISA harmonization progress in Brazil as signal for emerging market validation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Stacking | EU MDR Article 10 compliance opens access to German and French hospital procurement committees. |
| Backward Integration into Transducer Ceramic Sourcing | Captive supply of Japanese-manufactured piezoelectric substrates insulates against 90-day lead time volatility. |
| Robotic Loading Integration Development | Retrofit service contracts with US central sterile supply departments extend equipment lifecycle revenue. |
| Enzymatic Detergent Formulation Partnership | Locked-in consumable programs with dental service organizations create switching cost barriers. |
| Sweep-Capable Frequency Platform Launch | Variable-frequency systems displace fixed-frequency inventory in proteomics laboratories. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital sterile processing directors, GPO contracts managers, and dental clinic procurement leads and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up triangulation across equipment shipment data and top-down reconciliation against surgical volume and infection control investment flows anchored market sizing.
Variance decomposition across product type, application, end user, capacity tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating surgical instrument reprocessing mandate enforcement timing, genomic workflow expansion rates, and single-use instrument substitution elasticities.
The analysis sits within stated boundaries; outcomes outside FDA-EU MDR harmonization progress or ceramic substrate supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and surgical volume recovery trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
North America Radiotherapy Market