
 Ultrasound Equipment Market | 2026-2036
Ultrasound Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Equipment Market Intelligence
Software-as-a-Service revenue from cloud-based diagnostic platforms is tilting the profit pool away from one-time hardware sales. This shift favors companies with strong software development capabilities. Siemens Healthineers leverages its digital ecosystem to capture recurring revenue streams. GE HealthCare sustains its market position through a combination of advanced imaging hardware and integrated analytics software, while Mindray Medical International Limited competes on value and accessibility in emerging markets.
Ultrasound equipment utilizes high-frequency sound waves, generated by piezoelectric transducers, to produce real-time, non-invasive images of internal body structures. Its primary purpose is diagnostic imaging across various medical specialties. Cart-based ultrasound systems remain the standard in hospitals, commanding the largest share of the market. However, portable and handheld ultrasound devices are experiencing rapid adoption, particularly for use in point-of-care settings within diagnostic centers and private clinics.
Market access is governed by stringent regulatory approvals. In the United States, the FDA's 510(k) clearance pathway is critical, while in Europe, compliance with CE marking and the Medical Device Regulation (MDR) is mandatory. These frameworks dictate design, safety, and performance standards for all new equipment. The key decision for manufacturers now centers on balancing innovation in AI-driven features with the extended timelines and costs of regulatory validation.
Market Dynamics
The central dynamic in the ultrasound equipment market is the value migration from one-time hardware sales to recurring software and service revenues. This shift, driven by the integration of AI analytics and cloud-based platforms, fundamentally alters competitive advantage and profitability.
Growth Catalysts
- Advanced Imaging Applications:The expanding use of ultrasound in non-traditional areas, particularly musculoskeletal and orthopedic imaging, provides new avenues for market expansion beyond core radiology and obstetrics departments.
- Healthcare Infrastructure Investment:Government-led initiatives in China to build new hospitals and upgrade existing medical facilities are creating concentrated demand for a full spectrum of diagnostic imaging equipment, including cart-based ultrasound systems.
- Point-of-Care Adoption:The increasing utility of portable and handheld ultrasound devices in emergency rooms, private clinics, and ambulatory surgical centers is driving volume growth, making diagnostics more accessible and immediate.
Market Restraints
- Regulatory Scrutiny:Stringent and lengthy approval processes, such as the FDA 510(k) pathway in the US and the CE marking under the MDR in Europe, create significant barriers to market entry and slow the commercialization of innovative features.
- High Development Costs:Substantial investment is required to advance both piezoelectric transducer technology for hardware and the complex algorithms for AI-powered diagnostic software, limiting the participation of smaller, less-capitalized firms.
- Reimbursement Limitations:Inconsistent or low reimbursement rates for certain ultrasound procedures in various healthcare systems can disincentivize adoption by clinics and hospitals, particularly for newer, more specialized applications.
Strategic Opportunities
- Emerging Market Penetration:Developing healthcare systems in Southeast Asia and Latin America represent significant growth opportunities for manufacturers offering value-oriented, durable, and easy-to-use ultrasound systems tailored for regional needs.
- Therapeutic Ultrasound:Expanding beyond diagnostics into therapeutic applications, such as high-intensity focused ultrasound (HIFU) for non-invasive tumor ablation and drug delivery, opens an entirely new market segment for ultrasound technology.
- AI Software as a Medical Device:Developing standalone AI software that can be integrated with third-party ultrasound hardware creates a scalable business model focused on licensing and subscription revenue, independent of hardware sales cycles.
Industry Challenges
- Sonographer Skill Gaps:A persistent shortage of sonographers trained to operate advanced systems and interpret AI-assisted findings limits the effective deployment of new technology and can impact diagnostic quality and workflow efficiency.
- System Interoperability:Ensuring seamless integration of new ultrasound platforms with existing hospital picture archiving and communication systems (PACS) and electronic health records (EHR) remains a major technical and operational hurdle for providers.
- Cybersecurity of Connected Devices:Protecting networked ultrasound systems and cloud-based data platforms from cybersecurity threats is a critical challenge, requiring continuous investment to ensure patient data privacy and device integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Equipment Market |
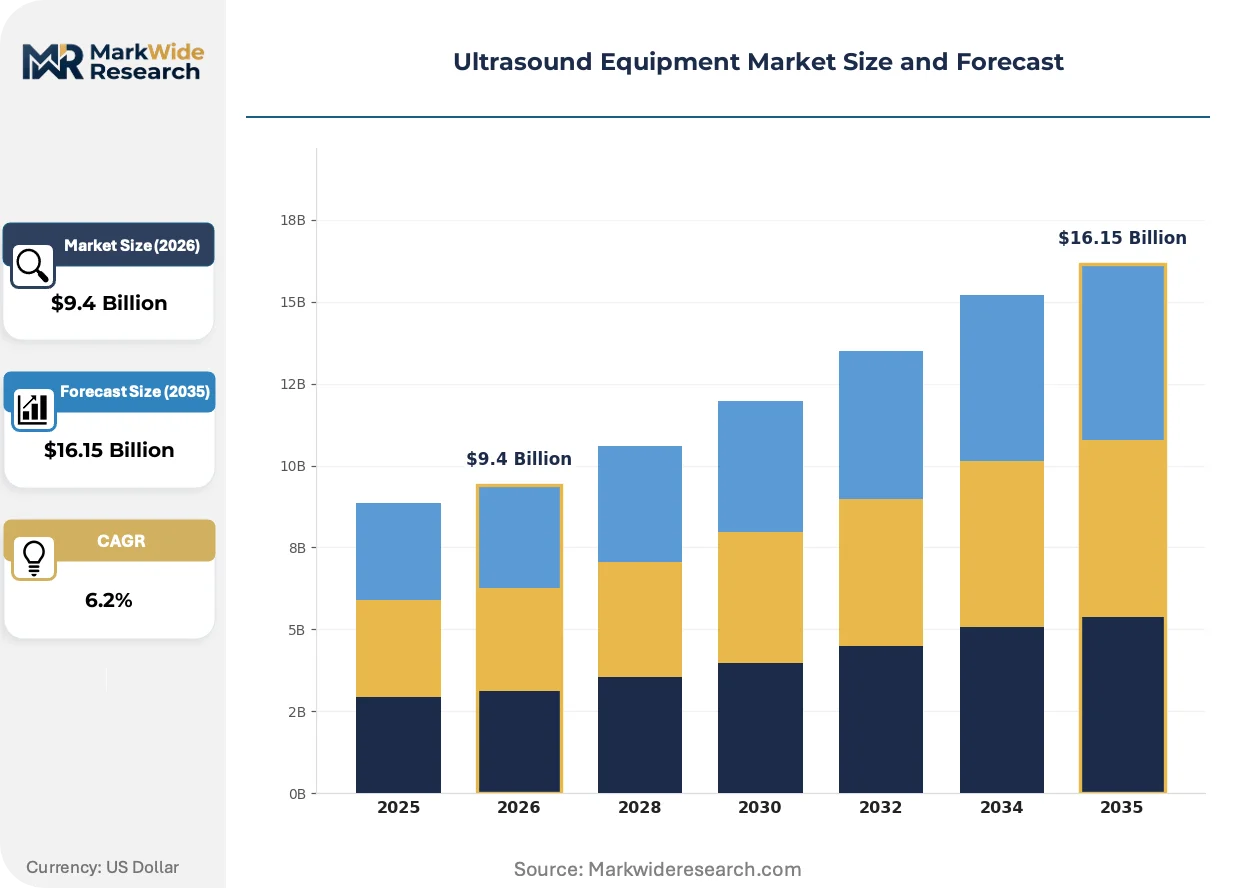
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Cart-Based Ultrasound, Handheld Ultrasound, 3D Ultrasound, Doppler Ultrasound Application: Obstetrics & Gynecology, Cardiovascular Imaging, Musculoskeletal Imaging, Urology Diagnostics, Abdominal Screening End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes, Private Clinics Deployment: On-Premise, Cloud-Based, Hybrid Systems, Remote Diagnostics, Mobile Integration |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, FUJIFILM Corporation, Mindray Medical International Limited, Hitachi Medical Corporation, Esaote S.p.A., Analogic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot from hardware specifications to software-defined capabilities. This transition prioritizes diagnostic intelligence, workflow automation, and data integration over incremental improvements in raw imaging performance, reshaping product development and competitive strategies.
Miniaturization of piezoelectric transducer arrays and onboard processors enables the core functionality of handheld ultrasound devices. Point-of-care clinicians in emergency medicine and primary care are rapidly adopting this technology. This profound shift in form factor is collapsing the boundary between large, stationary cart-based systems and portable diagnostic tools, democratizing access to high-quality imaging.
Europe’s Medical Device Regulation (MDR) has introduced more rigorous requirements for clinical evidence and post-market surveillance. This directly impacts all medical devices, including the software and AI algorithms embedded within ultrasound systems. Manufacturers targeting the European Union now face longer development timelines and increased compliance costs to secure and maintain the necessary CE marking.
A notable behavioral change involves a move away from large, one-time capital purchases toward operational expenditure models. This disrupts the traditional sales cycle for cart-based systems, with providers increasingly preferring subscriptions that bundle hardware, software, and service. This trend is most visible in the United States and Western Europe, where hospital administrators seek predictable costs and continuous technology access.
Ultrasound Equipment Market Segmentation
Understanding the Ultrasound Equipment Market requires a detailed segmentation analysis, which clarifies the varied demands and operational contexts for these diagnostic tools. This granular perspective reveals where technological advancements and service models are creating new value for providers and patients.
Product Type:
The after-sales service intensity for ultrasound equipment varies significantly by product type, influencing long-term profitability and customer engagement across the market.
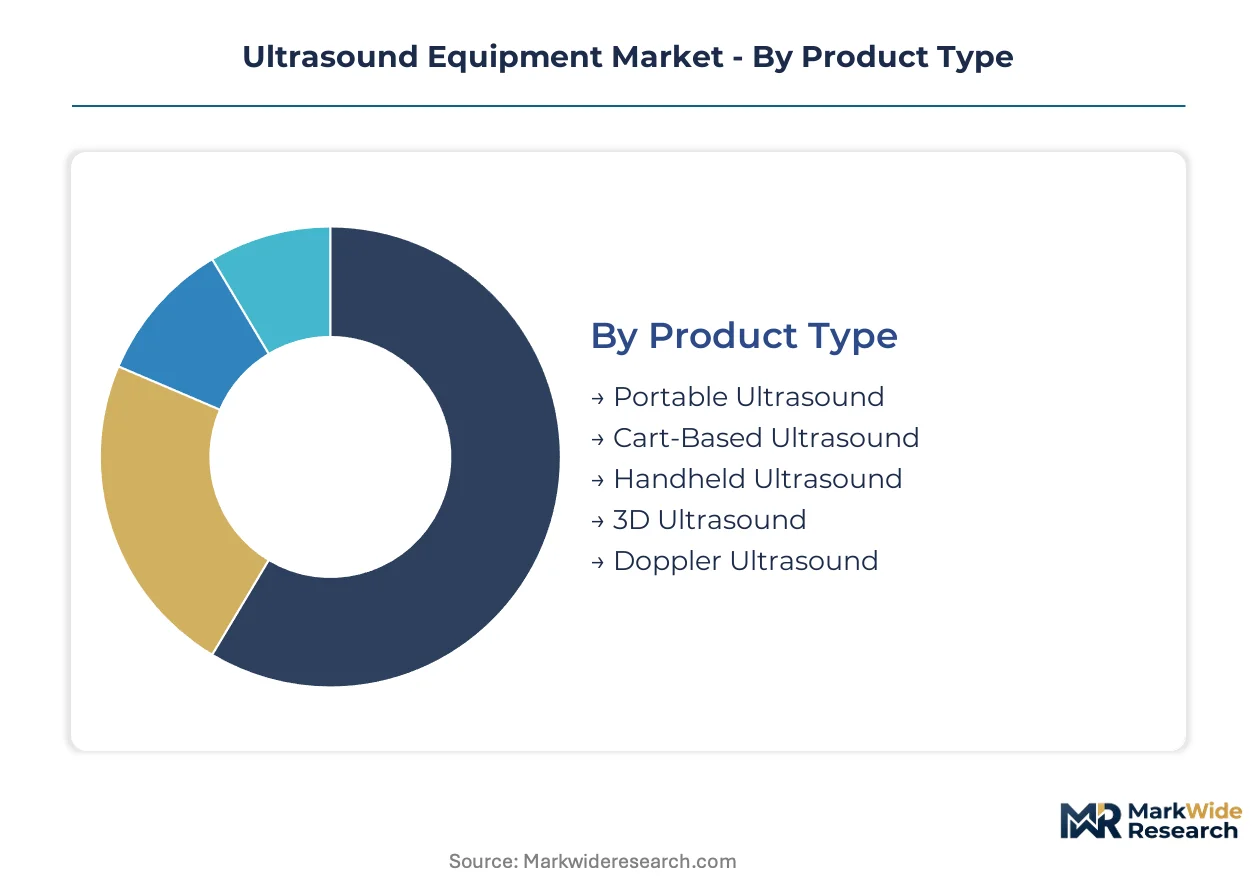
- Portable Ultrasound:These compact devices feature integrated probes and screens for quick examinations in diverse settings. Demand concentrates in point-of-care environments within emergency rooms and private clinics, driven by the need for immediate diagnostic insights.
- Cart-Based Ultrasound:These larger, stationary systems offer comprehensive imaging capabilities with multiple transducer ports and advanced processing units. Hospitals and large diagnostic centers are the primary users, prioritizing robust performance and extensive feature sets for complex procedures.
- Handheld Ultrasound:Ultra-compact devices, often connecting to smartphones or tablets, offer basic imaging for rapid assessments.
- 3D Ultrasound:This technology generates volumetric images, providing detailed anatomical views for specialized diagnostic purposes.
- Doppler Ultrasound:This modality assesses blood flow dynamics, crucial for cardiovascular and vascular diagnostic procedures.
Cart-Based Ultrasound holds the largest share; momentum sits with Portable Ultrasound.
Application:
The market's application segments reflect distinct clinical needs and the specialized capabilities required from ultrasound systems for precise diagnostic outcomes.
- Obstetrics & Gynecology:This application involves routine fetal monitoring, reproductive health assessments, and gynecological diagnostics using specialized transducers. Global demand remains consistently high due to essential prenatal care and women's health initiatives.
- Musculoskeletal Imaging:This segment focuses on visualizing tendons, ligaments, muscles, and joints for diagnosing injuries and inflammatory conditions. Adoption is expanding in orthopedic clinics and sports medicine centers, driven by its non-invasive nature and real-time assessment capabilities.
- Cardiovascular Imaging:This application employs echocardiography and vascular ultrasound to assess heart function and blood vessel health.
- Urology Diagnostics:Ultrasound aids in visualizing the kidneys, bladder, and prostate for diagnosing urinary tract conditions.
- Abdominal Screening:This broad application covers imaging of organs like the liver, gallbladder, pancreas, and spleen for general diagnostic purposes.
Obstetrics & Gynecology maintains significant volume; Musculoskeletal Imaging is expanding most quickly.
End User:
Ultrasound equipment adoption patterns are heavily influenced by the distinct customer types and their operational requirements across the healthcare spectrum.
- Hospitals:These institutions utilize a full range of ultrasound systems, from cart-based to portable, for diverse departments including radiology, emergency, and surgery. Investment decisions are driven by comprehensive patient care needs and integration with existing IT infrastructure.
- Diagnostic Centers:Specialized facilities focus on high-volume imaging services, often employing advanced ultrasound technologies for detailed diagnostic reports. Their procurement emphasizes throughput efficiency and specialized application capabilities.
- Ambulatory Surgical Centers:These facilities use ultrasound for pre-operative assessments and guiding minimally invasive procedures.
- Research Institutes:These entities employ advanced ultrasound for clinical trials, physiological studies, and developing new diagnostic techniques.
- Private Clinics:Smaller medical practices adopt portable and handheld ultrasound devices for immediate patient evaluation and improved workflow.
Hospitals represent the largest segment; Private Clinics show significant adoption growth.
Deployment:
The maturity of deployment models for ultrasound systems dictates data accessibility, security protocols, and operational flexibility for healthcare providers.
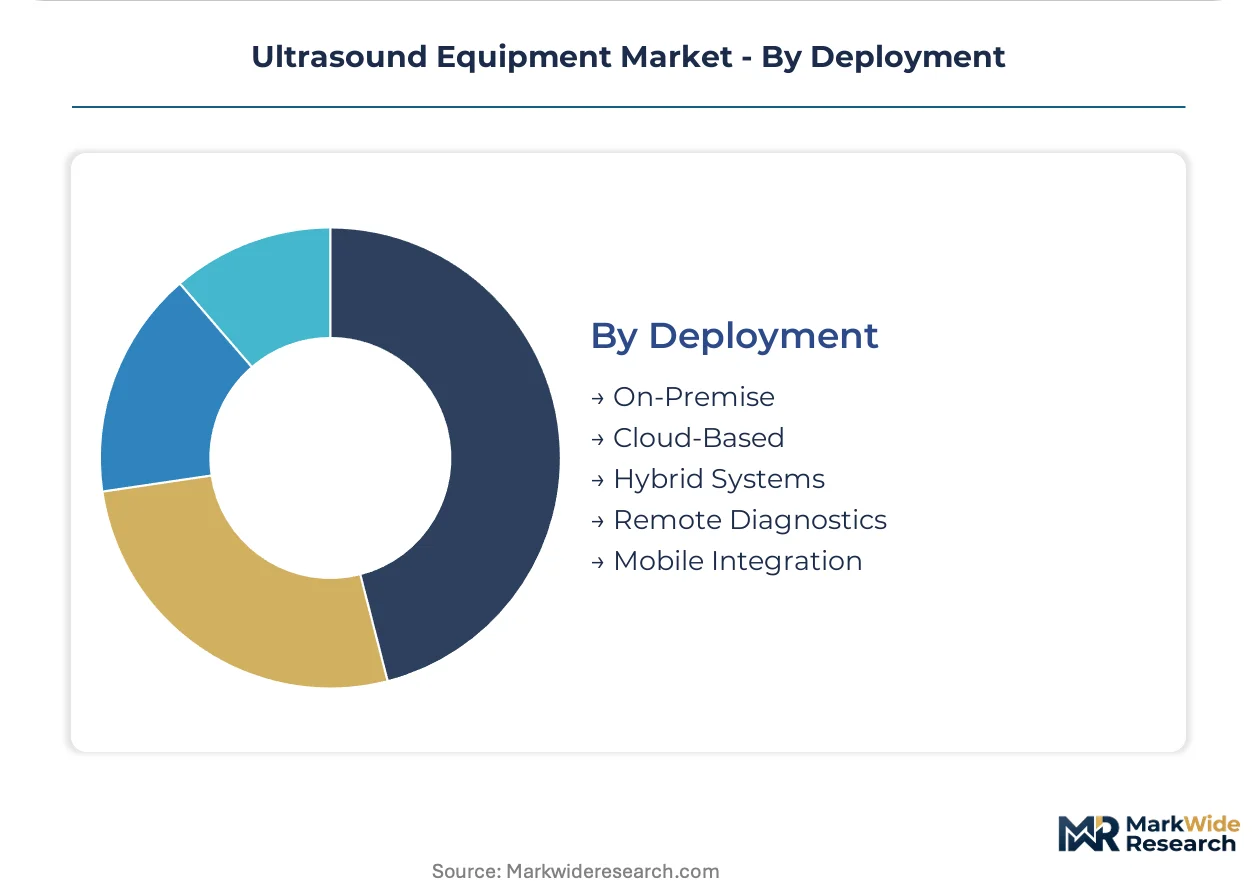
- Cloud-Based:This deployment model leverages remote servers for data storage, image processing, and AI analytics, offering scalability and accessibility from various locations. Its adoption is driven by the demand for remote diagnostics and collaborative care platforms.
- On-Premise:Traditional on-site servers manage ultrasound data and software, providing direct control over infrastructure and enhanced security for sensitive patient information. Hospitals often prefer this model for established workflows and regulatory compliance.
- Hybrid Systems:These deployments combine elements of both on-premise and cloud solutions, balancing local control with remote access capabilities.
- Remote Diagnostics:This enables specialists to interpret ultrasound images from distant locations, improving access to expertise in underserved areas.
- Mobile Integration:Ultrasound devices connect with mobile platforms, facilitating data sharing and interpretation on portable electronic devices.
On-Premise solutions maintain a dominant position; Cloud-Based deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's demand for ultrasound equipment concentrates on new hospital construction, favoring cart-based systems. In contrast, the United States and Western Europe increasingly adopt subscription models for integrated diagnostic platforms. Developing economies like India prioritize value-oriented, accessible devices for expanding healthcare access.
China
China's robust healthcare infrastructure investments drive concentrated demand for advanced cart-based ultrasound systems. The NMPA's regulatory framework ensures product safety and efficacy for domestic and imported devices. Major medical technology hubs in Shenzhen and Beijing are advancing indigenous ultrasound manufacturing capabilities.
United States
United States healthcare providers increasingly favor subscription models for ultrasound equipment, moving away from large capital purchases. The FDA's 510(k) clearance pathway remains a critical hurdle for new device commercialization. Innovation clusters in Boston and San Francisco are accelerating the integration of AI analytics.
Germany
Germany's demand for ultrasound equipment stems from its advanced healthcare system and focus on high-precision diagnostics. Compliance with CE marking under the EU Medical Device Regulation (MDR) dictates market access and post-market surveillance. Medical technology centers in Bavaria and Baden-Württemberg are pioneering therapeutic ultrasound applications.
India
India's market growth is driven by expanding healthcare infrastructure and the need for accessible, durable ultrasound systems. The CDSCO oversees the approval and quality standards for medical devices, including diagnostic equipment. Emerging manufacturing clusters in Bengaluru and Pune are developing cost-effective solutions for regional needs.
Brazil
Brazil presents significant growth opportunities for manufacturers offering value-oriented ultrasound systems amidst healthcare infrastructure development. ANVISA's stringent registration processes ensure the safety and efficacy of medical devices entering the market. Major urban centers like São Paulo and Rio de Janeiro serve as primary hubs for diagnostic centers.
Ultrasound Equipment Market Key Industry Players
Capability concentration sits with specialized software developers focusing on AI analytics and cloud platforms, while scale advantage remains with established medical device conglomerates. The market exhibits a tiered structure, from premium hardware providers offering comprehensive solutions to value-focused regional players. Strategic archetypes include integrated solution providers, niche technology innovators, and accessible device manufacturers. Companies often pursue strategic partnerships, portfolio diversification, and geographic expansion to enhance their market footprint and capture new revenue streams.
Among global technology leaders, GE HealthCare exemplifies a vertically integrated provider offering advanced imaging hardware with integrated analytics software solutions for diverse clinical needs. Siemens Healthineers, a Germany-based AG, occupies a strong position by leveraging its digital ecosystem to capture recurring revenue streams from cloud-based diagnostic platforms and services. Mindray Medical International Limited, a China-based company, sits within the value-oriented segment, providing accessible and durable ultrasound systems tailored for emerging markets. These entities collectively shape the competitive dynamics through their distinct approaches to innovation, market penetration, and business model evolution.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| Mindray Medical International Limited |
| Hitachi Medical Corporation |
| Esaote S.p.A. |
| Analogic Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for delivering components like piezoelectric transducers and finished ultrasound systems, directly influence supply concentration and downstream price differentiation across the market. These logistics costs contribute to the overall pricing structure for both premium cart-based units and value-oriented portable devices.
Pricing Analysis
Long-term contract agreements for hardware procurement and SaaS-tiered subscriptions for cloud-based platforms characterize the dominant pricing models. Price differentiation stems from advanced AI features, the brand premium of established players like Siemens Healthineers, and comprehensive after-sales service bundles. Pricing pressure stems from the rise of value-oriented manufacturers such as Mindray Medical. Private clinics and emerging markets exhibit the highest price sensitivity, while large hospital systems prioritize advanced features and integration capabilities.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the complex manufacturing and distribution networks for ultrasound equipment. Geographic supply concentration for key components exists in China for manufacturing and specialized materials, while Germany and the United States are hubs for advanced system assembly. Raw material dependencies include piezoelectric crystals and specialized microprocessors. Single-source vulnerability for advanced AI chips represents a structural supply chain risk. Distribution runs through direct sales forces for major hospital accounts and extensive distributor networks for private clinics and international markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasound equipment market presents a defensive moat story, largely due to significant regulatory entrenchment and high switching costs associated with integrated hospital IT systems.
For Market Incumbents: Insulate core market share by deepening the integration of AI analytics into existing diagnostic platforms and expanding cloud-based subscription offerings. This strategy counters the threat from emerging software-only AI solutions. Investment in next-generation transducer technology and strategic partnerships for AI development serve as critical levers to maintain technological leadership.
For New Entrants and Emerging Players: Pursue white-space opportunities in therapeutic ultrasound applications or specialized point-of-care niches within underserved regions. Private clinics in emerging markets, such as India and Southeast Asia, represent the most penetrable segments for value-oriented handheld devices. Licensing AI software as a medical device (SaMD) to integrate with third-party hardware offers a scalable go-to-market angle.
For Investors and Strategic Acquirers: Niche AI analytics firms specializing in medical imaging or developers of novel therapeutic ultrasound technologies represent compelling acquisition targets. This market remains attractive over a five-to-ten-year window due to expanding applications and digital transformation. Increasing M&A activity in SaMD companies or significant shifts in regulatory approvals for therapeutic devices signal inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Development | Enhances diagnostic accuracy and workflow efficiency for clinicians. |
| Regulatory Pathway Navigation | Secures market access for innovative devices in the US and Europe. |
| Cloud Platform Expansion | Captures recurring revenue streams from integrated diagnostic services. |
| Emerging Market Localization | Tailors products for regional needs, expanding patient access in India. |
| Therapeutic Application R&D | Unlocks new revenue opportunities beyond traditional diagnostic imaging. |
Research Approach
The analysis maps diagnostic imaging, therapeutic ultrasound, and point-of-care device sub-sectors, each validated through primary interviews with radiologists, hospital procurement managers, and biomedical engineers. This approach combines insights from industry stakeholders with secondary data sources including FDA filings, CE marking databases, and medical device industry reports. Bottom-up and top-down triangulation ensures comprehensive market sizing and segmentation.
The forecast framework assumes continued technological advancements and stable healthcare investment across the analysis window. Segmentation dimensions modeled include product type, application, end-user, deployment model, and regional healthcare expenditure. Compound annual growth rates (CAGRs) were derived from historical trends and projected market dynamics. Key industry-specific forecast inputs include new hospital construction rates in China and the adoption rates of handheld devices in private clinics.
Macroeconomic conditions sit as an overlay; deviation in healthcare spending policies or global economic stability would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Unforeseen regulatory changes, significant technological breakthroughs, or shifts in reimbursement policies represent specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Medical Automation Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
US Durable Medical Equipment Market