
 Global Clinical Trials Matching Software Market | 2026-2036
Global Clinical Trials Matching Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trials Matching Software Market Foresight
Capital-intensity divergence between cloud-native entrants and legacy on-premise incumbents is rotating competitive advantage toward platforms with elastic infrastructure. IQVIA leverages its real-world data networks to sustain geographic dominance across North American trial sites. Deep 6 AI anchors its position through natural language processing specialization that extracts unstructured clinical criteria from electronic health records. TriNetX differentiates by controlling federated data access protocols that preserve patient privacy across hospital systems.
Clinical trials matching software comprises algorithmic platforms that parse structured and unstructured patient data against protocol eligibility criteria, typically processing NLP-derived phenotypes through FHIR-compliant APIs to identify qualified candidates. Its primary commercial purpose is reducing enrollment timelines that currently average 30% of total trial duration. Cloud-based deployments lead solution type adoption due to lower upfront infrastructure costs and faster integration with hospital EHR systems. Oncology studies represent the fastest-growing application segment as immuno-oncology protocols multiply inclusion criteria complexity. Patient recruitment modules capture concentrated margin pools because sponsors directly tie vendor payments to enrollment velocity metrics.
FDA 21 CFR Part 11, EMA GCP guidelines, and HIPAA privacy frameworks collectively shape product development roadmaps by mandating audit trails, informed consent documentation, and de-identification protocols. Japan's PMDA has tightened data localization requirements that favor hybrid deployment architectures with domestic hosting capabilities. Stakeholders must monitor evolving FDA guidance on decentralized trial technologies and artificial intelligence validation standards to anticipate compliance-driven procurement shifts.
Market Dynamics
Algorithmic patient-matching platforms are compressing enrollment timelines by automating eligibility screening against electronic health record repositories. Cloud-native architectures with FHIR-compliant APIs are displacing legacy on-premise installations as hospital systems demand faster integration cycles.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates are forcing sponsors to replace paper-based screening workflows with validated software platforms.
- Oncology protocol complexity:Immuno-oncology trials with 50-plus inclusion criteria are overwhelming manual patient identification methods at academic medical centers.
- Germany's trial density:Concentrated pharmaceutical R&D activity in Munich and Berlin clusters is generating concentrated demand for automated matching infrastructure.
Market Restraints
- Data localization mandates:Japan's PMDA requirements for domestic hosting are fragmenting vendor architectures and raising compliance costs for global deployments.
- EHR interoperability gaps:Non-standardized data formats across hospital systems are limiting algorithmic matching accuracy and requiring expensive custom mapping.
- Specialized NLP talent scarcity:Shortage of engineers trained in clinical natural language processing is constraining platform development velocity.
Strategic Opportunities
- India's underpenetrated site network:Expansion of CDSCO-regulated trial activity in Hyderabad and Mumbai creates first-mover advantage for matching platforms with regional language capabilities.
- Decentralized trial convergence:Integration of telemedicine endpoints with matching algorithms is opening direct-to-patient recruitment channels outside traditional site networks.
- EU AI Act compliance:Proactive alignment with risk-classification frameworks for clinical decision-support tools is creating procurement preference among EMA-regulated sponsors.
Industry Challenges
- HIPAA de-identification complexity:Maintaining Safe Harbor compliance while preserving clinical utility for matching algorithms requires continuous legal-technical coordination.
- Legacy CTMS integration:Custom API development for sponsor-specific clinical trial management systems is extending implementation timelines and consuming professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trials Matching Software Market |
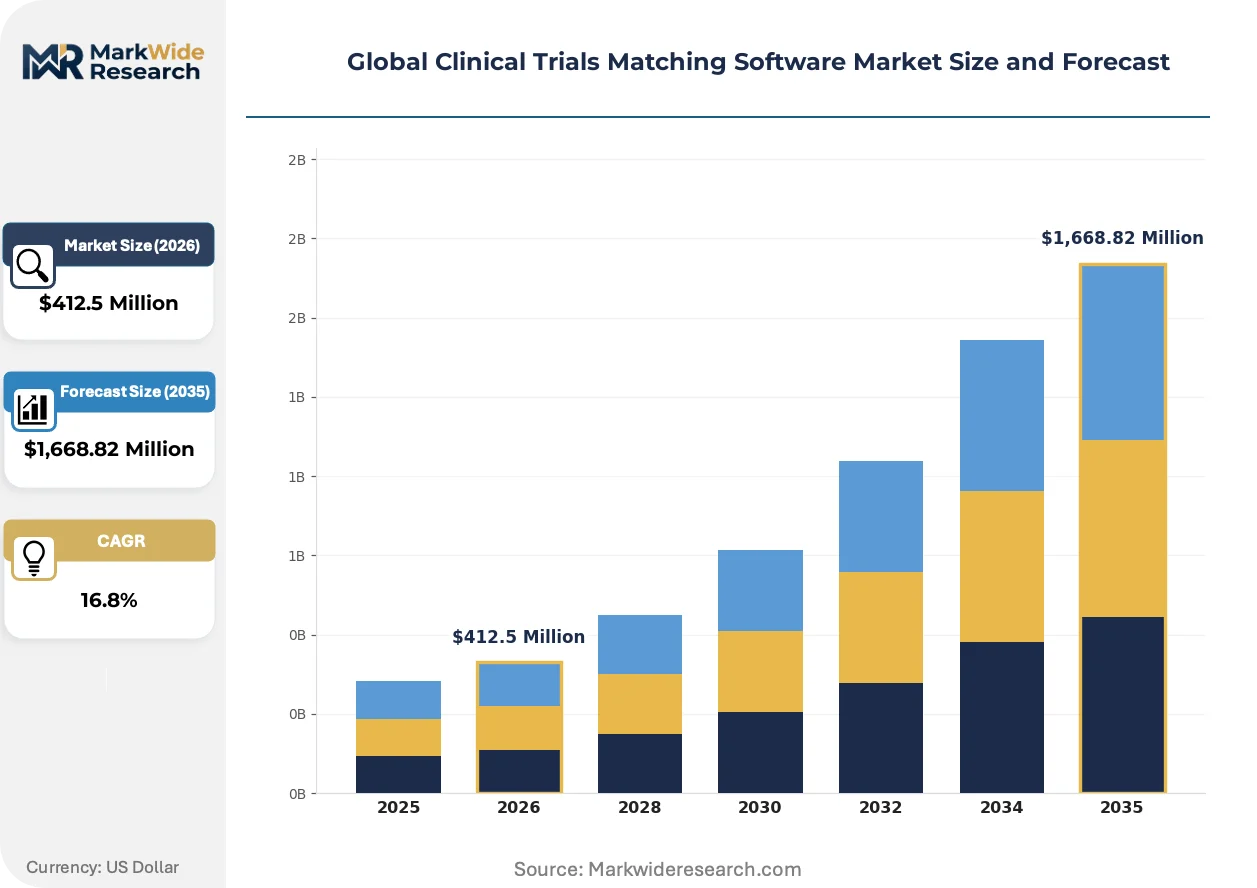
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,668.82 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Patient Recruitment, Protocol Optimization, Data Integration, Outcomes Analysis, Compliance Monitoring Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Application: Oncology Studies, Cardiovascular Studies, Neurology Research, Rare Disease Trials, Infectious Disease Research End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Research Centers, Regulatory Agencies |
| Companies Covered | Antidote Technologies, Advarra, IBM Watson Health, Deep 6 AI, TriNetX, Clario, Clinerion, ArisGlobal, IQVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trials Matching Software Market Shifts & Advancements
Natural language processing engines are extracting unstructured clinical concepts from physician notes with precision rates approaching structured data fields. This capability is eliminating the manual chart review bottleneck that has historically constrained enrollment velocity.
Federated learning architectures are miniaturizing data movement requirements by pushing computation to hospital edge nodes rather than centralizing protected health information. Academic medical centers in Boston and Stanford are deploying these configurations to satisfy institutional review board constraints. The approach is compressing contracting timelines with privacy-sensitive health systems.
EMA's forthcoming guidance on artificial intelligence in clinical development is mandating algorithmic transparency documentation for patient selection tools. Sponsors operating under European jurisdiction are restructuring vendor qualification procedures to preempt validation failures. Oncology trials with adaptive designs are experiencing the most intensive regulatory scrutiny.
Site sponsors are unbundling recruitment services from full-service contract research organization contracts to procure matching software directly. Mid-size biotechnology firms in the San Francisco Bay Area are leading this disintermediation pattern. Direct vendor relationships are shortening procurement cycles from 18 months to under six months.
Global Clinical Trials Matching Software Market Segmentation
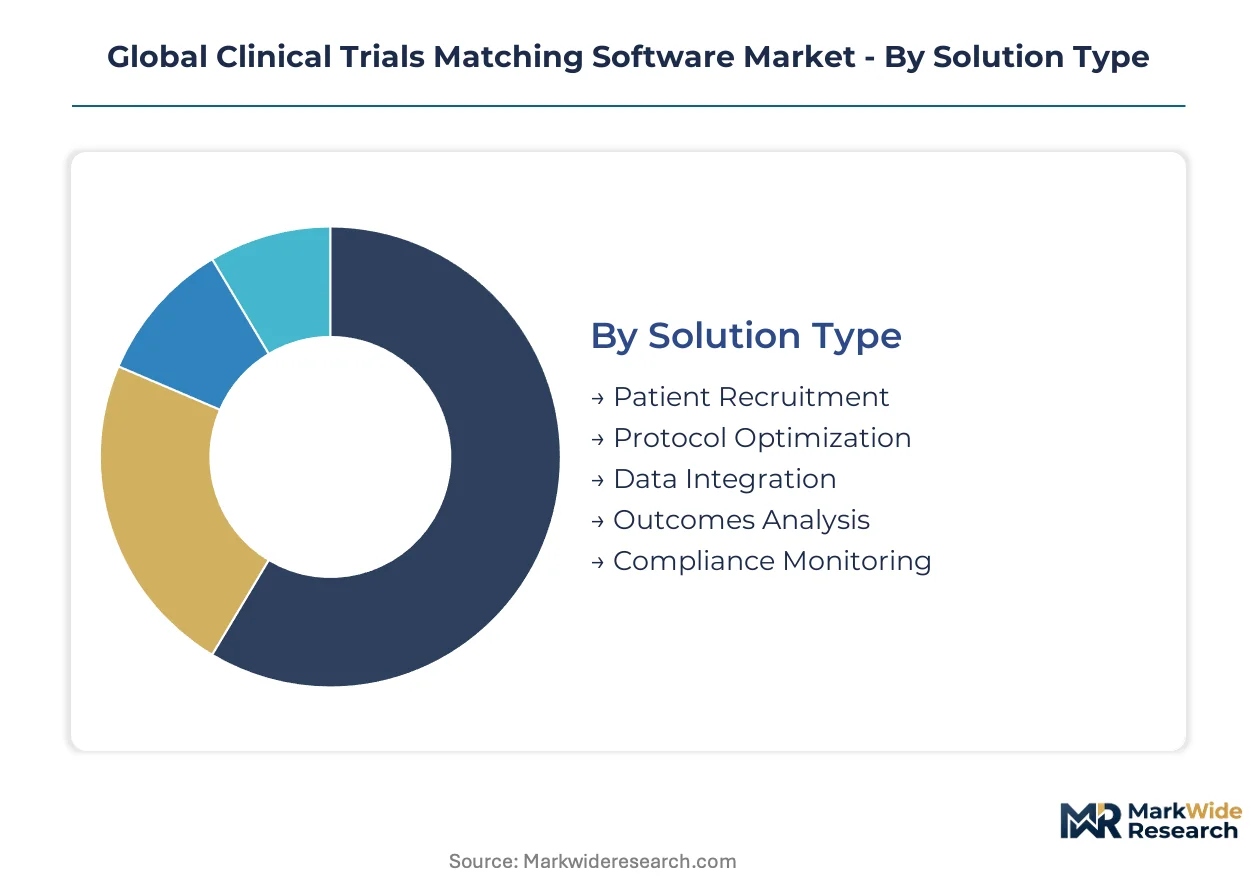
Segmentation in clinical trials matching software reveals how vendor capabilities align with sponsor procurement priorities. Deployment architecture and application complexity drive the steepest divergence in pricing and implementation timelines across customer categories.
Solution Type:
Patient recruitment modules face the strongest substitution pressure from full-service contract research organizations bundling matching services with site management.
- Patient Recruitment:Algorithmic platforms automate eligibility screening against electronic health record repositories, compressing enrollment timelines. Sponsors in the United States and Germany directly tie vendor payments to enrollment velocity metrics, concentrating margin pools in this segment.
- Protocol Optimization:Natural language processing engines parse inclusion criteria complexity against real-world data assets to refine feasibility assumptions. Academic medical centers in Boston and Stanford deploy these tools to preempt protocol amendments that delay study activation.
- Data Integration:FHIR-compliant APIs bridge hospital EHR systems with sponsor clinical trial management systems.
- Outcomes Analysis:Longitudinal tracking modules connect matched patients to treatment response endpoints.
- Compliance Monitoring:Audit trail automation satisfies FDA 21 CFR Part 11 and EMA GCP documentation requirements.
Patient recruitment anchors the volume base while protocol optimization gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates cloud-native entrants from capital-intensive on-premise installations requiring dedicated infrastructure teams.
- Cloud-Based:Elastic infrastructure reduces upfront capital expenditure and accelerates integration cycles with hospital systems. Mid-size biotechnology firms in the San Francisco Bay Area favor this model for trials spanning multiple countries.
- SaaS:Subscription pricing aligns vendor revenue with sponsor study duration, shortening procurement cycles from 18 months to under six months for direct vendor relationships.
- On-Premise:Legacy installations persist at pharmaceutical companies with established data security protocols and captive IT infrastructure.
- Hybrid:Domestic hosting capabilities satisfy Japan's PMDA data localization mandates while maintaining global platform consistency.
- Private Cloud:Isolated environments address institutional review board constraints at privacy-sensitive academic medical centers.
Cloud-based deployments capture the largest revenue share while SaaS models expand most quickly among emerging biotechnology sponsors.
Application:
Maturity gradients separate established therapeutic areas with standardized eligibility criteria from emerging domains requiring adaptive algorithmic approaches.
- Oncology Studies:Immuno-oncology protocols with 50-plus inclusion criteria overwhelm manual patient identification methods. Academic medical centers in Munich and Berlin clusters generate concentrated demand for automated matching infrastructure.
- Rare Disease Trials:Ultra-small patient populations spanning dispersed geographies require federated data access protocols that preserve privacy across hospital systems.
- Cardiovascular Studies:Established endpoint definitions enable straightforward structured data matching against EHR fields.
- Neurology Research:Unstructured clinical notes from specialty clinics demand advanced natural language processing capabilities.
- Infectious Disease Research:Rapid protocol adaptation during outbreak response prioritizes deployment speed over customization depth.
Oncology studies anchor the volume base while rare disease trials gain share at the steepest rate.
End User:
Customer type determines procurement authority and pricing sensitivity, with direct sponsor relationships commanding premium terms versus intermediary-mediated transactions.
- Pharmaceutical Companies:Enterprise-scale deployments across therapeutic portfolios justify dedicated platform instances with custom API development for sponsor-specific clinical trial management systems.
- Contract Research Organizations:Full-service providers bundle matching software with site activation and monitoring services, though site sponsors increasingly disintermediate this relationship.
- Biotechnology Firms:Asset-specific procurement favors modular solutions with rapid implementation timelines.
- Academic Research Centers:Institutional review board constraints prioritize federated learning architectures that miniaturize data movement requirements.
- Regulatory Agencies:Validation toolkits for algorithmic transparency documentation support EMA's forthcoming guidance on artificial intelligence in clinical development.
Pharmaceutical companies anchor the volume base while biotechnology firms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while Germany commands premium terms for compliance-heavy deployments. Japan's data localization mandates fragment vendor architectures and inflate implementation costs. India's underpenetrated site networks create first-mover discounting pressure.
United States
FDA 21 CFR Part 11 compliance requirements and dense pharmaceutical R&D activity drive concentrated demand. The regulation mandates electronic signatures and audit trails that force sponsors toward validated software platforms. Academic medical centers in Boston and the San Francisco Bay Area deploy federated learning architectures to satisfy institutional review board constraints.
Germany
Trial density in Munich and Berlin clusters generates sustained procurement of automated matching infrastructure. EMA Good Clinical Practice standards and forthcoming EU AI Act compliance requirements reshape vendor qualification criteria. Pharmaceutical sponsors in Baden-Württemberg directly tie vendor payments to enrollment velocity metrics.
Japan
PMDA data localization mandates require domestic hosting capabilities that raise compliance costs for global deployments. The regulator's tightening requirements favor hybrid deployment architectures with domestic edge nodes. Tokyo-based hospital systems demand miniaturized data movement through federated protocols to preserve patient privacy.
India
CDSCO-regulated trial expansion in Hyderabad and Mumbai creates demand for matching platforms with regional language capabilities. The national pharmaceutical regulator's evolving framework supports decentralized trial convergence. Site networks in Maharashtra and Karnataka remain underpenetrated by automated screening tools.
United Kingdom
NHS digital transformation programs accelerate FHIR-compliant API integration with hospital EHR systems. MHRA alignment with EMA post-Brexit maintains GCP standard continuity for sponsor operations. London and Cambridge clusters concentrate biotechnology firm procurement of modular recruitment solutions.
Global Clinical Trials Matching Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the market structure. Cloud-native specialists with natural language processing capabilities command premium positioning against legacy on-premise incumbents with captive infrastructure. The vendor base stratifies into three tiers: enterprise-scale platform providers, federated data access specialists, and modular recruitment module vendors. Consolidation pressure operates through M&A activity targeting NLP engineering teams and strategic partnerships bridging EHR interoperability gaps.
Among United States-based platform providers, IQVIA and Deep 6 AI occupy distinct positions within the competitive matrix. IQVIA exemplifies the enterprise-scale archetype through real-world data network integration. Deep 6 AI represents specialization in clinical natural language processing. TriNetX anchors the federated data access tier with privacy-preserving protocols. These three entities collectively illustrate how vendor differentiation concentrates around data asset control and algorithmic extraction capabilities rather than infrastructure scale alone.
| Leading Market Players |
|---|
| Antidote Technologies |
| Advarra |
| IBM Watson Health |
| Deep 6 AI |
| TriNetX |
| Clario |
| Clinerion |
| ArisGlobal |
| IQVIA |
| Others |
Supply & Pricing Matrix
Elastic infrastructure utilization at cloud-native vendors compresses unit economics below legacy on-premise incumbents, concentrating pricing power with platforms achieving hospital network density in the United States and Germany. Scale-driven margin expansion enables aggressive SaaS-tiered pricing that undercuts capital-intensive deployment alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standard SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA 21 CFR Part 11 validation tiers and FHIR API integration depth driving differentiation. Cost compression in the standard tier intensifies as cloud-native entrants compete on implementation speed. Mid-size biotechnology firms in the San Francisco Bay Area exhibit highest price sensitivity, while pharmaceutical companies with captive IT infrastructure tolerate premium configured pricing.
Supply Chain Analysis
Implementation lead times stretch from six to eighteen months depending on EHR interoperability complexity and institutional review board contracting velocity. Engineering talent concentrates in the United States, Germany, and India, with clinical natural language processing specialists commanding scarcity premiums. Platform development draws from academic medical center research partnerships, cloud infrastructure providers, and regulatory compliance consultancies. Single-source vulnerability runs through concentrated NLP engineering pipelines. Distribution runs through direct vendor relationships and contract research organization intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than core platform licensing, with patient recruitment outcome-based pricing and continuous protocol optimization subscriptions outpacing perpetual license growth.
For Market Incumbents: Fortify federated data access capabilities through deeper hospital system integration to defend against cloud-native entrants displacing legacy on-premise installations. Prioritize backward integration into clinical natural language processing engineering teams to constrain talent scarcity risks. EMA's forthcoming AI Act compliance requirements threaten validation failure costs for platforms lacking algorithmic transparency documentation. For New Entrants and Emerging Players: FDA 21 CFR Part 11 certification fast-tracks open procurement pathways at pharmaceutical sponsors replacing paper-based screening workflows. India's underpenetrated site networks in Hyderabad and Mumbai present the most penetrable geography, with regional language capabilities differentiating against English-centric incumbents. Target decentralized trial convergence through telemedicine endpoint integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with elastic infrastructure and direct sponsor relationships. Long-term viability hinges on data asset control rather than infrastructure scale alone. Acquisition candidates with federated learning architectures and privacy-preserving protocols command premium positioning. Monitor EMA AI Act validation standard finalization as the inflection signal for compliance-driven procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | Privacy-preserving computation at hospital edge nodes satisfies institutional review board constraints in Boston and Stanford clusters. |
| FHIR-Compliant API Integration | Standardized health data exchange accelerates EHR connectivity with sponsor clinical trial management systems. |
| Natural Language Processing Talent Acquisition | Clinical NLP engineering teams extract unstructured phenotypes from physician notes with structured-data precision. |
| Hybrid Deployment Infrastructure | Domestic hosting capabilities satisfy Japan's PMDA data localization mandates without fragmenting global platform consistency. |
| Outcome-Based Recruitment Pricing | Vendor payments tied to enrollment velocity metrics concentrate margin pools in patient recruitment modules. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and platform engineers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases anchors the qualitative findings. Bottom-up and top-down triangulation reconciles vendor-reported deployment metrics with sponsor procurement patterns.
Sensitivity analysis across deployment model, organization size, therapeutic vertical, integration complexity, and regional adoption pattern dimensions stress-tests volume and value outputs over the projection horizon. CAGRs derive from algorithmic matching adoption curves, EHR interoperability expansion rates, and regulatory compliance mandate implementation timelines. Oncology protocol complexity indices and decentralized trial technology penetration serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 21 CFR Part 11 enforcement and EMA AI Act compliance timeline adherence; material deviation would warrant model refresh. Forecasts reflect assumptions of hospital system cloud migration velocity and NLP engineering talent supply stability. Revision becomes warranted when data localization mandate proliferation crosses thresholds fragmenting global deployment architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
India CRO Market
Clinical Research
India Preclinical CRO Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Asia-Pacific Contract Research Organization Market