
 Urodynamic Equipment and Consumables Market | 2026-2036
Urodynamic Equipment and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamic Equipment and Consumables Market Analysis
Disposable polymer catheters is rebalancing cost structures against reusable silicone alternatives in urodynamic suites. Laborie Medical Technologies leverages vertical integration across catheter manufacturing to sustain margin control in North American hospital chains. Medtronic PLC anchors its position through R&D intensity in wireless sensor platforms. Boston Scientific Corporation competes via specialized urodynamics software that integrates with existing electronic health record architectures.
Urodynamic equipment and consumables encompass diagnostic systems that measure bladder pressure, urine flow rate, and sphincter electromyography using fluid-filled catheters, pressure transducers, and digital acquisition hardware to evaluate lower urinary tract dysfunction. These systems typically operate at sampling frequencies of 10-50 Hz with pressure measurement ranges of 0-300 cmH₂O for clinical accuracy. Urodynamics systems occupy the largest installed base among product categories, though wireless systems within the technology dimension represent the fastest structural expansion as outpatient clinics seek cable-free examination rooms. Catheters concentrate margin pools through high replacement frequency against durable capital equipment, while diagnostic centers as an end user segment show accelerating procurement of integrated devices that combine cystometry with uroflowmetry.
The FDA governs 510(k) clearance pathways for urodynamic catheters and pressure transducers as Class II devices, while the EU MDR imposes strengthened clinical evidence requirements on urodynamics systems sold in European member states. ISO 13485 certification shapes supplier qualification criteria for hospital procurement committees evaluating catheter vendors. Stakeholders must monitor how wireless connectivity standards intersect with HIPAA data transmission rules as cloud-based urodynamic analysis expands beyond on-premise storage architectures.
Market Dynamics
Wireless sensor architectures are compressing replacement cycles for catheter-based urodynamic systems as hospitals prioritize cable-free examination workflows and cloud-connected diagnostic platforms.
Growth Catalysts
- EU MDR clinical evidence mandates:Strengthened post-market surveillance requirements for Class IIa urodynamics systems are filtering out marginal suppliers and consolidating procurement toward ISO 13485-certified vendors with robust quality management systems.
- Ambulatory surgical centers:Freestanding urology clinics across Germany and the Netherlands are deploying compact wireless uroflowmetry units to expand service capacity without capital-intensive infrastructure buildouts.
- Pressure transducer miniaturization:MEMS-based sensing elements are enabling single-use catheter designs that eliminate sterilization logistics while maintaining 0-300 cmH₂O measurement fidelity.
Market Restraints
- Silicone polymer price volatility:Medical-grade elastomer feedstock costs fluctuate with petrochemical indices, squeezing margins on reusable catheter portfolios against fixed-price hospital contracts.
- Single-use plastic directives:France's AGEC law and similar national sustainability frameworks impose extended producer responsibility fees on disposable catheter manufacturers, complicating cost structures.
- Wireless coexistence limitations:2.4 GHz spectrum congestion in dense clinical environments creates interference risks for Bluetooth-enabled urodynamic sensors, requiring redundant wired backup configurations.
Strategic Opportunities
- India's tertiary hospital expansion:Government-funded medical college hospitals under the Pradhan Mantri Swasthya Suraksha Yojana are installing urodynamics laboratories with preference for integrated cystometry-uroflowmetry systems.
- Artificial intelligence convergence:Machine learning algorithms applied to pressure-flow tracings are automating detrusor overactivity detection, creating software-as-a-service revenue streams atop hardware installations.
- Direct-to-clinic distribution:Manufacturers are bypassing traditional medical device distributors to establish captive e-commerce portals serving independent urology practices with just-in-time catheter replenishment.
Industry Challenges
- Clinical engineer scarcity:Healthcare technology management departments face recruitment gaps for specialists capable of calibrating multi-channel pressure transducers and troubleshooting wireless telemetry faults.
- HIPAA-compliant cloud architecture:Urodynamics vendors must re-engineer data pipelines to satisfy business associate agreement requirements when transmitting patient bladder pressure recordings to third-party analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamic Equipment and Consumables Market |
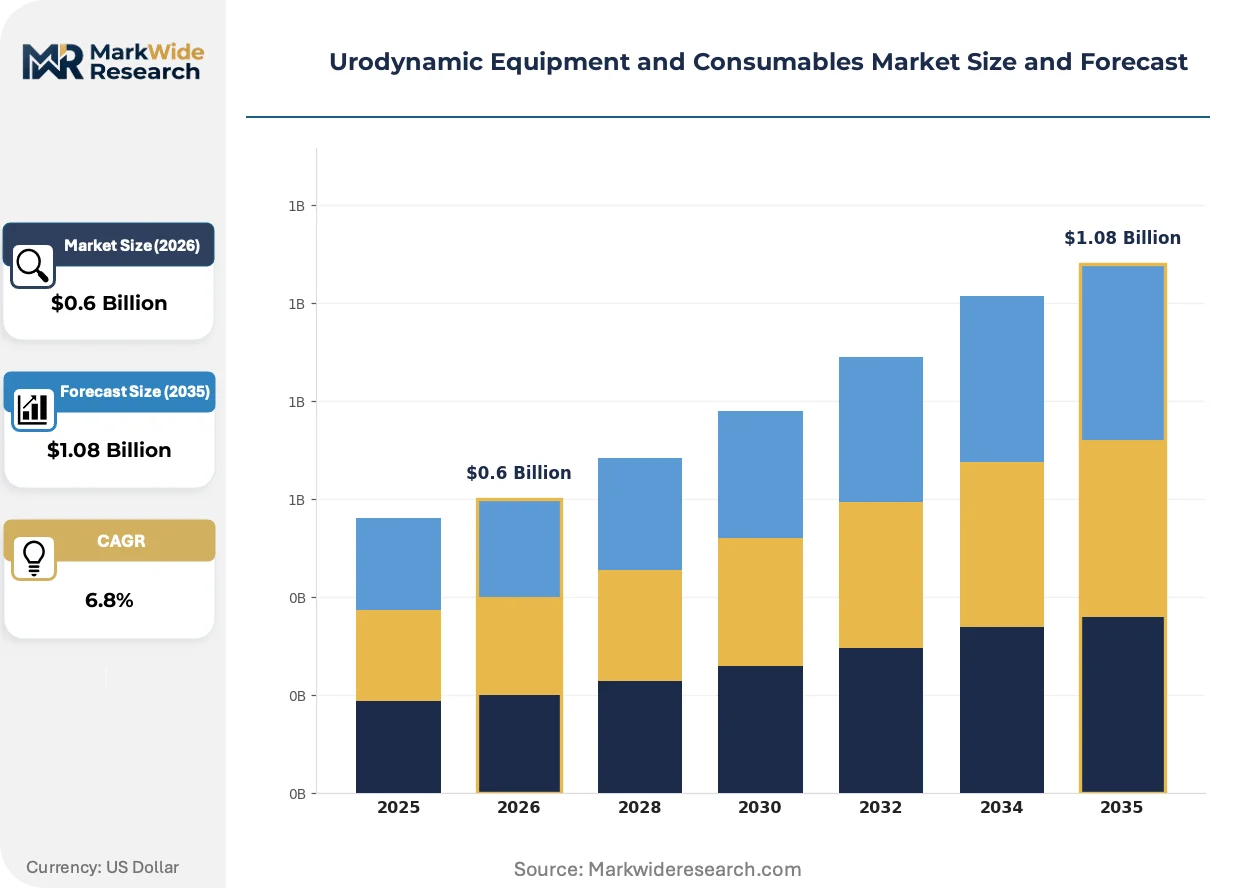
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urodynamics Systems, Catheters, Pressure Transducers, Software Solutions End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Technology: Types of Sensors, Data Analysis Tools, Wireless Systems, Integrated Devices Application: Urinary Incontinence, Bladder Dysfunction, Neurological Disorders, Others |
| Companies Covered | Verathon Inc, Boston Scientific Corporation, Laborie Medical Technologies, Medtronic PLC, Cook Medical, The Prometheus Group, Albyn Medical Ltd, Digitimer Ltd, Cooper Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamic Equipment and Consumables Market Emerging Trajectories
Digital acquisition hardware is displacing analog chart recorders across urodynamics suites, while regulatory frameworks and procurement behaviors co-evolve around connected diagnostic ecosystems.
Wireless bladder pressure monitoring is integrating with electronic health record APIs to enable real-time waveform streaming from examination rooms to centralized review stations. Outpatient urology clinics in the United States are adopting these systems fastest, driven by Medicare reimbursement incentives for comprehensive diagnostic evaluations. This connectivity architecture is compressing report turnaround times and enabling remote specialist consultations for complex lower urinary tract dysfunction cases.
Japan's PMDA has tightened software validation requirements for urodynamics systems incorporating automated measurement algorithms, mandating standalone clinical performance trials for AI-assisted pressure-flow analysis modules. Domestic manufacturers must submit predicate device comparisons demonstrating equivalent safety profiles to legacy catheter-based systems. Smaller developers lacking regulatory affairs infrastructure are partnering with established device firms to navigate premarket notification pathways.
Hospital procurement committees are bundling catheter supply contracts with multi-year equipment service agreements, shifting vendor selection criteria from capital cost minimization toward total cost of ownership optimization. Integrated delivery networks in Texas and California are piloting consignment inventory models where manufacturers retain ownership of catheter stock until point-of-use consumption. This arrangement transfers working capital burden upstream while locking in exclusive supply relationships.
Urodynamic Equipment and Consumables Market Segmentation
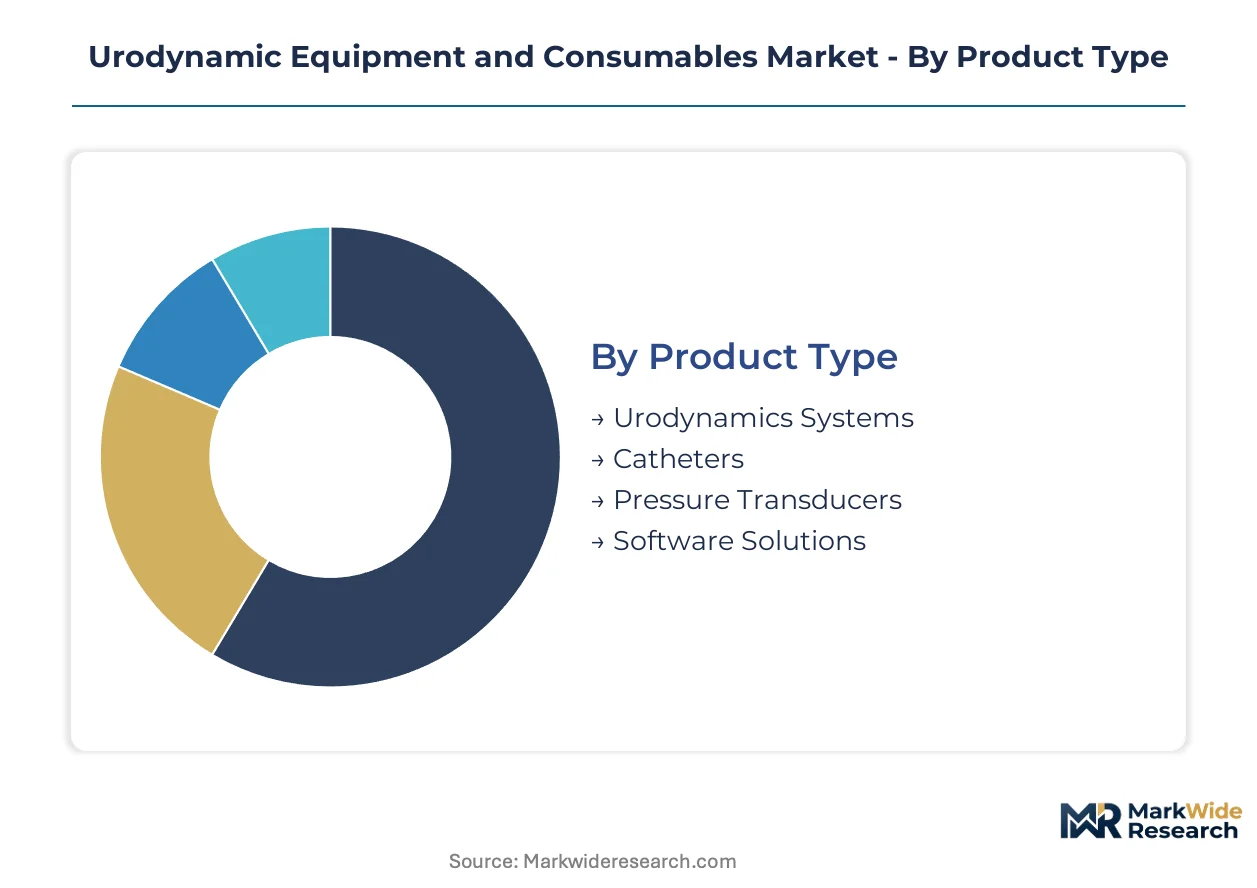
Urodynamic market segmentation reveals divergent capital requirements across diagnostic hardware, disposable consumables, and software platforms. Procurement committees weight upfront equipment investment against recurring catheter replenishment cycles when structuring vendor contracts.
Product Type:
Capital intensity varies sharply between durable systems and single-use components, with pressure transducer manufacturing demanding the steepest upfront tooling investment.
- Urodynamics Systems:Multi-channel acquisition hardware sampling at 10-50 Hz dominates hospital laboratory budgets. German university hospitals anchor installed capacity through centralized diagnostic hubs serving regional referral networks.
- Catheters:Fluid-filled polymer tubes with pressure lumens require sterile manufacturing environments but lower per-unit capital than transducer fabrication. France's AGEC law imposes extended producer responsibility fees on disposable catheter portfolios, reshaping total cost calculations.
- Pressure Transducers:MEMS-based sensing elements enable 0-300 cmH₂O measurement fidelity.
- Software Solutions:Digital waveform analysis platforms integrate with electronic health record APIs.
Urodynamics systems absorb the bulk of installed capacity; wireless-enabled platforms within this category are expanding most quickly.
End User:
Procurement authority concentrates in institutions with dedicated urology departments and capital equipment committees.
- Hospitals:Tertiary medical centers in India under the Pradhan Mantri Swasthya Suraksha Yojana are installing integrated cystometry-uroflowmetry laboratories. These facilities prioritize multi-channel systems capable of handling complex lower urinary tract dysfunction referrals.
- Diagnostic Centers:Freestanding facilities combine rapid report turnaround with specialized technician staffing. Outpatient urology clinics across Germany and the Netherlands deploy compact wireless uroflowmetry units to expand service capacity without infrastructure buildouts.
- Clinics:Independent practices favor consignment inventory models transferring working capital burden upstream.
- Research Laboratories:Academic medical centers require FDA 510(k) cleared devices for clinical trial endpoints.
Hospitals command the largest capital deployment; diagnostic centers are gaining share fastest through ambulatory service expansion.
Technology:
Sensor architecture determines replacement cycle length and interoperability with existing hospital information systems.
- Wireless Systems:Bluetooth-enabled telemetry eliminates cable clutter in examination rooms. Dense clinical environments face 2.4 GHz spectrum congestion risks requiring redundant wired backup configurations.
- Integrated Devices:Combined cystometry-uroflowmetry platforms reduce footprint in space-constrained facilities. Texas and California integrated delivery networks pilot these systems to standardize diagnostic protocols across affiliate sites.
- Types of Sensors:Strain gauge and capacitive pressure elements compete on calibration stability.
- Data Analysis Tools:Machine learning algorithms automate detrusor overactivity detection from pressure-flow tracings.
Wireless systems capture the steepest expansion trajectory; integrated devices are consolidating procurement preference in multi-site health systems.
Application:
Clinical indication drives test complexity and reimbursement coding, shaping equipment specification requirements.
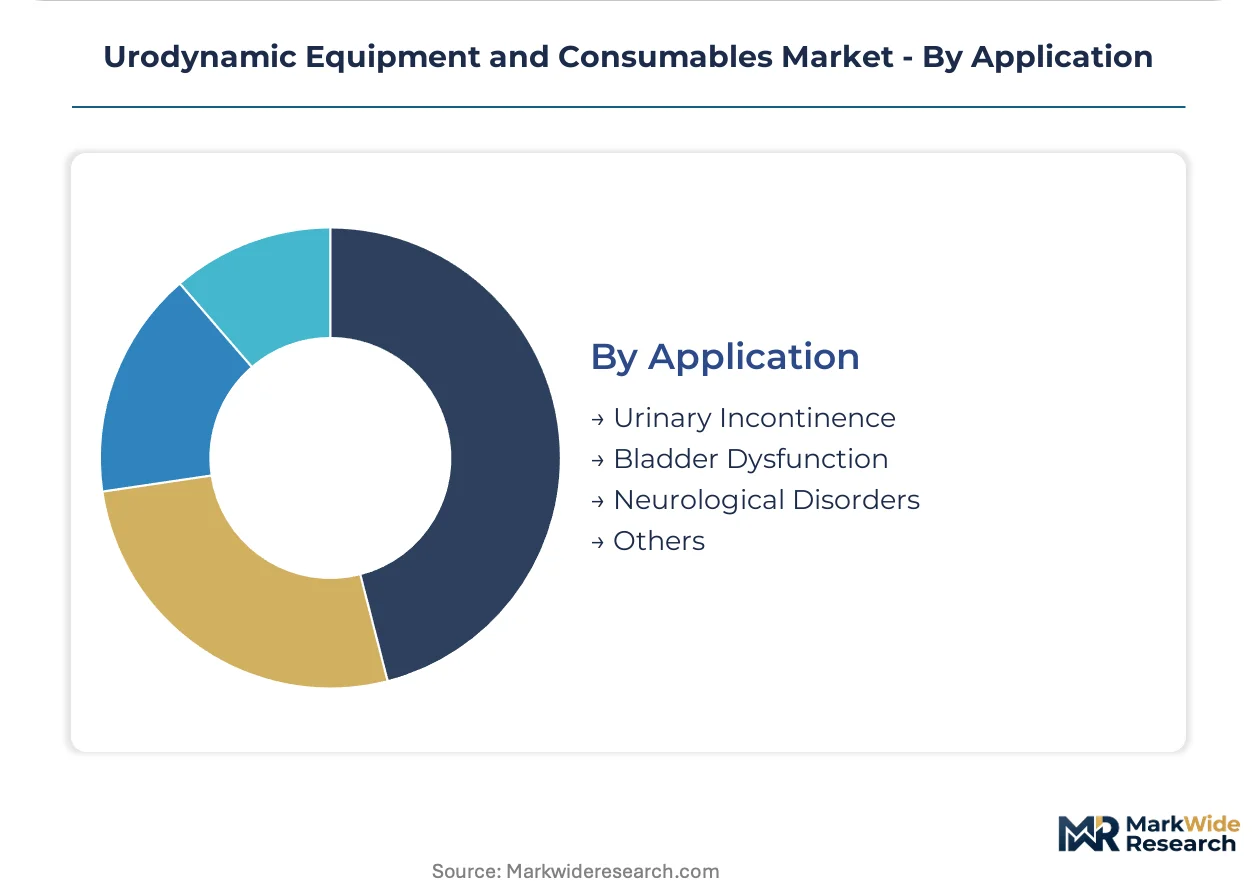
- Urinary Incontinence:Stress and urge incontinence evaluations constitute the highest procedure volume. Medicare reimbursement incentives in the United States accelerate comprehensive diagnostic workup adoption in outpatient settings.
- Bladder Dysfunction:Detrusor overactivity and underactivity assessments demand multi-channel pressure-flow analysis. Japan's PMDA mandates standalone clinical performance trials for automated measurement algorithms in this indication.
- Neurological Disorders:Neurogenic bladder evaluation requires electromyography synchronization.
- Others:Post-procedural monitoring and pediatric cases represent specialized subsegments.
Urinary incontinence procedures absorb the bulk of test volume; bladder dysfunction applications are climbing the fastest as automated analysis reduces interpretation burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the highest clinical research volumes for urodynamic diagnostics, with university hospitals anchoring procurement decisions across Western Europe. National health technology assessment bodies in France and the Netherlands are accelerating wireless system adoption through outpatient reimbursement incentives. India's tertiary hospital expansion under central government programs is creating new installed base growth in Asia-Pacific.
United States
Medicare reimbursement codes for comprehensive urodynamic studies drive outpatient clinic investment in multi-channel acquisition systems. The FDA's updated 510(k) guidance for Class II pressure transducers tightens validation requirements for wireless sensor platforms. Texas and California integrated delivery networks pilot consignment inventory models that transfer catheter working capital burden upstream to manufacturers.
Germany
University hospitals in Heidelberg and Munich anchor regional referral networks for complex lower urinary tract dysfunction cases. The EU MDR's strengthened clinical evidence requirements for Class IIa urodynamics systems filter procurement toward ISO 13485-certified vendors. Baden-Württemberg medical device clusters concentrate pressure transducer manufacturing expertise for MEMS-based sensing elements.
India
Government-funded medical college hospitals under the Pradhan Mantri Swasthya Suraksha Yojana are installing integrated cystometry-uroflowmetry laboratories. The Central Drugs Standard Control Organization governs import licensing for urodynamic catheters and pressure transducers as notified medical devices. Maharashtra and Karnataka tertiary centers prioritize multi-channel systems capable of handling neurogenic bladder referrals from surrounding states.
Japan
Academic medical centers in Tokyo and Osaka require PMDA-cleared devices with standalone clinical performance trials for AI-assisted pressure-flow analysis. The Pharmaceuticals and Medical Devices Agency tightened software validation requirements for automated measurement algorithms in 2024. Domestic manufacturers partner with established device firms to navigate premarket notification pathways for wireless telemetry systems.
France
The AGEC law imposes extended producer responsibility fees on disposable catheter manufacturers, reshaping total cost calculations for hospital procurement committees. ANSM post-market surveillance requirements align with EU MDR implementation timelines for urodynamics systems. Paris and Lyon university hospitals concentrate demand for combined cystometry-uroflowmetry platforms in space-constrained facilities.
Urodynamic Equipment and Consumables Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with catheter consumables showing higher fragmentation than integrated systems. Three archetypes dominate: diversified medical technology conglomerates with urology divisions, pure-play urodynamics specialists with captive catheter production, and regional distributors private-labeling OEM components. Competitive moves concentrate on backward integration into polymer extrusion and strategic partnerships with hospital procurement networks.
Among North American diversified manufacturers, Boston Scientific Corporation and Medtronic PLC exemplify the conglomerate archetype with broad urology portfolios. Laborie Medical Technologies occupies a position within the pure-play specialist tier. Verathon Inc represents the technology-focused segment with emphasis on digital acquisition platforms. These three companies anchor competitive dynamics through differentiated channel strategies rather than direct product confrontation.
| Leading Market Players |
|---|
| Verathon Inc |
| Boston Scientific Corporation |
| Laborie Medical Technologies |
| Medtronic PLC |
| Cook Medical |
| The Prometheus Group |
| Albyn Medical Ltd |
| Digitimer Ltd |
| Cooper Surgical |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees in Germany are consolidating catheter supply contracts under multi-year equipment service agreements, forcing manufacturers to absorb working capital burdens through consignment inventory models while locking in exclusive supply relationships that reshape margin structures across the value chain.
Pricing Analysis
Volume concentrates in single-use polymer catheters while margins pool in wireless urodynamics systems. Three-tier pricing structure across premium wireless platforms, standard integrated devices, and economy catheter lines separates ISO 13485-certified vendors from regional distributors. Pricing pressure stems from France's AGEC law imposing extended producer responsibility fees on disposable portfolios. Independent urology clinics exhibit highest price sensitivity; university hospitals in Germany show lowest.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg and Massachusetts anchor hub-and-spoke patterns serving hospital chains and ambulatory surgical centers. Manufacturing concentrates in Germany, the United States, and Japan. MEMS pressure sensing elements and medical-grade silicone polymers constitute critical input dependencies. Single-source vulnerability runs through specialized MEMS foundry capacity. Distribution runs through captive e-commerce portals and traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 certification scarcity constrains supplier qualification, propping pricing power for certified manufacturers while filtering marginal competitors from hospital procurement shortlists.
For Market Incumbents: Cement market position by deepening backward integration into polymer extrusion for catheter manufacturing and securing exclusive GPO contracts with Texas and California integrated delivery networks. Wireless telemetry patent portfolios defend against emerging sensor platform entrants. Captive supply of pressure transducer components insulates margins from silicone polymer price volatility. For New Entrants and Emerging Players: EU MDR in Germany opens a window for ISO 13485-certified contract manufacturers to capture share from legacy suppliers lacking robust quality management systems. India's tertiary hospital expansion under Pradhan Mantri Swasthya Suraksha Yojana represents the most penetrable geography. Direct-to-clinic e-commerce distribution bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors pure-play urodynamics specialists with captive catheter production and established hospital system partnerships. Acquisition targets should demonstrate installed base expansion in wireless-enabled platforms. Watch FDA 510(k) clearance velocity for AI-assisted pressure-flow analysis modules as inflection signal for software-as-a-service revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Wireless sensor platforms require updated Class II validation under tightened FDA guidance for hospital adoption. |
| CE Marking Pathway | EU MDR clinical evidence mandates filter procurement toward vendors with robust post-market surveillance infrastructure. |
| Hospital System Partnership | Consignment inventory models with Texas integrated delivery networks transfer working capital burden upstream to manufacturers. |
| Software Companion Development | Machine learning algorithms for detrusor overactivity detection create recurring SaaS revenue atop hardware installations. |
| Reimbursement Strategy | Medicare coding for comprehensive urodynamic studies drives outpatient clinic investment in multi-channel acquisition systems. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract records, complemented by interviews with hospital biomedical engineers, urology department heads, medical device regulatory affairs specialists, and catheter manufacturing plant managers. Secondary validation drew from SEC 10-K disclosures, ISO 13485 certification registries, and CMS Medicare reimbursement data. Bottom-up installed base estimates triangulated against top-down market sizing.
Segmented outputs across product type, end user, technology, and application dimensions fed into growth trajectory modeling over the projection horizon. Cystometry-uroflowmetry integration rates and wireless system replacement cycles served as industry-specific demand drivers. CAGRs derived from logistic diffusion curves fitted to hospital capital expenditure patterns and catheter replenishment frequencies.
Caveats apply where FDA guidance revisions, EU MDR implementation delays, or silicone polymer feedstock disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Global Intraoperative Radiation Therapy Market