
 Cryopreservation Systems Market | 2026-2036
Cryopreservation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cryopreservation Systems Market Analysis
Biorepository procurement channels are reshaping how cryopreservation equipment reaches end users, with distributors consolidating around validated cold-chain partners. Thermo Fisher Scientific leverages its installed base of ultra-low temperature freezers to control aftermarket service revenue. Merck KGaA sustains R&D intensity in cryoprotectant formulations. Sartorius AG specializes in single-use accessories that integrate with third-party freezer platforms.
Cryopreservation systems encompass mechanical freezers, liquid nitrogen dewars, controlled-rate freezing instruments, and ancillary consumables designed to maintain biological specimens below minus 130 degrees Celsius to arrest metabolic activity. These systems serve pharmaceutical manufacturing, clinical diagnostics, and academic research by preserving cell viability across extended storage intervals. Freezers dominate installed value due to capital intensity and replacement cycles, while vitrification solutions capture recurring revenue streams through protocol-specific formulations. Mechanical cryocoolers gain share in facilities seeking to reduce liquid nitrogen dependency and associated supply volatility.
The FDA enforces current Good Manufacturing Practice standards for cryopreserved cell therapies, while the EMA's ATMP guidelines mandate traceable temperature monitoring across distribution networks. ISO 20387 establishes biobanking quality benchmarks that shape equipment qualification requirements in Europe and Asia-Pacific facilities alike. Stakeholders must weigh capital deployment between mechanical and hybrid cooling architectures as energy costs and refrigerant regulations tighten operational constraints.
Market Dynamics
Mechanical cryocooler technology is hybridizing with liquid nitrogen backup systems to resolve energy cost volatility and refrigerant phase-out pressures reshaping capital deployment decisions across biorepositories and cell therapy manufacturing facilities.
Growth Catalysts
- EMA ATMP Guidelines:The European Medicines Agency's advanced therapy medicinal products framework mandates traceable cold-chain documentation, forcing biobanks to upgrade monitoring infrastructure and expand controlled-rate freezer procurement.
- Stem Cell Banking Expansion:Government-funded stem cell repositories in China are scaling cryogenic storage capacity to serve regenerative medicine pipelines, driving bulk orders for high-capacity liquid nitrogen dewars and automated inventory systems.
- Vitrification Protocol Standardization:Clinical adoption of ultra-rapid cooling methods for oocyte and embryo preservation is displacing slow-freezing techniques, creating pull-through demand for specialized cryoprotectant formulations and programmable freezing instruments.
Market Restraints
- Liquid Nitrogen Supply Concentration:Industrial gas production clusters in the United States Gulf Coast and Northwestern Europe expose biorepositories to regional supply disruptions and price spikes during fertilizer manufacturing cycles.
- Refrigerant Regulatory Friction:The EPA's phasedown of hydrofluorocarbons under the AIM Act compresses equipment replacement timelines for mechanical freezers using legacy coolants, stranding installed base value.
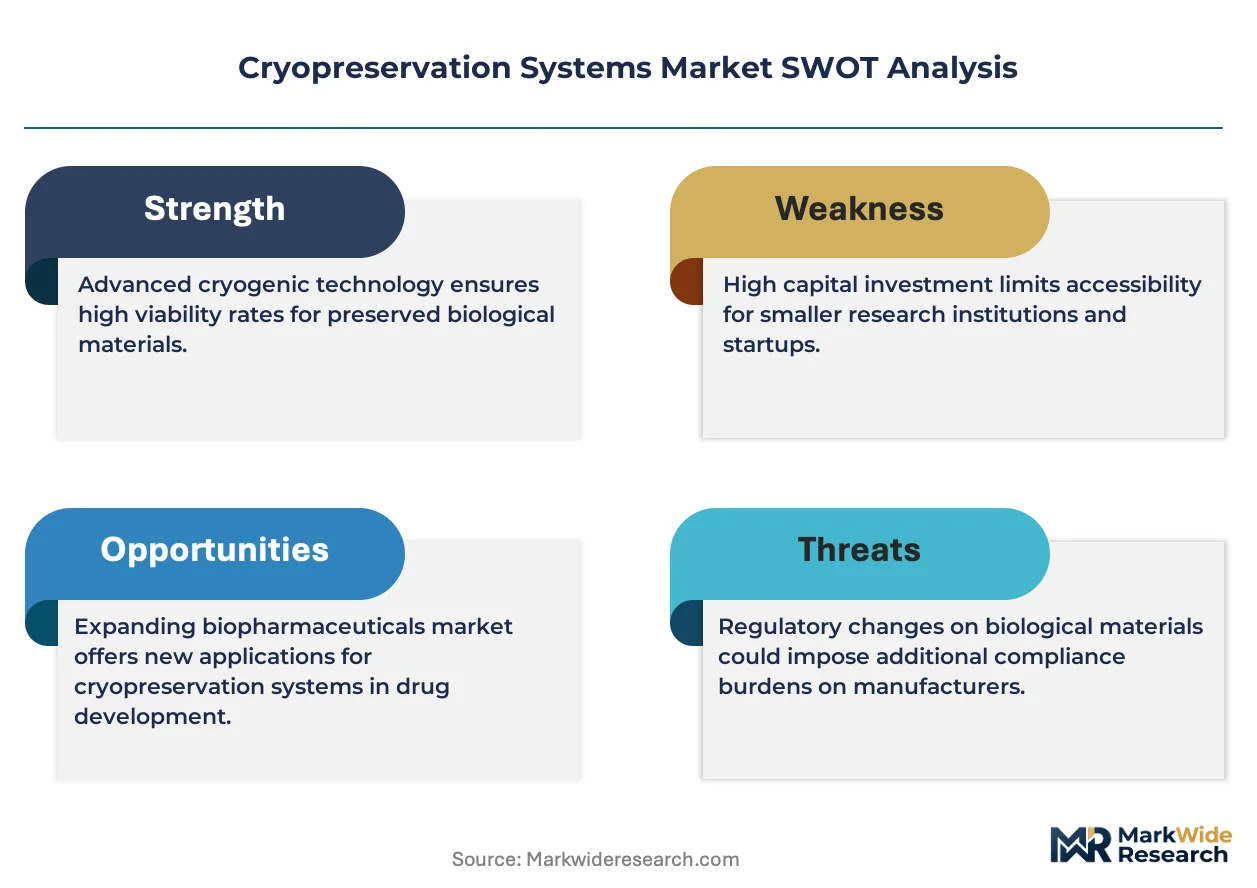
- Capital Intensity Barriers:Automated sample retrieval systems and integrated cold-chain monitoring platforms require seven-figure capital commitments that exclude mid-sized academic research centers from upgrading legacy infrastructure.
Strategic Opportunities
- India Biobanking Infrastructure:The country's national cancer grid and emerging cell therapy startups lack standardized cryopreservation capacity, opening white space for equipment vendors offering lease-to-own financing and validation support.
- CAR-T Manufacturing Localization:Regional production of chimeric antigen receptor T-cell therapies in Singapore and South Korea requires distributed cryogenic storage networks rather than centralized biorepository models.
- ISO 20387 Certification Tailwinds:Biobanking quality standard adoption across Asia-Pacific research hospitals creates compliance-driven replacement cycles for non-validated freezer equipment and manual temperature logging systems.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Facilities report twelve-month hiring timelines for technicians qualified in both ultra-low temperature system maintenance and GMP documentation protocols.
- Legacy Integration Complexity:Biorepositories with decades-old sample collections face data migration and physical transfer risks when retrofitting automated storage and retrieval systems into existing infrastructure.
- Validation Timeline Compression:The FDA's updated cell therapy guidance accelerates equipment qualification requirements, forcing manufacturers to parallel-track IQ/OQ/PQ protocols with production ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryopreservation Systems Market |
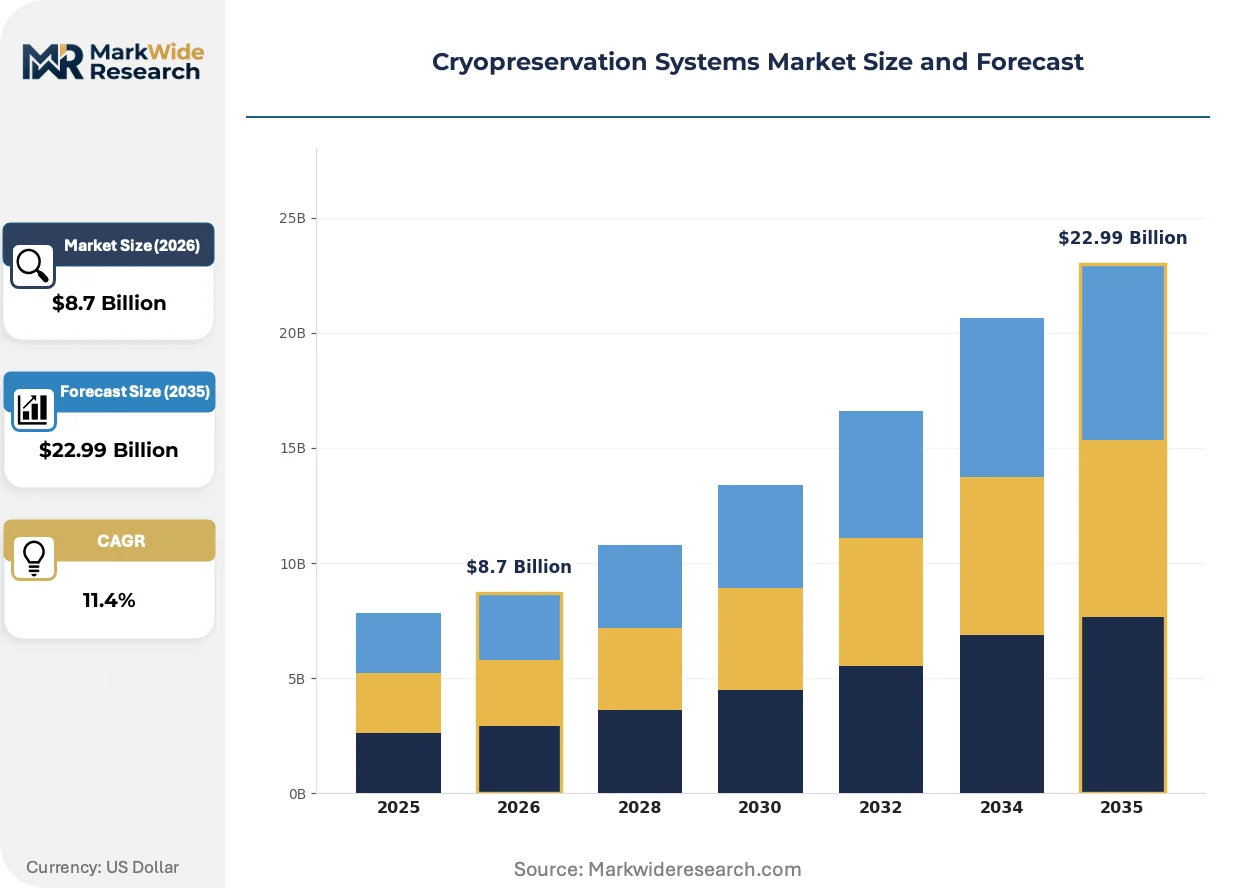
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freezers, Vitrification Solutions, Biorepositories, Controlled-rate Freezers Technology: Liquid Nitrogen, Mechanical Cryocoolers, Hybrid Systems, Air-blast Freezers End User: Research Laboratories, Fertility Clinics, Blood Banks, Manufacturing Facilities Application: Stem Cell Preservation, Biological Sample Storage, Organ Preservation, Gamete Storage |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, BioLife Solutions Inc., PHC Holdings Corporation, Lonza, PromoCell GmbH, Corning Incorporated, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryopreservation Systems Market Emerging Trajectories
Equipment architecture is converging around hybrid cooling designs that reduce operational dependency on volatile liquid nitrogen supply chains while preserving sample integrity during power interruptions.
Stirling engine-based mechanical cryocoolers is hybridizing with vacuum-insulated liquid nitrogen backup reservoirs to create dual-mode systems. Cell therapy contract manufacturers in Massachusetts and North Carolina are specifying these configurations for new facilities. The technology is hybridizing capital equipment procurement patterns by extending replacement cycles and compressing aftermarket service contract margins for pure-play liquid nitrogen system vendors.
The EPA's hydrofluorocarbon phasedown under the AIM Act is accelerating adoption of natural refrigerant alternatives in ultra-low temperature freezer designs. Equipment manufacturers are redesigning compressor architectures to accommodate hydrocarbon and carbon dioxide coolants. North American biorepositories face the most compressed compliance timelines, with several large academic medical centers piloting hydrocarbon-based units ahead of 2025 regulatory milestones.
Biopharma procurement teams are unbundling equipment purchases from multi-year service agreements that historically locked in OEM maintenance revenue. Third-party validation specialists and independent cold-chain monitoring providers are capturing service margins previously retained by freezer manufacturers. This pattern is most visible among mid-sized contract development and manufacturing organizations in the Research Triangle and San Diego clusters seeking operational flexibility.
Cryopreservation Systems Market Segmentation
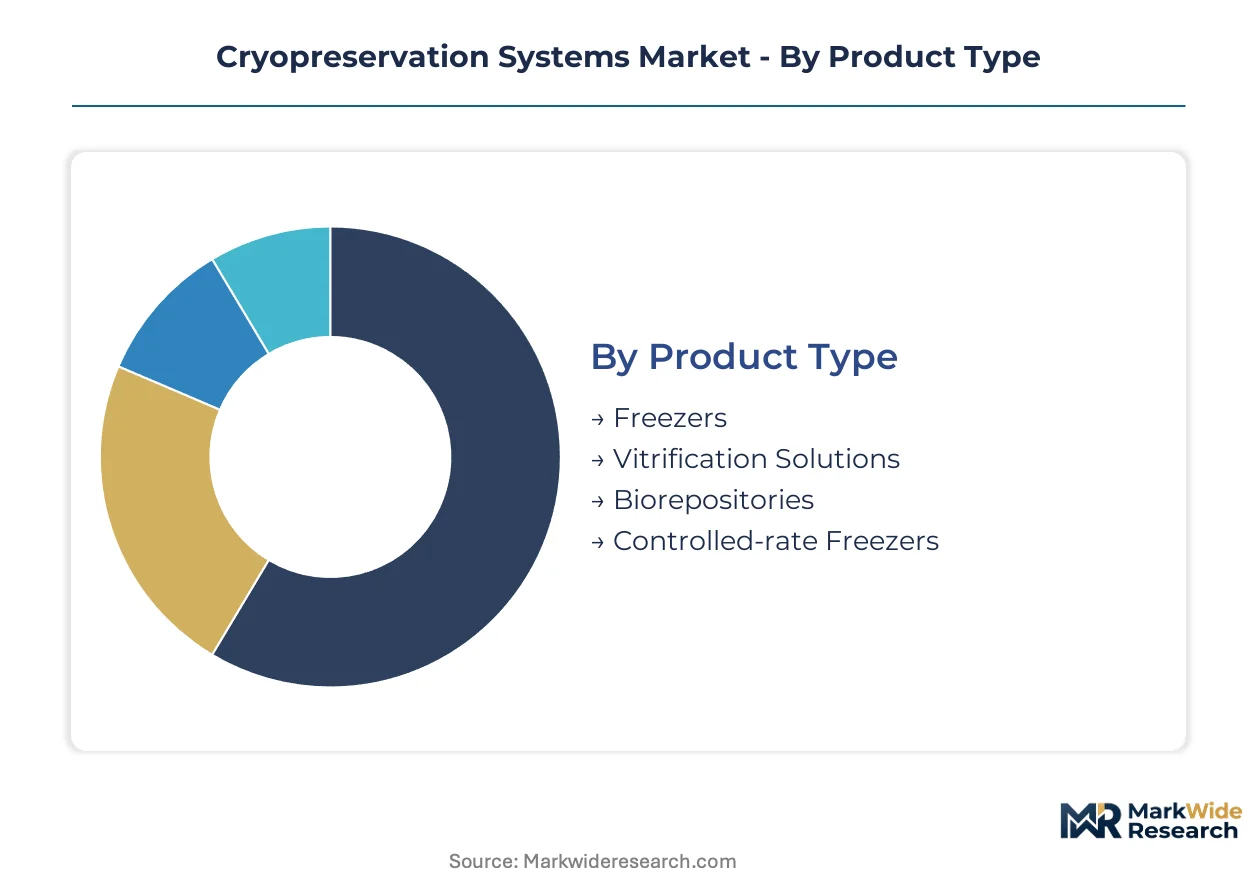
Cryopreservation systems serve divergent operational requirements across biopharma manufacturing and clinical settings. Equipment selection hinges on temperature stability demands, sample throughput, and regulatory validation burdens rather than capital cost alone.
Product Type:
After-sales-service intensity varies sharply across product categories, with mechanical freezers generating recurring calibration and compressor maintenance revenue while consumable-driven segments rely on reagent replenishment cycles.
- Freezers:Ultra-low temperature mechanical units and liquid nitrogen dewars constitute the capital backbone of biorepository infrastructure. Pharmaceutical manufacturing facilities in Massachusetts and North Carolina drive replacement demand as EPA refrigerant phasedowns accelerate equipment refresh cycles.
- Vitrification Solutions:Cryoprotectant formulations enable ultra-rapid cooling protocols that arrest ice crystal formation in oocyte and embryo preservation. Fertility clinics in Spain and Italy are displacing slow-freezing methods, pulling through specialized DMSO-free and ethylene glycol-based reagent volumes.
- Biorepositories:Integrated storage facilities combine equipment, inventory management software, and sample logistics services. China's government-funded stem cell banks anchor procurement scale through centralized high-capacity installations.
- Controlled-rate Freezers:Programmable instruments manage cooling curves for GMP-compliant cell therapy manufacturing. The FDA's updated guidance on cold-chain integrity tightens IQ/OQ/PQ validation requirements for these systems.
By volume, Freezers leads. By growth pace, Vitrification Solutions is climbing the fastest.
Technology:
Technology selection determines operational expenditure profiles and supply chain risk exposure for end users managing irreplaceable biological collections.
- Liquid Nitrogen:Dewar-based systems deliver temperatures below minus 150 degrees Celsius through evaporative cooling. Industrial gas production concentration on the US Gulf Coast exposes users to regional supply disruptions during fertilizer manufacturing peaks.
- Mechanical Cryocoolers:Stirling engine and cascade compressor systems eliminate cryogenic fluid dependency. Academic medical centers in Germany pilot hydrocarbon-refrigerant units ahead of F-Gas Regulation compliance deadlines.
- Hybrid Systems:Dual-mode architectures combine mechanical primary cooling with liquid nitrogen backup reservoirs. Cell therapy contract manufacturers specify these configurations to hedge against power interruption risks.
- Air-blast Freezers:Convective cooling systems serve lower-tier temperature requirements in blood banking and plasma storage applications. Blood centers in Brazil deploy these units for intermediate holding prior to long-term cryogenic transfer.
By installed base, Liquid Nitrogen dominates. By replacement velocity, Hybrid Systems is gaining share fastest.
End User:
End-user procurement authority varies from centralized capital committees at manufacturing facilities to principal-investigator-driven purchasing in academic settings.
- Research Laboratories:University and institutional biobanks manage diverse sample collections across principal investigator portfolios. ISO 20387 certification requirements in Japan and Australia are forcing upgrades from manual temperature logging systems.
- Fertility Clinics:Assisted reproduction centers prioritize vitrification protocols for oocyte and embryo banking. Regulatory frameworks in France and the United Kingdom mandate traceable chain-of-custody documentation for gamete storage.
- Blood Banks:Transfusion services and cord blood repositories require high-availability systems for inventory management. India's national cancer grid is expanding cryogenic capacity to support emerging cell therapy manufacturing.
- Manufacturing Facilities:GMP-compliant cell and gene therapy production sites demand validated cold-chain infrastructure. Singapore and South Korea are localizing CAR-T production, requiring distributed cryogenic networks rather than centralized biorepository models.
By capital deployment, Manufacturing Facilities leads. By expansion rate, Fertility Clinics shows the steepest trajectory.
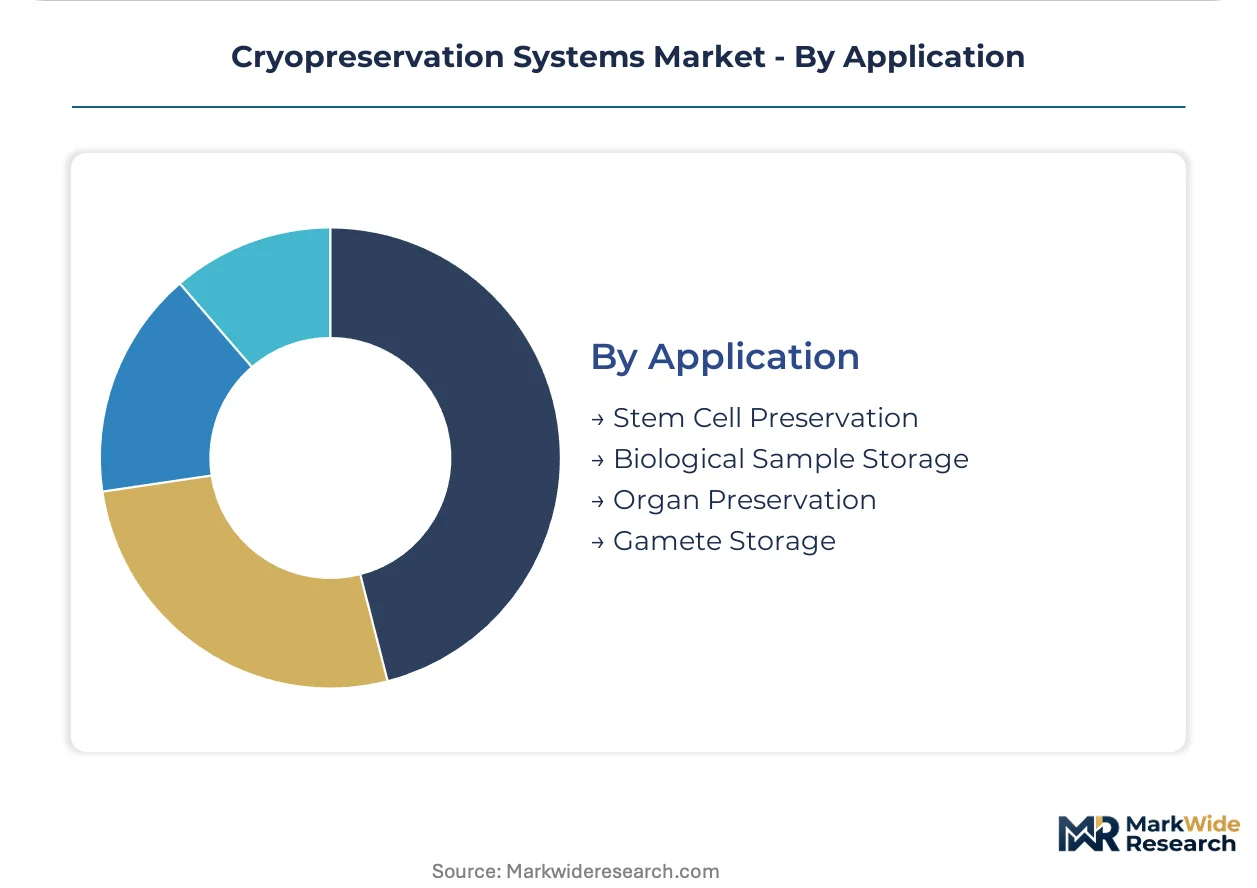
Application:
Application-specific protocols dictate equipment specifications, with cell therapy manufacturing imposing the most stringent temperature uniformity and documentation requirements.
- Stem Cell Preservation:Umbilical cord blood and induced pluripotent stem cell banking requires indefinite storage stability. China's expanding network of government-funded repositories anchors bulk equipment procurement.
- Biological Sample Storage:Tumor biopsies, serum collections, and genomic material repositories support longitudinal research studies. Biobanks in the United Kingdom face legacy integration complexity when retrofitting automated retrieval systems into decades-old infrastructure.
- Organ Preservation:Extracorporeal perfusion and supercooling protocols extend viable transport windows for transplantation. Research hospitals in Switzerland and the Netherlands pilot machine perfusion platforms with integrated cryogenic components.
- Gamete Storage:Sperm, oocyte, and embryo banking for fertility preservation and donor programs. Social egg freezing demand in urban centers across the United States and Spain is expanding clinic storage capacity requirements.
By repository scale, Stem Cell Preservation leads. By protocol innovation velocity, Gamete Storage is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded stem cell banking initiatives and tightening cell therapy cold-chain regulations are redistributing procurement volumes across national biorepository networks. Facilities in jurisdictions with advanced ATMP frameworks command premium equipment specifications, while emerging markets absorb lease-to-own financing structures.
United States
The FDA's updated guidance on cell and gene therapy cold-chain integrity accelerates equipment validation timelines for Massachusetts and North Carolina cell therapy contract manufacturers. The EPA's AIM Act hydrofluorocarbon phasedown compresses mechanical freezer replacement cycles, stranding legacy coolant-dependent installed bases. Greater Boston bioclusters pilot hydrocarbon-refrigerant ultra-low temperature units ahead of 2025 compliance deadlines.
China
Expanding government-funded stem cell repositories anchor bulk procurement for high-capacity liquid nitrogen dewars and automated inventory systems. The National Medical Products Administration harmonizes biobanking quality benchmarks with international standards. Yangtze River Delta research hospitals scale cryogenic storage to serve regenerative medicine pipelines.
Germany
The EMA's ATMP guidelines mandate traceable temperature monitoring, forcing biobanks to upgrade from manual logging systems. The F-Gas Regulation accelerates natural refrigerant adoption in academic medical center freezer fleets. Bavarian research institutions pilot hydrocarbon-based mechanical cryocoolers ahead of EU-wide compliance deadlines.
India
The national cancer grid and emerging cell therapy startups lack standardized cryopreservation capacity, opening white space for equipment vendors offering validation support. The Central Drugs Standard Control Organization drafts biobanking quality standards aligned with ISO 20387. Maharashtra-based research hospitals expand cryogenic infrastructure to support localized CAR-T manufacturing.
Singapore
Regional CAR-T production localization requires distributed cryogenic storage networks rather than centralized biorepository models. The Health Sciences Authority enforces GMP-aligned cold-chain documentation for advanced therapy manufacturing. Biopolis research clusters specify hybrid cooling architectures to hedge against tropical climate power interruption risks.
Cryopreservation Systems Market Vendor Landscape
On the supply side, the industry is consolidating around integrated equipment-service platforms while fragmenting across specialized consumable niches. Diversified laboratory conglomerates leverage installed base lock-in to capture aftermarket calibration and maintenance revenue. Three archetypes dominate: capital equipment OEMs with validation expertise, cryoprotectant formulation specialists, and single-use accessory integrators. Competitive moves center on unbundling service agreements from equipment sales and hybrid cooling technology licensing.
Within the diversified laboratory technology tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify contrasting strategic positions. The former anchors capital equipment procurement channels through ultra-low temperature freezer installed bases. The latter occupies a position in cryoprotectant formulation R&D intensity. Sartorius AG represents the single-use accessory integration archetype, sitting within third-party platform ecosystems rather than competing for primary freezer sales.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sartorius AG |
| BioLife Solutions Inc. |
| PHC Holdings Corporation |
| Lonza |
| PromoCell GmbH |
| Corning Incorporated |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific refrigerated container lanes from Shanghai to Long Beach transmit LNG freight cost volatility into liquid nitrogen dewar landed prices, compressing margins for mid-tier biorepository equipment vendors while amplifying price spreads between GMP-validated and research-grade freezer tiers.
Pricing Analysis
Certification level (ISO 20387/FDA-grade) creates the primary spread between equipment tiers, with GMP-validated controlled-rate freezers commanding substantial premiums over research-grade mechanical units. Three-tier pricing structure across premium, standard, and economy levels reflects validation burden, after-sales bundling intensity, and regional service network density. Pricing pressure stems from third-party validation specialists unbundling service agreements from OEM equipment sales, eroding captive maintenance revenue. Academic research centers exhibit highest price sensitivity due to grant-funded capital constraints, while cell therapy contract manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
Export controls on Stirling engine cryocooler technology limit component flows from Germany and Japan into Chinese manufacturing facilities, constraining hybrid system production capacity. Compressor assemblies draw from specialized suppliers in the United States and Germany, while cryogenic-grade aluminum alloys and vacuum insulation panels rest on Japanese and South Korean material streams. Single-source vulnerability concentrates in precision temperature sensor modules sourced from Swiss manufacturers. Distribution runs through validated cold-chain logistics partners rather than traditional laboratory equipment distributors, with biorepository operators consolidating procurement around integrated equipment-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through biorepository network consolidation, with pharmaceutical manufacturing facilities and government-funded stem cell banks extracting volume discounts and unbundled service terms from legacy OEM relationships.
For Market Incumbents: Build switching-cost moats through embedded IoT monitoring platforms that lock biorepositories into proprietary data architectures. Deepen aftermarket capture by acquiring third-party validation specialists before they scale. Hybrid cooling technology licensing represents the critical defensive lever against mechanical-only competitors facing refrigerant phasedown deadlines. Threat substitution from natural refrigerant startups demands accelerated hydrocarbon-based product line transitions. For New Entrants and Emerging Players: India's fragmented biobanking infrastructure offers the most penetrable white space, with national cancer grid expansion outpacing domestic equipment supply. Lease-to-own financing structures unlock capital-constrained academic medical centers excluded from seven-figure automated retrieval system deployments. Target validation-support bundling as the primary go-to-market angle, differentiating against incumbent equipment-only sales motions. For Investors and Strategic Acquirers: Cryoprotectant formulation specialists with GMP-grade manufacturing capabilities represent the most attractive acquisition archetype, capturing recurring revenue streams with lower capital intensity than freezer OEMs. Long-term viability hinges on protocol standardization tailwinds in cell therapy manufacturing. Watch FDA guidance acceleration on cold-chain integrity as the signal for compliance-driven replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cooling Technology Licensing | Cell therapy manufacturers in Massachusetts specify dual-mode architectures to hedge power interruption risks. |
| Third-Party Validation Specialist Acquisition | Unbundled service agreements erode OEM maintenance margins across Research Triangle CDMO clusters. |
| Natural Refrigerant Product Line Transition | EPA AIM Act phasedown deadlines compress compliance timelines for hydrocarbon-based freezer adoption. |
| Lease-to-Own Financing Program Launch | India's emerging cell therapy startups lack standardized cryopreservation capacity for capital purchase. |
| ISO 20387 Certification Support Bundling | Asia-Pacific research hospitals face compliance-driven replacement cycles for manual temperature logging systems. |
Methodological Framework
A spread of perspectives from biorepository operations directors, GMP manufacturing quality leads, cryogenic equipment procurement managers, and cold-chain logistics specialists converged on the working assumptions driving segment-level demand projections. Primary fieldwork across North American, European, and Asia-Pacific facilities combined with secondary validation from FDA guidance documents, EMA ATMP framework updates, ISO 20387 biobanking standards, and national stem cell bank procurement disclosures. Bottom-up equipment shipment analysis and top-down biopharma capital expenditure tracking triangulated market sizing across the projection horizon.
Demand-supply balance modeling anchored volume forecasts, with segmentation across product type, cooling technology architecture, end-user procurement authority, and application-specific protocol requirements. Cryogenic storage capacity expansion pipelines, cell therapy manufacturing facility buildouts, and fertility clinic vitrification protocol adoption curves fed analytical frameworks. CAGRs derived from equipment replacement cycle compression, regulatory compliance deadline clustering, and regional biobanking infrastructure investment trajectories without year-specific milestone anchoring.
Practitioners should monitor EPA refrigerant phasedown acceleration, EMA ATMP guideline enforcement intensity, and liquid nitrogen supply disruption patterns for early signals of forecast deviation. Material shifts in hybrid cooling technology cost curves or cryoprotectant formulation patent expiries would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Medical Filter Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Surgical Table Market