
 Proctologic Table Market | 2026-2036
Proctologic Table Market Size, Share, and Industry Trends Forecast 2026-2036
Proctologic Table Market Analytics
Specialized biomedical technician availability is reorganizing how manufacturers scale service networks across Europe. SCHMITZ u. Söhne leverages its German engineering heritage to dominate electromechanical table production for hospital systems. AGA Sanitätsartikel GmbH anchors its position through deep specialization in pneumatic-assisted positioning mechanisms for proctology suites. Bıçakcılar Medical Devices competes aggressively on cost-engineered manual and hydraulic variants for clinic-tier buyers in Eastern Europe and Central Asia.
A proctologic table is a purpose-built patient support platform featuring height adjustability typically spanning 50-90 centimeters, Trendelenburg and reverse-Trendelenburg tilt capability, and integrated leg support abduction to enable access to the perineal region during anorectal examination and intervention. Electric tables with programmable memory positioning command premium placement in surgical centers where turnover efficiency determines throughput. Hydraulic variants retain substantial share in cost-sensitive clinic environments where power infrastructure reliability varies. The electromechanical technology segment captures the fastest expansion as digital position feedback integrates with operating room workflow systems.
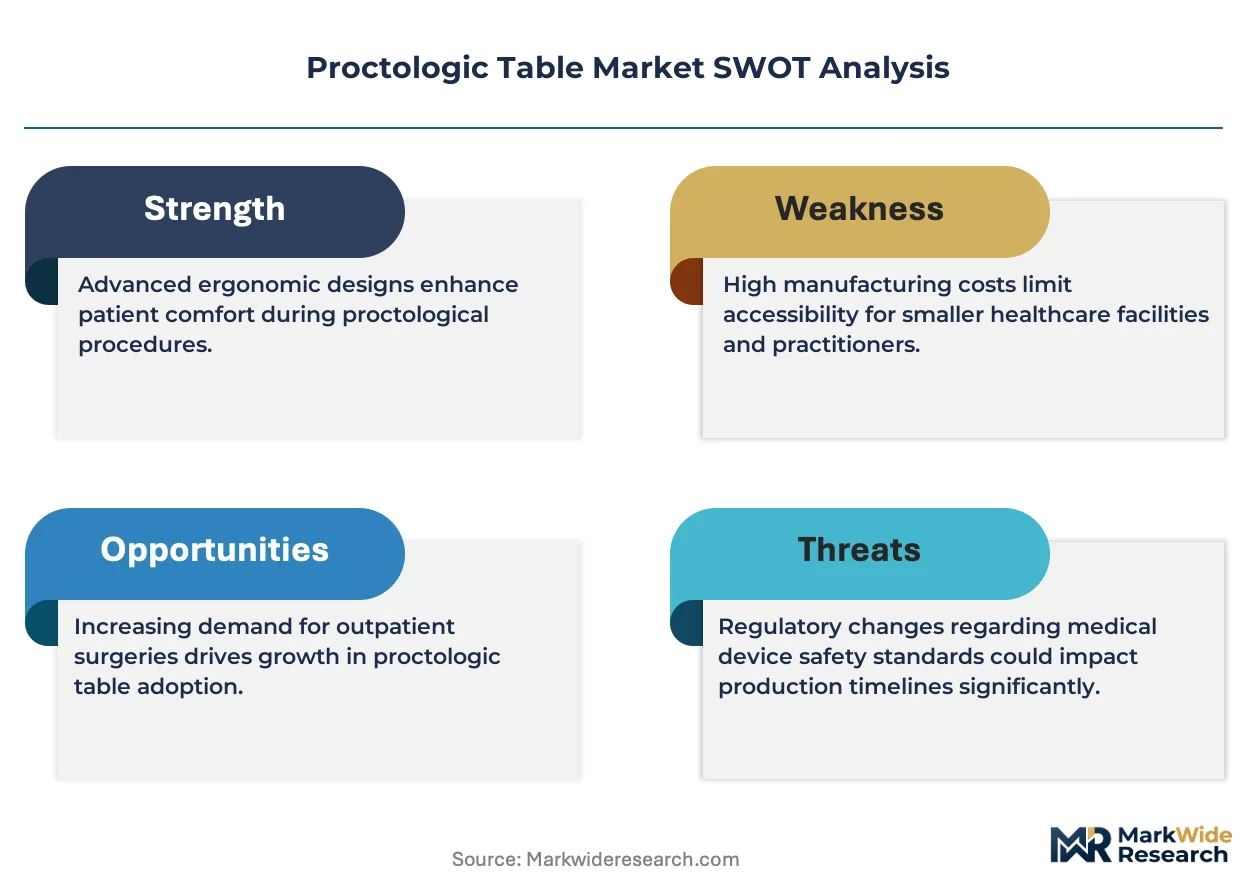
The EU Medical Device Regulation and CE marking framework govern market access for patient support equipment across member states, with notified bodies intensifying scrutiny of electrical safety and biocompatibility documentation for powered tables. Germany's KBA-equivalent medical device surveillance and Turkey's Ministry of Health import registration requirements create layered compliance obligations for non-European suppliers. ISO 13485 quality management certification functions as a baseline qualifier for procurement eligibility in public hospital tenders. Stakeholders must weigh the capital intensity of digital platform development against the margin compression risk from standardized manual table commoditization.
Market Dynamics
EU Medical Device Regulation compliance timelines are compressing procurement cycles as hospital systems accelerate replacement of legacy positioning equipment ahead of 2027 certificate renewal deadlines.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day procedure volume in Germany and Turkey is driving procurement of powered tables with programmable memory positioning. These facilities prioritize turnover efficiency over capital cost.
- MDR conformity alignment:CE marking under the EU Medical Device Regulation now mandates enhanced electrical safety documentation. Manufacturers completing notified body reviews early capture tender eligibility advantages.
- Pneumatic-assisted positioning:Pneumatic mechanisms for leg support abduction are penetrating mid-tier clinic installations where electromechanical infrastructure remains unreliable.
Market Restraints
- Biomedical technician scarcity:Specialized service capacity concentrates in Germany and Northern Italy, limiting manufacturer ability to scale preventive maintenance networks into Eastern Europe and Central Asia.
- Steel and aluminum input volatility:Electromechanical table frames require precision-machined alloys. Price swings in European metal markets compress margin buffers for cost-engineered manual variants.
- Hydraulic fluid environmental compliance:REACH restrictions on specific hydraulic oil formulations force reformulation cycles that delay product recertification.
Strategic Opportunities
- Turkish domestic production incentives:Turkey's Ministry of Health import registration requirements create localization pull for manufacturers establishing electromechanical assembly within the country.
- Digital workflow integration:Operating room information systems in Italian hospital systems now demand position feedback APIs. Tables with native connectivity command placement preference.
- Refurbishment channel development:Secondary market for certified pre-owned powered tables remains underdeveloped in Poland and Romania, creating service-revenue expansion potential.
Industry Challenges
- ISO 13485 auditor availability:Notified body capacity constraints extend quality management recertification timelines, freezing new product introductions for six to nine months.
- Legacy hydraulic inventory integration:Clinic buyers in Bulgaria and Serbia operate mixed fleets of manual and powered tables. Spare parts standardization across generations strains distributor inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proctologic Table Market |
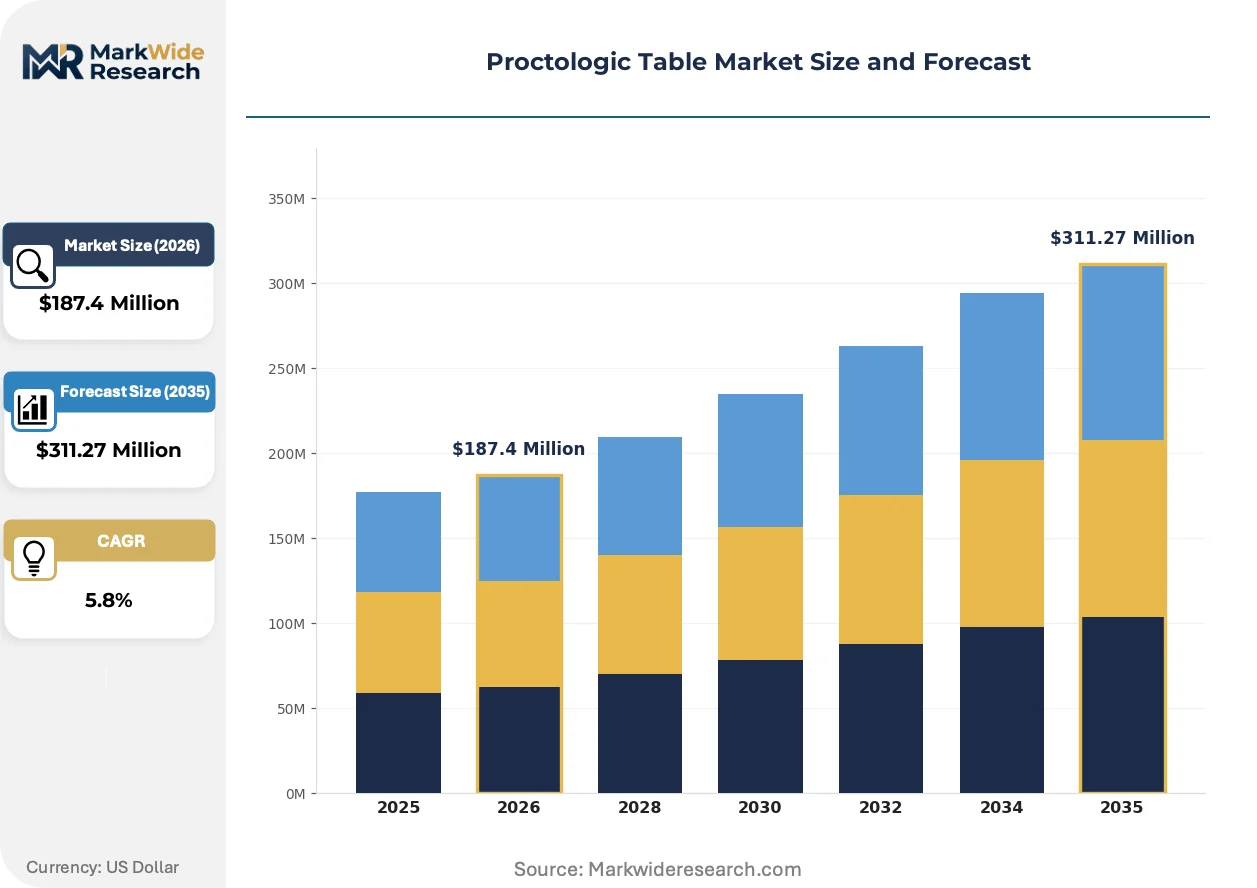
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Table, Hydraulic Table, Electric Table, Adjustable Table End User: Hospitals, Clinics, Surgical Centers, Proctology Practices Technology: Electromechanical, Pneumatic, Mechanical, Digital Application: Diagnostic Procedures, Therapeutic Treatments, Minimally Invasive Surgery, Patient Examination |
| Companies Covered | AR-EL MEDICAL PRODUCTS, Promotal, Bıçakcılar Medical Devices, ECHOMED INDUSTRIAL, SCHMITZ u. Söhne, RQL, Wardray Premise, AGA Sanitätsartikel GmbH, PROJESAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proctologic Table Market Evolving Landscape
Digital position feedback systems are rewiring competitive advantage in surgical infrastructure procurement, compressing the performance gap between premium electromechanical platforms and mid-tier alternatives.
Programmable memory positioning is supplanting manual crank adjustment in ambulatory surgical centers across Germany and Northern Italy. Surgical coordinators at high-throughput facilities prioritize single-button recall of lithotomy and jackknife configurations. This capability is compressing table turnover intervals from four minutes to under ninety seconds, enabling case volume expansion without physical capacity investment.
EU Medical Device Regulation notified body scrutiny of electrical safety documentation intensified through 2024. Manufacturers now submit accelerated life testing data for motor drive systems alongside biocompatibility assessments for patient contact surfaces. Powered table suppliers with early MDR certificate holdings capture tender preference in French and Dutch public hospital systems where procurement committees weight compliance documentation scores.
Hospital procurement committees now unbundle after-sales service from equipment capital cost, negotiating multi-year preventive maintenance contracts separately. German university hospitals pioneered this model, and Italian regional health authorities adopted similar frameworks in 2023. Distributors with captive biomedical technician networks capture recurring revenue streams that offset compressed equipment margins.
Proctologic Table Market Segmentation
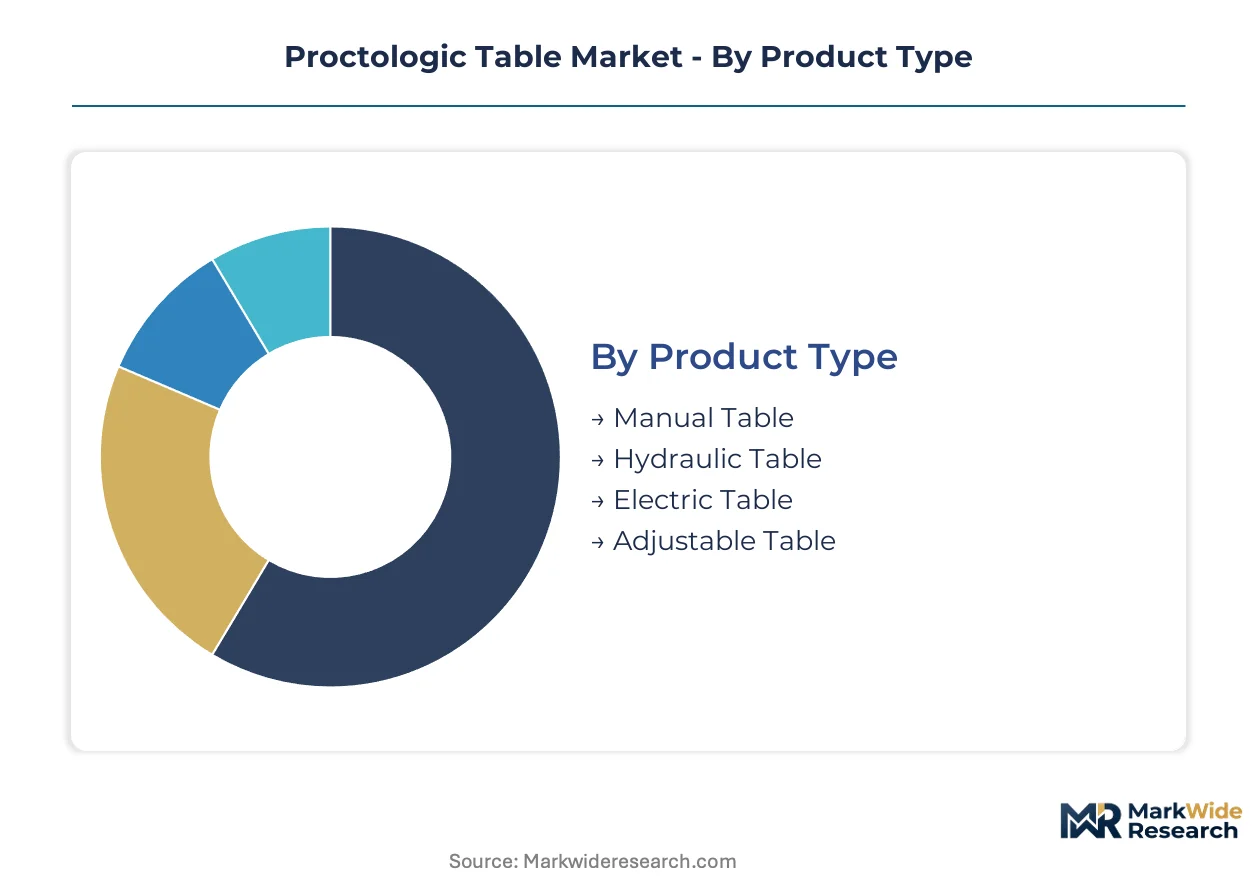
Proctologic table procurement patterns diverge sharply across facility tiers and clinical workflows. CE marking requirements under the EU Medical Device Regulation create divergent compliance burdens that reshape segment prioritization for manufacturers and distributors.
Product Type:
EU MDR electrical safety documentation mandates split the competitive landscape between powered and non-powered variants, with notified body scrutiny intensifying for motorized positioning systems.
- Electric Table:Programmable memory positioning enables single-button recall of lithotomy and jackknife configurations. German ambulatory surgical centers prioritize these systems where turnover compression from four minutes to ninety seconds justifies capital expenditure.
- Hydraulic Table:Fluid-actuated height adjustment operates without electrical infrastructure, suiting Bulgarian and Serbian clinics with unreliable power supply. REACH reformulation cycles for hydraulic oils periodically delay recertification.
- Manual Table:Hand-crank mechanisms dominate cost-engineered procurement in Eastern Europe and Central Asia where capital constraints override efficiency considerations.
- Adjustable Table:Modular frame systems accommodate retrofit accessories across mixed fleet installations common in Polish regional hospitals.
Electric tables handle the majority of throughput in high-volume surgical infrastructure; manual tables are gaining share fastest in clinic-tier expansion markets.
End User:
Facility capital intensity determines positioning technology selection, with procurement committees unbundling equipment from service contracts in German and Italian health systems.
- Surgical Centers:Same-day procedure volume in Turkey and Germany drives demand for powered tables with programmable positioning. These facilities negotiate multi-year preventive maintenance separately from capital acquisition.
- Hospitals:Integrated perioperative suites require digital workflow connectivity through position feedback APIs, now mandatory in Italian regional health authority tenders.
- Clinics:Cost-sensitive purchasers in Romania and Bulgaria favor pneumatic-assisted or hydraulic variants where infrastructure reliability varies.
- Proctology Practices:Specialist outpatient facilities concentrate in German urban clusters, sourcing mid-tier electromechanical platforms with essential positioning memory.
Surgical centers command the steepest expansion trajectory; hospitals retain the largest installed base requiring replacement ahead of MDR certificate deadlines.
Technology:
Digital integration capabilities now function as primary selection criteria in tenders specifying operating room information system compatibility.
- Electromechanical:Motor-driven positioning with encoder feedback dominates premium procurement in German university hospitals and Turkish metropolitan surgical centers.
- Digital:Native connectivity to OR workflow systems commands placement preference in Italian hospital procurement, with position data logging supporting quality audit requirements.
- Pneumatic:Compressed-air leg support abduction penetrates mid-tier clinic installations where electromechanical service networks remain sparse.
- Mechanical:Purely physical adjustment mechanisms persist in manual table production for price-driven markets in Central Asia.
Electromechanical systems anchor current revenue concentration; digital platforms are climbing the fastest as connectivity specifications harden in procurement documents.
Application:
Procedure complexity and reimbursement levels determine table specification requirements across diagnostic versus interventional clinical settings.
- Minimally Invasive Surgery:Precision positioning stability supports trocar placement and endoscopic navigation in German and Italian high-volume centers.
- Therapeutic Treatments:Hemorrhoid banding and fistula procedures require sustained Trendelenburg positioning with integrated perineal access in Turkish surgical infrastructure.
- Diagnostic Procedures:Anoscopy and sigmoidoscopy examination tables prioritize rapid height adjustment for physician ergonomics in busy proctology practices.
- Patient Examination:Routine consultation tables emphasize cost minimization and basic abduction capability in Eastern European clinic deployments.
Minimally invasive surgery applications carry the highest specification requirements; therapeutic treatments represent the fastest-expanding procedure category driving table replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MDR compliance timelines anchor procurement dynamics across European surgical infrastructure, with notified body scrutiny intensifying replacement cycles ahead of 2027 certificate deadlines. Hospital systems in Germany, Italy, and Turkey concentrate demand for powered positioning platforms, while Eastern European clinics sustain manual table procurement.
Germany
Ambulatory surgical center expansion in Bavaria and North Rhine-Westphalia drives premium electromechanical table procurement with programmable memory positioning. KBA-equivalent medical device surveillance mandates accelerated electrical safety documentation for powered systems. The Stuttgart surgical cluster concentrates engineering-intensive fabrication serving university hospital networks.
Italy
Regional health authorities in Lombardy and Emilia-Romagna unbundle equipment capital cost from multi-year preventive maintenance contracts. CE marking under EU MDR now requires position feedback API documentation for OR information system integration. The Milan-Bologna corridor anchors procurement committee decision-making for integrated perioperative suites.
Turkey
Ministry of Health import registration requirements pull toward domestic electromechanical assembly localization. Same-day procedure volume in Istanbul and Ankara metropolitan surgical centers prioritizes turnover efficiency over capital expenditure. The Ankara medical device manufacturing zone attracts regional headquarters establishment for MENA market access.
Poland
Regional hospital networks in Masovia and Silesia operate mixed fleets of manual and powered tables requiring spare parts standardization. ISO 13485 quality management certification functions as baseline tender eligibility for public procurement. The Warsaw-Wrocław distribution corridor strains inventory planning across legacy hydraulic inventory integration.
Bulgaria
Clinic-tier buyers in Sofia and Plovdiv favor pneumatic-assisted positioning where electromechanical service networks remain sparse. REACH restrictions on hydraulic oil formulations force reformulation cycles delaying product recertification. The Plovdiv medical equipment distribution hub concentrates cost-engineered manual table procurement for Balkan clinic networks.
Proctologic Table Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with German engineering heritage commanding premium placement in hospital system tenders. The competitive landscape fragments across electromechanical, pneumatic, and hydraulic technology vectors rather than consolidating around scale. Three archetypes dominate: integrated electromechanical platform builders, pneumatic positioning specialists, and cost-engineered manual fabricators. Capacity expansion into Turkish domestic production and technology licensing for digital workflow integration represent the dominant competitive moves reshaping positioning.
Among German GmbH-structured fabricators, SCHMITZ u. Söhne and AGA Sanitätsartikel GmbH occupy positions within the premium-tier electromechanical and pneumatic specialist vectors respectively. Bıçakcılar Medical Devices exemplifies the cost-engineered archetype serving clinic-tier procurement across Eastern European and Central Asian markets. These three anchors represent distinct strategic postures: engineering-intensive platform building, deep specialization in compressed-air positioning mechanisms, and aggressive cost optimization for infrastructure-constrained environments.
| Leading Market Players |
|---|
| AR-EL MEDICAL PRODUCTS |
| Promotal |
| Bıçakcılar Medical Devices |
| ECHOMED INDUSTRIAL |
| SCHMITZ u. Söhne |
| RQL |
| Wardray Premise |
| AGA Sanitätsartikel GmbH |
| PROJESAN |
| Others |
Value Network & Pricing Analysis
Multi-year preventive maintenance contracts lock in supply access and price visibility for powered table manufacturers serving German university hospital networks, while spot procurement dominates manual table transactions in Bulgarian and Romanian clinic markets where capital constraints override predictability preferences.
Pricing Analysis
Price spreads between German metropolitan surgical centers and Bulgarian regional clinics exceed two-to-one for comparable electromechanical platforms. Three-tier pricing structure across premium, standard, and economy levels segments by CE marking tier and after-sales bundling intensity. Cost compression in manual variants is intensifying because REACH hydraulic oil reformulation cycles force repeated recertification investments. Clinic buyers in Eastern Europe demonstrate highest price sensitivity; ambulatory surgical centers in Turkey and Germany show lowest sensitivity where turnover efficiency justifies capital expenditure.
Supply Chain Analysis
Strategic stockpiling of precision-machined aluminum frames and electromechanical drive components characterizes German fabricator inventory management ahead of EU MDR certificate renewal deadlines, while just-in-time preferences dominate pneumatic component sourcing for mid-tier clinic suppliers. Manufacturing concentrates in Germany, Turkey, and Italy. Electromechanical tables draw from precision-machined alloys, motor drive systems, and encoder feedback modules. Single-source vulnerability concentrates in German electromechanical component suppliers. Distribution runs through hospital procurement committees in Western Europe and medical equipment distributors in Eastern Europe and Central Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proctologic table procurement is shifting toward platform-economics logic where native connectivity to operating room information systems functions as the interoperability layer determining vendor lock-in, with Italian regional health authority tenders now mandating position feedback APIs as baseline eligibility.
For Market Incumbents: Compound service network density in Turkey and Poland to preempt emerging entrant field-service advantages. Backward integration into electromechanical drive component production defends margin position against steel and aluminum input volatility. Accelerate MDR certificate holdings to capture tender preference in French and Dutch public hospital systems where compliance documentation scores determine placement.
For New Entrants and Emerging Players: Differentiate on digital workflow integration capabilities targeting Italian hospital procurement committees with unbundled service contract frameworks. White-space penetration concentrates in certified pre-owned powered table refurbishment channels across Poland and Romania. Go-to-market leverage rests on biomedical technician training partnerships with regional distributors.
For Investors and Strategic Acquirers: Pneumatic positioning specialists with established clinic-tier distribution in Eastern Europe represent the most defensible acquisition archetype. Long-term viability hinges on MDR compliance infrastructure and digital platform development capacity. Watch Turkish domestic production incentive utilization rates as inflection indicator for regional manufacturing gravity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Early MDR certificate completion captures tender eligibility in German and Italian public hospital systems. |
| Hospital System Partnership | Multi-year preventive maintenance contracts with Bavarian surgical clusters lock in recurring revenue streams. |
| Software Companion Development | Position feedback API integration with Italian OR information systems commands procurement preference. |
| Backward Integration into Drive Components | In-house electromechanical motor production buffers margin compression from European metal price volatility. |
| Geographic Manufacturing Footprint | Turkish domestic assembly localization satisfies Ministry of Health import registration requirements for MENA access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineers, GPO contracts managers, and proctology practice administrators. Secondary validation drew from EU MDR notified body filings, hospital procurement databases, ISO 13485 certification registries, and customs trade records. Bottom-up installation base modeling and top-down surgical procedure volume estimates were triangulated to anchor market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user facility tier, positioning technology, and application complexity. CAGRs were derived from procedure volume trajectories and replacement cycle compression patterns. Forecast inputs incorporated EU MDR compliance timeline acceleration and ambulatory surgical center expansion rates in Germany and Turkey.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity or accelerated Turkish domestic production incentive utilization would require recalibration. Forecasts reflect assumptions around surgical infrastructure investment continuity and electromechanical service network scalability. Practitioners should keep alternative scenarios live as REACH hydraulic oil restriction scope and notified body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Global Blood Purification Equipment Market