
 Defibrillator Analyzers Market | 2026-2036
Defibrillator Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Defibrillator Analyzers Market Outlook
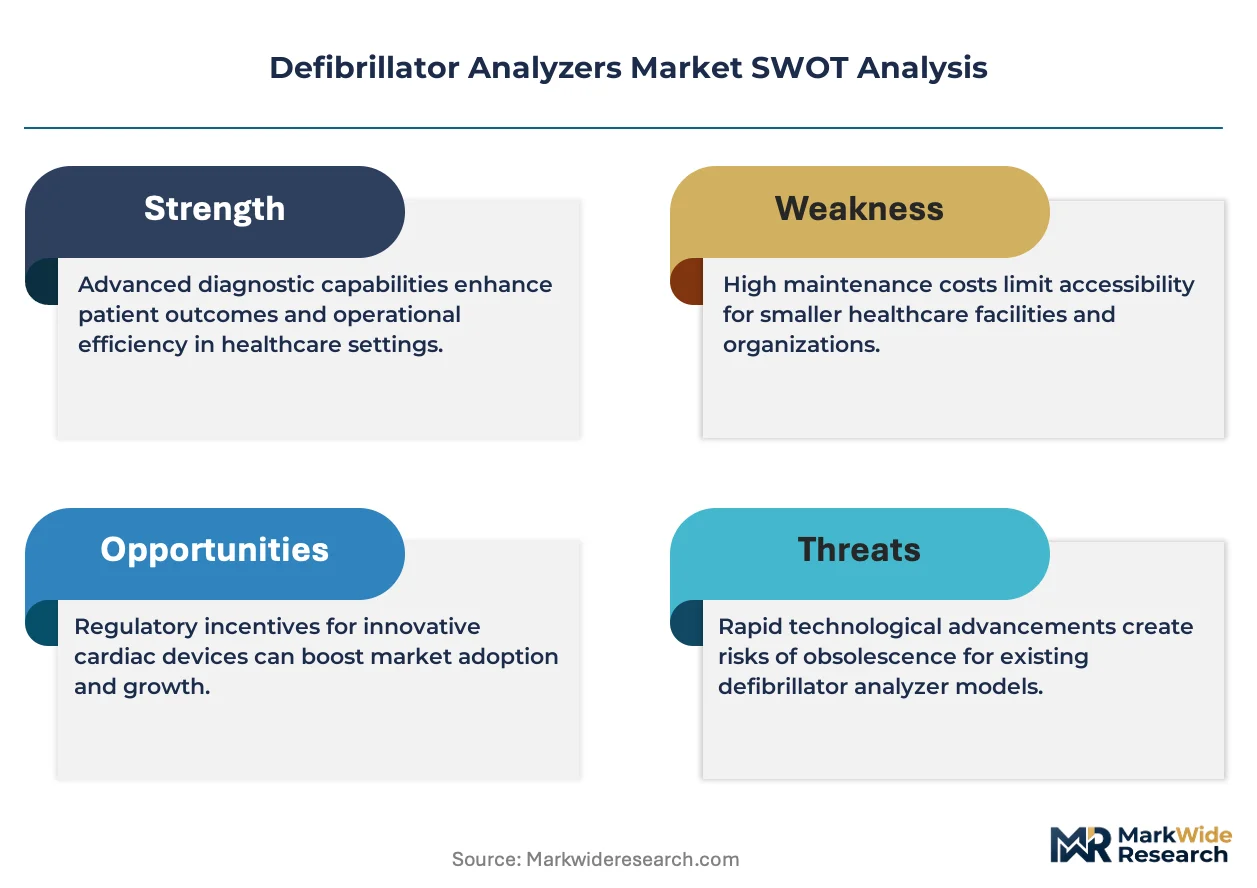
The gap between premium automated analyzers and commodity manual units is rebalancing as hospitals consolidate vendor relationships around software-integrated testing platforms. Fluke leverages its calibration heritage to anchor the high-reliability segment across North American hospital networks. Datrend Systems competes through specialized simulation testing modules that dominate Canadian and US emergency medical services procurement. BC Group International sustains its position via deep product specialization in wall-mounted analyzer configurations for clinical training environments.
A defibrillator analyzer is an electromechanical test instrument that verifies the energy delivery waveform, charge time, and synchronized cardioversion output of automated external defibrillators and manual units, typically measuring biphasic truncated exponential or rectilinear biphasic waveforms with joule accuracy within plus or minus one percent. Its primary commercial purpose is to ensure compliance with IEC 60601-2-4 and AAMI DF80 standards while reducing device failure risk in clinical settings. Portable analyzers lead unit shipments due to field service mobility requirements, yet automated analyzers capture disproportionate margin pools through recurring software validation contracts. Software-integrated testing represents the fastest-expanding technology dimension as hospitals seek centralized fleet management dashboards.
The FDA enforces 21 CFR Part 820 quality system requirements for defibrillator analyzer manufacturers, while IEC 60601-2-4 and AAMI DF80 establish the electrical safety and performance benchmarks that drive analyzer specification sheets. Health Canada and the EU MDR framework add parallel conformity pressures that shape product roadmaps for multi-jurisdiction vendors. Stakeholders must monitor evolving harmonization gaps between FDA predicate device pathways and EU MDR technical documentation requirements when allocating R&D and regulatory affairs resources.
Market Dynamics
Software-integrated testing platforms are consolidating hospital purchasing decisions around single-vendor fleets, compressing procurement cycles for standalone manual analyzers while elevating recurring revenue pools for automated systems with centralized dashboard capabilities.
Growth Catalysts
- IEC 60601-2-4 waveform validation mandates:Electrical safety testing protocols now require documented energy delivery verification for every defibrillator in clinical service, forcing systematic analyzer deployment across hospital networks.
- Preventive maintenance program expansion:Emergency medical services are formalizing fleet testing schedules to reduce device failure risk during field deployment, creating sustained demand for portable analyzer units.
- Aging installed base replacement:Defibrillator fleets exceeding ten years of service life in the United States, Germany, and Japan require compatible testing equipment for legacy waveform architectures.
Market Restraints
- Capital equipment budget constraints:Automated analyzers with software validation contracts demand upfront investment that smaller rural hospitals cannot prioritize against direct patient care equipment.
- Specialized technician scarcity:Biphasic waveform calibration expertise concentrates among field service engineers trained on Fluke and Datrend platforms, limiting deployment velocity.
- Manual analyzer substitution threat:Low-cost handheld units without software integration satisfy minimum compliance requirements for low-volume clinical settings, pressuring premium pricing tiers.
Strategic Opportunities
- Clinical training environment specialization:Wall-mounted analyzer configurations for simulation labs remain underpenetrated relative to acute care saturation, offering product differentiation paths.
- Cloud-based fleet management convergence:Integration of analyzer data with hospital asset management systems enables predictive maintenance scheduling and remote compliance documentation.
- EU MDR technical documentation harmonization:Vendors aligning analyzer validation protocols with European Medical Device Regulation requirements gain streamlined multi-jurisdiction market access.
Industry Challenges
- Legacy system integration complexity:Automated analyzers must interface with heterogeneous hospital IT infrastructures spanning multiple electronic health record platforms and network security protocols.
- Calibration certification timeline compression:FDA 21 CFR Part 820 quality system documentation requirements extend product validation cycles, delaying revenue recognition for new analyzer releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defibrillator Analyzers Market |
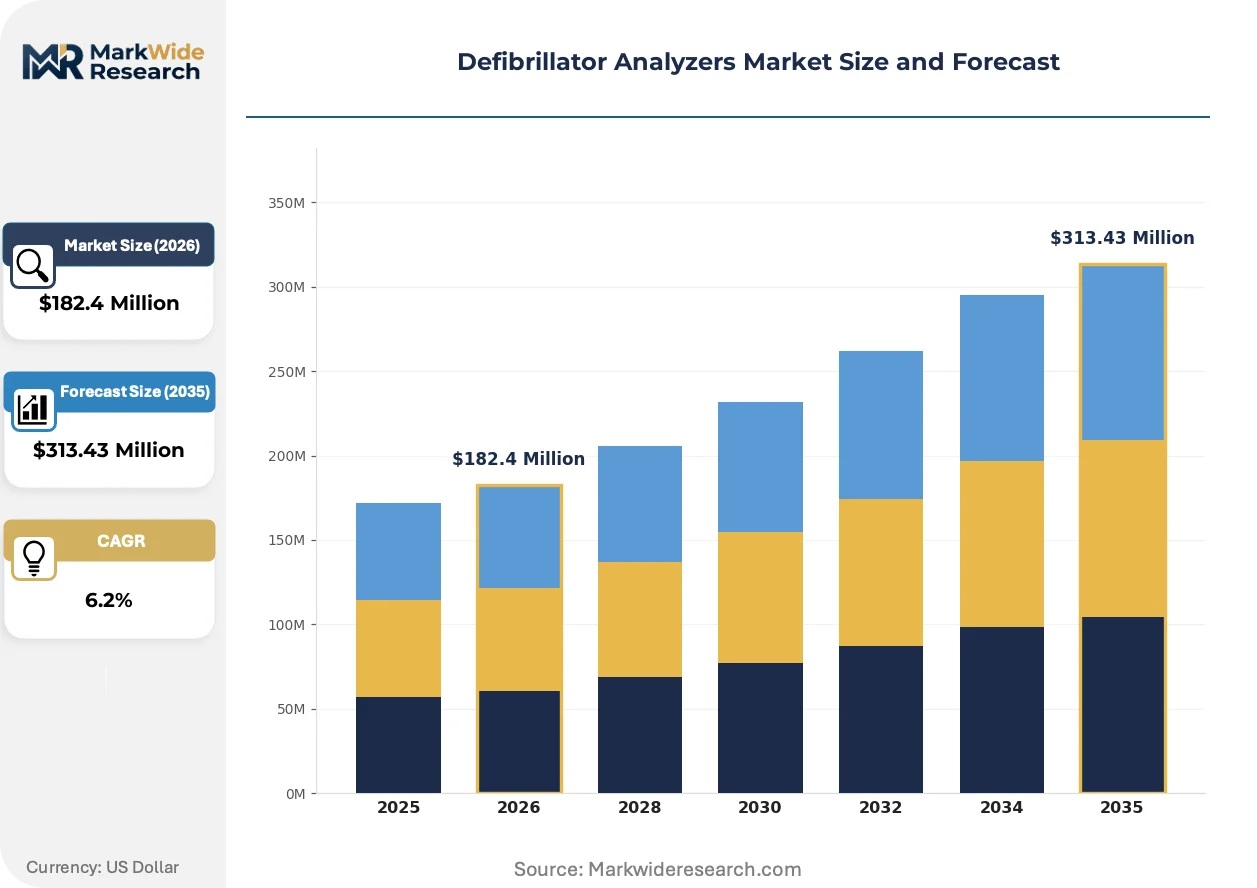
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $313.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Wall-Mounted Analyzers, Handheld Analyzers, Automated Analyzers Technology: Manual Testing, Automated Testing, Software-Integrated Testing, Simulation Testing End User: Hospitals, Clinics, Emergency Medical Services, Training Centers Service Type: Calibration Services, Maintenance Services, Repair Services, Training Services |
| Companies Covered | Fluke, Datrend Systems, BC Group International, Netech, GMC Instruments, Seaward Electronic Ltd, Helix India, METRAWATT International, Rigel Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defibrillator Analyzers Market Strategic Shifts
Waveform analysis algorithms and connectivity architectures are converging to transform defibrillator testing from isolated compliance checks into integrated clinical asset management workflows.
Artificial intelligence-enhanced waveform pattern recognition is electrifying diagnostic capabilities in next-generation analyzer platforms. Hospital biomedical engineering departments are piloting machine learning modules that predict defibrillator capacitor degradation before energy delivery failure. This predictive capability is compressing preventive maintenance intervals from calendar-based schedules to condition-based interventions.
EU MDR Article 10 post-market surveillance requirements are mandating traceable analyzer validation records across the device lifecycle. German hospital networks are deploying blockchain-anchored test certificates to satisfy notified body audit demands. Wall-mounted training analyzers in simulation centers face the steepest documentation burden under these technical file expansion rules.
Biomedical engineering departments are unbundling analyzer procurement from defibrillator original equipment manufacturer service contracts. Third-party testing platform vendors are capturing maintenance budgets previously captive to device makers through independent software validation subscriptions. This purchasing autonomy is most pronounced in United States academic medical centers with centralized clinical engineering operations.
Defibrillator Analyzers Market Segmentation
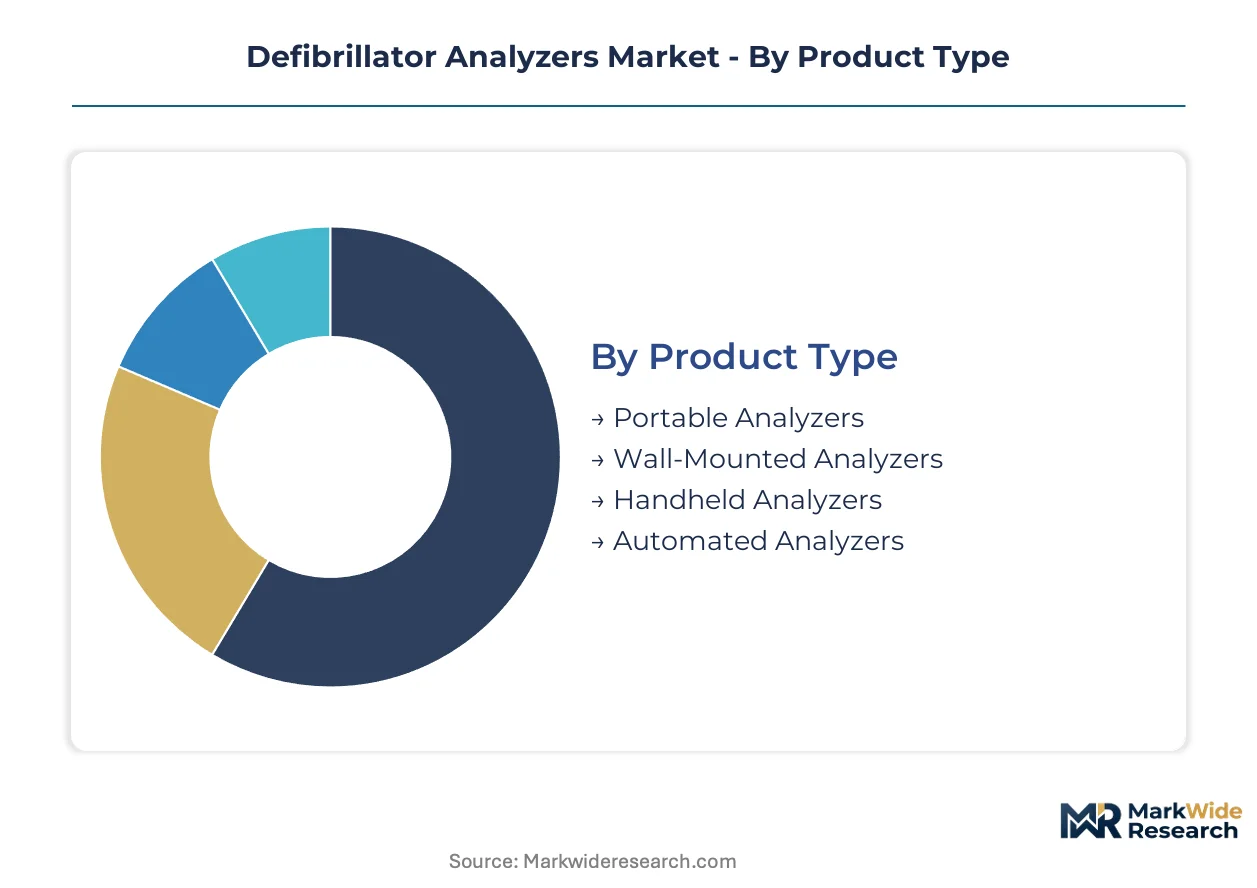
Defibrillator analyzer procurement splits sharply between capital-intensive automated platforms and lower-cost portable units. Segmentation reveals how hospitals consolidate spending around software-integrated systems while emergency services prioritize field mobility over dashboard connectivity.
Product Type:
Capital intensity varies dramatically across form factors, with automated analyzers demanding the highest upfront investment for software licensing and network infrastructure.
- Portable Analyzers:Battery-powered units with biphasic waveform measurement capability serve field service engineers across hospital networks. EMS fleets in the United States and Germany standardize on these for roadside defibrillator verification.
- Automated Analyzers:Rack-mounted systems with centralized fleet management dashboards anchor preventive maintenance programs in large hospital systems. Recurring software validation contracts generate sustained revenue streams for vendors.
- Wall-Mounted Analyzers:Fixed installations dominate clinical simulation labs and training centers.
- Handheld Analyzers:Compact units satisfy minimum compliance for low-volume clinical settings.
Most installed capacity flows through portable analyzers. Expansion is steepest in automated analyzers.
Technology:
Technology selection tracks customer sophistication, with software-integrated testing commanding premium pricing against manual alternatives.
- Software-Integrated Testing:Cloud-connected platforms synchronize analyzer data with hospital asset management systems. Academic medical centers in the United States deploy these for predictive maintenance scheduling and remote compliance documentation.
- Automated Testing:Pre-programmed test sequences reduce technician intervention time while ensuring IEC 60601-2-4 waveform validation consistency across large device fleets.
- Simulation Testing:Specialized modules replicate cardiac arrhythmia scenarios for defibrillator performance verification.
- Manual Testing:Technician-directed measurement protocols persist in budget-constrained rural hospitals.
Software-integrated testing is gaining share fastest. Manual testing retains the largest installed base.
End User:
End-user segmentation reflects divergent compliance pressures and fleet scale economics across care settings.
- Hospitals:Multi-campus health systems deploy analyzer fleets exceeding fifty units with centralized biomedical engineering oversight. FDA 21 CFR Part 820 documentation requirements drive automated platform adoption.
- Emergency Medical Services:Mobile fleets require ruggedized portable analyzers for field deployment. Preventive maintenance program formalization is accelerating unit procurement across municipal and private ambulance operators.
- Clinics:Outpatient facilities prioritize handheld units for periodic verification of single or dual defibrillator installations.
- Training Centers:Simulation labs demand wall-mounted analyzers with extended waveform libraries for educational scenarios.
Hospitals absorb the majority of analyzer spending. Training centers are expanding most quickly.
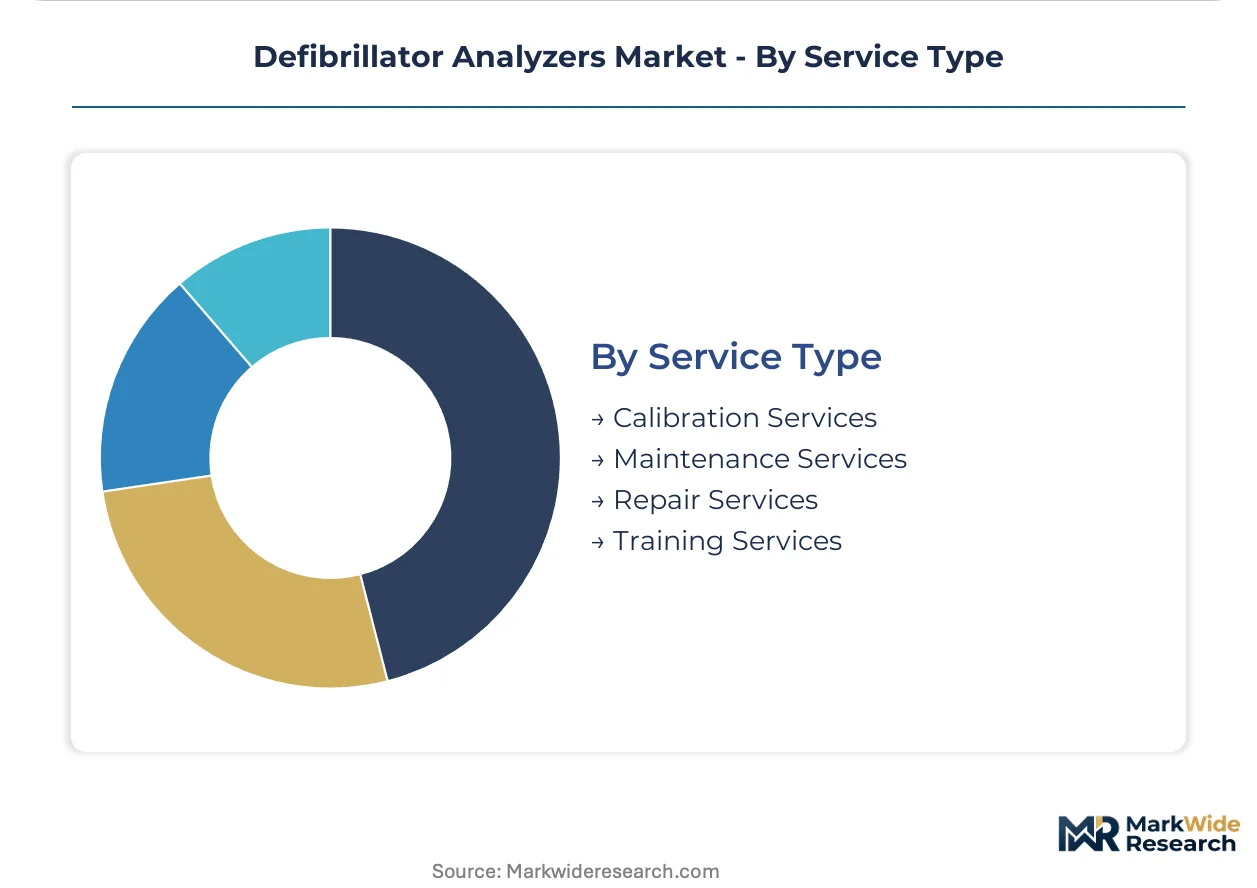
Service Type:
Service segmentation reveals shifting vendor economics as hospitals unbundle testing from OEM maintenance contracts.
- Calibration Services:NIST-traceable energy delivery verification ensures joule accuracy within plus or minus one percent. Third-party providers are capturing budgets previously captive to defibrillator manufacturers.
- Maintenance Services:Scheduled preventive programs reduce capacitor degradation failure risk. EMS operators are formalizing these contracts to meet fleet availability targets.
- Repair Services:Component-level refurbishment extends analyzer service life in capital-constrained settings.
- Training Services:Technician certification programs address scarcity of biphasic waveform calibration expertise.
Calibration services represent the largest revenue pool. Training services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys automated analyzer fleets at triple the per-capita density of Japan, yet German hospital networks currently outpace both in blockchain-anchored compliance documentation adoption.
United States
FDA 21 CFR Part 820 quality system enforcement drives multi-campus health systems toward centralized preventive maintenance programs. Academic medical centers in Boston and the Research Triangle unbundle analyzer procurement from defibrillator OEM service contracts. The Southeast corridor from Atlanta to Florida concentrates EMS fleet standardization efforts around portable unit deployment.
Germany
EU MDR Article 10 post-market surveillance mandates push university hospitals toward automated platforms with traceable validation records. Notified body audit requirements in Baden-Württemberg and Bavaria accelerate blockchain-anchored test certificate adoption. The Rhine-Ruhr metropolitan cluster anchors third-party calibration service expansion.
Japan
PMDA electrical safety protocols and aging defibrillator installed bases exceeding fifteen years force systematic analyzer deployment. Tokyo and Osaka metropolitan hospitals lead software-integrated testing adoption for predictive maintenance scheduling. The Chubu region around Nagoya concentrates biomedical engineering technician certification programs.
Canada
Health Canada conformity pressures parallel FDA requirements while emergency medical services formalize fleet testing schedules across provincial networks. Ontario and Quebec health authorities standardize on specialized simulation testing modules for paramedic training. Vancouver coastal health clusters pioneer cloud-based fleet management integration.
United Kingdom
MHRA alignment with EU MDR technical documentation requirements shapes analyzer validation protocol roadmaps for multi-jurisdiction vendors. London and Southeast England academic medical centers deploy wall-mounted analyzers in simulation labs at accelerating rates. The Midlands region concentrates third-party maintenance service provider expansion.
Defibrillator Analyzers Market Competitive Environment
Top-tier vendors anchor the high-reliability automated segment, while mid-tier specialists capture emergency medical services procurement through modular portability. The vendor base stratifies across three functional tiers: calibration heritage players, simulation testing specialists, and clinical training environment focused configurators. Consolidation pressure intensifies as hospital networks reduce approved vendor lists to single-source software-integrated platforms. Competitive moves concentrate on strategic partnerships for cloud connectivity architecture and geographic expansion into underpenetrated training center segments.
Within the calibration heritage tier, Fluke leverages its North American hospital network relationships to exemplify high-reliability positioning. Among specialized simulation testing providers, Datrend Systems occupies a position reflecting emergency medical services procurement dominance in Canadian and US municipal markets. BC Group International represents the clinical training environment specialization archetype, anchoring wall-mounted analyzer configuration demand in simulation labs. These three players collectively illustrate how product form factor specialization maps to distinct end-user procurement channels.
| Leading Market Players |
|---|
| Fluke |
| Datrend Systems |
| BC Group International |
| Netech |
| GMC Instruments |
| Seaward Electronic Ltd |
| Helix India |
| METRAWATT International |
| Rigel Medical |
| Others |
Value Chain & Pricing Dynamics
IEC 60601-2-4 compliance documentation mandates gate qualified supply access for defibrillator analyzer vendors while simultaneously stratifying pricing tiers across the hospital procurement landscape. Buyers lacking internal biomedical engineering certification programs face premium markups for analyzer platforms with embedded training modules and NIST-traceable calibration certificates.
Pricing Analysis
Capacity additions in automated testing platforms across United States academic medical centers are reshaping price floors for software-integrated analyzers. Three-tier pricing structure across premium automated, standard portable, and economy handheld levels separates hospital networks with centralized fleet management from rural clinics with minimal compliance requirements. Cost compression in the handheld tier intensifies because manual analyzer substitution threatens premium positioning. EMS operators demonstrate highest price sensitivity due to municipal budget cycles, while German university hospitals show least sensitivity given EU MDR Article 10 documentation burdens.
Supply Chain Analysis
FDA 21 CFR Part 820 quality system certification and IEC 60601-2-4 testing accreditation gate component sourcing for analyzer manufacturers. Final assembly concentrates in the United States, Germany, and Japan where precision electronics manufacturing infrastructure supports joule-accuracy calibration standards. Supply chains draw from specialized capacitor suppliers, medical-grade display manufacturers, and embedded software development houses. Single-source vulnerability in biphasic waveform simulation chipsets creates procurement risk during semiconductor allocation cycles. Distribution runs through biomedical engineering distributors and direct hospital system contracts rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital consolidation around single-vendor software platforms rewards incumbents with recurring validation contracts over transactional equipment sales. The demand-shift toward predictive maintenance specifications with AI-enhanced capacitor degradation monitoring justifies premium positioning.
For Market Incumbents: Deploy cloud-based fleet management integration as the primary defensive lever. Consolidate hospital network relationships through exclusive software validation subscriptions that lock out third-party calibration providers. Counter emerging entrant pressure from Asian electronics manufacturers by deepening backward integration into proprietary waveform simulation chipsets. Anchor capacity expansion in United States metropolitan clusters where academic medical center procurement autonomy is most pronounced. For New Entrants and Emerging Players: Launch via specialized simulation testing modules targeting underpenetrated clinical training environments in Canadian and United Kingdom health systems. Capture municipal EMS procurement in secondary United States markets where Datrend Systems maintains weaker distributor relationships. Exploit white-space in wall-mounted analyzer configurations for paramedic certification programs. Prioritize Health Canada conformity pathways to bypass entrenched FDA predicate device competition. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because hospital unbundling from OEM maintenance contracts creates fragmented third-party validation markets. Five-to-ten year viability hinges on software subscription renewal rates exceeding equipment replacement cycles. Target acquisition profiles emphasizing biomedical engineering technician training infrastructure and existing GPO contract relationships. Monitor blockchain-anchored test certificate adoption in German hospital networks as signal for documentation-heavy compliance market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Cloud-connected validation platforms synchronize with Epic and Cerner asset management systems. |
| CE Marking Pathway | EU MDR technical documentation alignment streamlines multi-jurisdiction market access for automated analyzers. |
| Hospital System Partnership | Exclusive fleet management contracts with United States academic medical centers lock out competing vendors. |
| Backward Integration | In-house production of biphasic waveform simulation modules reduces single-source semiconductor exposure. |
| Reimbursement Strategy | Predictive maintenance scheduling integration with CMS quality metrics justifies analyzer capital expenditure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and purchasing decision dynamics. Primary discussions with biomedical engineering directors, hospital purchasing committee members, EMS fleet managers, GPO contracts specialists, and defibrillator OEM service executives informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, Health Canada device licenses, EU MDR technical documentation databases, hospital procurement records, and GPO contract award notices. Bottom-up analyzer unit deployment estimates triangulated against top-down hospital capital expenditure benchmarks.
Segment-weighting approaches applied differential growth assumptions across product type, technology architecture, and end-user setting dimensions. Automated analyzer software subscription revenues received distinct modeling treatment from portable unit transactional sales. CAGRs derived from installed base replacement cycles, preventive maintenance program formalization rates, and regulatory documentation burden expansion. Forecast inputs incorporated IEC 60601-2-4 amendment timelines and FDA quality system enforcement intensity variations across the analysis window.
Several conditions sit outside the modeled scope, including defibrillator OEM vertical integration into captive analyzer manufacturing and breakthrough solid-state capacitor technologies eliminating degradation monitoring demand. Forecasts reflect documented assumptions about hospital network consolidation velocity and EMS municipal budget allocation priorities. A model refresh is warranted upon material change in FDA 21 CFR Part 820 enforcement posture or EU MDR notified body audit standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Electric Bed Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Medical Filter Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Global Medical Equipment Cooling Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Animal Operating Table Market