
 Global 3D Printed Surgical Models Market | 2026-2036
Global 3D Printed Surgical Models Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printed Surgical Models Market Foresight
The EU Medical Device Regulation is repositioning competitive priorities across the sector, compelling manufacturers to validate quality management systems for patient-specific devices. Materialise NV anchors its position through certified medical device production facilities in Belgium and the United States. Stratasys Ltd. differentiates via PolyJet multi-material systems capable of replicating tissue density gradients for cardiac simulations. 3D Systems, Inc. dominates orthopedic applications through its VSP surgical planning service integrated with SLA production workflows.
3D printed surgical models are patient-specific physical replicas fabricated from digital imaging data using additive manufacturing processes, typically achieving layer resolutions between 16 and 100 microns depending on the technology platform, and serve primarily to reduce operative time and improve surgical outcomes through tactile preoperative rehearsal. Anatomic models command the largest revenue share among product types due to their universal applicability across surgical disciplines, while surgical guides capture expanding margin pools as hospitals seek to standardize complex osteotomy and implant placement procedures. Hospitals represent the most concentrated end-user segment, though medical schools are emerging as a high-volume channel for educational replicas.
FDA clearance pathways for 510(k) exempt custom devices and the EU MDR's Class I custom-device framework collectively shape market access requirements and reimbursement eligibility across the two largest addressable markets. ISO 13485 certification and ASTM F2900 standards for file format interoperability further constrain supplier qualification, favoring established players with dedicated quality infrastructure. Stakeholders must monitor evolving FDA guidance on point-of-care manufacturing and the EU AI Act's potential application to automated segmentation algorithms that generate model geometries.
Market Dynamics
Patient-specific manufacturing workflows are compressing preoperative planning cycles across cardiovascular and orthopedic disciplines, forcing hospitals to restructure surgical scheduling around additive production lead times rather than traditional inventory procurement.
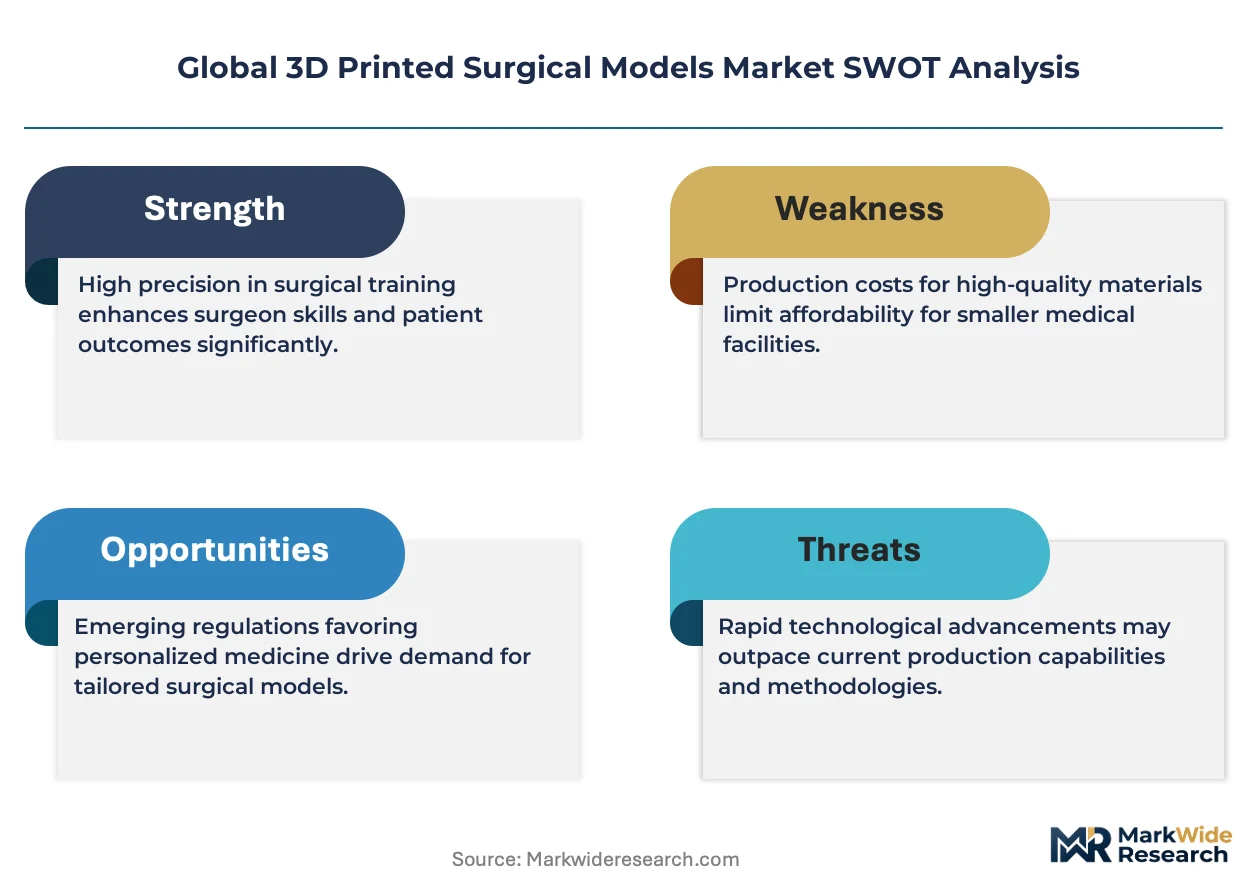
Growth Catalysts
- EU MDR Class I Custom-Device Framework:The European Union's streamlined classification pathway accelerates market entry for validated manufacturers, reducing regulatory friction for patient-specific anatomic replicas.
- Multi-Material Jetting Systems:PolyJet platforms capable of replicating tissue density gradients enable cardiac surgeons to rehearse valve replacement procedures with haptic fidelity previously unavailable in physical models.
- Japanese Reimbursement Maturation:Japan's Ministry of Health, Labour and Welfare expanded procedural codes covering personalized surgical planning, driving hospital procurement of anatomical replicas for complex oncology cases.
Market Restraints
- Biocompatible Photopolymer Cost Volatility:Medical-grade resins certified under ISO 10993 carry 3-5x premiums over industrial equivalents, compressing margins for high-volume model production.
- Belgian Production Concentration:A single certified facility cluster near Leuven handles disproportionate EU medical device output, creating geographic supply vulnerability for continental hospitals.
- Segmentation Algorithm Dependency:Automated DICOM-to-mesh conversion remains imperfect for vascular pathologies, requiring manual correction that extends production timelines.
Strategic Opportunities
- Indian Tertiary Hospital Expansion:Corporate hospital chains in Mumbai and Delhi are installing point-of-care manufacturing cells to bypass import logistics for emergency trauma reconstructions.
- AI Act Algorithm Validation:Early compliance with the European Union's artificial intelligence liability framework positions vendors for preferred supplier status as automated segmentation becomes regulated medical software.
- Medical School Channel Development:Anatomical education programs are replacing cadaveric specimens with reusable 3D printed alternatives, opening recurring revenue streams outside surgical applications.
Industry Challenges
- Biomedical Engineer Recruitment Bottlenecks:The intersection of radiological segmentation expertise and additive manufacturing operations remains sparsely staffed, constraining production scale-up at hospital-based facilities.
- ISO 13485 Certification Timelines:Quality management system validation for patient-specific device production averages 14-18 months, delaying market entry for new manufacturing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printed Surgical Models Market |
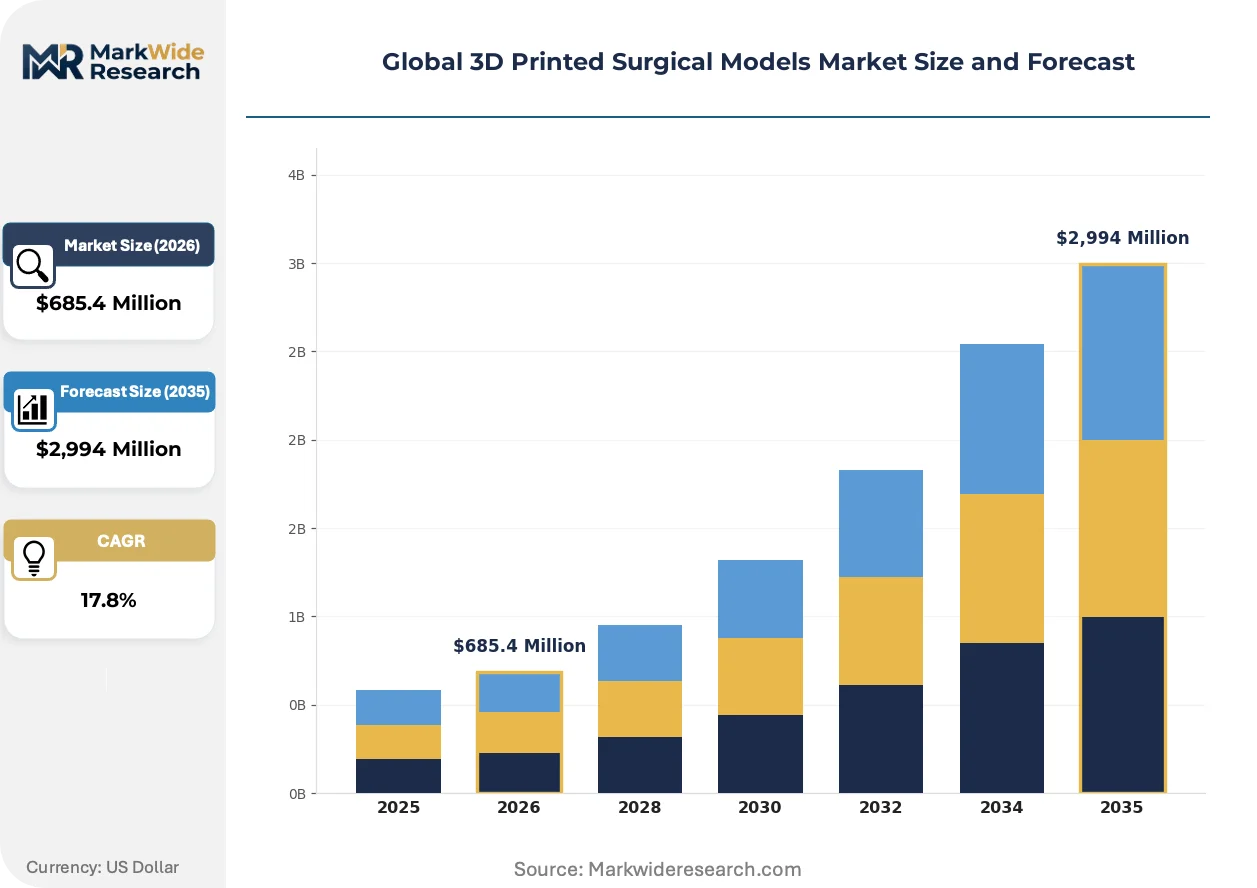
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,994 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anatomic Models, Surgical Guides, Educational Replicas, Custom Implants Technology: SLA, FDM, PolyJet, SLS, DLP Application: Preoperative Planning, Surgical Training, Patient Communication, Medical Education End User: Hospitals, Medical Schools, Research Centers, Specialized Clinics |
| Companies Covered | 3D Systems, Inc., Stratasys Ltd., Materialise NV, Axial3D, Formlabs, Lazarus 3D, LLC, Osteo3D, Anatomiz3D, SYNBONE AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printed Surgical Models Market Shifts & Advancements
Computational segmentation pipelines and regulatory clarity around point-of-care production are converging to relocate manufacturing authority from centralized vendors to hospital-based engineering departments.
Machine learning-based DICOM segmentation is automating the conversion of CT and MRI datasets into printable mesh geometries, reducing manual preprocessing from hours to minutes. Cardiovascular surgery departments at major academic medical centers are adopting these tools fastest, compressing the interval between imaging and physical model delivery from days to same-day turnaround.
The FDA's evolving guidance on point-of-care manufacturing is clarifying quality system obligations for hospital-based production facilities. Orthopedic surgery units are responding by establishing captive ISO 13485-certified cleanrooms, insulating their patient-specific guide production from third-party supply disruption.
Subscription-based model libraries are displacing per-unit procurement contracts in medical education channels. Anatomical teaching programs in Germany and the United States are licensing digital repositories that enable unlimited local printing of pathological variants, reducing dependence on physical inventory and freight logistics.
Global 3D Printed Surgical Models Market Segmentation
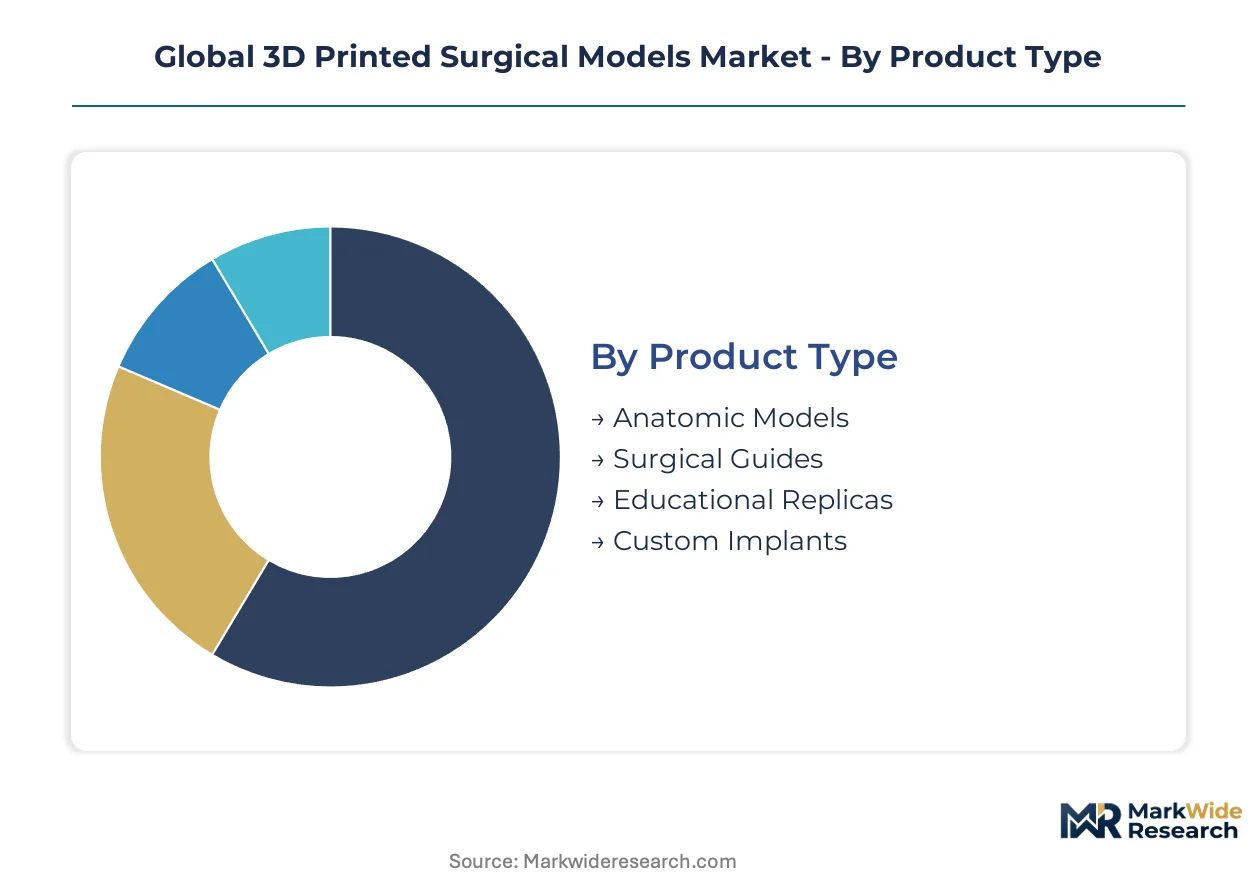
Segmentation in the 3D printed surgical models market determines regulatory pathway complexity and reimbursement eligibility. Certification requirements vary sharply by product intrusiveness and patient contact duration.
Product Type:
Anatomic models and surgical guides carry divergent certification burdens under FDA 510(k) exemptions and EU MDR Class I custom-device frameworks, with implantable categories triggering full premarket review cycles.
- Anatomic Models:Non-sterile physical replicas fabricated from patient DICOM data achieve layer resolutions between 16 and 100 microns. Demand concentrates in German and Japanese university hospitals where reimbursement for personalized surgical planning has matured, driven by cardiovascular and orthopedic procedure volumes.
- Surgical Guides:Patient-specific osteotomy and drilling templates require ISO 13485-certified production workflows and biocompatible material validation. US orthopedic surgery departments are standardizing these for total joint arthroplasty, compressing operative time and implant placement variability.
- Educational Replicas:Reusable anatomical teaching specimens replace cadaveric inventory in medical schools.
- Custom Implants:Patient-matched cranial plates and mandibular reconstructions trigger full regulatory review pathways.
Anatomic models sit at the top of the volume ranking, with surgical guides climbing the fastest.
Technology:
Technology selection dictates material compatibility, surface finish quality, and production throughput for specific clinical applications.
- SLA:Stereolithography dominates orthopedic model production through sub-25 micron layer resolution and established biocompatible resin portfolios. Belgian and US production facilities have validated ISO 13485 workflows for this platform, serving hospital networks requiring high-fidelity bone replicas.
- PolyJet:Multi-material jetting enables simultaneous deposition of rigid and flexible photopolymers to replicate tissue density gradients. Cardiac surgery departments at academic medical centers in Germany and Japan are adopting these systems fastest for valve replacement rehearsal.
- FDM:Fused deposition modeling offers lower-cost production for non-sterile educational applications.
- SLS:Selective laser sintering processes nylon and TPU powders for durable surgical guides.
- DLP:Digital light projection accelerates throughput for same-day model delivery in point-of-care configurations.
SLA maintains the highest installed base, while PolyJet systems are expanding most quickly in cardiovascular applications.
Application:
Application segmentation determines reimbursement coding eligibility and sales cycle length, with clinical applications commanding premium pricing over educational uses.
- Preoperative Planning:Tactile rehearsal of complex procedures using patient-specific replicas reduces operative time and complication rates. US and German hospitals are securing dedicated procedural reimbursement codes, converting capital equipment purchases into operational budget line items.
- Surgical Training:High-fidelity replicas enable repeated practice of rare pathological presentations without cadaveric specimen constraints. Japanese medical device manufacturers are subsidizing these programs to accelerate surgeon familiarity with novel implant systems.
- Patient Communication:Physical models improve informed consent comprehension for complex oncological resections.
- Medical Education:Subscription-based digital libraries enable unlimited local printing of pathological variants.
Preoperative planning commands the largest revenue share, with surgical training gaining share fastest as residency programs replace cadaveric curricula.
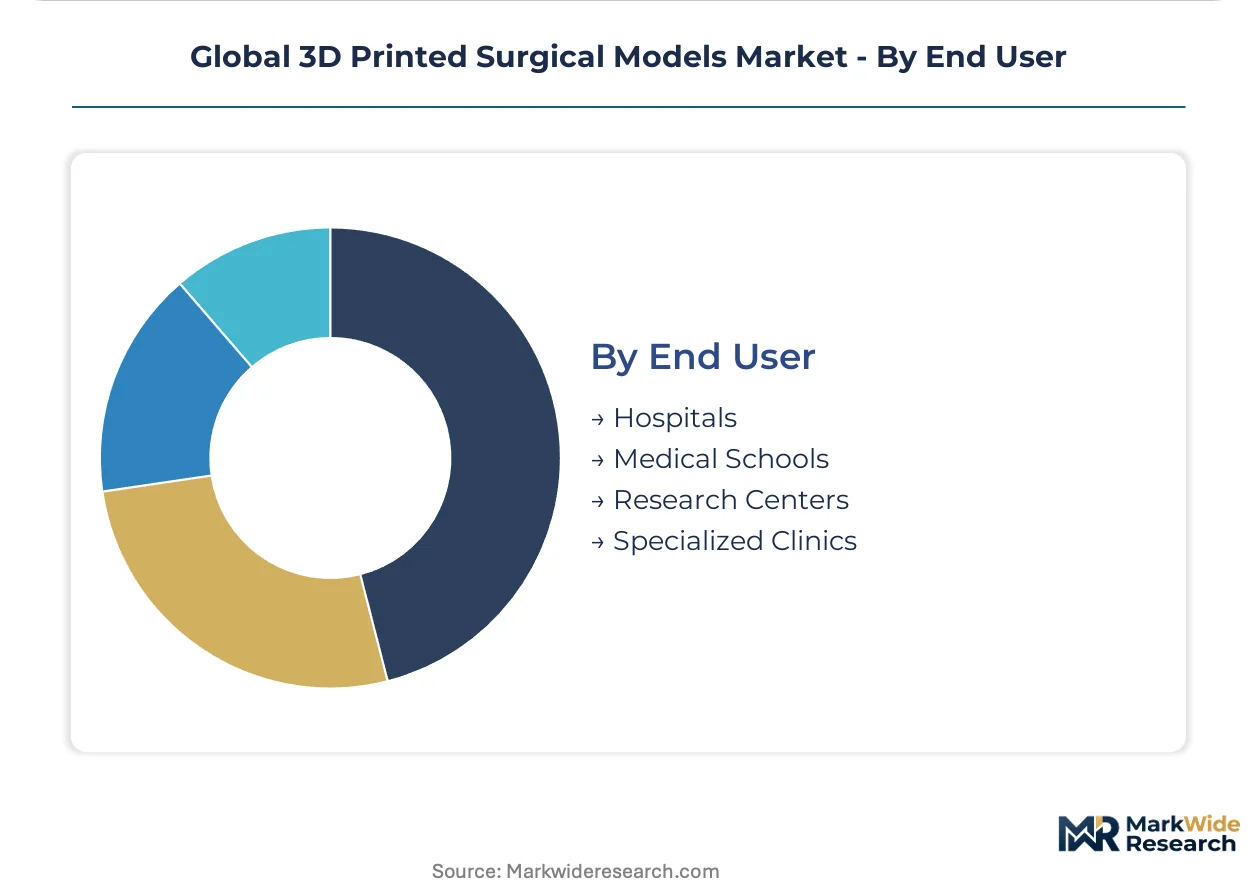
End User:
End-user concentration shapes distribution strategy, with hospital procurement cycles differing materially from academic institutional purchasing patterns.
- Hospitals:Tertiary and quaternary care facilities represent the most concentrated demand channel, with orthopedic and cardiovascular surgery departments driving procurement. US health systems are consolidating vendor relationships under enterprise agreements that bundle model production with surgical planning software.
- Medical Schools:Anatomical education programs in Germany and the United States are licensing digital repositories for unlimited local printing, creating recurring revenue streams outside surgical applications.
- Research Centers:Biomechanical validation studies and device development programs require standardized phantom production.
- Specialized Clinics:Ambulatory surgery centers are adopting point-of-care manufacturing for orthognathic and podiatric procedures.
Hospitals dominate absolute spending, with medical schools representing the steepest expansion trajectory as cadaver costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian biomedical engineers anchor European production capacity for patient-specific devices, while US health systems and Japanese academic medical centers drive procurement volumes through maturing reimbursement frameworks.
United States
FDA 510(k) exemption pathways for custom devices accelerate hospital adoption of point-of-care manufacturing. The agency's evolving guidance on quality system obligations clarifies regulatory boundaries for captive production facilities. Orthopedic surgery departments in the Greater Boston and Midwest corridors are establishing ISO 13485-certified cleanrooms to insulate guide production from supply disruption.
Germany
University hospitals in Bavaria and Baden-Württemberg secure dedicated procedural reimbursement codes for personalized surgical planning. The EU MDR Class I custom-device framework reduces regulatory friction for validated manufacturers. The Leuven-adjacent production cluster handles disproportionate continental output, though German facilities are expanding to diversify geographic supply.
Japan
METI and PMDA reimbursement expansion drives hospital procurement for complex oncology cases. The Ministry of Health, Labour and Welfare's procedural code maturation converts capital equipment into operational budget line items. Cardiac surgery departments in the Kanto and Kansai regions adopt multi-material systems fastest for valve replacement rehearsal.
India
Corporate hospital chains in Mumbai and Delhi install point-of-care cells to bypass import logistics for emergency trauma reconstructions. CDSCO's medical device rules shape quality expectations for local production. Tertiary facilities in Maharashtra and Karnataka are recruiting biomedical engineers to bridge radiological segmentation and additive manufacturing operations.
Belgium
Materialise NV's certified medical device production facilities anchor EU output for patient-specific replicas. The national regulator's alignment with EU MDR quality requirements positions Belgian manufacturers for streamlined continental market access. The Leuven technology cluster concentrates disproportionate biomedical engineering talent and validated ISO 13485 workflows.
Global 3D Printed Surgical Models Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the 3D printed surgical models sector. The vendor base stratifies between established platform manufacturers with certified quality infrastructure and emerging point-of-care specialists. Three archetypes dominate: integrated hardware-software platforms, pure-play segmentation service providers, and hospital-embedded engineering departments. Competitive intensity centers on M&A for regulatory capabilities and capacity expansion into ISO 13485-certified cleanrooms.
Among platform specialists, 3D Systems, Inc., Stratasys Ltd., and Materialise NV exemplify contrasting geographic and technological positioning. The Delaware-incorporated entity anchors orthopedic applications through validated production workflows. The Israeli limited company differentiates via multi-material systems capable of tissue density replication. The Belgian naamloze vennootschap secures European market access through certified medical device facilities in Leuven and the United States.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Stratasys Ltd. |
| Materialise NV |
| Axial3D |
| Formlabs |
| Lazarus 3D, LLC |
| Osteo3D |
| Anatomiz3D |
| SYNBONE AG |
| Others |
Supply & Pricing Matrix
Captive production in hospital-based ISO 13485 cleanrooms anchors supply security and pricing power for US orthopedic surgery departments, insulating patient-specific guide manufacturing from third-party margin extraction while compressing per-unit costs through volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biocompatible resins from industrial-grade alternatives and educational replicas. Price differentiation hinges on ISO 10993 certification grade and geographic delivery cost from Belgian or US production hubs. Cost compression in economy-tier educational models is intensifying because medical schools are licensing unlimited digital repositories. Hospital procurement committees demonstrate highest price sensitivity for high-volume anatomic replicas, while cardiovascular surgery departments show lowest sensitivity for multi-material cardiac simulations.
Supply Chain Analysis
Domestic-content mandates under India's CDSCO medical device rules are reshaping sourcing patterns for corporate hospital chains in Mumbai and Delhi, driving local recruitment of biomedical engineers and point-of-care cell installation. Supply concentrates in Belgium, the United States, and Japan for certified production. Raw material dependencies center on medical-grade photopolymers, biocompatible nylon powders, and DICOM segmentation software licenses. Single-source vulnerability persists around the Leuven-adjacent facility cluster handling disproportionate EU output. Distribution runs through enterprise agreements bundling model production with surgical planning software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market has shifted into late-cycle quality dominance as hospital procurement committees prioritize ISO 13485-certified workflows over uncertified alternatives, elevating premium specifications across all product tiers.
For Market Incumbents: Acquire point-of-care manufacturing capabilities in Indian tertiary hospital chains to preempt domestic-content requirements under CDSCO rules. Expand ISO 13485-certified cleanroom capacity in Germany to diversify supply beyond the Leuven cluster. Biomedical engineer recruitment bottlenecks threaten production scale-up at hospital-based facilities.
For New Entrants and Emerging Players: Launch via subscription-based digital model libraries targeting German and US medical schools replacing cadaveric curricula. White-space concentration sits in Indian emergency trauma reconstruction and Japanese cardiac surgery training programs. Partner with academic medical centers for automated segmentation algorithm validation ahead of EU AI Act enforcement.
For Investors and Strategic Acquirers: Roll-up economics work for segmentation-software specialists because automated DICOM-to-mesh conversion is becoming regulated medical software under EU AI Act liability frameworks. Five-to-ten-year viability favors platform-agnostic service providers with validated quality infrastructure. Monitor FDA guidance evolution on point-of-care manufacturing quality obligations as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Validates quality management systems for patient-specific device production under EU MDR and FDA pathways. |
| Hospital System Partnership | Enterprise agreements bundling model production with surgical planning software consolidate procurement relationships. |
| Multi-Material Platform Deployment | PolyJet systems enable cardiac surgeons to rehearse valve replacement with tissue-density haptic fidelity. |
| Point-of-Care Manufacturing Cell Installation | Bypasses import logistics for emergency trauma reconstructions in Indian corporate hospital chains. |
| Reimbursement Strategy Development | Secures dedicated procedural codes converting capital equipment into operational budget line items in Japan. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at platform manufacturers with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up facility-level capacity estimates and top-down regional spending patterns were triangulated for convergence.
Historical reference periods anchored the projection horizon through verified installed base data and procedural volume trends. Segmentation dimensions modeled include product type, technology platform, application use case, end-user category, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and technology diffusion S-curves. Forecast inputs incorporated ISO 13485 certification timelines and reimbursement code maturation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement timing and FDA point-of-care guidance finalization. Forecasts reflect documented assumptions regarding biocompatible resin cost trajectories and biomedical engineer labor supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Vision Aids Market
Medical Devices
Global Ventilators Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Prescription Lens Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
US Surgical Microscopes Market