
 Personalized LASIK Surgery Market | 2026-2036
Personalized LASIK Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized LASIK Surgery Market Outlook
Equipment leasing and pay-per-procedure financing is reshaping competitive entry in personalized LASIK, allowing mid-tier surgical centers to deploy femtosecond laser platforms without capital-intensive purchases. Carl Zeiss Meditec AG leverages its integrated diagnostic-to-surgical workflow to sustain premium positioning across academic medical centers. Alcon Inc. competes through its broad consumables and device portfolio, while SCHWIND eye-tech-solutions GmbH specializes in excimer laser refinement for complex corneal topography cases.
Personalized LASIK surgery employs patient-specific corneal mapping data to guide laser ablation patterns, typically achieving sub-micron precision in tissue removal through femtosecond and excimer laser systems designed to correct refractive errors beyond standard spherical and cylindrical parameters. Wavefront-guided procedures command margin pools due to their superior higher-order aberration correction, while bladeless platforms are expanding fastest as patient preference shifts toward all-laser approaches. Software-driven systems increasingly determine procedural differentiation as algorithms integrate topography, tomography, and wavefront data into unified treatment planning.
FDA premarket notification requirements for excimer laser systems and femtosecond laser platforms govern device commercialization in the United States, while the EU Medical Device Regulation imposes clinical evidence standards through notified body conformity assessments. Japan's PMDA oversees ophthalmic laser approvals under its pharmaceutical and medical device framework, creating layered compliance obligations for multi-region vendors. Stakeholders must monitor evolving software validation requirements as artificial intelligence components enter treatment planning systems.
Market Dynamics
Bladeless femtosecond laser platforms are consolidating procedural workflows across refractive surgical centers, compressing equipment replacement cycles and reshaping vendor financing structures throughout the ophthalmology device supply chain.
Growth Catalysts
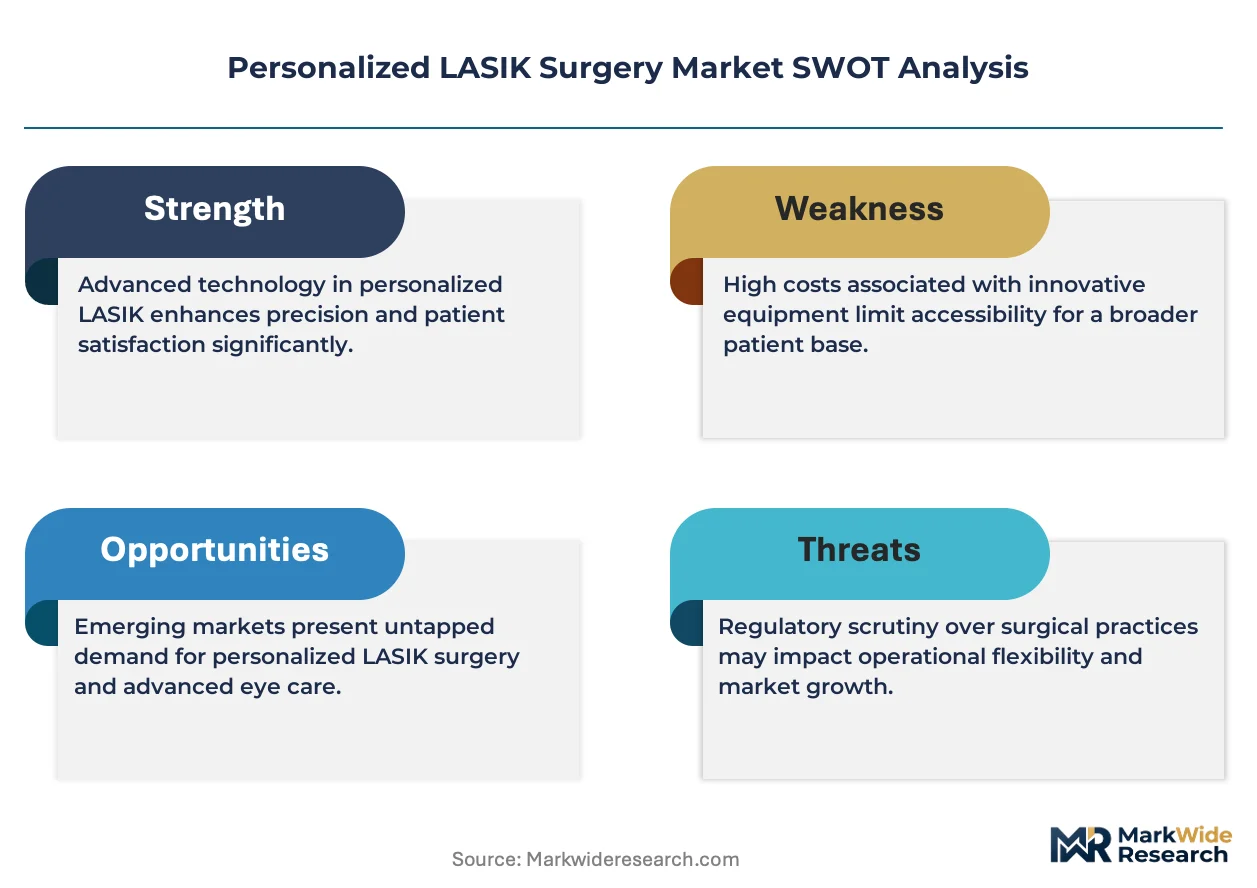
- Wavefront-guided ablation protocols:FDA streamlined 510(k) clearance pathways for topography-integrated systems accelerate commercialization timelines for advanced diagnostic-to-surgical platforms.
- Germany's dense ophthalmology infrastructure:Academic medical centers in Heidelberg and Berlin drive premium procedure uptake through integrated refractive surgery training programs.
- Japan's aging demographic profile:PMDA reimbursement frameworks for presbyopia-correcting interventions expand addressable patient pools beyond traditional myopia corrections.
Market Restraints
- Excimer laser consumable costs:Single-use patient interface components and proprietary gas mixtures create recurring cost burdens that constrain mid-tier center margins.
- US supply concentration:FDA-registered femtosecond laser manufacturers cluster in California and Massachusetts, creating geographic vulnerability to regional logistics disruptions.
- Technical limitation in keratoconus screening:Current tomography algorithms generate false-positive referrals that inflate pre-operative evaluation costs without improving surgical outcomes.
Strategic Opportunities
- India's underpenetrated tier-2 cities:Equipment leasing models enable refractive centers in Pune and Hyderabad to deploy femtosecond platforms without capital-intensive purchases.
- EU AI Act compliance frameworks:Early alignment with algorithmic transparency requirements for treatment planning software creates regulatory moats against later entrants.
- Telemedicine-integrated pre-screening:Remote corneal topography review protocols expand patient funnel efficiency for high-volume surgical chains.
Industry Challenges
- Femtosecond laser engineer scarcity:Specialized service technicians command premium compensation that elevates total cost of ownership for installed equipment bases.
- ISO 13485 certification timelines:Quality management system audits for software-as-medical-device modules extend product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized LASIK Surgery Market |
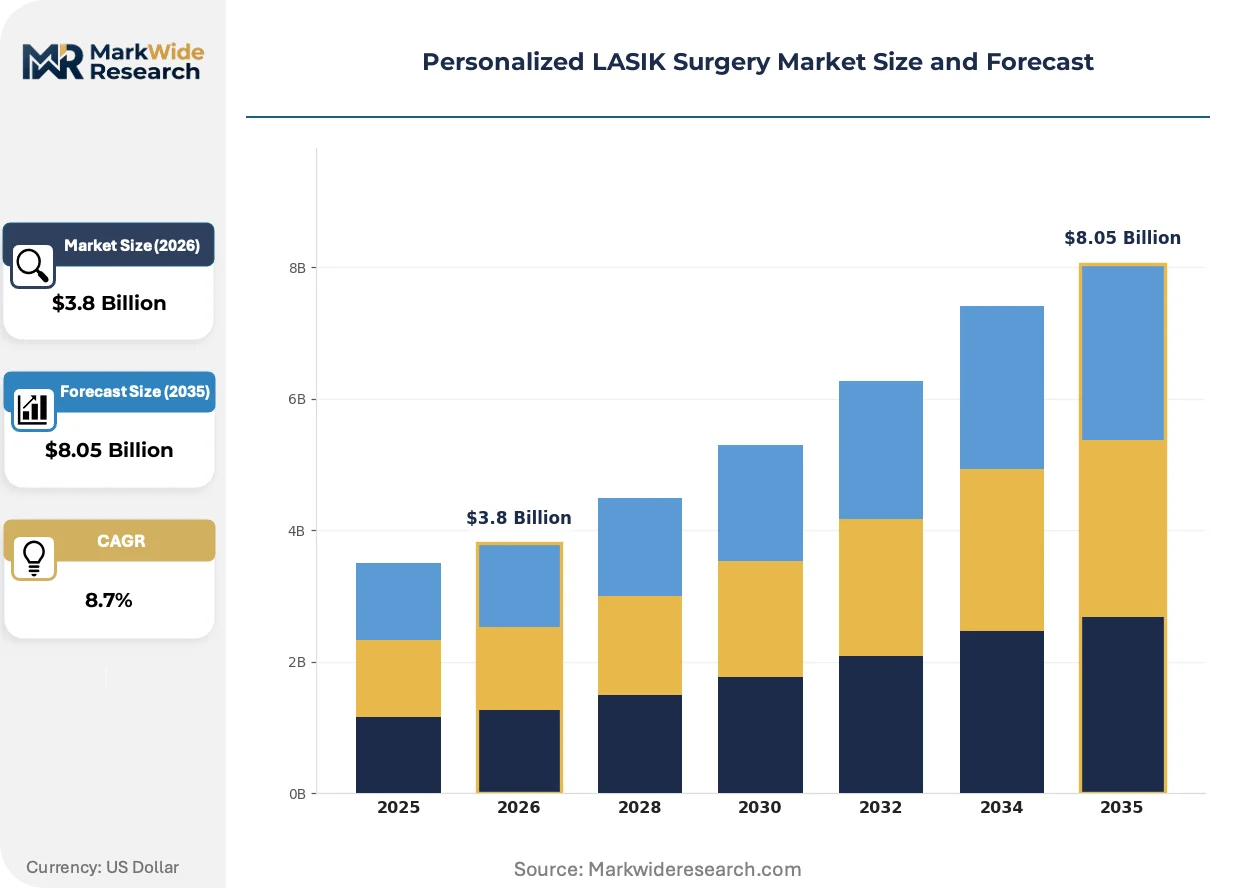
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Wavefront-Guided, Custom Wavefront, Bladeless, Traditional Technology: Femtosecond Laser, Excimer Laser, Energy-Based Techniques, Software-Driven Systems Patient Type: Candidates with Astigmatism, Myopia, Hyperopia, Presbyopia End User: Eye Clinics, Hospitals, Surgical Centers, Private Practices |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Alcon Inc., SCHWIND eye-tech-solutions GmbH, Ziemer Ophthalmic Systems AG, Johnson & Johnson Vision Care Inc., NIDEK Co. Ltd., STAAR Surgical Company, Bausch + Lomb Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized LASIK Surgery Market Strategic Shifts
Artificial intelligence components are entering corneal treatment planning systems, compressing the gap between diagnostic data acquisition and laser ablation execution while raising new validation requirements for software-as-medical-device classifications.
Topography-guided ablation algorithms integrate Scheimpflug tomography with wavefront aberrometry to address complex corneal irregularities beyond standard refractive errors. Academic medical centers in the United States and Germany adopt these systems for post-LASIK enhancement procedures and keratoconus-stage corrections. Conventional wavefront-only platforms are rendering obsolete for patients with significant higher-order aberrations or prior refractive surgery histories.
The EU Medical Device Regulation imposes clinical evidence standards through notified body conformity assessments for excimer laser systems with integrated AI planning modules. Manufacturers must demonstrate algorithmic traceability and performance consistency across diverse corneal phenotypes. Germany's notified bodies lead enforcement interpretation, creating compliance templates that other EU member states reference.
Patients increasingly demand all-laser bladeless procedures after direct-to-consumer education campaigns from refractive surgery chains. This preference shift compresses conversion rates for microkeratome-dependent practices and elevates equipment financing urgency among independent ophthalmologists. Japan's cosmetic surgery clinics report the strongest bladeless preference intensity, with patient willingness-to-pay premiums exceeding other Asia-Pacific markets.
Personalized LASIK Surgery Market Segmentation
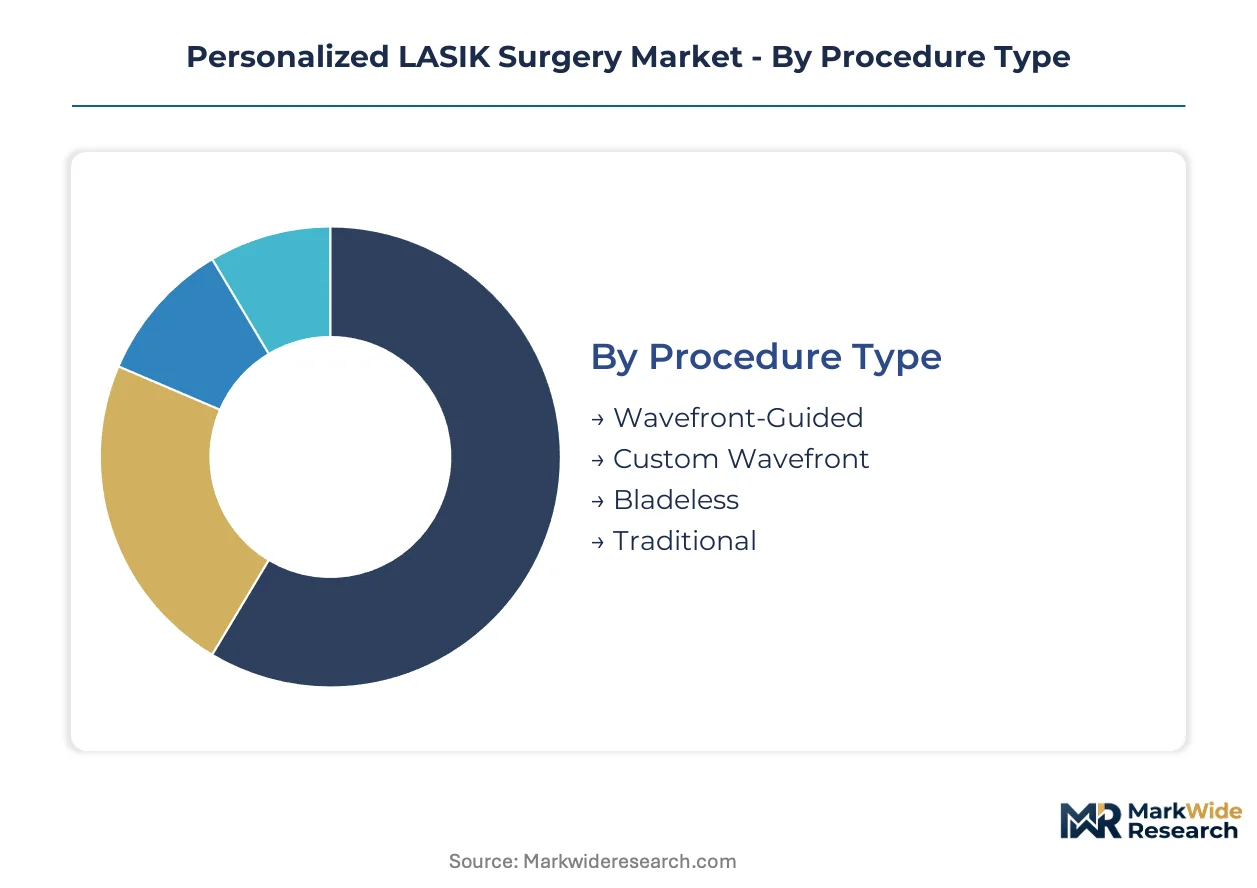
Segmentation in personalized LASIK surgery reveals how reimbursement patterns, equipment financing structures, and clinical training pathways concentrate demand across distinct procedure and technology categories. Understanding these divisions clarifies where capital deployment yields highest returns and where regulatory pathways create competitive moats.
Procedure Type:
After-sales service intensity varies sharply across procedure categories, with bladeless platforms requiring specialized femtosecond laser technicians while wavefront-guided systems demand ongoing software calibration support.
- Wavefront-Guided:Corneal ablation protocols integrate aberrometry data to correct higher-order optical imperfections beyond spherical and cylindrical errors. Demand concentrates in Germany's academic medical centers where integrated diagnostic-to-surgical workflows justify premium positioning through superior visual acuity outcomes.
- Custom Wavefront:Patient-specific treatment algorithms incorporate individualized wavefront maps with proprietary ablation zone calculations. United States refractive surgery chains in California and Massachusetts deploy these systems to differentiate against commoditized LASIK offerings through measurable contrast sensitivity improvements.
- Bladeless:All-laser approaches using femtosecond platforms for flap creation command elevated patient willingness-to-pay across Japan's cosmetic surgery clinics.
- Traditional:Microkeratome-dependent procedures retain cost-sensitive volume in India's tier-2 cities where equipment leasing penetration remains limited.
By volume, Traditional procedures lead. By growth pace, Bladeless platforms are expanding most quickly.
Technology:
Technology cost tiers stratify procurement decisions, with femtosecond platforms representing capital-intensive infrastructure while software modules enable incremental capability upgrades.
- Femtosecond Laser:Ultrafast infrared pulse systems create precise corneal flaps through photodisruption without mechanical blade contact. United States FDA-registered manufacturers cluster in California and Massachusetts, creating geographic concentration in equipment supply chains that elevates vulnerability to regional logistics disruptions.
- Excimer Laser:Ultraviolet ablation systems remove corneal tissue with sub-micron precision through controlled photoablative decomposition. Germany's Heidelberg and Berlin academic centers drive premium uptake through integrated refractive surgery training programs that standardize excimer platform protocols.
- Energy-Based Techniques:Alternative thermal and mechanical approaches address specific corneal pathologies outside standard LASIK parameters.
- Software-Driven Systems:Algorithmic treatment planning modules integrate topography, tomography, and wavefront data into unified ablation patterns.
By installed base, Excimer Laser systems dominate. By capability expansion, Software-Driven Systems are climbing the fastest.
Patient Type:
Application patterns differ across refractive error categories, with myopia corrections representing high-volume standard procedures while presbyopia interventions command premium pricing through multi-focal ablation complexity.
- Candidates with Astigmatism:Toric ablation protocols address corneal asymmetry through customized cylindrical correction algorithms. Japan's PMDA reimbursement frameworks increasingly cover astigmatism-integrated presbyopia corrections, expanding addressable pools beyond traditional single-error interventions.
- Candidates with Myopia:Standard spherical corrections constitute the foundational volume base across all geographies, with highest throughput in high-volume surgical chains.
- Candidates with Hyperopia:Farsightedness corrections require deeper stromal ablation patterns that elevate enhancement rates and post-operative monitoring intensity.
- Candidates with Presbyopia:Age-related near-vision loss interventions utilize multi-focal or monovision ablation strategies with complex pre-operative screening protocols.
By procedure volume, Myopia corrections lead. By pricing power, Presbyopia interventions are gaining share fastest.
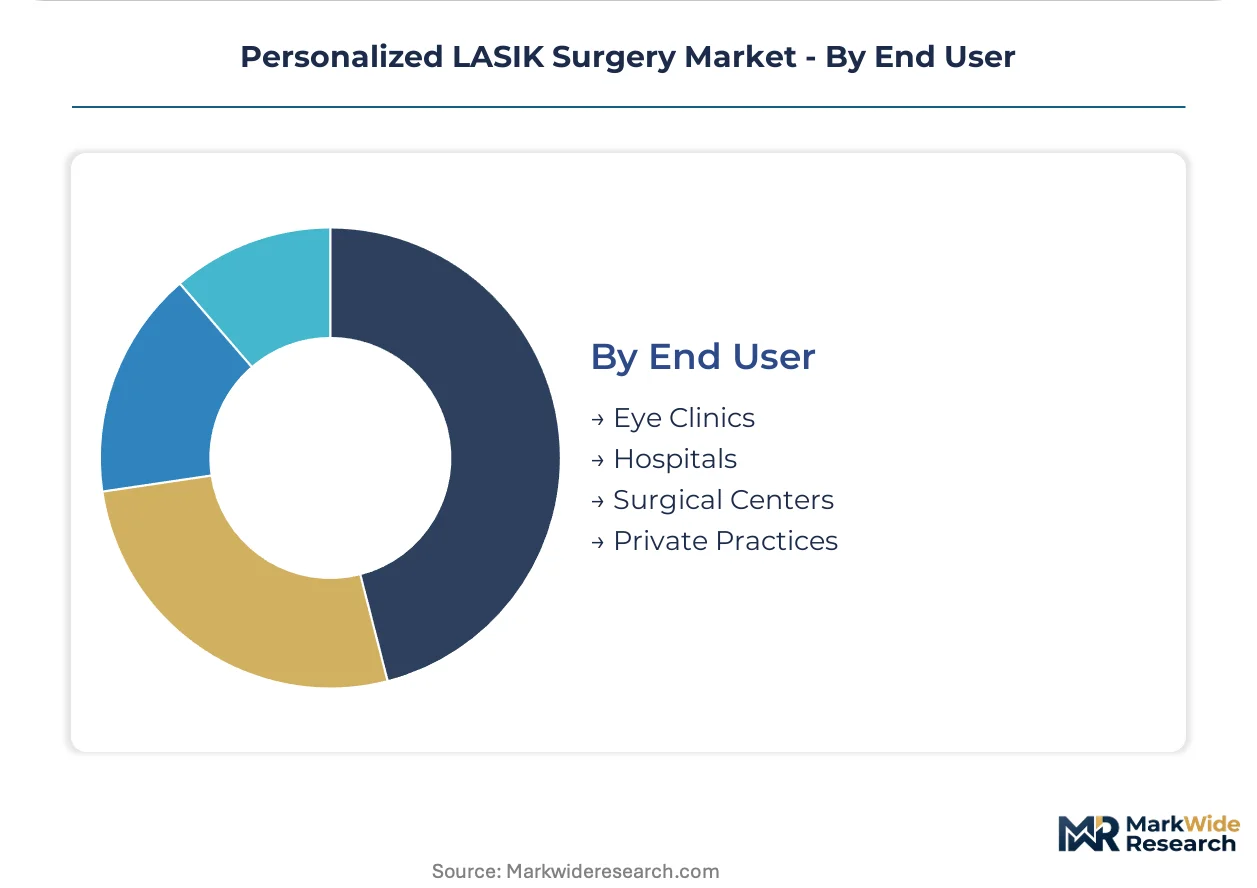
End User:
Customer type determines procurement authority structures, with hospital systems leveraging centralized capital budgets while private practices respond to equipment financing availability and pay-per-procedure arrangements.
- Eye Clinics:Specialized refractive facilities concentrate high-volume LASIK throughput with dedicated diagnostic suites and streamlined patient workflows. India's underpenetrated tier-2 cities in Pune and Hyderabad enable equipment leasing models that deploy femtosecond platforms without capital-intensive purchases.
- Hospitals:Integrated health systems cross-subsidize refractive services through ophthalmology department revenues and academic research funding. Germany's dense ophthalmology infrastructure supports premium procedure uptake through university-affiliated medical centers in Heidelberg and Berlin.
- Surgical Centers:Ambulatory facilities optimize throughput efficiency with dedicated laser suites and standardized pre-operative protocols.
- Private Practices:Independent ophthalmologists face equipment financing urgency as patient preference shifts toward all-laser bladeless approaches.
By facility count, Private Practices lead. By technology upgrade velocity, Surgical Centers are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment flows concentrate where ophthalmology infrastructure supports premium procedure uptake, with the United States and Germany running structural trade surpluses in femtosecond laser platforms while Japan and India rely on imported systems.
United States
FDA streamlined 510(k) clearance pathways accelerate commercialization timelines for wavefront-guided diagnostic-to-surgical platforms. California and Massachusetts host the densest clusters of femtosecond laser manufacturers, creating geographic concentration in equipment supply chains. Academic medical centers in Boston and Stanford drive premium procedure adoption through integrated refractive surgery training programs.
Germany
Heidelberg and Berlin academic centers sustain premium uptake through university-affiliated medical centers with standardized excimer platform protocols. The EU Medical Device Regulation imposes clinical evidence standards through notified body conformity assessments for excimer laser systems. Baden-Württemberg's precision optics heritage supports diagnostic-to-surgical workflow integration across Carl Zeiss Meditec's manufacturing base.
Japan
PMDA reimbursement frameworks for presbyopia-correcting interventions expand addressable patient pools beyond traditional myopia corrections. Tokyo and Osaka cosmetic surgery clinics report the strongest bladeless preference intensity, with patient willingness-to-pay premiums exceeding other Asia-Pacific markets. METI industrial policy supports domestic ophthalmic device R&D through targeted funding mechanisms.
India
Equipment leasing models enable refractive centers in Pune and Hyderabad to deploy femtosecond platforms without capital-intensive purchases. CDSCO medical device regulations govern import licensing for excimer and femtosecond laser systems. Maharashtra and Telangana concentrate private ophthalmology infrastructure, with tier-2 cities representing underpenetrated expansion corridors.
Personalized LASIK Surgery Market Competitive Environment
On the supply side, the industry is consolidated around integrated diagnostic-to-surgical workflow providers and specialized excimer laser refiners. Three archetypes dominate: diversified ophthalmology conglomerates with broad consumables portfolios, precision optics specialists leveraging vertical integration from diagnostic imaging to laser ablation, and focused excimer technology vendors serving complex corneal topography cases. Competitive moves center on equipment leasing structures and pay-per-procedure financing arrangements that lower barriers for mid-tier surgical centers.
Among German precision optics specialists, Carl Zeiss Meditec AG and SCHWIND eye-tech-solutions GmbH exemplify contrasting strategic positions. Carl Zeiss Meditec AG anchors the integrated workflow archetype, while SCHWIND eye-tech-solutions GmbH occupies the specialized excimer refinement tier. Alcon Inc. represents the diversified ophthalmology conglomerate model with broad device and consumables exposure.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Alcon Inc. |
| SCHWIND eye-tech-solutions GmbH |
| Ziemer Ophthalmic Systems AG |
| Johnson & Johnson Vision Care Inc. |
| NIDEK Co. Ltd. |
| STAAR Surgical Company |
| Bausch + Lomb Incorporated |
| Others |
Value Chain & Pricing Dynamics
Pacific Rim container freight corridors from Shanghai to Los Angeles and Yokohama to Hamburg transmit cost volatility through femtosecond laser supply chains, concentrating pricing power with California and Massachusetts manufacturers while forcing tiered equipment financing structures that separate premium bladeless platforms from standard excimer configurations across mid-tier surgical centers.
Pricing Analysis
High-volume refractive surgery chains anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) clearance tier and bundled after-sales service intensity, with wavefront-guided systems commanding premiums against commoditized microkeratome procedures. Cost compression in economy tiers intensifies as Indian tier-2 centers negotiate equipment leases. Private practices in Japan show least price sensitivity, absorbing bladeless premiums willingly.
Supply Chain Analysis
Export-control restrictions on ultrafast laser optics limit component flows from Germany and Switzerland into United States assembly operations. Supply concentrates in California, Massachusetts, and Baden-Württemberg, drawing from specialized gas mixtures, precision motion stages, and infrared optical substrates. Single-source vulnerability in femtosecond oscillator crystals creates chokepoint exposure. Distribution runs through authorized dealer networks with captive service technician pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personalized LASIK surgery is approaching a platform-economics inflection where diagnostic-to-surgical workflow interoperability determines vendor lock-in, with Carl Zeiss Meditec's integrated ecosystem creating switching costs that reshape competitive dynamics across academic medical centers.
For Market Incumbents: Pre-empt software-as-medical-device displacement by embedding AI treatment planning modules directly into diagnostic hardware, closing the gap between topography acquisition and ablation execution. Fortify against SCHWIND's specialized excimer refinement by captive supply of femtosecond service technician training pipelines, creating personnel scarcity moats.
For New Entrants and Emerging Players: India's underpenetrated tier-2 cities in Pune and Hyderabad offer white-space expansion through equipment leasing partnerships that bypass capital barriers for independent ophthalmologists. Target telemedicine-integrated pre-screening protocols as the go-to-market angle, capturing patient funnel efficiency before surgical commitment.
For Investors and Strategic Acquirers: Focused excimer laser refiners with proprietary topography-guided algorithms represent the highest-conviction acquisition archetype, given their irreplaceable position in post-LASIK enhancement and keratoconus-stage corrections. Monitor FDA software validation requirement expansions as the inflection signal that elevates regulatory moat value for pre-compliant vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Treatment Planning Module Development | FDA software validation alignment creates regulatory barriers against later entrants in wavefront-guided systems. |
| Equipment Leasing Program Expansion | Pay-per-procedure financing unlocks mid-tier surgical center adoption in India's underpenetrated tier-2 corridors. |
| Femtosecond Service Technician Academy | Captive training pipelines address engineer scarcity that elevates total cost of ownership for installed bases. |
| EU MDR Conformity Assessment Acceleration | Early notified body engagement in Germany creates compliance templates referenced across member states. |
| Telemedicine Pre-Screening Integration | Remote corneal topography review expands patient funnel efficiency for high-volume refractive surgery chains. |
Study Parameters
Operator-level perspectives from refractive surgeons, biomedical engineers at femtosecond laser manufacturers, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base. Primary interview insights combined with FDA 510(k) filings, PMDA approval databases, EU MDR notified body assessments, and customs import records for ophthalmic laser systems. Bottom-up procedure volume estimates from surgical center utilization data triangulated against top-down equipment shipment tracking.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling procedure type, technology platform, patient refractive error category, and end-user facility type as core segmentation dimensions. CAGRs derived from equipment replacement cycle compression, reimbursement pathway expansions, and patient preference shift velocities. Forecast inputs incorporated PMDA presbyopia coverage decisions and EU AI Act compliance timeline uncertainties.
Practitioners should monitor FDA software validation requirement expansions and PMDA reimbursement framework revisions for early signals of forecast deviation. Forecasts reflect assumptions about femtosecond platform adoption curves and wavefront-guided premium retention. Material shifts in EU MDR enforcement interpretation or export-control restrictions on ultrafast laser optics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Global Artificial Tear Market