
 Penile Implants Market | 2026-2036
Penile Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Penile Implants Market Intelligence
A capital-intensity divergence between established manufacturers and newer entrants is rotating competitive dynamics toward in-house silicone fabrication and precision molding capabilities. Boston Scientific Corporation leverages vertical integration across its supply chain to sustain margin resilience. Coloplast Corp anchors its position through specialized urology channel control in European markets. Zephyr Surgical Implants competes by focusing on customizable device architectures for complex anatomical presentations.
Penile implants are surgically inserted prosthetic devices designed to restore erectile function through either fluid-filled inflatable cylinders or bendable malleable rods, typically constructed from medical-grade silicone elastomers with titanium-reinforced mechanical components. Their primary commercial purpose is to provide a durable, patient-controlled solution for severe erectile dysfunction refractory to pharmacological therapy. The inflatable product category leads volume due to superior patient satisfaction metrics and concealed flaccid-state functionality, while malleable systems retain share in cost-sensitive procurement environments. Titanium material selection commands premium positioning owing to biocompatibility and fatigue resistance, whereas silicone formulations dominate across both product architectures.
The FDA governs penile implants through Class III premarket approval pathways requiring extensive clinical safety and efficacy documentation. ISO 10993 biocompatibility testing standards and EU MDR conformity assessment procedures shape international market access timelines and technical file requirements. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies and adapt clinical evidence generation strategies accordingly.
Market Dynamics
Patient-controlled fluid dynamics in inflatable penile prostheses are displacing malleable rod architectures as the default clinical standard, forcing manufacturers to reallocate R&D toward multi-component pump-reservoir systems and away from single-piece silicone rod fabrication.
Growth Catalysts
- FDA Class III PMA Pathway Clarity:Streamlined premarket approval documentation for biocompatibility-tested silicone elastomers accelerates product clearance timelines for established manufacturers with ISO 13485 quality management systems.
- Japan's Super-Aged Society:METI-supported reimbursement frameworks for severe erectile dysfunction interventions expand procedural access for men aged 75 and above in tertiary hospital settings.
- Titanium-Reinforced Mechanical Components:Fatigue-resistant alloy selection in pump and cylinder construction extends device longevity and reduces revision surgery rates in high-volume implant centers.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Three specialty chemical suppliers in Germany and the United States control 80 percent of implant-grade elastomer feedstock, exposing manufacturers to input cost volatility and allocation risk.
- EU MDR Technical File Burden:Expanded clinical evidence requirements for Class III implantable devices extend conformity assessment timelines by 18-24 months for new market entrants lacking predicate device histories.
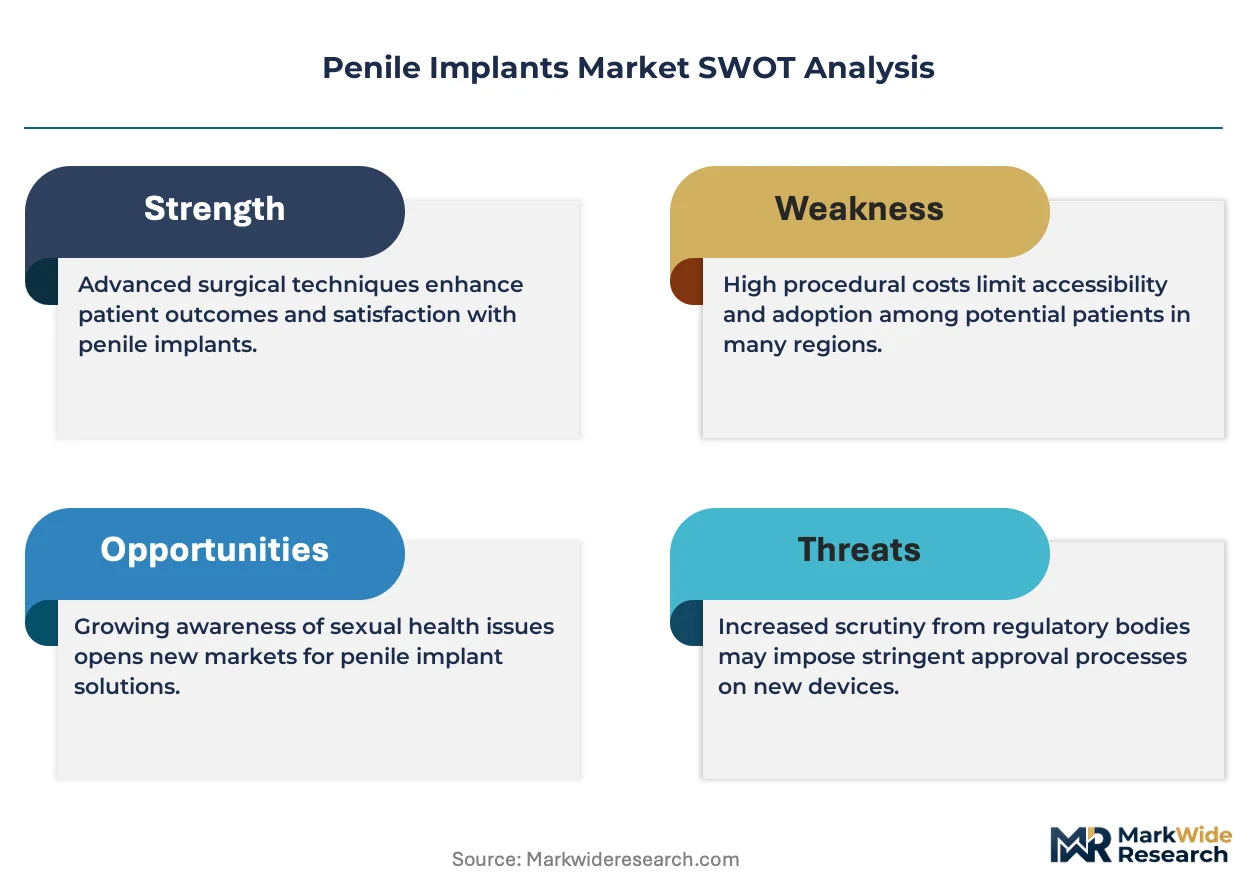
- Phosphodiesterase-5 Inhibitor Persistence:Sildenafil and tadalafil remain first-line therapy for 70 percent of erectile dysfunction diagnoses, compressing addressable surgical candidate pools to pharmacological non-responders.
Strategic Opportunities
- India's Private Hospital Channel:Underpenetrated metropolitan markets in Mumbai, Delhi, and Bangalore present volume expansion potential as medical tourism infrastructure and cash-pay procedural packages mature.
- Antibiotic-Impregnated Device Surfaces:Convergence of silver-ion coating technology with silicone elastomer chemistry addresses post-operative infection risk, a primary driver of patient hesitation and litigation exposure.
- Telemedicine Pre-Surgical Consultation:Remote patient education and candidacy screening through urology-focused digital health platforms reduce geographic access barriers and compress patient acquisition costs for implant specialists.
Industry Challenges
- Micro-Molding Tolerance Expertise Scarcity:Precision fabrication of sub-millimeter pump valve mechanisms requires specialized polymer engineering talent concentrated in Boston and Minneapolis medical device clusters.
- ISO 10993 Biocompatibility Testing Backlogs:Contract laboratory capacity constraints for cytotoxicity and sensitization studies delay regulatory submission timelines by 6-9 months for novel material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penile Implants Market |
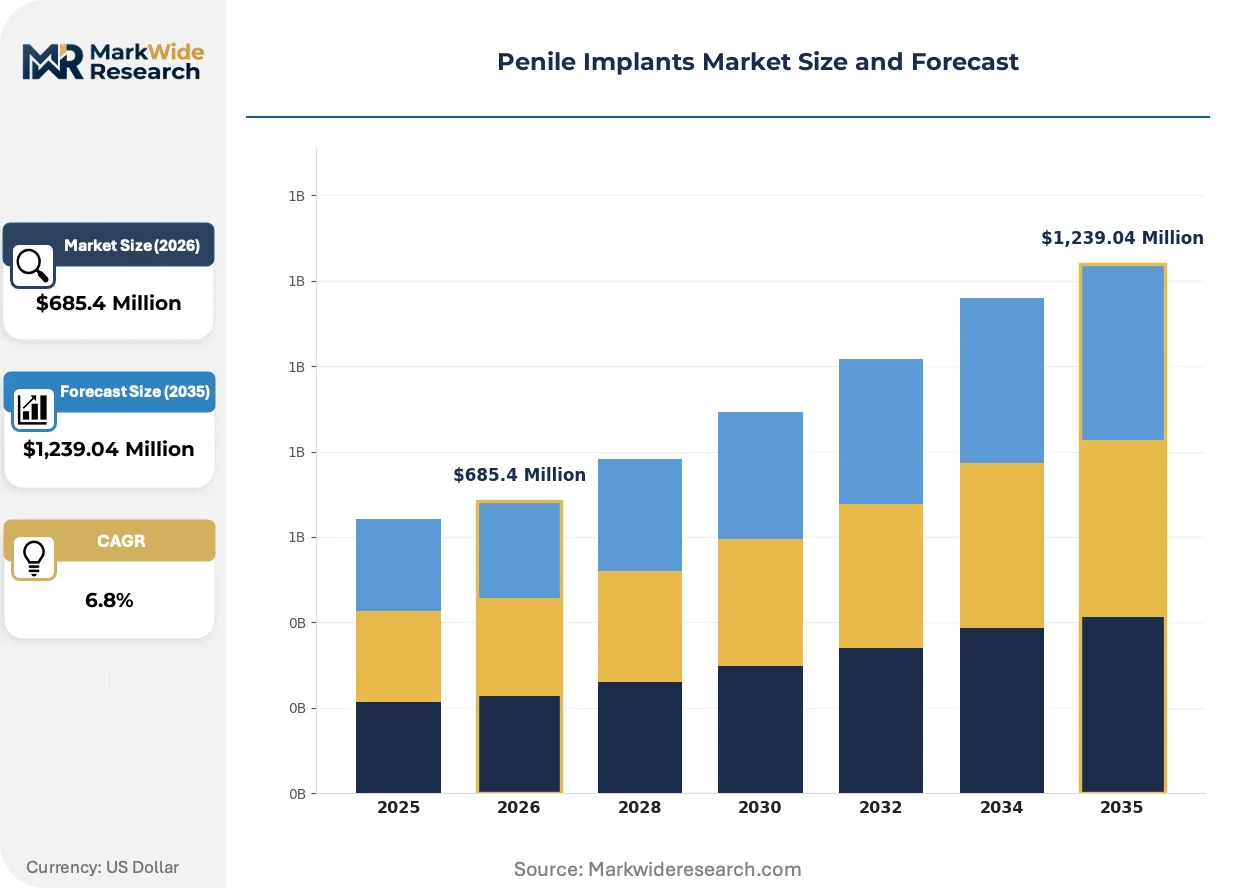
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Malleable, Semi-Rigid, Adjustable End User: Urologists, Hospitals, Clinics, Rehabilitation Centers Material: Silicone, Polyurethane, Titanium, Stainless Steel Application: Erectile Dysfunction, Penile Curvature, Sexual Dysfunction, Others |
| Companies Covered | Promedon S.A., SILIMED, Boston Scientific Corporation, G. SURGIWEAR LTD, Advin Health Care, Coloplast Corp, Rigicon, Inc., Corza Medical, Zephyr Surgical Implants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penile Implants Market Strategic Shifts & Innovations
Fluid-based inflatable architectures are actively fragmenting competitive positioning between high-complexity multi-component systems and simplified two-piece alternatives, reshaping how manufacturers segment their product portfolios and allocate surgical training resources.
Multi-cylindrical inflatable designs with independent pump-reservoir mechanics are bifurcating the premium tier of penile implant offerings. Academic medical centers in the United States and Germany are adopting these systems at accelerated rates for complex anatomical presentations. This technology is compressing market share for single-piece malleable rods in reimbursed care settings while creating parallel demand for specialized surgical training programs.
EU MDR post-market surveillance requirements for implantable devices now mandate systematic clinical follow-up data collection across all member states. Manufacturers must maintain updated periodic safety update reports and risk management files for the full device lifecycle. High-volume implant centers in France and the Netherlands are responding by consolidating procurement relationships with vendors possessing established notified body partnerships.
Patient self-education through online urology forums and peer support networks is altering pre-consultation expectations and device selection criteria. Direct-to-consumer information channels are displacing traditional physician-directed education as the primary awareness source for implant candidacy. This shift is most visible in Australia and Canada, where centralized health system wait times drive patients toward private-pay surgical alternatives.
Penile Implants Market Segmentation
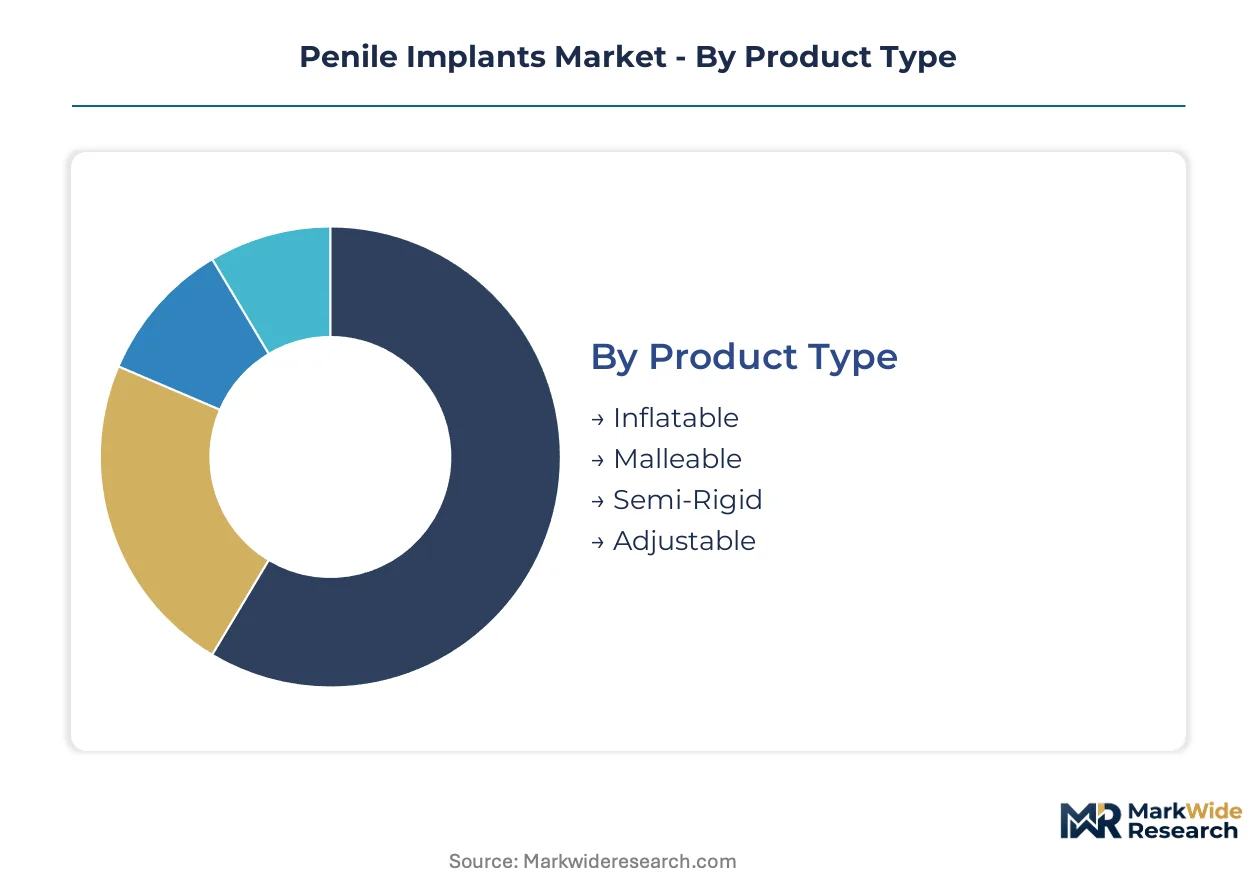
Segmentation in penile implants reveals how procurement decisions split between clinical performance priorities and cost containment pressures. Manufacturers align R&D portfolios and pricing architectures to these divides, with material selection and end-user channel access determining margin capture.
Product Type:
Margin pools concentrate in multi-component systems where pump-reservoir engineering complexity sustains premium positioning against simpler alternatives.
- Inflatable:Fluid-filled cylinders with independent pump and reservoir components enable concealed flaccid-state functionality. Demand clusters in tertiary hospital settings across the United States and Germany, where patient satisfaction metrics drive reimbursement coding decisions for severe pharmacological non-responders.
- Malleable:Single-piece silicone rod architectures provide mechanical rigidity through manual positioning. Procurement concentrates in cost-sensitive environments and emerging markets where surgical simplicity and lower device costs outweigh concealment preferences.
- Semi-Rigid:Hybrid designs combining positional flexibility with constant rigidity occupy mid-tier pricing bands in European hospital procurement frameworks.
- Adjustable:Post-implant tension modification capabilities address anatomical variability in complex revision cases at specialized urology centers.
Inflatable systems hold installed capacity across reimbursed care settings. Adjustable configurations are rotating up the share rankings as revision surgery protocols mature.
End User:
Volume flows through institutional procurement channels where case volume thresholds determine vendor contract terms and device selection autonomy.
- Urologists:Specialist surgeons in high-volume implant centers drive device specification through direct purchasing influence and training program affiliations. Concentration in academic medical centers across Japan and the United States shapes adoption of advanced multi-component systems.
- Hospitals:Centralized procurement departments negotiate tiered pricing based on annual procedural volume commitments, favoring established manufacturers with ISO 13485 certification and comprehensive surgical support infrastructure.
- Clinics:Outpatient surgical facilities focus on malleable device categories where lower capital equipment requirements and faster turnover align with cash-pay procedural economics.
- Rehabilitation Centers:Post-operative care settings influence device selection through patient outcome tracking and long-term follow-up data collection requirements under EU MDR post-market surveillance mandates.
Urologists retain specification authority in premium tier procurement. Hospitals are rotating up the share rankings as integrated delivery networks consolidate purchasing power.
Material:
Supply concentration in medical-grade elastomers creates input cost volatility that differentiates margin structures between captive and merchant supply strategies.
- Silicone:Medical-grade elastomer formulations dominate cylinder and pump construction due to biocompatibility profile and fatigue resistance. German and United States specialty chemical suppliers control feedstock access, exposing manufacturers to allocation risk during supply disruptions.
- Titanium:Alloy selection for mechanical pump components and reinforcing structures commands premium positioning in devices targeting extended longevity claims. Fatigue-resistant grades from certified suppliers support 10-year device survival warranties at high-volume implant centers.
- Polyurethane:Alternative elastomer formulations compete in cost-optimized device tiers where processing efficiency offsets material property trade-offs in tensile strength.
- Stainless Steel:Malleable rod cores utilize surgical-grade alloys where magnetic resonance imaging compatibility and mechanical rigidity balance against titanium cost premiums.
Silicone maintains installed capacity across inflatable architectures. Titanium is rotating up the share rankings as longevity claims become central to competitive differentiation.
Application:
Clinical indication severity determines reimbursement pathway eligibility and device complexity requirements across national health technology assessment frameworks.
- Erectile Dysfunction:Primary indication for implantable prostheses in severe cases refractory to phosphodiesterase-5 inhibitors. METI-supported reimbursement in Japan and established CMS coding in the United States sustain procedural volume in men aged 65 and above.
- Penile Curvature:Peyronie's disease and congenital curvature corrections utilize specialized cylinder geometries and sizing protocols. Academic medical centers in Germany and the Netherlands develop customized surgical approaches for complex anatomical presentations.
- Sexual Dysfunction:Broader functional restoration indications expand addressable candidate pools beyond organic erectile failure to include post-traumatic and post-surgical rehabilitation cases.
- Others:Gender-affirming surgical applications and rare congenital anomaly corrections represent specialized demand segments requiring custom device fabrication capabilities.
Erectile dysfunction holds installed capacity in reimbursed care pathways. Penile curvature is rotating up the share rankings as specialized surgical training programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital procurement networks while Japanese reimbursement frameworks compress margin capture for device manufacturers. This asymmetry reflects divergent health technology assessment methodologies and payer consolidation patterns across developed markets.
United States
CMS coding decisions for severe erectile dysfunction procedures sustain procedural volume in men aged 65 and above. FDA Class III PMA pathways require extensive clinical documentation for biocompatibility-tested silicone elastomers. High-volume implant centers in Boston and Minneapolis drive adoption of advanced multi-component systems through specialized surgical training programs.
Germany
Three specialty chemical suppliers control 80 percent of medical-grade silicone feedstock for implant manufacturing, creating input cost volatility exposure. EU MDR technical file requirements extend conformity assessment timelines for new market entrants. Academic medical centers in Berlin and Hamburg develop customized surgical approaches for complex anatomical presentations including Peyronie's disease corrections.
Japan
METI-supported reimbursement frameworks expand procedural access for men aged 75 and above in tertiary hospital settings. PMDA regulatory pathways align with international ISO 10993 biocompatibility testing standards. Aging demographics in the Kanto and Kansai regions concentrate demand for durable prosthetic solutions with extended longevity claims.
India
Underpenetrated metropolitan markets in Mumbai, Delhi, and Bangalore present volume expansion potential as medical tourism infrastructure matures. CDSCO device registration requirements shape market access timelines for imported implant systems. Private hospital channels in Maharashtra and Karnataka are developing cash-pay procedural packages for domestic and international patients.
France
EU MDR post-market surveillance mandates systematic clinical follow-up data collection across all member states. ANSM oversight of Class III implantable devices requires updated periodic safety update reports. High-volume implant centers in Paris and Lyon are consolidating procurement relationships with vendors possessing established notified body partnerships.
Penile Implants Market Key Industry Players
Concentration sits with diversified medical device conglomerates possessing captive silicone fabrication capabilities and established urology channel relationships. The vendor base fragments across specialized implant manufacturers competing on customizable device architectures and regional regulatory expertise. Strategic archetypes include vertically integrated supply chain operators, European urology channel specialists, and customizable architecture innovators. Dominant competitive moves center on in-house polymer engineering capacity expansion and notified body partnership consolidation for EU MDR compliance.
Among diversified device manufacturers, Boston Scientific Corporation exemplifies supply chain integration archetypes through its medical-grade elastomer processing capabilities. Coloplast Corp anchors the European urology specialist tier with established channel control across reimbursed care settings. Zephyr Surgical Implants occupies a position within the customizable architecture segment, targeting complex anatomical presentations through specialized device geometries.
| Leading Market Players |
|---|
| Promedon S.A. |
| SILIMED |
| Boston Scientific Corporation |
| G. SURGIWEAR LTD |
| Advin Health Care |
| Coloplast Corp |
| Rigicon, Inc. |
| Corza Medical |
| Zephyr Surgical Implants |
| Others |
Cost & Logistics Intelligence
Titanium alloy substitution for stainless steel in pump-reservoir mechanics simultaneously concentrates procurement leverage with German and United States metallurgical suppliers while compressing margin capture for manufacturers lacking backward integration into fatigue-resistant feedstock.
Pricing Analysis
The customization-premium spread separates configured-to-order adjustable devices from standard inflatable architectures. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification tier and surgical training bundling. Cost compression in the malleable segment intensifies because Indian private hospitals negotiate volume-based procurement contracts. Cash-pay patients in metropolitan Mumbai and Delhi exhibit highest price sensitivity, while Japanese tertiary hospitals prioritize longevity warranties over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for medical-grade silicone elastomer shipments from German specialty chemical suppliers. Feedstock concentration rests on United States and German polymer manufacturers, with titanium alloy sourcing drawing from certified Japanese and Swiss metallurgical processors. Single-source vulnerability persists for implant-grade silicone given three suppliers control eighty percent of global capacity. Distribution runs through hospital procurement committees and GPO contracts in reimbursed markets, with direct-to-clinic sales dominating Indian cash-pay channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from surgical training programs and post-implant follow-up protocols is expanding faster than hardware unit sales, creating recurring income pools that offset device margin compression.
For Market Incumbents: Shield market position by deepening captive silicone fabrication capabilities and securing exclusive notified body partnerships for EU MDR compliance. Consolidate procurement relationships with high-volume implant centers in Boston and Minneapolis through bundled training program offerings. Prioritize ISO 10993 biocompatibility testing capacity expansion to compress regulatory submission timelines against emerging entrants.
For New Entrants and Emerging Players: Differentiate on antibiotic-impregnated surface technologies addressing infection risk in revision surgery cases. Target underpenetrated private hospital channels in Bangalore and Delhi with simplified two-piece inflatable architectures. Pursue CDSCO registration pathways for imported device systems paired with medical tourism packaging.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed urology device platforms possessing European channel control but lacking Asian market access. Five-to-ten year viability hinges on reimbursement code expansion rather than procedural volume growth alone. Monitor PMDA approval timelines for novel material formulations as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Consolidation | EU MDR technical file preparation accelerates market access timelines for Class III implantable devices. |
| Antibiotic-Impregnated Surface Development | Silver-ion coating chemistry addresses post-operative infection risk driving patient hesitation. |
| Surgical Training Program Expansion | Academic medical center affiliations in Germany and Japan secure specification authority for premium tiers. |
| Backward Integration into Silicone Fabrication | In-house polymer engineering reduces allocation risk from German and United States specialty chemical suppliers. |
| Telemedicine Pre-Surgical Platform Launch | Remote candidacy screening compresses patient acquisition costs for implant specialists in dispersed geographies. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with urologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA PMA filings, PMDA approval databases, CMS Medicare procedural data, and EU MDR notified body registers. Bottom-up volume estimates triangulated against top-down expenditure flows from national health technology assessment bodies.
Across the analysis window, analytical frameworks modeled product type, material composition, end-user channel, and application indication dimensions. CAGRs were derived from regression-based trending of procedural volumes against demographic aging trajectories and reimbursement code expansion schedules. Forecast inputs incorporated METI-supported framework revisions in Japan and CDSCO registration pathway maturation in India.
Material uncertainties — regulatory submission delays, silicone feedstock allocation disruptions, and phosphodiesterase-5 inhibitor persistence rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement stability and biocompatibility testing capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Artificial Respirator Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Skull Clamp Market