
 South Korea Minimally Invasive Surgery Devices Market | 2026-2036
South Korea Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Minimally Invasive Surgery Devices Market Analytics
Polymer-based trocar sleeves and disposable instrument kits are repositioning cost structures across South Korea's surgical device supply chain. Medtronic leverages its integrated energy platform to dominate electrosurgical device placements in Korean teaching hospitals. Olympus Corporation anchors endoscopy demand through its dominant channel presence in gastrointestinal screening programs nationwide.
Minimally invasive surgery devices encompass instruments, visualization systems, and robotic platforms engineered for procedures through incisions under 25 millimeters, prioritizing reduced tissue trauma and faster patient recovery. Robotic surgery systems command premium positioning due to capital intensity and proprietary console architectures, while laparoscopic instruments represent the volume foundation sustained by procedure breadth across gastrointestinal and gynecological surgery applications. Energy devices within the technology segment capture disproportionate margin pools as bipolar and ultrasonic platforms displace conventional monopolar equipment in Korean operating rooms.
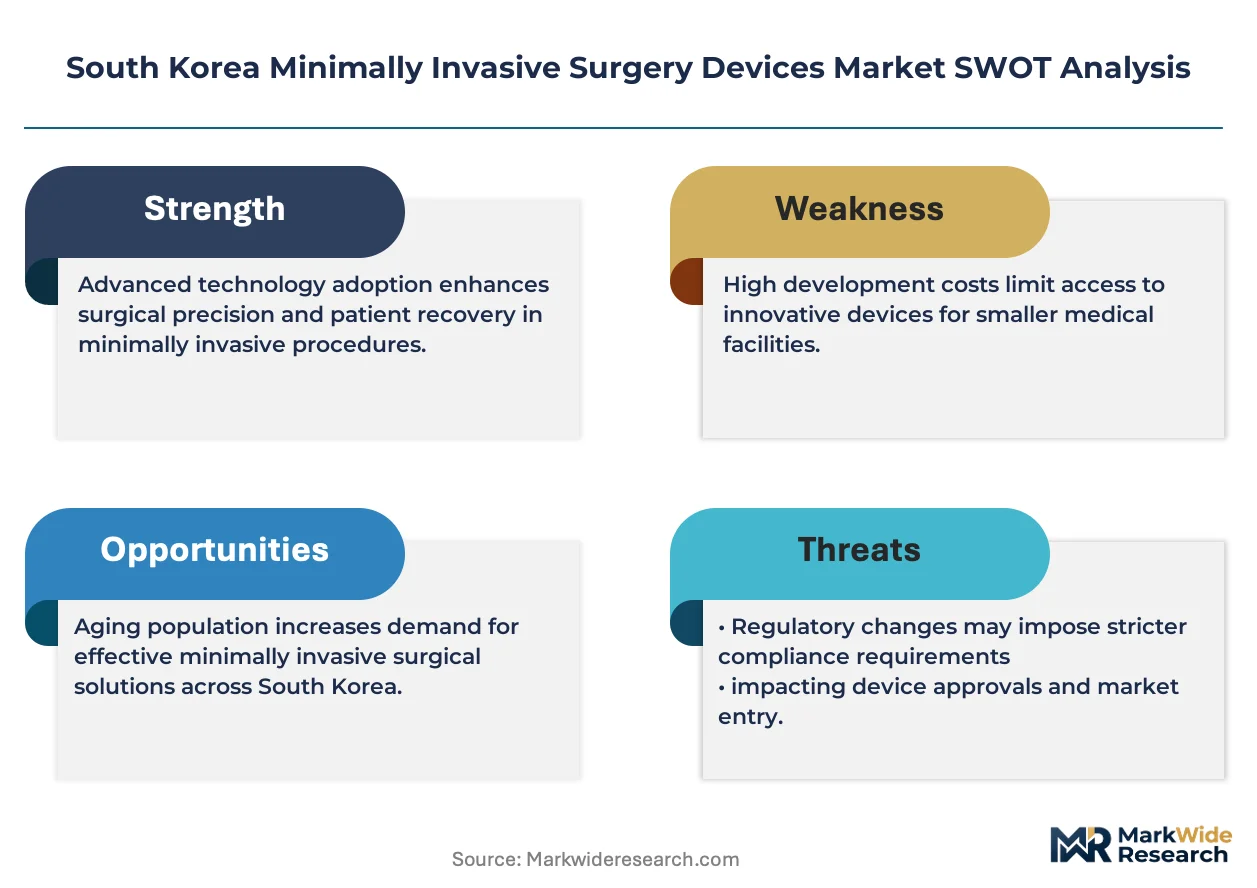
MFDS maintains stringent biocompatibility and electrical safety standards for all implantable and active surgical devices, with MFDS Good Manufacturing Practice audits shaping supplier qualification timelines for foreign manufacturers. The Korean Ministry of Health and Welfare reimbursement rate revisions for robotic-assisted procedures directly influence hospital capital commitment cycles. Stakeholders must monitor MFDS real-world evidence requirements and Health Insurance Review and Assessment Service procedure coding updates as these determine commercial access velocity for next-generation single-port platforms.
Market Dynamics
MFDS streamlined review reforms are compressing approval timelines for novel surgical staplers and energy devices, accelerating competitive entry velocity while university medical centers in Seoul expand robotic surgery programs to capture reimbursement premiums.
Growth Catalysts
- MFDS Fast-Track Pathways:Streamlined medical device review reforms shorten qualification timelines for foreign manufacturers seeking Korean market entry. MFDS Good Manufacturing Practice audits now prioritize electrosurgical and robotic platform categories.
- Metropolitan Hospital Expansion:Tertiary hospitals affiliated with Seoul National University and Yonsei University medical centers are scaling laparoscopic and robotic surgery programs to reduce patient recovery times and capture Health Insurance Review and Assessment Service premium reimbursements.
- Single-Port Platform Development:Next-generation surgical consoles enabling reduced incision profiles are attracting capital commitment from Gyeonggi Province hospital networks seeking differentiated service positioning.
Market Restraints
- Capital Intensity Barriers:Robotic surgery systems require proprietary console architectures and dedicated facility infrastructure, limiting deployment to Seoul metropolitan area tertiary institutions with balance sheet capacity.
- Input Concentration Risk:Polymer-based trocar sleeves and disposable instrument kits depend on specialized medical-grade polymer supply chains concentrated in East Asian contract manufacturers.
- Reimbursement Uncertainty:Korean Ministry of Health and Welfare rate revisions for robotic-assisted procedures create irregular hospital capital commitment cycles and equipment procurement delays.
Strategic Opportunities
- Gyeonggi Province Penetration:Secondary metropolitan hospitals outside Seoul core present underpenetrated demand for laparoscopic instrument volume contracts and energy device placements.
- Real-World Evidence Requirements:MFDS post-market surveillance mandates create service revenue streams for clinical data collection and outcomes documentation platforms.
- Ultrasonic-Bipolar Convergence:Energy device manufacturers integrating ultrasonic and bipolar modalities capture disproportionate margin pools as Korean operating rooms displace conventional monopolar equipment.
Industry Challenges
- Surgeon Training Pipeline:Robotic console certification programs require extended proctored case volumes, constraining deployment velocity at expanding hospital networks.
- Legacy System Integration:Single-port platforms must interface with existing laparoscopic tower configurations and visualization systems, complicating operating room workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Minimally Invasive Surgery Devices Market |
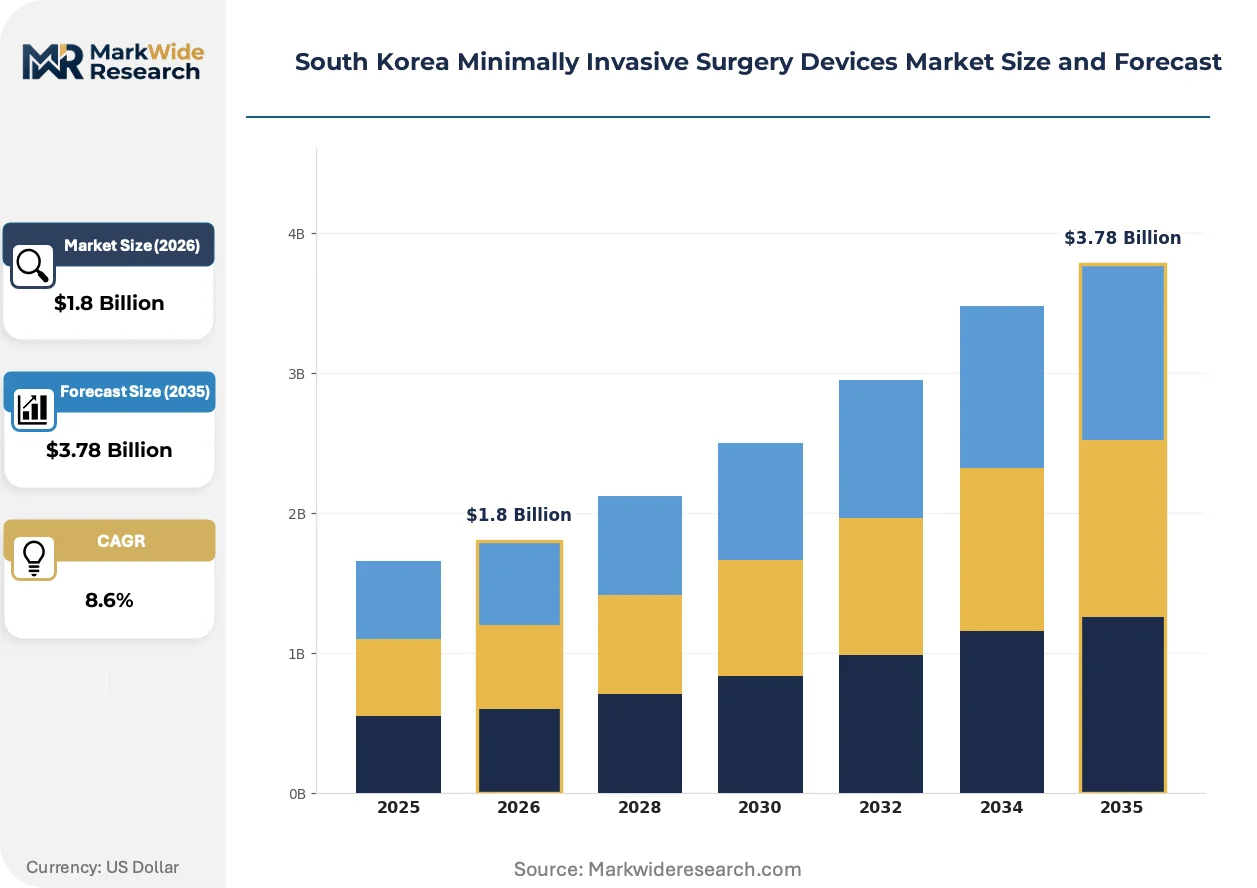
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic Instruments, Robotic Surgery Systems, Endoscopy Devices, Surgical Staplers Application: Gastrointestinal Surgery, Cardiothoracic Surgery, Urological Procedures, Gynecological Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: 3D Imaging Systems, Energy Devices, Access Devices, Single-Port Technology |
| Companies Covered | GE Healthcare, Medtronic, Olympus Corporation, Smith & Nephew, Siemens Healthineers, Intuitive Surgical, Johnson & Johnson, Koninklijke Philips, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Minimally Invasive Surgery Devices Market Evolving Landscape
Technology convergence between energy modalities and robotic platforms is restructuring competitive positioning in Korean surgical device procurement. Regulatory pathway acceleration and procurement model evolution are simultaneously reshaping market access dynamics.
Ultrasonic energy devices are converging with bipolar sealing platforms to create integrated surgical systems that reduce instrument exchange frequency. Tertiary hospitals in Seoul metropolitan area are adopting these convergent platforms at accelerated replacement cycles. This convergence is compressing standalone electrosurgical device margins while elevating service contract value capture.
MFDS real-world evidence requirements are mandating systematic post-market clinical data collection for all novel surgical staplers and active energy devices. Foreign manufacturers face extended supplier qualification timelines as MFDS Good Manufacturing Practice audits intensify biocompatibility documentation standards. Implantable surgical device categories bear the heaviest compliance burden, with Korean university medical centers now requiring local clinical trial participation as a procurement precondition.
Hospital procurement committees are consolidating vendor relationships around integrated platform suppliers capable of delivering energy devices, visualization systems, and disposable kits under unified service agreements. Independent instrument distributors in Gyeonggi Province are losing shelf space to manufacturer-direct clinical specialist teams. This consolidation is most visible among tertiary hospitals affiliated with major university medical centers, where single-source contracts now cover entire minimally invasive surgery device portfolios.
South Korea Minimally Invasive Surgery Devices Market Segmentation
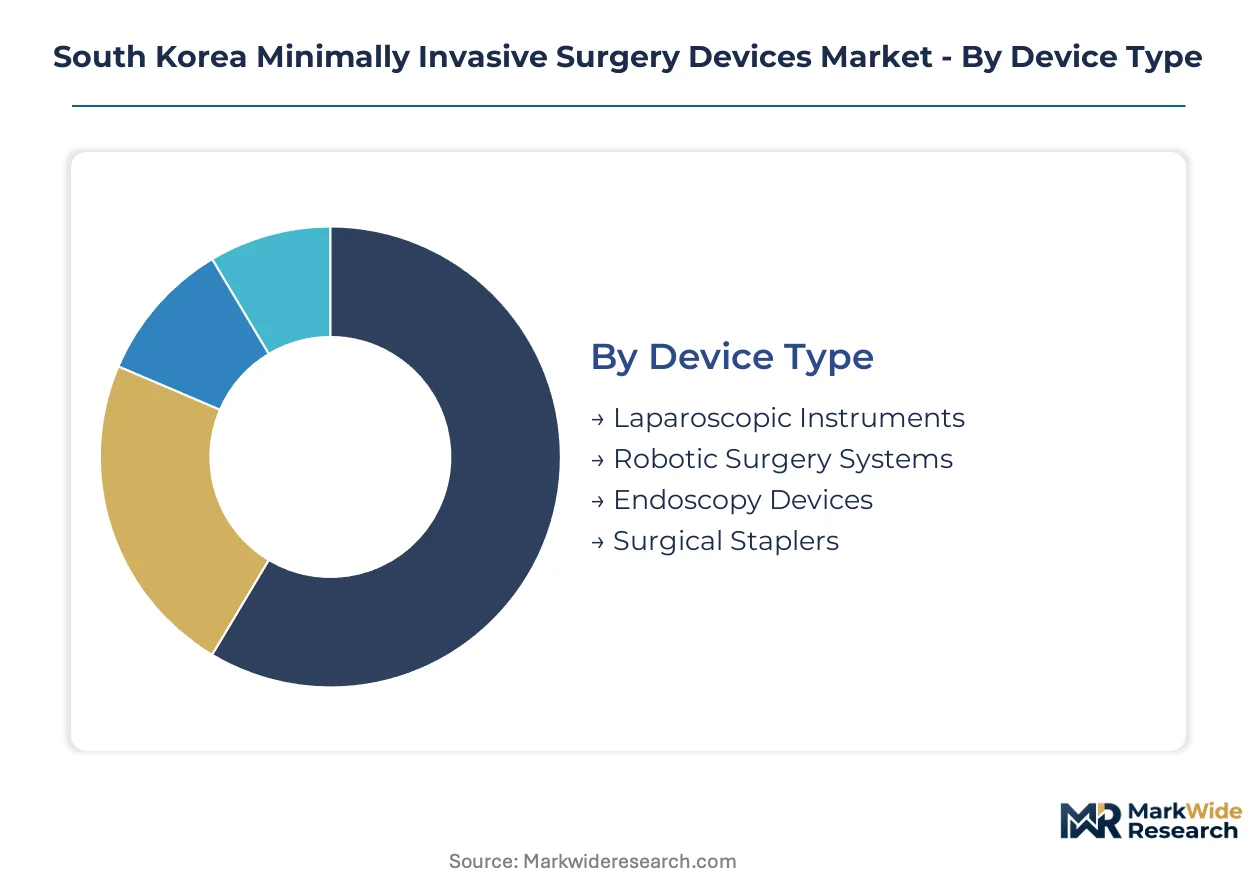
Segmentation in South Korea's minimally invasive surgery devices market reveals distinct procurement patterns across device categories and institutional tiers. Seoul metropolitan hospitals concentrate demand for capital-intensive platforms while provincial networks prioritize volume-driven instrument contracts.
Device Type:
Supply concentration for active surgical platforms clusters around integrated energy console manufacturers with established MFDS certification pathways.
- Laparoscopic Instruments:Graspers, scissors, and dissectors manufactured from medical-grade stainless steel and polymer composites form the procedural foundation across Korean operating rooms. Tertiary hospitals in Seoul National University and Yonsei University medical center networks standardize on disposable kit configurations to reduce reprocessing overhead and infection risk.
- Robotic Surgery Systems:Proprietary console architectures with multi-arm instrument manipulation capabilities command premium capital allocations from Seoul metropolitan institutions. Health Insurance Review and Assessment Service reimbursement premiums for robotic-assisted procedures drive concentrated deployment at university-affiliated hospitals with dedicated facility infrastructure.
- Endoscopy Devices:Flexible gastrointestinal scopes with high-definition imaging processors anchor screening program volumes nationwide.
- Surgical Staplers:Disposable linear and circular stapling platforms with tissue-specific cartridge configurations support gastrointestinal anastomosis procedures.
Laparoscopic instruments absorb the bulk of installed capacity; robotic surgery systems are expanding most quickly.
Application:
Procedure volume distribution across surgical specialties shapes instrument procurement specifications and replacement cycle timing.
- Gastrointestinal Surgery:Gastrectomy and colorectal resection procedures utilizing advanced energy sealing platforms dominate minimally invasive case volumes in Korean tertiary hospitals. Seoul metropolitan medical centers report the highest per-facility utilization rates for laparoscopic gastrointestinal interventions.
- Gynecological Surgery:Hysterectomy and myomectomy procedures through multi-port and single-port access configurations represent the second-largest application segment. University hospital networks in Gyeonggi Province are expanding dedicated gynecological minimally invasive surgery units to capture regional patient flows.
- Cardiothoracic Surgery:Mitral valve repair and lung resection procedures through thoracoscopic and robotic-assisted approaches require specialized instrument sets.
- Urological Procedures:Prostatectomy and nephrectomy interventions utilize both pure laparoscopic and robotic-assisted techniques depending on institutional platform availability.
Gastrointestinal surgery commands the largest share of active device utilization; gynecological surgery is climbing the fastest among major applications.
End User:
Institutional purchasing power and procedure reimbursement structures create tiered demand patterns across South Korea's healthcare delivery system.
- Hospitals:Tertiary and general hospitals with over 300 beds account for the dominant share of capital equipment procurement and high-volume disposable consumption. Seoul metropolitan university medical centers concentrate robotic platform installations and drive energy device standardization across affiliated regional networks.
- Ambulatory Surgical Centers:Freestanding surgical facilities performing selected laparoscopic procedures represent an emerging channel for streamlined instrument kit distribution. Gyeonggi Province regulatory expansions for ambulatory surgical licensing are accelerating site development outside Seoul core.
- Specialty Clinics:Gastroenterology-focused endoscopy centers perform diagnostic and therapeutic procedures with dedicated scope processing capabilities.
- Research Laboratories:University-affiliated surgical innovation centers conduct preclinical validation for novel device platforms seeking MFDS approval.
Hospitals retain the dominant installed base; ambulatory surgical centers are gaining share fastest among institutional categories.
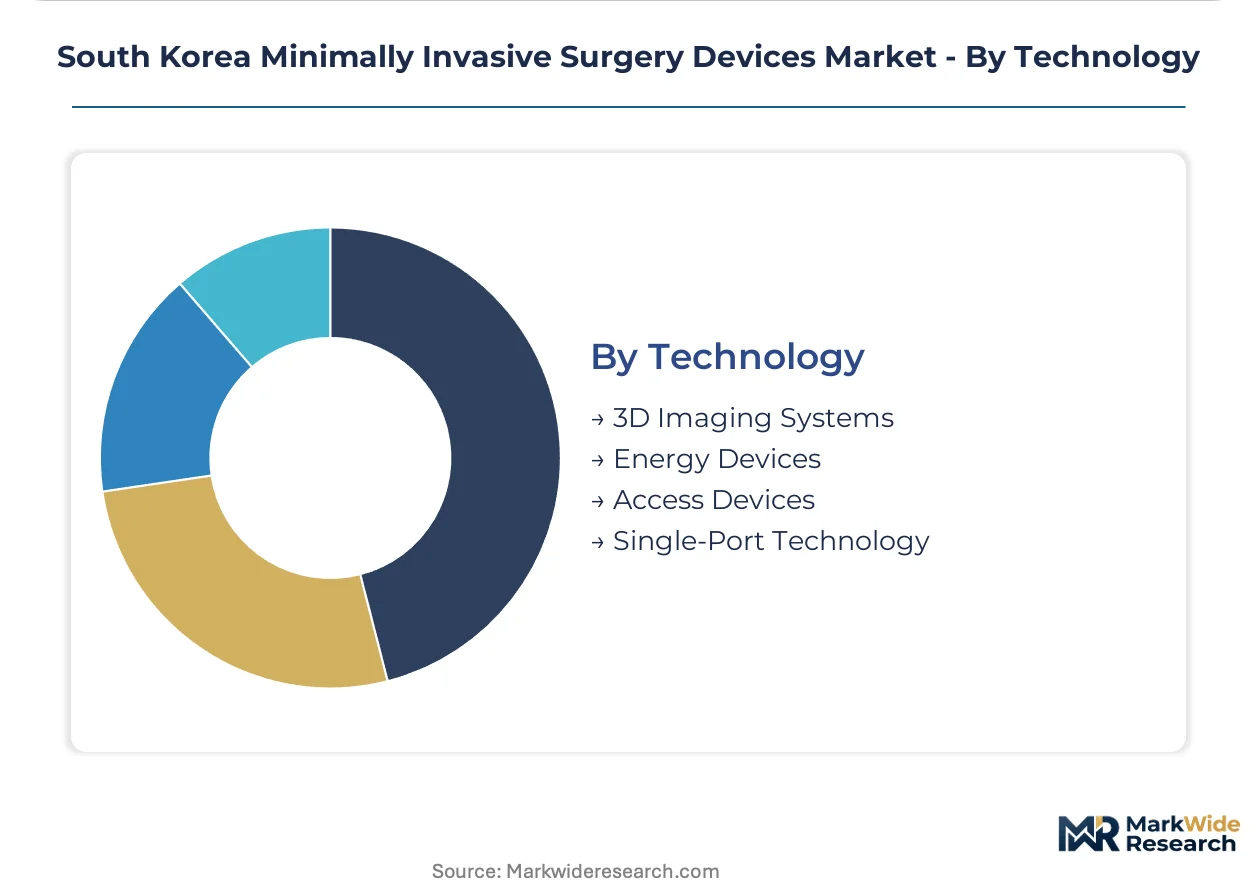
Technology:
Technology convergence between imaging, energy delivery, and access modalities is restructuring competitive positioning in Korean procurement.
- Energy Devices:Bipolar and ultrasonic sealing platforms with integrated vessel-sensing algorithms are displacing conventional monopolar equipment in Korean operating rooms. Tertiary hospitals prioritize convergent systems that reduce instrument exchange frequency during complex procedures.
- 3D Imaging Systems:Stereoscopic visualization platforms with depth-perception enhancement support precision dissection in robotic and advanced laparoscopic procedures. Seoul metropolitan teaching hospitals specify 3D capability as a standard console feature for resident training programs.
- Access Devices:Trocar sleeves and cannula systems in polymer and metal configurations establish pneumoperitoneum maintenance across procedure types.
- Single-Port Technology:Multi-instrument access platforms through single incision sites enable reduced scar profiles for selected patient populations.
Energy devices capture the largest technology investment allocation; single-port technology is expanding most quickly among emerging platform categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for minimally invasive surgery devices in South Korea concentrates heavily within the Seoul metropolitan corridor, where university-affiliated tertiary hospitals drive capital procurement and standardize procurement protocols across affiliated regional networks.
Seoul Capital Area
Seoul National University Hospital and Yonsei University Severance Hospital anchor robotic surgery deployment and energy device standardization across the metropolitan core. MFDS streamlined review reforms accelerate qualification timelines for foreign manufacturers seeking entry through this high-volume channel. Bundang and Songdo medical clusters in Gyeonggi Province are expanding dedicated minimally invasive surgery units to capture overflow patient flows from Seoul core institutions.
Busan-Ulsan
Pusan National University Hospital and Ulsan University Hospital are scaling laparoscopic gastrointestinal programs to reduce referral leakage to Seoul. Regional MFDS audit facilities in Busan shorten supplier qualification timelines for East Asian contract manufacturers. The Busan Port logistics corridor enables faster customs clearance for polymer-based trocar sleeves and disposable instrument kits.
Daegu-Gyeongbuk
Kyungpook National University Hospital anchors tertiary demand in this southeastern manufacturing belt. Health Insurance Review and Assessment Service reimbursement parity for robotic-assisted procedures is driving capital commitment cycles at expanding general hospitals. Daegu's medical device distribution hub serves as a secondary procurement channel for Gyeonggi Province hospital networks.
Daejeon-Sejong
Korea University Hospital Daejeon and Sejong Chungnam National University Hospital are consolidating laparoscopic volume contracts under unified procurement committees. The Sejong administrative city hosts MFDS regional offices that process Good Manufacturing Practice audits for domestic manufacturers. Daejeon's central location enables same-day instrument kit replenishment to satellite facilities across Chungcheong Province.
Gwangju-Honam
Chonnam National University Hospital and Chosun University Hospital dominate tertiary demand in this southwestern agricultural region. Ambulatory surgical center licensing expansions are accelerating site development for streamlined laparoscopic procedures. The Gwangju biomedical cluster supports preclinical validation for novel single-port platforms seeking MFDS approval.
South Korea Minimally Invasive Surgery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform suppliers capturing unified service contracts at tertiary institutions while independent distributors retain footholds in secondary metropolitan markets. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with full-stack surgical portfolios, specialized endoscopy and visualization equipment manufacturers, and regional distributors with localized clinical specialist teams. Consolidation pressure is intensifying as hospital procurement committees favor single-source agreements, while technology licensing partnerships enable faster access to convergent energy modalities.
Among diversified medical technology conglomerates, Medtronic, Johnson & Johnson, and Stryker exemplify the integrated platform positioning that dominates Seoul metropolitan university hospital procurement. Olympus Corporation represents the specialized visualization archetype with established channel density in gastrointestinal screening programs. Intuitive Surgical occupies a distinct capital-equipment tier through its proprietary robotic console architecture. These named entities anchor competitive dynamics without exhausting the full vendor landscape, as the report's final coverage will extend to 15–20 leading companies tailored to specific analytical requirements.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic |
| Olympus Corporation |
| Smith & Nephew |
| Siemens Healthineers |
| Intuitive Surgical |
| Johnson & Johnson |
| Koninklijke Philips |
| Stryker |
| Others |
Value Network & Pricing Analysis
MFDS biocompatibility certification mandates gate both qualified polymer supply and premium-tier pricing access for surgical device manufacturers serving Seoul metropolitan hospitals. Korean university medical centers require local clinical trial participation as a procurement precondition, compressing margins for foreign entrants while elevating service contract value capture for domestic-integrated suppliers.
Pricing Analysis
Volume-driven laparoscopic instrument kits absorb procurement spend while robotic console platforms capture disproportionate margin pools. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified energy devices from reprocessed instruments and unbranded disposable kits. Cost compression in standard-tier laparoscopic graspers is intensifying because Gyeonggi Province hospital networks consolidate vendor relationships under unified service agreements. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, whereas Seoul National University-affiliated tertiary institutions prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Specialized polymer compounding technician shortages in South Korea, China, and Japan constrain medical-grade trocar sleeve production capacity. Korean manufacturers draw from German stainless steel feedstock, Taiwanese precision-machined components, and domestic polymer extrusion facilities. Single-source vulnerability concentrates in East Asian contract manufacturers holding proprietary molding tooling for disposable instrument kits. Distribution runs through manufacturer-direct clinical specialist teams at tertiary hospitals, with independent distributors retaining secondary metropolitan footholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's minimally invasive surgery devices market sits in a technology-transition phase as ultrasonic-bipolar convergent platforms displace conventional monopolar equipment across university hospital networks.
For Market Incumbents: Anchor service contract value through integrated energy platform bundling that encompasses visualization systems and disposable kits under unified procurement agreements. Deepen backward integration into polymer compounding capabilities to mitigate East Asian contract manufacturer concentration risk. Prioritize MFDS real-world evidence collection infrastructure to accelerate next-generation single-port platform qualification timelines.
For New Entrants and Emerging Players: Digital-channel direct procurement platforms targeting Gyeonggi Province secondary metropolitan hospitals present the most penetrable entry vector outside Seoul core procurement committee dominance. Focus initial placements on laparoscopic instrument volume contracts with standardized disposable kit configurations rather than capital-intensive robotic console competition. Leverage ultrasonic-bipolar convergence technology licensing partnerships to bypass proprietary console architecture barriers.
For Investors and Strategic Acquirers: MFDS streamlined review reform implementation velocity is the leading indicator that regulatory pathway acceleration will favor platform-integrated suppliers over standalone instrument manufacturers. Acquisition target archetypes include regional distributors with established Gyeonggi Province clinical specialist teams and domestic polymer processing capabilities. Monitor Health Insurance Review and Assessment Service reimbursement rate revision announcements as the primary signal for hospital capital commitment cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Fast-Track Certification Investment | Accelerated market entry velocity for novel energy devices through streamlined biocompatibility review pathways. |
| University Medical Center Partnership | Seoul National University and Yonsei University affiliations establish procurement standardization protocols across regional networks. |
| Ultrasonic-Bipolar Platform Convergence | Integrated sealing modalities capture premium positioning as Korean operating rooms displace monopolar equipment. |
| Gyeonggi Province Distribution Expansion | Secondary metropolitan hospital networks outside Seoul core present underpenetrated demand for volume instrument contracts. |
| Real-World Evidence Infrastructure Buildout | Post-market surveillance capabilities satisfy MFDS mandates while generating recurring service revenue streams. |
Research Methodology
Multi-period observation of MFDS approval timelines, Health Insurance Review and Assessment Service reimbursement rate revisions, and university hospital procurement committee vendor consolidation patterns anchored the trend analysis, supplemented by interviews with hospital purchasing managers, biomedical engineers, GPO contracts managers, and MFDS regulatory affairs specialists. Secondary validation drew from MFDS medical device registration databases, Health Insurance Review and Assessment Service procedure coding updates, Korean Ministry of Health and Welfare policy circulars, and tertiary hospital capital expenditure disclosures. Bottom-up instrument kit volume estimates and top-down energy device revenue triangulation cross-validated segment-level projections.
Segment-weighting across device type, application specialty, end-user institutional tier, and technology modality dimensions structured the analytical framework throughout the forecast period. CAGRs derived from procedure volume elasticity to reimbursement rate changes, replacement cycle compression for convergent energy platforms, and capital commitment velocity at Gyeonggi Province hospital networks. Modeling incorporated MFDS audit intensity trajectories, polymer supply chain concentration metrics, and robotic console certification pipeline constraints as industry-specific forecast inputs.
The model holds under stable MFDS review reform implementation and Health Insurance Review and Assessment Service reimbursement parity maintenance; deviation in regulatory audit intensity or ministry-level rate revision timing would shift hospital procurement cycle phasing and foreign manufacturer entry velocity. Forecasts reflect documented assumptions regarding polymer supply chain stability and university medical center expansion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prefilled Syringes Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Medical Face Shield Market
Medical Devices
Global Venous Stents Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Chest Drainage Devices Market