
 Polyglyconate Sutures Market | 2026-2036
Polyglyconate Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglyconate Sutures Market Analytics
Hospital procurement channels for synthetic absorbable sutures is narrowing as group purchasing organizations consolidate vendor panels across integrated delivery networks. Johnson & Johnson leverages its broad surgical portfolio to sustain contracted access across US health systems. Medtronic anchors its position through specialized cardiovascular suture lines tied to procedural kit bundling. B. Braun SE competes on manufacturing scale, operating dedicated cleanroom facilities for monofilament extrusion in Germany and Malaysia.
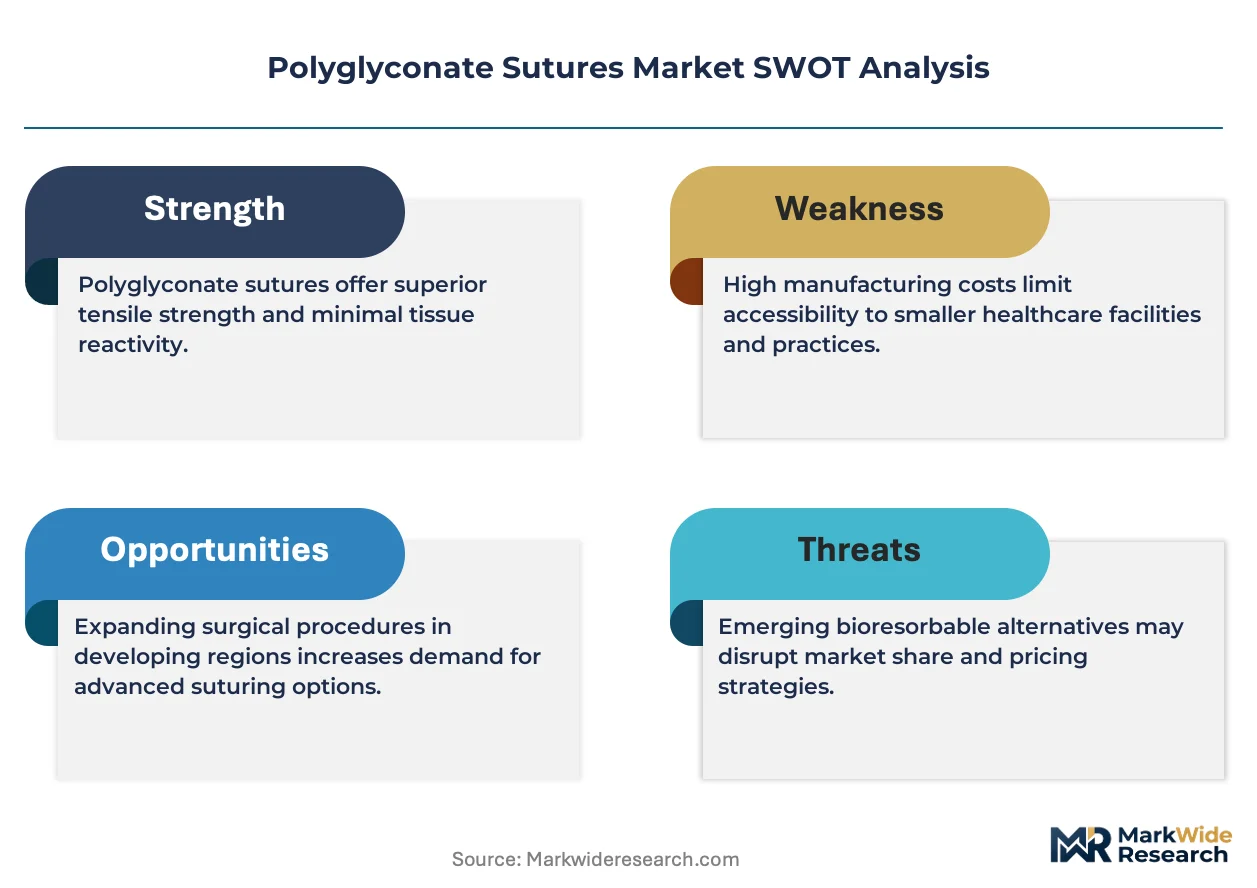
Polyglyconate sutures consist of a synthetic glycolide-based copolymer engineered for predictable tensile strength retention over 14 to 21 days followed by complete hydrolytic absorption within 90 to 120 days, serving primarily as a temporary wound closure medium in soft-tissue surgical applications. Monofilament constructions dominate premium general surgery applications where reduced tissue drag and bacterial wicking resistance command higher unit economics, while braided configurations retain share in orthopedic soft-tissue repair where knot security remains paramount. Hospitals as an end-user category represent the deepest installed base, though ambulatory surgical centers represent the fastest-growing procurement channel as same-day discharge protocols expand procedural migration.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market entry for polyglyconate suture manufacturers, with ISO 10993 biocompatibility testing serving as a baseline cross-border requirement. Health Canada and Japan's PMDA maintain aligned but distinct polymer purity standards that shape regional formulation specifications. Stakeholders must monitor evolving EU Green Deal chemical sustainability disclosures and US EPA industrial solvent emission limits as these frameworks increasingly influence synthetic polymer manufacturing location decisions and capital allocation priorities.
Market Dynamics
Group purchasing organization consolidation across US integrated delivery networks is compressing vendor access points, forcing synthetic absorbable suture manufacturers to defend contracted positions through procedural kit integration and volume commitment guarantees rather than standalone product differentiation.
Growth Catalysts
- Outpatient procedural migration:Ambulatory surgical centers in the United States and Germany are expanding same-day discharge protocols, driving absorbable suture procurement for soft-tissue closures that eliminate follow-up removal visits.
- FDA-EMA regulatory convergence:Aligned biocompatibility standards under ISO 10993 are accelerating 510(k) and MDR conformity assessment timelines, reducing registration delays for glycolide-based copolymer formulations.
- Monofilament construction preference:Reduced tissue drag and bacterial wicking resistance in premium general surgery applications is elevating unit economics for specialized synthetic sutures over conventional braided alternatives.
Market Restraints
- Polymer feedstock concentration:Glycolide monomer supply concentrates among specialized chemical manufacturers in Germany and China, exposing suture producers to input cost volatility and qualification bottlenecks.
- Polyglactin 910 substitution:Vicryl-equivalent braided sutures retain entrenched preference in orthopedic soft-tissue repair where knot security outweighs absorption profile advantages.
- EU Green Deal chemical disclosures:Evolving sustainability reporting requirements for synthetic polymer manufacturing are extending capital allocation timelines for cleanroom facility expansion decisions.
Strategic Opportunities
- Japanese tertiary infrastructure:Premium synthetic suture penetration remains below US and German levels despite comparable surgical volume density, presenting expansion potential through PMDA-registered distribution partnerships.
- Veterinary surgical adoption:Small-animal orthopedic and soft-tissue procedures are migrating toward human-grade absorbable sutures as specialty veterinary hospital chains standardize procurement.
- Kit bundling integration:Procedural pack consolidation by cardiovascular device manufacturers creates captive demand channels for specialized suture lines matched to specific implant systems.
Industry Challenges
- Cleanroom technician scarcity:Monofilament extrusion operations in Malaysia and Germany face qualified personnel gaps for ISO Class 7 environment maintenance and in-process quality verification.
- Dual regulatory pathway complexity:Simultaneous FDA 510(k) and EMA MDR submissions require divergent clinical evidence packages, stretching regulatory affairs bandwidth across multiple polymer purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglyconate Sutures Market |
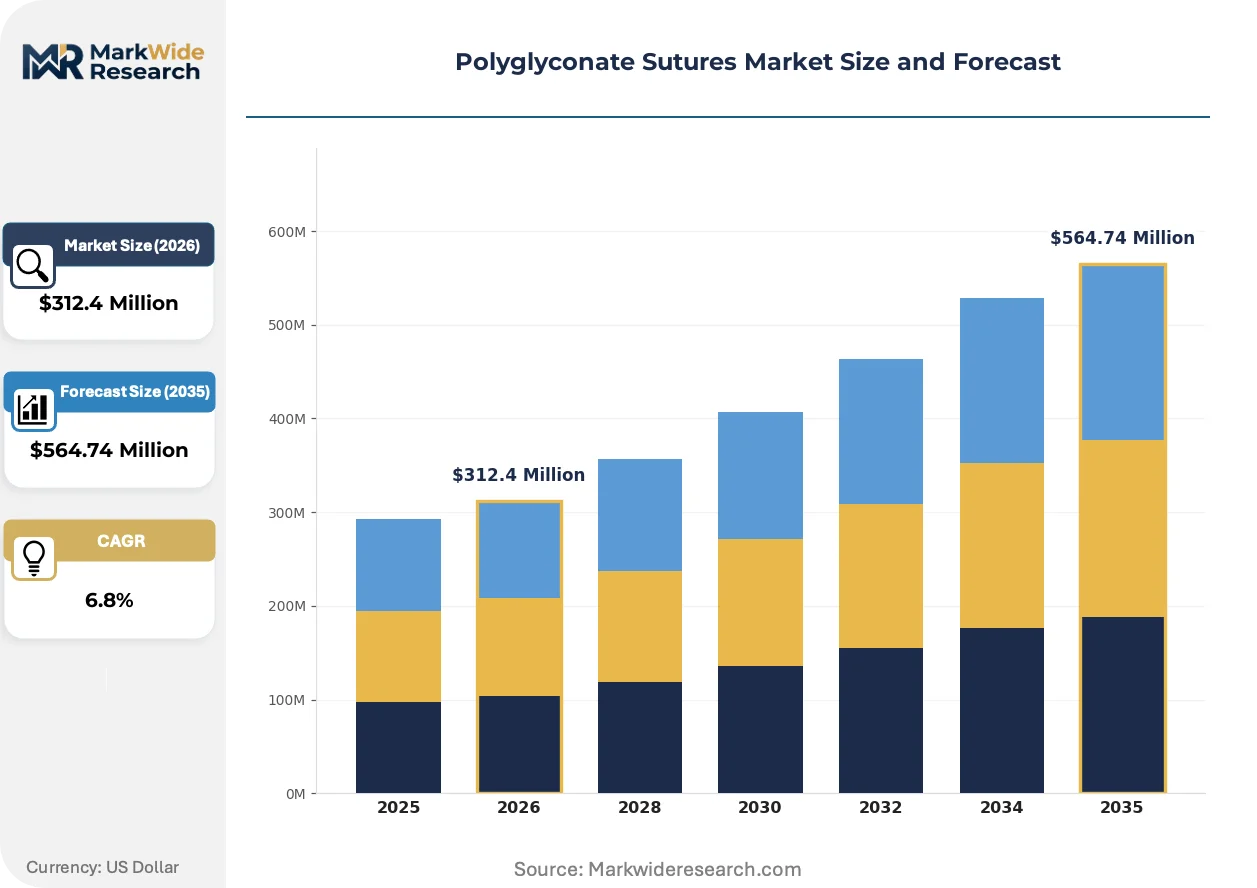
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Braided, Coated, Non-coated Application: General Surgery, Orthopedic Surgery, Cardiac Surgery, Gynecological Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Veterinary Clinics Material: Absorbable, Non-absorbable, Biodegradable, Synthetic |
| Companies Covered | Johnson & Johnson, Medtronic, B. Braun SE, Teleflex Incorporated, DemeTECH Corporation, Healthium Medtech Limited, Advanced Medical Solutions Group plc, Corza Medical, Integra Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglyconate Sutures Market Evolving Landscape
Absorbable suture engineering is converging with precision polymer chemistry and automated manufacturing controls, collapsing traditional performance trade-offs between tensile strength retention and absorption predictability.
Antimicrobial-coated monofilament constructions are collapsing the historical separation between infection prevention and wound closure hardware. Cardiovascular surgery departments in German university hospitals are adopting triclosan-integrated glycolide copolymers for sternal closure applications. This convergence is compressing procurement decisions toward single-source vendors capable of delivering both mechanical performance and antimicrobial efficacy without secondary device requirements.
EMA Medical Device Regulation Annex I general safety and performance requirements are mandating enhanced clinical evidence for synthetic absorbable polymers. Manufacturers must now submit biocompatibility data beyond ISO 10993 baseline testing, including longitudinal absorption profile documentation. Cardiovascular suture lines face the steepest compliance burden, with notified bodies in Germany and Ireland extending conformity assessment durations by four to six months for novel copolymer formulations.
Same-day discharge protocols are fragmenting historical hospital-centric procurement patterns. Ambulatory surgical centers in the United States are negotiating direct distributor relationships, bypassing integrated delivery network formularies for high-volume absorbable suture categories. This disintermediation is most visible in Florida and Texas metropolitan markets where independent ASC chains now represent fifteen to twenty percent of synthetic suture volume in soft-tissue general surgery applications.
Polyglyconate Sutures Market Segmentation
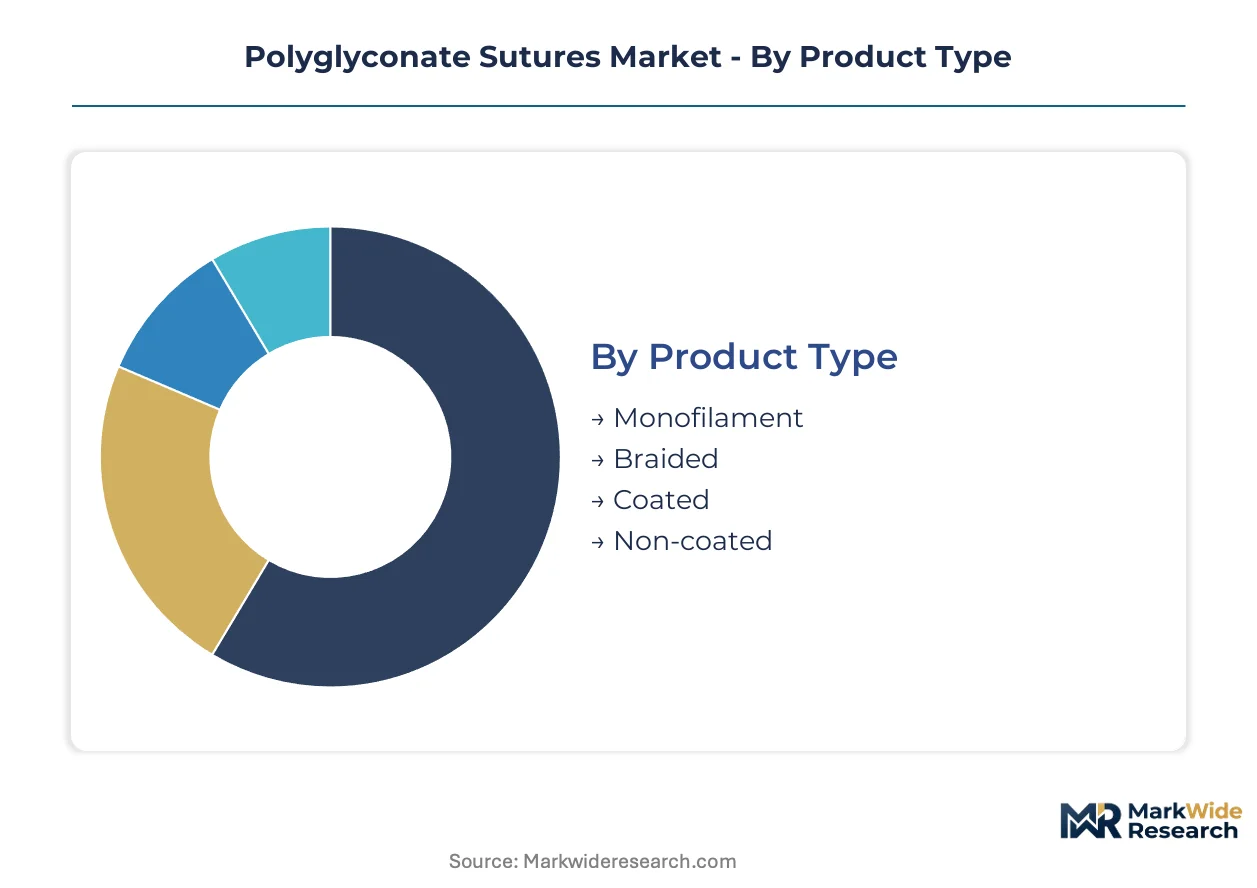
Polyglyconate suture manufacturers navigate distinct performance requirements across wound closure applications. Construction geometry, clinical setting, and absorption kinetics create divergent procurement patterns that shape product development priorities.
Product Type:
Mature monofilament formats dominate premium positioning while braided alternatives retain volume share through established clinical familiarity.
- Monofilament:Single-strand glycolide copolymer construction delivers reduced tissue drag and bacterial wicking resistance. German university hospitals and US tertiary centers specify monofilament for premium general surgery applications where elimination of follow-up removal visits justifies higher unit economics.
- Braided:Multifilament woven architecture provides superior knot security through increased surface friction. Orthopedic soft-tissue repair in Japanese and German hospital systems favors braided configurations where mechanical stability outweighs absorption speed considerations.
- Coated:Surface-treated variants reduce tissue adherence during passage.
- Non-coated:Untreated constructions serve cost-sensitive procurement channels.
Monofilament handles the majority of throughput; coated variants are climbing the fastest on share as antimicrobial integration expands.
Application:
Volume concentrates in high-frequency soft-tissue procedures while specialized cardiac interventions command premium positioning.
- General Surgery:Soft-tissue closure across abdominal, dermatological, and gastrointestinal procedures represents the deepest installed base. Ambulatory surgical centers in Florida and Texas metropolitan markets are expanding polyglyconate procurement for same-day discharge protocols.
- Orthopedic Surgery:Tendon and ligament repair applications favor slower-absorbing braided alternatives with extended tensile strength retention. German and Japanese hospital systems maintain entrenched preference for polyglactin 910 equivalents in this category.
- Cardiac Surgery:Sternal closure and vascular anastomosis require specialized antimicrobial-coated formulations.
- Gynecological Surgery:Pelvic floor and hysterectomy applications drive demand for predictable absorption profiles.
General Surgery anchors procurement volume; Ambulatory Surgical Centers are gaining share fastest through procedural migration.
End User:
Institutional scale determines contracting leverage, with integrated delivery networks consolidating vendor access points.
- Hospitals:Tertiary and community hospital systems maintain the deepest formulary penetration through group purchasing organization contracts. Johnson & Johnson and B. Braun SE defend positions through procedural kit bundling across US integrated delivery networks.
- Ambulatory Surgical Centers:Independent same-day facilities in Texas and Florida are negotiating direct distributor relationships, bypassing hospital formularies for high-volume absorbable suture categories.
- Clinics:Office-based procedural volumes remain limited for absorbable synthetic sutures.
- Veterinary Clinics:Specialty small-animal hospital chains are standardizing human-grade absorbable sutures for orthopedic procedures.
Hospitals retain the dominant procurement channel; Veterinary Clinics are expanding most quickly as specialty chains consolidate.
Material:
Absorption kinetics and polymer origin create tiered clinical positioning across synthetic absorbable categories.
- Absorbable:Hydrolytic degradation within 90 to 120 days eliminates removal visits. FDA 510(k) clearance pathways and EMA MDR conformity assessments govern registration for glycolide-based copolymer formulations.
- Synthetic:Engineered polymer purity enables predictable tensile strength retention profiles. ISO 10993 biocompatibility testing serves as baseline cross-border requirement for synthetic absorbable sutures.
- Biodegradable:Alternative degradation mechanisms serve niche applications.
- Non-absorbable:Permanent wound closure materials compete in limited procedural categories.
Absorbable synthetic constructions dominate clinical adoption; Biodegradable variants are gaining share fastest through sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for glycolide monomer feedstocks, while the Los Angeles-Long Beach port complex channels US Pacific surgical supply chains. These maritime gateways underwrite regional procurement concentration for synthetic absorbable sutures.
United States
Ambulatory surgical centers in Florida and Texas metropolitan markets are expanding polyglyconate procurement for same-day discharge protocols. FDA 510(k) clearance pathways govern market entry for glycolide-based copolymer formulations. The Southeast surgical corridor from Atlanta to Miami concentrates tertiary hospital procurement through integrated delivery network contracts.
Germany
German university hospitals specify monofilament constructions for premium general surgery applications where reduced tissue drag justifies higher unit economics. EMA Medical Device Regulation conformity assessments mandate enhanced clinical evidence beyond ISO 10993 baseline testing. The Rhine-Main industrial zone around Frankfurt hosts specialized cleanroom facilities for monofilament extrusion operations.
Japan
Premium synthetic suture penetration remains below US and German levels despite comparable surgical volume density in Japanese tertiary centers. PMDA maintains aligned but distinct polymer purity standards that shape regional formulation specifications. The Kanto region surrounding Tokyo anchors domestic distribution through PMDA-registered partnerships.
China
Glycolide monomer supply concentrates among specialized chemical manufacturers, exposing suture producers to input cost volatility and qualification bottlenecks. NMPA registration requirements for synthetic absorbable polymers are converging toward international biocompatibility standards. The Yangtze River Delta chemical corridor near Shanghai hosts feedstock production clusters.
Malaysia
Monofilament extrusion operations face qualified personnel gaps for ISO Class 7 environment maintenance and in-process quality verification. The country's national pharmaceutical regulator aligns with ASEAN harmonized medical device directives. Penang's medical device manufacturing zone attracts cleanroom facility investment from multinational suture producers.
Polyglyconate Sutures Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in monofilament extrusion and polymer formulation. The vendor base stratifies across three tiers: diversified surgical conglomerates defending contracted access through kit bundling, mid-scale manufacturers competing on cleanroom scale and regulatory bandwidth, and regional specialists serving price-sensitive procurement channels. Two dominant competitive moves are reshaping positioning: procedural pack consolidation by cardiovascular device manufacturers creating captive demand channels, and backward integration into glycolide monomer production to secure feedstock qualification.
Among diversified surgical conglomerates, Johnson & Johnson and Medtronic exemplify the platform-integrator archetype, leveraging broad procedural portfolios to sustain contracted access across US health systems. B. Braun SE anchors the mid-scale manufacturing tier, operating dedicated cleanroom facilities that represent the scale-driven competitive position in European and Asia-Pacific markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| B. Braun SE |
| Teleflex Incorporated |
| DemeTECH Corporation |
| Healthium Medtech Limited |
| Advanced Medical Solutions Group plc |
| Corza Medical |
| Integra Lifesciences Corporation |
| Others |
Value Network & Pricing Analysis
Glycolide monomer concentration among German and Chinese chemical manufacturers determines both the spread between premium antimicrobial-coated and standard uncoated suture tiers and the geographic configuration of cleanroom extrusion investments. Procurement managers at US integrated delivery networks face simultaneous input cost volatility and qualification bottlenecks that compress margin structures across the value chain.
Pricing Analysis
Volume-discount tiering structures dominate hospital system contracting, with group purchasing organizations negotiating 15-25 point spreads between committed annual volume tiers. Price differentiation rests on antimicrobial coating certification and monofilament construction precision, with FDA 510(k) cleared formulations commanding measurable premiums over standard glycolide copolymers. Cost compression in the standard braided segment is intensifying as polyglactin 910 substitutes retain orthopedic preference. Ambulatory surgical centers exhibit the highest price sensitivity due to direct distributor negotiations, while German university hospitals prioritize performance over unit cost.
Supply Chain Analysis
Upstream glycolide feedstock production centers on the Rhine-Main industrial zone near Frankfurt and the Yangtze River Delta chemical corridor outside Shanghai. Monofilament extrusion operations draw from specialized polymerization inputs including high-purity glycolide monomer, medical-grade catalyst systems, and ISO 10993 validated dye formulations. Single-source vulnerability concentrates in German specialty chemical manufacturers who control qualification pathways for pharmaceutical-grade copolymers. Distribution runs through integrated delivery network formularies in the United States and direct hospital procurement channels in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cardiovascular device manufacturers are collapsing procedural pack decisions into single-source vendor relationships, rewarding ecosystem breadth over standalone product performance.
For Market Incumbents: Harden contracted access positions through procedural kit bundling with implant system manufacturers, locking out standalone suture competitors from cardiovascular and orthopedic pack decisions. Deepen backward integration into glycolide monomer production to neutralize feedstock qualification bottlenecks and input cost volatility from German and Chinese chemical suppliers. Expand cleanroom capacity in Penang and the Rhine-Main zone to defend manufacturing scale advantages against mid-tier competitors. For New Entrants and Emerging Players: Japanese tertiary surgical centers represent the most penetrable entry point given below-peer premium synthetic suture penetration despite comparable procedural volume density to US and German markets. Veterinary specialty hospital chains standardizing human-grade absorbable sutures for small-animal orthopedic procedures offer a second white-space channel with reduced regulatory barriers and faster procurement cycles. Pursue PMDA-registered distribution partnerships as the primary go-to-market mechanism, leveraging distinct polymer purity specifications to differentiate from entrenched competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale manufacturers with captive cleanroom facilities and regulatory bandwidth across FDA and EMA pathways. Acquisition targets should display demonstrated 510(k) clearance velocity and established GPO contract presence within at least one major US health system. The signal to watch is cardiovascular device manufacturer pack consolidation announcements, which foreshadow captive demand channel formation and corresponding valuation premiums for integrated suture suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycolide Monomer | Captive supply of pharmaceutical-grade feedstock neutralizes qualification bottlenecks and cost volatility from German and Chinese chemical manufacturers. |
| Antimicrobial Coating FDA Submission | Triclosan-integrated formulations unlock premium positioning in sternal closure applications at German university hospitals. |
| PMDA Registration Partnership | Distinct polymer purity standards in Japan create differentiation pathways against US and European competitors with entrenched formulary positions. |
| Procedural Kit Bundling Agreement | Cardiovascular device manufacturer pack consolidation creates captive demand channels resistant to standalone suture competitors. |
| Cleanroom Capacity Expansion | ISO Class 7 facilities in Penang and the Rhine-Main zone defend manufacturing scale against qualified technician scarcity. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, group purchasing organization contract managers, biomedical engineers at tertiary surgical centers, and regulatory affairs specialists at synthetic polymer manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, hospital procurement databases, and integrated delivery network formulary disclosures. Bottom-up demand modeling across construction type, application, and end-user segments was triangulated against top-down polymer feedstock production estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning monofilament versus braided construction, general surgery versus orthopedic versus cardiac application, and hospital versus ambulatory surgical center procurement channel. CAGRs were derived from installed base erosion rates, procedural volume migration patterns, and premium product penetration curves. Industry-specific inputs included glycolide monomer capacity utilization at German and Chinese chemical manufacturers and PMDA registration timeline benchmarks for novel copolymer formulations.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates, Chinese industrial chemical export policies, or US healthcare reimbursement trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway convergence and cleanroom technician availability. Cross-checking against hospital capital expenditure surveys and cardiovascular device manufacturer pack consolidation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Loupes Market
Medical Devices
Bone Power Tools Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Endocavity Transducer Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Artificial Respirator Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Phoropters Market