
 Global Artificial Organs and Bionics Market | 2026-2036
Global Artificial Organs and Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Organs and Bionics Market Foresight
Hospital procurement channels for artificial organs and bionics is narrowing as integrated delivery networks consolidate vendor lists across North America and Western Europe. Medtronic plc leverages its cardiovascular portfolio depth to sustain long-term supply agreements with tier-one cardiac centers. Boston Scientific Corporation differentiates through electrophysiology and neuromodulation platforms, while Cochlear Ltd. dominates hearing restoration with direct-to-implant-center distribution in Australia and the United Kingdom.
Artificial organs and bionics encompass implantable and external devices engineered to replace or augment biological functions, typically fabricated from biocompatible polymers, titanium alloys, or bioactive ceramics and incorporating microelectromechanical systems for sensory feedback or electrical modulation. These devices restore physiological performance in patients with end-stage organ failure, sensory loss, or motor impairment, operating through battery-powered control units, wireless telemetry, or osseointegrated mechanical interfaces. Cochlear implants and neurostimulators lead revenue contribution due to established reimbursement codes and repeat-procedure economics, while 3D-printed prosthetic limbs and retinal implants represent faster-expanding categories where bioelectronics and tissue engineering convergence is compressing development timelines. Dialysis machines remain the most mature segment, with margin pools shifting toward portable and home-based configurations.
FDA premarket approval pathways and EMA Medical Device Regulation classification determine commercialization timelines and clinical evidence requirements for artificial heart and neurostimulator manufacturers. Japan's PMDA and Australia's TGA enforce parallel but divergent biocompatibility testing standards that fragment regulatory submission strategies for multi-region launches. Stakeholders must monitor evolving cybersecurity mandates for connected bionic devices and anticipate reimbursement recalibration as outcome-based payment models penetrate specialized clinics and veteran care centers.
Market Dynamics
Integrated delivery networks in North America and Western Europe are consolidating vendor lists for cardiovascular and neuromodulation devices, compressing procurement channels and favoring manufacturers with full-stack regulatory dossiers across FDA, EMA, and PMDA jurisdictions.
Growth Catalysts
- EMA Medical Device Regulation updates:Streamlined conformity assessment pathways for active implantable devices are accelerating hospital procurement cycles for ventricular assist systems in Germany and the Netherlands.
- Osseointegrated mechanical interfaces:Advances in titanium alloy surface engineering are expanding candidate pools for direct skeletal attachment prosthetics in veteran care centers.
- Japan's METI reimbursement acceleration:Fast-tracked national health insurance listing for neurostimulator implants is concentrating surgical volume in Tokyo-Osaka specialty clinics.
Market Restraints
- Battery chemistry supply concentration:Lithium-ion cell production for implantable device power units clusters in East Asian manufacturing hubs, exposing OEMs to raw material allocation volatility.
- Biocompatibility testing divergence:Japan's PMDA and Australia's TGA enforce non-harmonized cytotoxicity and sensitization protocols, fragmenting multi-region submission strategies and extending time-to-market.
- Donor organ availability:Persistent shortages of biological hearts and kidneys limit the addressable patient pool for total artificial heart systems relative to bridge-to-transplant devices.
Strategic Opportunities
- Home-based dialysis configurations:Portable hemodialysis systems are creating new reimbursement categories in Medicare Advantage and German statutory health insurance frameworks.
- Bioelectronics-tissue engineering convergence:3D-printed scaffolds with embedded microelectrode arrays are opening retinal implant applications previously excluded by geometric constraints.
- Veteran Affairs centralized procurement:The US Department of Veterans Affairs is consolidating limb prosthetics purchasing through single-source indefinite-delivery contracts, favoring suppliers with modular product architectures.
Industry Challenges
- Cybersecurity validation for connected bionics:FDA guidance on wireless telemetry security in cochlear implants and neurostimulators requires specialized firmware engineering talent scarce among traditional device manufacturers.
- Multi-jurisdiction quality management system audits:Simultaneous ISO 13485 surveillance by notified bodies in Europe, FDA inspections in the US, and PMDA document reviews in Japan strain regulatory affairs bandwidth at mid-scale OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Organs and Bionics Market |
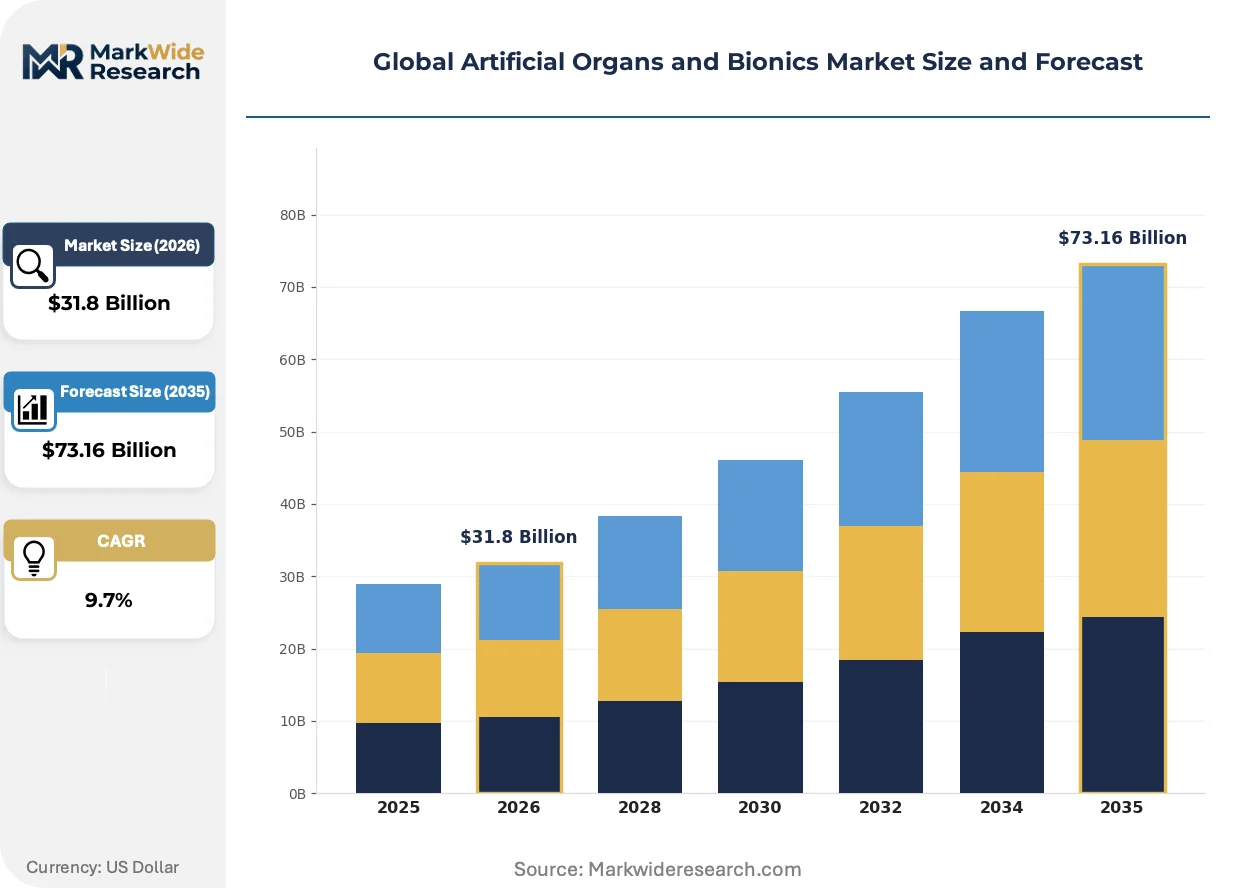
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $73.16 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Hearts, Cochlear Implants, Retinal Implants, Prosthetic Limbs, Dialysis Machines, Neurostimulators Technology: Biocompatible Polymers, Microelectromechanical Systems, Nanotechnology, Bioelectronics, 3D Printing, Tissue Engineering Application: Cardiac Replacement, Hearing Restoration, Vision Enhancement, Limb Replacement, Renal Support, Neuromodulation End User: Specialized Clinics, Rehabilitation Centers, Research Facilities, Veteran Care Centers, Elder Care Facilities, Biomedical Labs |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Zimmer Biomet Holdings Inc., Edwards Lifesciences Corporation, Abiomed Inc., Cochlear Ltd., Ekso Bionics Holdings Inc., Berlin Heart GmbH, Jarvik Heart Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Organs and Bionics Market Shifts & Advancements
Convergence between microelectromechanical systems and additive manufacturing is compressing development timelines for sensory restoration devices while regulatory bodies scramble to adapt premarket approval frameworks to iterative hardware-software platforms.
Bioresorbable electronic scaffolds that monitor tissue integration post-implantation are rendering obsolete the traditional two-stage explant-revision protocols for orthopedic and cardiac applications. Academic medical centers in Switzerland and Massachusetts are piloting these platforms in spinal fusion and sternal closure procedures, collapsing the feedback loop between implantation and functional assessment from months to days.
Europe's MDR transition deadline enforcement is redistributing commercialization resources toward Class III active implantable dossier remediation at the expense of pipeline expansion. Manufacturers are withdrawing legacy neurostimulator SKUs rather than absorbing clinical evidence costs, narrowing the product mix available to French and Italian implant centers and accelerating portfolio consolidation among firms with pre-existing PMCF study infrastructure.
Hospital buying committees are unbundling after-sales service contracts from device procurement, forcing OEMs to compete on discrete service line pricing for programming, calibration, and battery replacement. This disaggregation is most pronounced in German university hospitals and US academic medical centers, where specialized electrophysiology labs now source technical support from third-party clinical engineering firms rather than manufacturer captive service organizations.
Global Artificial Organs and Bionics Market Segmentation
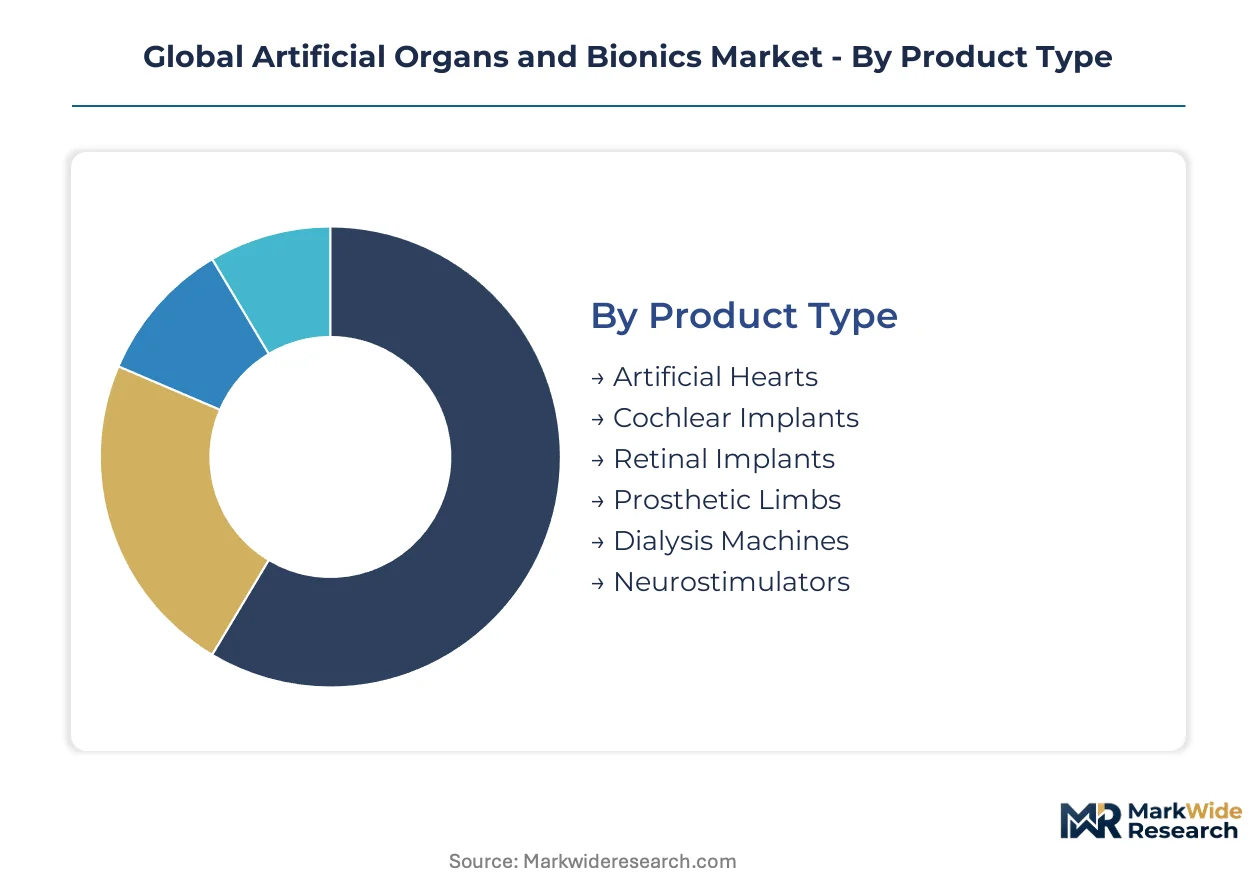
Segmentation in artificial organs and bionics reveals divergent service economics across implantable versus external device categories. After-sales intensity varies sharply—neurostimulators and cochlear implants demand chronic programming support, while dialysis machines concentrate margin in consumables and technical maintenance contracts.
Product Type:
After-sales-service intensity separates implantable devices from capital equipment, with battery replacement cycles and firmware updates creating recurring revenue streams that external devices cannot replicate.
- Artificial Hearts:Titanium-alloy ventricular assist systems and total artificial hearts incorporate transcutaneous power transfer and continuous-flow impeller designs. Demand clusters in German university hospitals following EMA MDR streamlining, with bridge-to-transplant configurations dominating over destination therapy due to donor organ queue dynamics.
- Cochlear Implants:Multi-channel electrode arrays with osseointegrated receiver-stimulators restore speech perception through processor-external microphone pairs. Surgical volume concentrates in Tokyo-Osaka specialty clinics leveraging METI accelerated reimbursement, while UK implant centers drive direct-to-center procurement efficiency.
- Retinal Implants:Epiretinal microelectrode arrays with wireless power and data transmission.
- Prosthetic Limbs:Microprocessor-controlled knees and myoelectric upper-extremity systems with socket-suspension optimization.
- Dialysis Machines:Hemodialysis and peritoneal systems with volumetric ultrafiltration control.
- Neurostimulators:Deep brain and spinal cord stimulators with rechargeable pulse generators.
By volume, Dialysis Machines leads. By growth pace, Retinal Implants is ahead.
Technology:
Cost tier stratification separates mature polymer processing from emerging bioelectronic fabrication, with MEMS foundry capacity constraining mid-tier OEM expansion.
- Biocompatible Polymers:Silicone elastomers and fluoropolymers for encapsulation and lead insulation.
- Microelectromechanical Systems:Silicon-based sensors and actuators for pressure and inertial measurement in implantable contexts.
- Nanotechnology:Surface modification and drug-eluting coatings for thromboresistance.
- Bioelectronics:Organic semiconductors and conductive polymers for tissue-electrode interfaces.
- 3D Printing:Patient-specific titanium lattice structures and polymer sockets.
- Tissue Engineering:Decellularized scaffolds and bioreactor-cultured constructs for organoid development.
Biocompatible Polymers command the largest installed base. Bioelectronics exhibits the steepest expansion trajectory.
Application:
Customer type fragmentation distinguishes acute hospital episodes from chronic disease management, with reimbursement codes determining addressable patient pools per indication.
- Cardiac Replacement:Mechanical circulatory support for end-stage heart failure.
- Hearing Restoration:Sensorineural loss intervention through cochlear and auditory brainstem implants.
- Vision Enhancement:Retinal prostheses and cortical implants for degenerative blindness.
- Limb Replacement:Upper and lower extremity prosthetics with targeted muscle reinnervation.
- Renal Support:Extracorporeal and peritoneal blood purification for ESRD.
- Neuromodulation:Electrical modulation for movement disorders, epilepsy, and chronic pain.
Renal Support generates the highest procedure volume. Vision Enhancement is climbing the fastest.
End User:
Supply concentration in veteran care procurement creates single-source contract opportunities distinct from fragmented academic medical center purchasing.
- Specialized Clinics:Electrophysiology and implantable device centers with dedicated surgical volume.
- Rehabilitation Centers:Prosthetic fitting and gait training facilities.
- Research Facilities:Preclinical and first-in-human trial sites.
- Veteran Care Centers:US Department of Veterans Affairs consolidated limb prosthetics purchasing.
- Elder Care Facilities:Long-term care settings with dialysis and mobility support.
- Biomedical Labs:Biocompatibility testing and regulatory submission support.
Specialized Clinics absorb the greatest device throughput. Veteran Care Centers are gaining share fastest through centralized procurement reform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography, while EMA Medical Device Regulation classification and Japan's PMDA standards fragment multi-region launch strategies for active implantable manufacturers.
United States
Veteran Affairs centralized procurement and Medicare Advantage reimbursement expansion drive demand for limb prosthetics and home-based dialysis configurations. FDA cybersecurity guidance for wireless telemetry in neurostimulators and cochlear implants shapes firmware engineering requirements. Boston and Minneapolis-St. Paul clusters concentrate electrophysiology labs and cardiac device manufacturing.
Germany
University hospital procurement of ventricular assist devices accelerates following EMA MDR streamlining for active implantable conformity assessments. German statutory health insurance frameworks create new reimbursement categories for portable hemodialysis systems. Berlin and Aachen implant centers concentrate surgical volume for mechanical circulatory support.
Japan
Tokyo-Osaka specialty clinics concentrate neurostimulator surgical volume under METI accelerated national health insurance listing. PMDA biocompatibility testing standards diverge from FDA and EMA protocols, extending submission timelines for multi-region OEMs. Osaka-based manufacturing clusters supply lithium-ion power units for implantable devices.
United Kingdom
Direct-to-implant-center distribution efficiency drives cochlear implant procurement through National Health Service contracting frameworks. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel submission requirements for active implantable devices. London and Manchester academic medical centers pilot bioresorbable electronic scaffolds for spinal fusion.
Australia
TGA biocompatibility testing protocols fragment with PMDA and FDA standards, complicating multi-region dossier preparation for mid-scale OEMs. Cochlear Ltd. anchors direct-to-center distribution networks across Sydney and Melbourne implant facilities. Veteran care procurement reforms concentrate limb prosthetics purchasing through single-source contracts.
Global Artificial Organs and Bionics Market Competitive Landscape
Diversified cardiovascular conglomerates and specialized neuromodulation players split the market between full-stack regulatory dossier capabilities and focused electrophysiology platforms. The vendor base concentrates around manufacturers with pre-existing PMCF study infrastructure and captive service organizations. Three archetypes dominate: integrated delivery network suppliers with multi-jurisdiction quality management systems, modular prosthetics specialists serving veteran procurement channels, and MEMS foundry-dependent sensory restoration device makers. Competitive moves center on portfolio consolidation to absorb legacy SKU remediation costs and unbundling of after-sales service contracts to compete on discrete technical support pricing.
Within the diversified cardiovascular tier, Medtronic plc and Edwards Lifesciences Corporation exemplify integrated delivery network suppliers with full-stack regulatory dossiers across FDA, EMA, and PMDA jurisdictions. Cochlear Ltd. occupies a position representing specialized sensory restoration players with direct-to-implant-center distribution architectures in Australia and the United Kingdom. Boston Scientific Corporation anchors the neuromodulation and electrophysiology specialist archetype competing on programming-intensive service line differentiation.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Zimmer Biomet Holdings Inc. |
| Edwards Lifesciences Corporation |
| Abiomed Inc. |
| Cochlear Ltd. |
| Ekso Bionics Holdings Inc. |
| Berlin Heart GmbH |
| Jarvik Heart Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian lithium-ion cell production for implantable device power units compresses pricing tier spreads between premium neurostimulator configurations and standard dialysis equipment while forcing OEMs to absorb raw material allocation volatility through inventory buffers or contract escalation clauses.
Pricing Analysis
Customization-premium spreads separate patient-specific 3D-printed titanium lattice prosthetics from catalog-configured cochlear implant systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and firmware update entitlements rather than hardware specifications alone. Price differentiation hinges on ISO 13485 certification tier and captive programming support availability. Cost compression in mid-tier ventricular assist devices is intensifying because hospital buying committees now unbundle technical service contracts from device procurement. Academic medical centers in Germany and the United States exhibit highest price sensitivity due to statutory budget caps, while Tokyo-Osaka specialty clinics show lowest sensitivity under METI accelerated reimbursement pathways.
Supply Chain Analysis
Contract-manufacturing concentration for MEMS sensors and microelectrode arrays sits with Taiwan-based foundries and Massachusetts academic fabrication facilities. Geographic supply concentration clusters in Japan for lithium-ion power cells, Switzerland for precision titanium machining, and Germany for polymer encapsulation materials. Raw material dependencies draw from rare earth elements for magnetic components in neurostimulator pulse generators, medical-grade silicone elastomers for lead insulation, and bioactive ceramics for osseointegrated interfaces. Single-source vulnerability in East Asian battery chemistry exposes OEMs to export restriction risk. Distribution runs through direct-to-implant-center channels for cochlear and retinal devices, contrasting with GPO-aggregated procurement for dialysis capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial organs and bionics markets reward service-attach economics where chronic programming support for neurostimulators and cochlear implants expands recurring revenue faster than hardware replacement cycles.
For Market Incumbents: Entrench position through captive firmware engineering capabilities addressing FDA cybersecurity guidance for wireless telemetry, while consolidating vendor lists at integrated delivery networks to exclude mid-scale competitors lacking multi-jurisdiction quality management systems. Absorb legacy SKU remediation costs ahead of EMA MDR transition deadlines to accelerate portfolio consolidation. Vertical integration into MEMS foundry capacity insulates against Taiwan supply concentration risk. For New Entrants and Emerging Players: Geographic underpenetration in Australian veteran care procurement channels offers white-space entry through modular prosthetic architectures qualifying for single-source indefinite-delivery contracts. Portable hemodialysis configurations in Medicare Advantage plans represent the most penetrable reimbursement category. Target German statutory health insurance frameworks with home-based renal support systems leveraging existing technical maintenance infrastructure. For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors acquisition targets with pre-existing PMCF study infrastructure and captive clinical engineering service organizations. Long-term viability over the next decade rests on outcome-based payment model readiness and software-hardware platform iteration capabilities. Watch for FDA premarket approval pathway streamlining for bioresorbable electronic scaffolds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR streamlining accelerates conformity assessment for active implantable devices in German university hospitals. |
| Hospital System Partnership | Direct-to-implant-center distribution with NHS contracting frameworks secures cochlear implant volume in the United Kingdom. |
| Software Companion Development | Firmware updates for wireless telemetry security address FDA guidance and create recurring revenue attachment. |
| Reimbursement Strategy | METI accelerated national health insurance listing concentrates neurostimulator surgical volume in Tokyo-Osaka specialty clinics. |
| FDA Submission | Premarket approval for bioresorbable electronic scaffolds collapses feedback loops between implantation and functional assessment. |
Research Methodology
A spread of perspectives from cardiac surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers converged on the working assumptions through structured primary interviews validated against secondary sources including FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up triangulation across implant procedure volumes and top-down validation against manufacturer revenue disclosures anchored segmentation estimates.
Demand-supply-balance framing modeled patient eligibility pools against manufacturing capacity constraints across the analysis window. Segmentation dimensions included product type, technology platform, application indication, and end-user facility category. CAGRs were derived from procedure volume trajectories and average selling price evolution. Forecast inputs incorporated regulatory approval timelines and reimbursement pathway acceleration effects.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified cardiovascular conglomerates or MEMS foundry-dependent entrants would shift outcomes through accelerated portfolio consolidation or supply chain vertical integration. Quarterly review of FDA cybersecurity guidance implementation and EMA MDR transition compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Devices Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Medical Polyetheretherketone Market