
 Marshmallow Market | 2026-2036
Marshmallow Market Size, Share, and Industry Trends Forecast 2026-2036
Marshmallow Market Analysis
Confectionery process engineering talent is collapsing across Midwestern US manufacturing corridors, tightening production capacity for extruded and deposited marshmallow formats. Kraft Heinz leverages its integrated corn syrup and gelatin supply chains to sustain volume leadership in private-label and branded channels. Doumak specializes in seasonal and private-label contract manufacturing, occupying a defensible niche in holiday-themed marshmallow shapes. Campfire Marshmallows anchors the outdoor and s'mores occasion segment through dominant retail placement in camping and grocery channels.
Marshmallow denotes a aerated confection produced by whipping hydrolyzed gelatin or plant-based alternatives with sucrose or glucose syrup to specific densities, then setting the foam through controlled cooling to achieve a stable cellular structure between 0.2 and 0.4 grams per cubic centimeter. The primary commercial purpose centers on providing textural contrast, moisture retention, and visual appeal across baked goods, hot beverages, and ready-to-eat snacks. Gourmet and mini formats lead value expansion as bakeries and specialty cafés trade up from commodity fluff, while marshmallow fluff maintains volume dominance in institutional baking and ice cream manufacturing where cost-per-ounce governs procurement decisions.
FDA food additive regulations and USDA organic certification requirements shape gelatin sourcing, sweetener labeling, and clean-claim eligibility for domestic producers, while EFSA sweetener guidance and REACH chemical compliance govern European import specifications and reformulation timelines. Stakeholders must monitor plant-based collagen alternatives and precision fermentation-derived proteins as these technologies force decisions on capital allocation between traditional gelatin infrastructure and next-generation ingredient platforms.
Market Dynamics
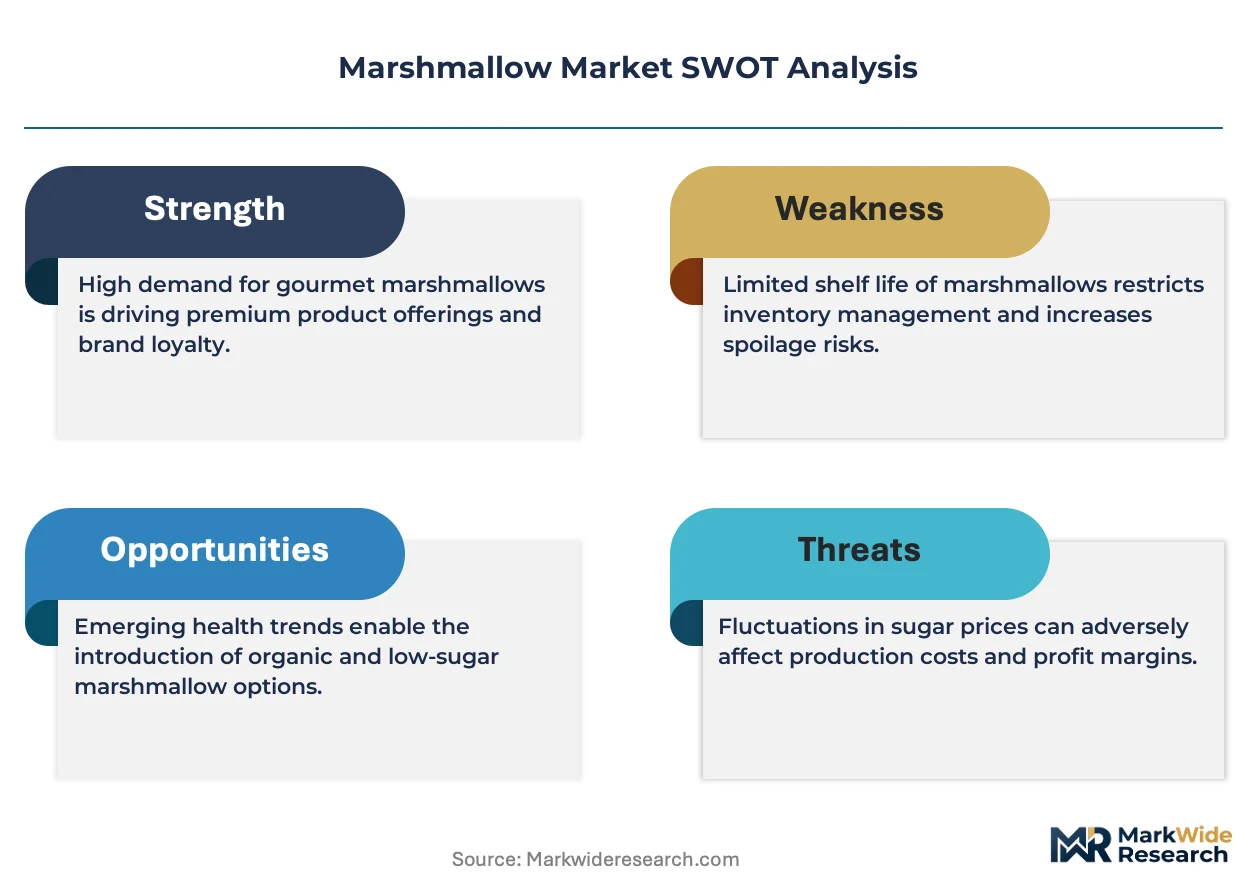
Clean-label reformulation mandates from FDA and EFSA are compressing formulation timelines and forcing capital reallocation from traditional gelatin infrastructure toward plant-based collagen alternatives and precision fermentation-derived proteins.
Growth Catalysts
- EFSA Sweetener Guidance:European importers accelerate reformulation to meet clean-claim eligibility, opening premium positioning for natural sweetener formulations in continental retail channels.
- Food Service Operators:Gourmet marshmallow adoption accelerates among specialty cafés and bakeries trading up from commodity fluff to mini and artisan formats for visual differentiation.
- Camping and Outdoor Retail:Seasonal demand concentration in s'mores occasions drives volume guarantees through dominant grocery placement during peak summer months.
Market Restraints
- Gelatin Input Volatility:Bovine and porcine collagen prices fluctuate with livestock feed costs and rendering capacity constraints in Midwestern US processing corridors.
- REACH Chemical Compliance:European import specifications create documentation friction and extended timeline risk for reformulated products seeking market entry.
- Plant-Based Substitutes:Aquafaba and agar-agar formulations displace conventional marshmallows in vegan bakery applications, eroding addressable volume in institutional segments.
Strategic Opportunities
- USDA Organic Certification:Domestic producers capturing clean-claim eligibility command shelf-space premiums in natural channel retail and food service procurement.
- Precision Fermentation:Microbial collagen production converges with extrusion technology to eliminate animal-derived inputs while maintaining cellular structure density specifications.
- Specialty Pharmacy and Clinical Nutrition:Textural modification applications in dysphagia-friendly foods open reimbursement-adjacent demand in institutional healthcare feeding programs.
Industry Challenges
- Confectionery Process Engineering Talent:Collapsing expertise in extruded and deposited formats across Midwestern manufacturing corridors tightens production capacity expansion feasibility.
- FDA Food Additive Petition Timelines:Novel protein ingredient approvals extend 18-24 months, delaying clean-label product launches beyond competitive windows.
- Legacy Equipment Retrofit Costs:Transitioning from gelatin-based to plant-based foam stabilization requires cooling tunnel reconfiguration and whip speed recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marshmallow Market |
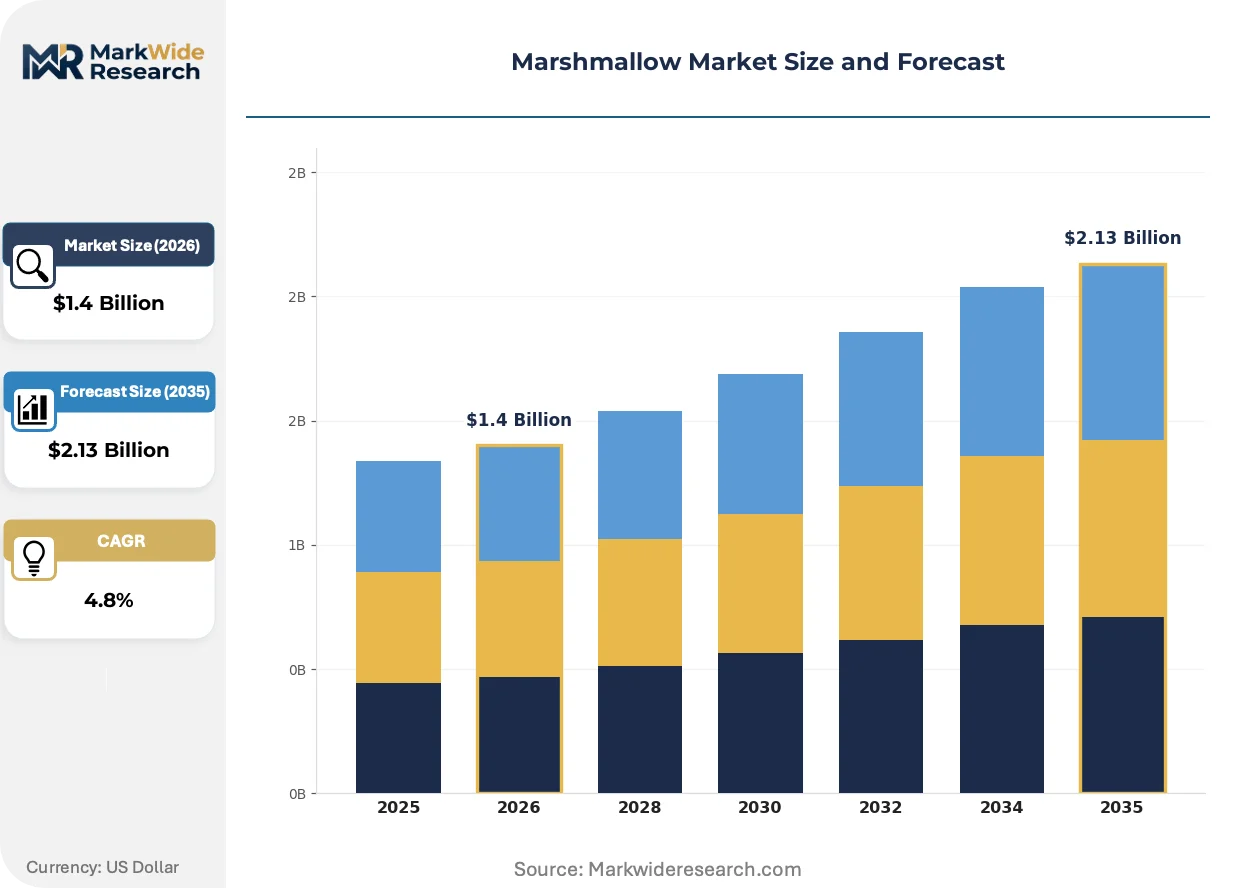
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Mini, Gourmet, Marshmallow Fluff End User: Retail Consumers, Food Service, Confectioneries, Bakeries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Application: Snack Foods, Baking, Toppings, Desserts |
| Companies Covered | Kraft Heinz, Doumak, Just Born, Mondelez International, General Mills, Dandies Marshmallow, Stuffed Puffs, Campfire Marshmallows, Hammond’s Candies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marshmallow Market Emerging Trajectories
Active reformulation is compressing ingredient supply chains while precision fermentation and miniaturized formats reshape competitive positioning across premium and mass-market tiers.
Aerated confection engineering is miniaturizing through controlled-density micro-marshmallow formats designed for hot beverage suspension and baked good integration. Specialty roasters and boutique bakeries in Portland, Brooklyn, and Austin adopt sub-1-centimeter specifications at accelerated procurement cycles. This miniaturization enables textural layering previously impossible with standard sizing, compressing per-unit ingredient costs while expanding application versatility across dessert menus.
REACH chemical compliance mandates now govern European import specifications for hydrolyzed protein additives and processing aids in aerated confections. Industrial consequence includes mandatory substance registration and safety data documentation extending reformulation timelines 8-14 months. German and Dutch importers respond by pre-qualifying alternative gelatin sources and accelerating plant-based collagen trials to de-risk supply continuity.
Certification-driven preference rotation is displacing conventional procurement criteria in food service channels. Clean-label eligibility now governs bakery and café supplier selection ahead of cost-per-ounce metrics, with USDA Organic and Non-GMO Project verification becoming table stakes for national chain consideration. This rotation concentrates demand among domestic producers with captive organic corn syrup and certified gelatin supply chains, visible most acutely in Pacific Northwest and New England regional markets where consumer scrutiny intensifies.
Marshmallow Market Segmentation
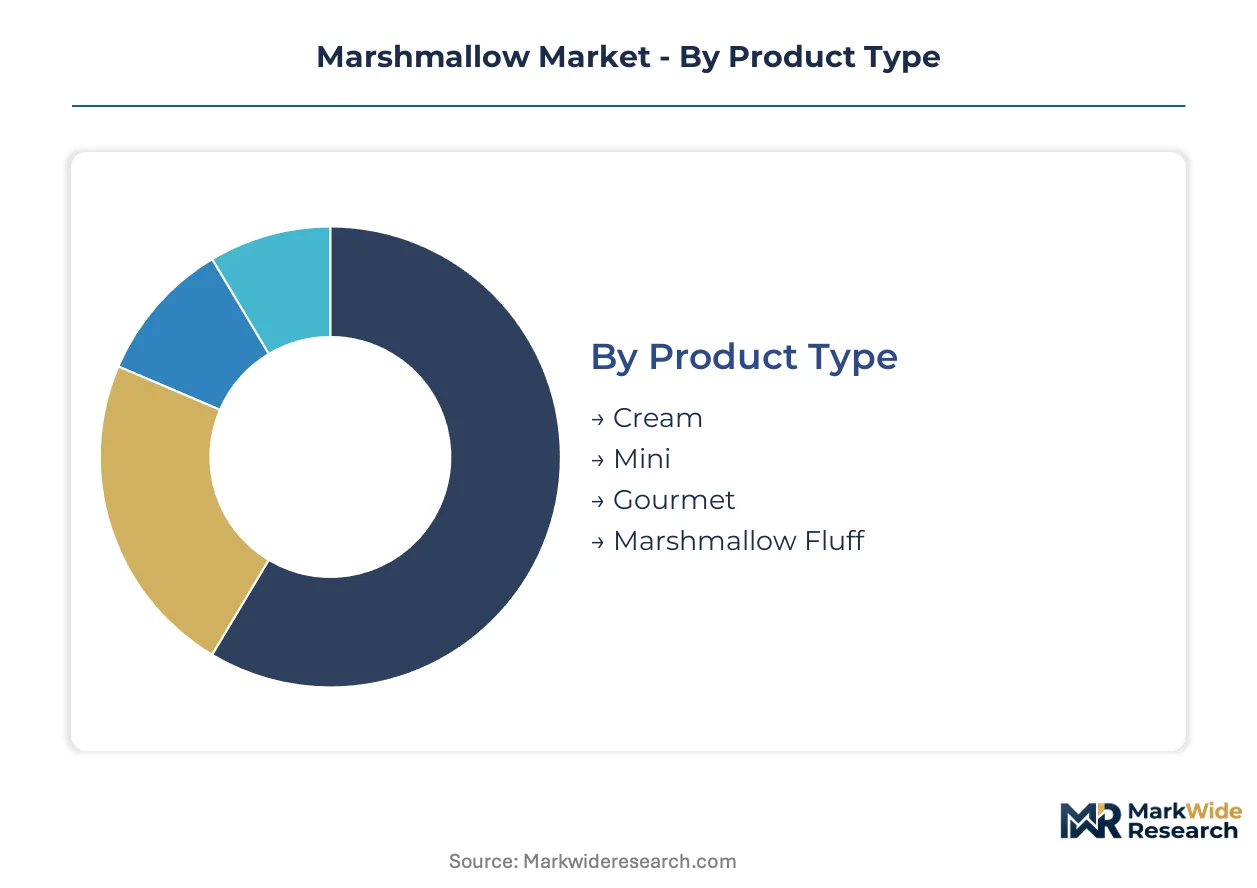
Marshmallow demand fragments across four distinct classification axes, each governing procurement logic and margin capture differently. Product format determines production technology requirements and shelf-stability economics. End-user concentration shapes volume contracting terms and reformulation urgency.
Product Type:
Mini and Gourmet formats concentrate demand in domestic craft confectionery corridors and Pacific Northwest specialty retail. Cream and Fluff variants anchor institutional baking procurement with cost-per-ounce governing supplier selection.
- Mini:Sub-1-centimeter specifications enable hot beverage suspension and baked good textural layering. Specialty roasters in Portland and Brooklyn accelerate procurement cycles for controlled-density micro-formats that compress per-unit ingredient costs while expanding menu versatility.
- Gourmet:Artisan formulations with natural sweeteners and clean-label certification command shelf-space premiums in natural channel retail. Domestic producers with captive organic corn syrup supply chains capture food service procurement from specialty cafés trading up from commodity alternatives.
- Cream:Aerated confection with higher moisture content serves ice cream manufacturing and dessert filling applications where spreadability governs functional selection.
- Marshmallow Fluff:Spreadable emulsion dominates institutional baking and manufacturing procurement where cost efficiency outweighs textural complexity requirements.
Mini and Gourmet formats concentrate the steepest expansion trajectory. Marshmallow Fluff commands the established volume base.
End User:
Food service and bakery procurement is rotating toward clean-label eligibility ahead of cost metrics, concentrating demand among certified domestic suppliers. Retail consumer purchasing fragments across impulse, seasonal, and pantry-stocking occasions with distinct channel preferences.
- Food Service:Specialty cafés and boutique bakeries in Austin and Brooklyn trade up to artisan formats for visual differentiation on dessert menus. USDA Organic certification is becoming table stakes for national chain supplier qualification.
- Retail Consumers:Seasonal demand spikes around summer camping occasions drive s'mores-format volume guarantees through dominant grocery placement.
- Confectioneries:Handmade and small-batch producers in regional markets source premium gelatin and natural colorants for gift and specialty occasions.
- Bakeries:Commercial and artisan baking operations procure mini formats for cupcake decoration and textural contrast in pastry applications.
Food Service is gaining share fastest through certification-driven preference rotation. Retail Consumers anchor the volume foundation.
Distribution Channel:
Supermarket and wholesale concentration in Midwestern manufacturing corridors reflects legacy supply chain configurations. Online and specialty retail expansion is reshaping geographic reach for premium and seasonal formats.
- Supermarkets:Dominant retail placement during peak summer months secures volume guarantees for s'mores occasion marketing. Campfire and seasonal private-label contracts concentrate shelf space in camping and grocery channels.
- Specialty Stores:Natural channel retail in Pacific Northwest and New England regional markets intensifies consumer scrutiny of ingredient sourcing and certification claims.
- Online Retail:Direct-to-consumer and marketplace platforms enable artisan producers to bypass traditional distribution markups and reach geographically dispersed gourmet buyers.
- Wholesalers:Institutional baking and ice cream manufacturing procurement runs through food service distributors where cost-per-ounce and volume reliability govern supplier relationships.
Supermarkets command the established base. Specialty Stores are expanding most quickly through clean-label preference concentration.
Application:
Baking and dessert applications drive reformulation urgency as clean-label mandates compress formulation timelines. Snack food integration is emerging through textural layering innovations in bar and cluster formats.
- Baking:Cupcake decoration, brownie inclusions, and pastry fillings demand consistent cellular structure density between 0.2 and 0.4 grams per cubic centimeter. Commercial bakeries prioritize volume reliability and whip stability across production batches.
- Desserts:Artisan plating and composed dessert applications in fine dining and specialty cafés favor mini and gourmet formats for visual precision and flavor pairing flexibility.
- Snack Foods:Bar, cluster, and trail mix inclusions leverage mini formats for textural contrast without moisture migration issues in shelf-stable packaging.
- Toppings:Hot chocolate and beverage applications require rapid dissolution properties and suspension stability in liquid matrices.
Baking commands the established application base. Desserts are climbing the fastest through gourmet format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clean-label mandates and USDA organic certification requirements anchor United States market dynamics, while EFSA sweetener guidance and REACH chemical compliance reshape European procurement patterns. Domestic producers with captive supply chains capture premium positioning as certification-driven preference rotation intensifies across food service channels.
United States
Craft confectionery culture in Portland and Brooklyn drives gourmet marshmallow adoption among specialty cafés and boutique bakeries. FDA food additive regulations compress formulation timelines for novel protein ingredients, extending approval windows 18-24 months. Midwestern manufacturing corridors face collapsing confectionery process engineering talent, tightening production capacity for extruded and deposited formats.
Germany
German importers accelerate reformulation to meet EFSA clean-claim eligibility, opening premium positioning for natural sweetener formulations. REACH chemical compliance mandates mandatory substance registration and safety data documentation, extending reformulation timelines 8-14 months. Industrial clusters in North Rhine-Westphalia pre-qualify alternative gelatin sources and accelerate plant-based collagen trials to de-risk supply continuity.
United Kingdom
Specialty roasters in London adopt sub-1-centimeter mini specifications for hot beverage suspension and baked good textural layering. EFSA sweetener guidance governs import specifications for hydrolyzed protein additives in aerated confections. Regional markets in Scotland and Northern England intensify consumer scrutiny of ingredient sourcing and certification claims through natural channel retail expansion.
France
French confectioneries source premium gelatin and natural colorants for gift and specialty occasion marshmallow production. ANSM labeling mandates intersect with EFSA guidance to reshape clean-label eligibility for continental retail channels. Île-de-France and Auvergne-Rhône-Alpes industrial zones concentrate artisan baking procurement from certified domestic suppliers.
Canada
Health Canada and PMRA regulations govern sweetener labeling and food additive approvals for domestic marshmallow manufacturing. Seasonal demand concentration around summer camping occasions drives s'mores-format volume guarantees through dominant grocery placement. Ontario and Quebec food service distributors prioritize USDA Organic and Non-GMO Project verification for national chain supplier qualification.
Marshmallow Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the marshmallow market structure. Consolidated volume positions in private-label and branded channels coexist with fragmented artisan and seasonal specialty production. Three archetypes dominate: integrated conglomerates with captive supply chains, contract manufacturers specializing in seasonal shapes, and craft confectioners leveraging clean-label certification for premium positioning. Competitive moves concentrate on backward integration into corn syrup and gelatin supply chains, alongside cooling tunnel reconfiguration for plant-based foam stabilization.
Among integrated food conglomerates, Kraft Heinz anchors volume leadership through supply chain control, while Doumak occupies contract manufacturing specialization in holiday-themed formats. Campfire Marshmallows exemplifies occasion-segment dominance through retail placement in camping and grocery channels. These three represent distinct competitive archetypes: upstream-integrated scale, seasonal contract flexibility, and occasion-based channel capture.
| Leading Market Players |
|---|
| Kraft Heinz |
| Doumak |
| Just Born |
| Mondelez International |
| General Mills |
| Dandies Marshmallow |
| Stuffed Puffs |
| Campfire Marshmallows |
| Hammond's Candies |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for Midwestern corn syrup and gelatin lock in both supply access and price visibility for domestic producers, insulating volume leaders from livestock feed cost volatility while compressing margin flexibility for spot-market buyers facing bovine collagen price swings.
Pricing Analysis
Domestic price spreads widen between certified organic supply corridors in the Pacific Northwest and commodity-grade production in Midwestern manufacturing zones. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price differentiation stems from USDA Organic and Non-GMO Project verification premiums in food service procurement. Cost compression in institutional fluff segments is intensifying because gelatin input volatility feeds through rendering capacity constraints. Commercial bakeries exhibit highest price sensitivity; specialty cafés in Portland and Brooklyn show least sensitivity due to menu premiumization strategies.
Supply Chain Analysis
Midwestern US rendering corridor chokepoints tether gelatin supply to livestock processing capacity and seasonal feed cost cycles. Supply concentrates in United States corn belt regions, Brazilian tallow export zones, and European porcine collagen processing hubs. Raw material dependencies center on hydrolyzed bovine and porcine collagen, organic corn syrup, and natural sweetener alternatives. Single-source vulnerability runs through concentrated Midwestern rendering facilities serving multiple confectionery manufacturers. Distribution runs through food service distributors for institutional baking, direct-to-retail for camping occasion formats, and natural channel brokers for certified organic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marshmallow market sits in early-cycle recovery as camping and outdoor recreation demand rebounds from pandemic-era disruptions, with s'mores occasion volume guarantees restoring predictable seasonal contracting patterns.
For Market Incumbents: Consolidate backward integration into captive organic corn syrup supply chains to defend margin position against gelatin input volatility. Lock in long-term offtake agreements with Midwestern rendering facilities before capacity constraints tighten further. Prioritize cooling tunnel reconfiguration capex to enable plant-based foam stabilization trials ahead of FDA food additive petition timelines for precision fermentation proteins.
For New Entrants and Emerging Players: Differentiate on clean-label certification density by pursuing simultaneous USDA Organic and Non-GMO Project verification to bypass commodity fluff competition. Target specialty pharmacy and clinical nutrition applications for dysphagia-friendly textural modifications where reimbursement-adjacent demand offers pricing power. Penetrate Pacific Northwest and New England natural channel retail through direct-store-delivery relationships with independent grocers.
For Investors and Strategic Acquirers: Capital is best deployed toward craft confectioners with established clean-label certification and regional brand equity in underconsolidated gourmet segments. Long-term viability across the next decade hinges on successful transition from gelatin-dependent infrastructure to precision fermentation-compatible production platforms. Monitor FDA food additive petition approvals for novel protein ingredients as the critical inflection signal for capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Corn Syrup | Captive supply chains insulate Kraft Heinz and integrated players from commodity price swings. |
| Cooling Tunnel Reconfiguration | Equipment retrofit enables plant-based foam stabilization without sacrificing cellular density specifications. |
| Precision Fermentation Protein Trials | Microbial collagen production eliminates animal-derived inputs while meeting EFSA clean-claim eligibility. |
| Specialty Pharmacy Channel Entry | Dysphagia-friendly formats open reimbursement-adjacent demand in institutional healthcare feeding programs. |
| Direct-to-Consumer Platform Launch | Artisan producers bypass traditional distribution markups to reach geographically dispersed gourmet buyers. |
Methodological Framework
The analysis maps mini and gourmet formats, cream and fluff variants, and specialty pharmacy applications, each validated through confectionery process engineers, food service procurement directors, and natural channel retail buyers. Primary interviews with plant managers at Midwestern manufacturing facilities, category buyers at camping and outdoor retailers, and regulatory affairs specialists at FDA and EFSA intersected with secondary validation from USDA organic certification databases, FDA food additive petition filings, and EFSA sweetener guidance documentation. Bottom-up volume modeling triangulated against top-down category spend estimates from food service distribution data.
Consistency checks validated volume and value outputs against external benchmarks including customs records for gelatin imports, corn syrup production disclosures, and camping goods retail audit data. Segmentation dimensions modeled include product format density specifications, end-user procurement criteria rotation, distribution channel concentration patterns, and application-specific reformulation urgency across the analysis window. CAGRs derived from segment-level growth trajectory analysis incorporating clean-label adoption curves and precision fermentation technology maturation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EFSA clean-label mandate enforcement; material deviation in regulatory timelines or precision fermentation cost curves would warrant model refresh. Practitioners should keep alternative scenarios live as plant-based collagen alternative performance specifications and camping occasion demand cyclicality evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Snacks Market
Snacks
Europe Energy Bar Market
Snacks
Europe Frozen Snacks Market
Snacks
Jerky Snacks Market
Snacks
Italy Energy Bar Market
Snacks
Corn Chips Market
Snacks
Seafood Snacks Market
Snacks
Crackers Market
Snacks
Seaweed Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
Snack Pellets Market
Snacks
Italy Snack Bar Market
Snacks
Europe Snacks Food Market
Snacks
South America Cereal Bar Market
Snacks
North America Baked Chips Market
Snacks
Extruded Snacks Market