
 Low Calorie Snacks Market | 2026-2036
Low Calorie Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Snacks Market Analysis
FDA nutrition labeling reform is broadening the cost-of-entry calculus for new low calorie snack entrants, forcing reformulation investments that favor scaled operators. PepsiCo leverages its Frito-Lay distribution infrastructure to sustain shelf dominance across convenience and club channels. Nestlé anchors its portfolio with specialized nutrition science capabilities that differentiate functional snack lines from commodity alternatives. Mondelez International competes through premium chocolate and biscuit innovations that occupy the intersection of indulgence and portion control.
Low calorie snacks are formulated food products containing reduced caloric density per serving, typically achieved through sugar substitutes, fiber enrichment, fat replacers, or air-puffed processing that maintains texture while cutting energy content. Their primary commercial purpose is to satisfy satiety and taste expectations within controlled energy budgets for weight management and metabolic health applications. Bars lead product type revenue due to portability and protein fortification trends that command premium positioning, while pouches as a packaging format are displacing rigid containers in online channels where shipping economics favor lightweight flexible formats. Specialty stores capture margin concentration through curated assortments targeting fitness enthusiasts and diabetics with certification-driven purchasing behavior.
FDA enforcement of updated serving-size standards and added-sugar disclosure rules shapes formulation pipelines and label claims across the United States. USDA Smart Snacks in School standards and state-level sugar taxes in California and Colorado further constrain permissible product profiles and channel access. Stakeholders must monitor evolving front-of-package scoring systems and state legislative momentum to determine whether portfolio diversification or geographic concentration offers superior risk-adjusted returns.
Market Dynamics
FDA serving-size recalibration and added-sugar disclosure mandates are forcing simultaneous reformulation across protein bars, puffed snacks, and confectionery portfolios, compressing development timelines while elevating R&D spend thresholds for viable market entry.
Growth Catalysts
- USDA Smart Snacks in School:Federal standards for competitive foods in educational institutions channel institutional procurement toward sub-200-calorie portion formats, creating captive demand for compliant manufacturers.
- Air-puffing extrusion technology:Advanced thermal processing expands snack matrices without fat addition, enabling texture parity in reduced-calorie chips and crisps that satisfies sensory expectations.
- Corporate wellness program integration:Fortune 500 employers subsidize low-calorie vending options as metabolic health interventions, converting workplace micro-markets into high-frequency consumption nodes.
Market Restraints
- Allulose supply concentration:Domestic fermentation capacity for this FDA-recognized low-calorie sweetener remains constrained to three North American producers, creating input cost volatility and allocation risk.
- Clean-label certification complexity:Non-GMO Project and Certified Gluten-Free verification timelines extend 14-18 months, delaying product launches and freezing working capital in pipeline inventory.
- Whole-food snack substitution:Fresh-cut vegetables and minimally processed nuts capture perimeter-of-store traffic, eroding center-store shelf space for formulated low-calorie alternatives.
Strategic Opportunities
- Diabetes-focused retail channels:Specialty pharmacies and endocrinology clinic kiosks offer direct access to glycemic-conscious consumers seeking clinically positioned snacking solutions.
- California sugar tax spillover:State-level excise structures on sugar-sweetened beverages create pricing umbrellas that favor reformulated low-calorie adjacent categories in West Coast distribution.
- Flexible packaging automation convergence:Integration of digital printing with form-fill-seal equipment enables micro-batch personalization for direct-to-consumer subscription models.
Industry Challenges
- Sensory scientist scarcity:Formulation expertise at the intersection of flavor chemistry and caloric reduction commands premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Legacy ERP integration friction:New product development platforms for rapid SKU proliferation encounter data architecture conflicts with incumbent manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Snacks Market |
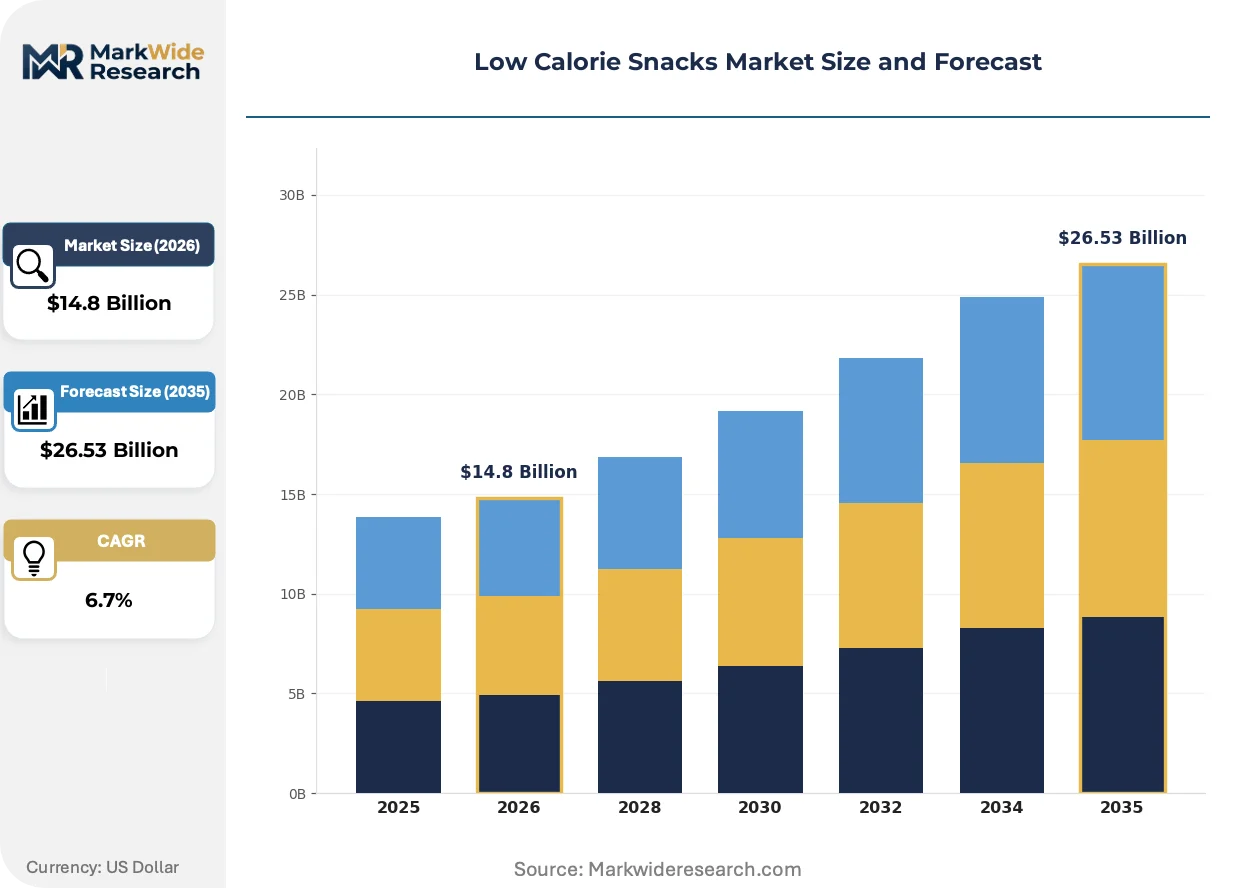
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Chips, Cookies, Crackers Packaging Type: Bags, Boxes, Pouches, Containers Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores Target Audience: Health Conscious Consumers, Fitness Enthusiasts, Diabetics, Weight Watchers |
| Companies Covered | PepsiCo Inc., Mondelez International Inc., Nestlé SA, The Hain Celestial Group Inc., The Kraft Heinz Company, Conagra Brands Inc., General Mills Inc., Cargill Incorporated, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Snacks Market Emerging Trajectories
Reformulation science is converging with packaging engineering and channel-specific distribution economics to compress product development cycles while fragmenting consumption occasions across new eating contexts.
Precision fermentation-derived protein isolates are modularizing ingredient sourcing for low-calorie bars and bites. Sports nutrition and weight-management brands are accelerating adoption of these single-cell proteins to achieve complete amino acid profiles without dairy or soy allergen declarations. This ingredient architecture is modularizing supply chain risk by decoupling protein supply from agricultural commodity cycles.
California and Colorado sugar tax frameworks are creating regulatory patchworks that complicate national SKU strategies. Manufacturers face divergent cost structures and labeling requirements across state lines, forcing either geographic product differentiation or highest-common-denominator formulation. Premium chocolate and indulgence-positioned segments absorb compliance costs through price architecture adjustments.
Direct-to-consumer sampling subscriptions are compressing traditional retail trial pathways. Fitness enthusiasts and diabetic consumers now encounter new low-calorie formats through curated monthly boxes before mass-market shelf presence, reversing the conventional awareness-to-purchase funnel. This pattern concentrates initially in coastal metropolitan markets with elevated health-consciousness indices.
Low Calorie Snacks Market Segmentation
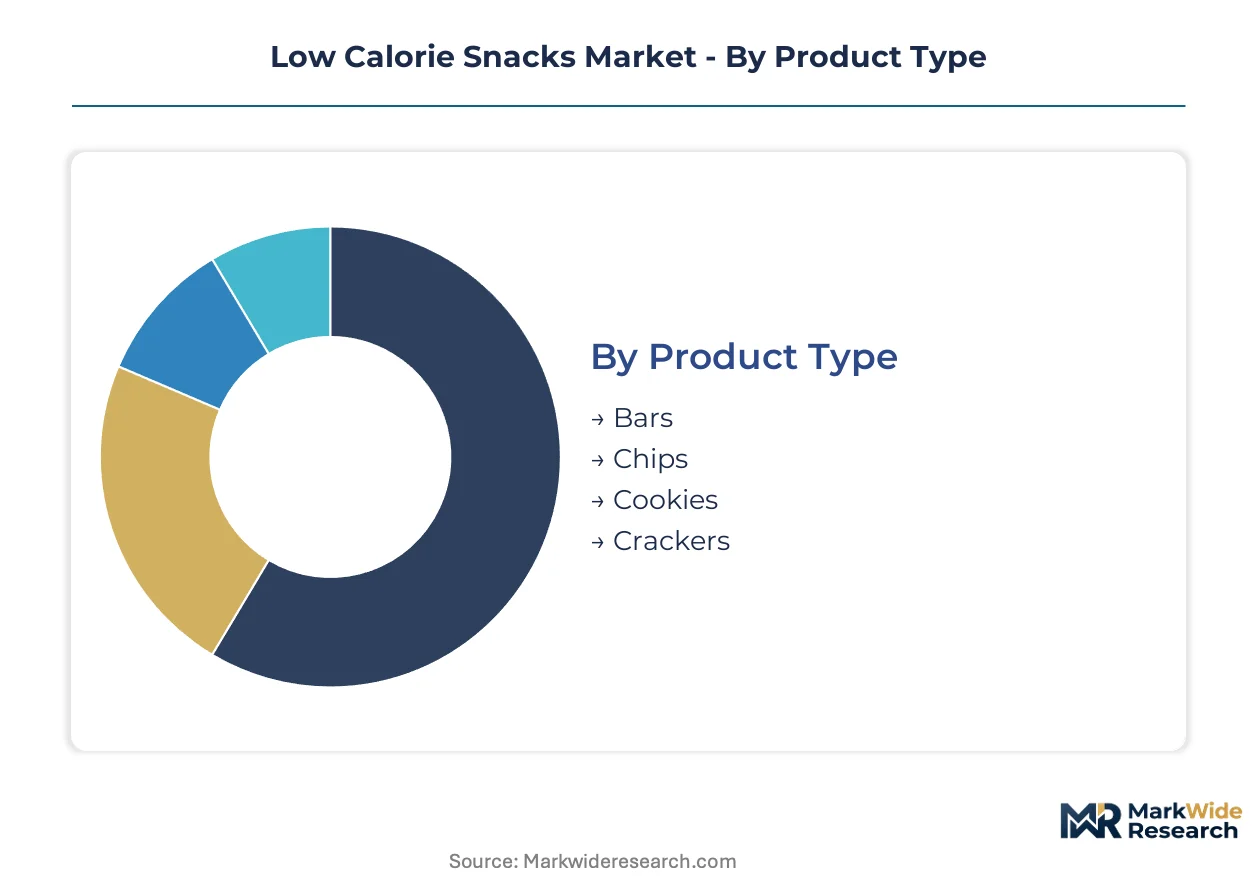
Segmentation in low calorie snacks determines formulation priorities, packaging investments, and channel-specific compliance burdens. Each dimension carries distinct certification requirements that reshape margin structures and competitive entry costs.
Product Type:
FDA added-sugar disclosure rules and USDA Smart Snacks standards impose tiered compliance burdens across formats, with protein-fortified categories facing the most stringent nutrient-content claim verification.
- Bars:Compressed matrices combining protein isolates, fiber syrups, and sugar alcohols achieve sub-200-calorie targets while maintaining structural integrity. Demand concentrates in corporate wellness programs where Fortune 500 employers subsidize portion-controlled options as metabolic health interventions. Allulose supply constraints elevate reformulation costs for mid-tier manufacturers seeking clean-label positioning.
- Chips:Air-puffing extrusion technology expands starch matrices without fat addition, producing texture parity in reduced-calorie crisps. California and Colorado sugar tax spillover effects favor these savory formats in West Coast distribution where reformulated adjacent categories gain pricing umbrellas. Sensory scientist scarcity constrains rapid flavor optimization pipelines.
- Cookies:Sugar substitute integration challenges browning chemistry and moisture retention.
- Crackers:Fermentation-derived protein fortification enables complete amino acid profiles without allergen declarations.
Bars sit at the top of the volume ranking, with chips climbing the fastest.
Packaging Type:
Cost tier differentiation separates premium sustainable formats from economy rigid containers, with mid-tier flexible options capturing channel-specific automation investments.
- Pouches:Lightweight flexible formats displace rigid containers in online channels where shipping economics favor dimensional weight reductions. Digital printing convergence with form-fill-seal equipment enables micro-batch personalization for direct-to-consumer subscription models. Non-GMO Project verification timelines extend working capital cycles for emerging brands.
- Bags:Multi-layer barrier films preserve shelf stability in high-humidity climates without refrigeration infrastructure.
- Boxes:Retail-ready secondary packaging supports club-channel palletization efficiency.
- Containers:Reusable rigid formats target specialty store premium positioning.
Pouches lead volume contribution, with bags gaining share fastest through e-commerce penetration.
Distribution Channel:
Application-driven channel selection determines whether products encounter institutional procurement standards, impulse-purchase velocity constraints, or curated certification requirements.
- Specialty Stores:Curated assortments targeting fitness enthusiasts and diabetics command margin concentration through certification-driven purchasing behavior. Endocrinology clinic kiosks and specialty pharmacies offer direct access to glycemic-conscious consumers seeking clinically positioned solutions. Front-of-package scoring systems create additional labeling complexity for multi-channel SKUs.
- Online:Direct-to-consumer sampling subscriptions compress traditional retail trial pathways, reversing conventional awareness-to-purchase funnels.
- Supermarkets:Center-store shelf space erosion from perimeter-of-store whole-food alternatives intensifies promotion spending.
- Convenience Stores:Grab-and-go occasions favor single-serve portion formats with immediate satiety signaling.
Supermarkets maintain volume leadership, with specialty stores expanding most quickly through diabetes-focused positioning.
Target Audience:
Customer type segmentation aligns formulation science with distinct metabolic requirements and purchasing trigger points across wellness and clinical contexts.
- Diabetics:Glycemic index certification and endocrinology channel placement require specialized nutrient-density calculations beyond standard calorie reduction. Precision fermentation-derived protein isolates enable complete amino acid profiles without dairy or soy allergen concerns that complicate meal planning. State-level sugar tax frameworks create divergent cost structures across geographic markets.
- Fitness Enthusiasts:Protein fortification trends and amino acid completeness drive premium positioning in sports nutrition adjacent categories.
- Health Conscious Consumers:Clean-label preferences intensify competition between established and emerging brands in mass-market channels.
- Weight Watchers:Portion-controlled satiety engineering focuses on energy-density manipulation through air-puffing and fiber enrichment.
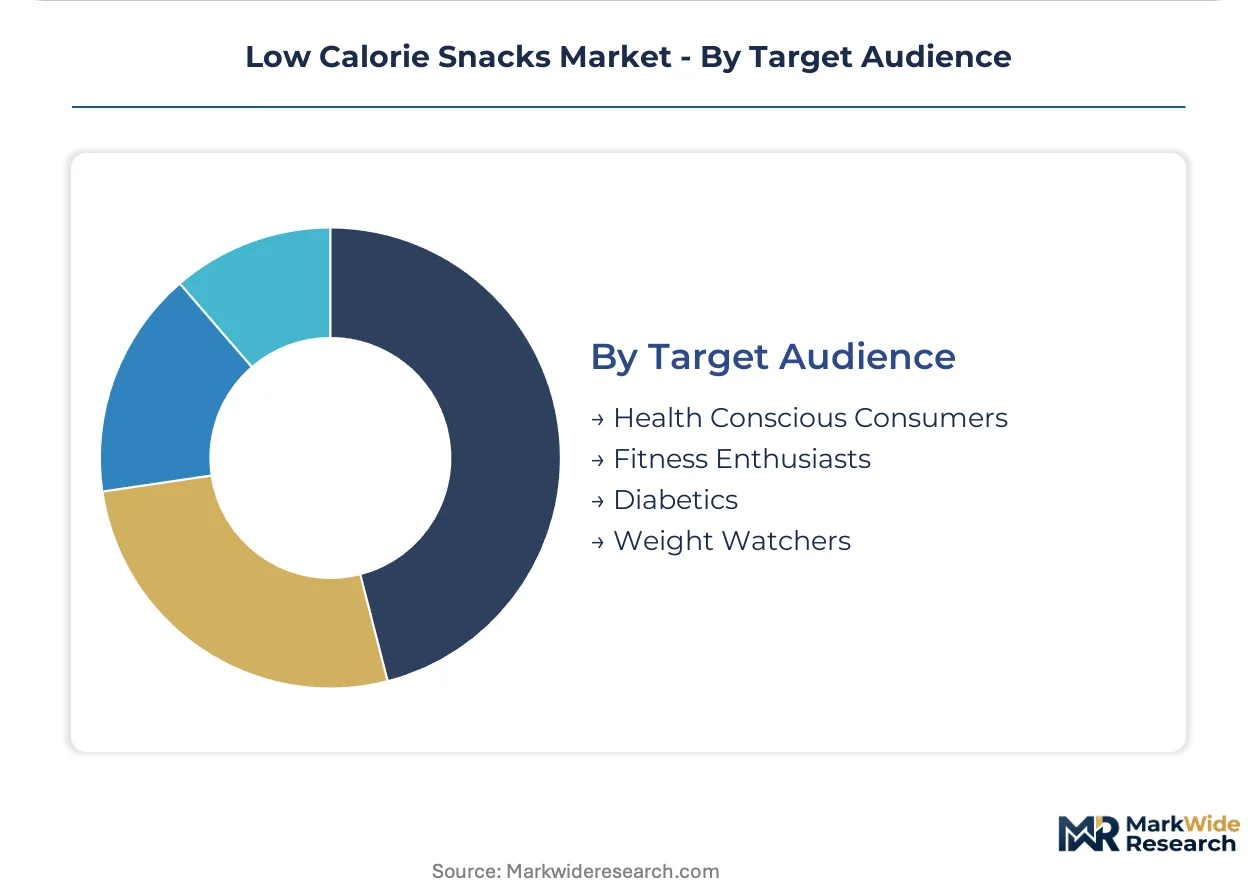
Health conscious consumers represent the largest addressable base, with diabetics following the steepest expansion trajectory through clinical channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientist and formulation specialist talent concentrates in the United States, Germany, and Japan, anchoring the industry's R&D infrastructure and driving regional competitive advantages in clean-label innovation.
United States
Corporate wellness program subsidies and clean-label retail preferences drive demand concentration. FDA updated Nutrition Facts label rules and USDA Smart Snacks in School standards reshape permissible formulations. The Chicago-Naperville corridor hosts major CPG headquarters clusters where R&D pipelines accelerate air-puffing extrusion adoption.
Germany
Precision fermentation protein isolate adoption and functional snack positioning command premium shelf space. EFSA novel food approval pathways and EU Green Deal sustainability mandates influence ingredient sourcing decisions. The Munich-Stuttgart industrial corridor anchors biotechnology fermentation capacity expansion for alternative protein inputs.
Japan
Portion-controlled indulgence formats and elderly nutrition applications sustain market development. METI functional food claim regulations and PMDA health food standards govern permissible efficacy messaging. The Kansai region around Osaka maintains concentrated food processing equipment manufacturing for air-puffing technology exports.
United Kingdom
Sugar tax spillover effects and diabetes-focused retail channel development accelerate reformulation timelines. FSA front-of-pack traffic light labeling requirements constrain permissible nutrient profiles. Greater London hosts specialty pharmacy distribution networks targeting glycemic-conscious consumers with clinically positioned assortments.
Canada
Health Canada nutrition labeling harmonization with FDA standards simplifies cross-border SKU management. PMRA novel ingredient approval timelines affect precision fermentation protein market entry sequencing. The Toronto-Waterloo corridor concentrates food technology startups developing flexible packaging automation for direct-to-consumer channels.
Low Calorie Snacks Market Vendor Landscape
The competitive structure tilts toward diversified multinational conglomerates with captive distribution infrastructure. Consolidation pressure favors scaled operators capable of absorbing FDA reformulation compliance costs while sustaining multi-channel shelf presence. Three archetypes dominate: integrated snack-food conglomerates leveraging Frito-Lay-style distribution networks; specialized nutrition science players with clinical channel positioning; and agile clean-label insurgents exploiting direct-to-consumer sampling subscriptions. Dominant competitive moves include portfolio diversification into functional adjacent categories and backward integration into precision fermentation protein supply.
Among North American-based conglomerates, PepsiCo Inc. and Mondelez International Inc. occupy positions representing integrated distribution archetypes, while Nestlé SA exemplifies specialized nutrition science capabilities. These three entities anchor the competitive landscape through divergent strategic postures: distribution infrastructure leverage, functional positioning depth, and clinical channel development respectively.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Mondelez International Inc. |
| Nestlé SA |
| The Hain Celestial Group Inc. |
| The Kraft Heinz Company |
| Conagra Brands Inc. |
| General Mills Inc. |
| Cargill Incorporated |
| Danone SA |
| Others |
Supply Flow & Price Mechanics
Formulation scientist concentration in the Chicago-Naperville corridor and Munich-Stuttgart industrial belt feeds labor-cost differentials into pricing-tier spreads across premium functional and economy private-label portfolios. Allulose fermentation capacity scarcity in North America compresses margins for mid-tier manufacturers while scaled operators absorb input volatility through captive supply arrangements.
Pricing Analysis
Bundled certification-plus-formulation services command premiums against unbundled commodity ingredient sourcing. Three-tier pricing structure across premium clean-label, standard mass-market, and economy private-label levels separates buyers by certification investment capacity. Price differentiation rests on Non-GMO Project verification timelines and precision fermentation protein integration. Pricing pressure stems from allulose supply concentration among three domestic producers. Corporate wellness program procurement teams exhibit lowest price sensitivity; convenience channel distributors show highest.
Supply Chain Analysis
Warehouse-distribution layer consolidation around regional distribution centers in Illinois, Texas, and California shapes hub-and-spoke fulfillment patterns for temperature-sensitive protein isolates. Manufacturing concentrates in the United States, Germany, and Japan where food scientist talent anchors R&D infrastructure. Raw material dependencies include allulose syrup, precision fermentation protein isolates, and air-puffing extrusion equipment. Single-source vulnerability in allulose fermentation capacity creates allocation risk during demand spikes. Distribution runs through Frito-Lay-style direct-store-delivery networks for mass-market penetration alongside direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: California sugar tax spillover creates pricing umbrellas for reformulated products that face no comparable excise in Texas or Florida distribution corridors.
For Market Incumbents: Extend precision fermentation protein backward integration to decouple from agricultural commodity cycles. Fortify clinical channel positioning through endocrinology clinic kiosk expansion before clean-label insurgents capture diabetes-focused retail. Allulose supply concentration threatens margin stability without captive fermentation capacity. For New Entrants and Emerging Players: Enter via specialty pharmacy distribution networks targeting glycemic-conscious consumers where certification requirements filter out mass-market competition. White-space concentrates in diabetes-focused retail channels and direct-to-consumer sampling subscriptions. Curated monthly boxes offer lower trial-cost entry than conventional retail slotting fees. For Investors and Strategic Acquirers: Snack-food conglomerates with Frito-Lay-style distribution infrastructure are the most active acquirer in this space, seeking functional snack lines to fill wellness-positioned portfolio gaps. Long-term viability hinges on clinical channel penetration depth and fermentation capacity ownership. Watch FDA enforcement patterns on updated serving-size standards as inflection indicator for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Captive allulose and protein isolate supply insulates margins from North American producer concentration. |
| Clinical Channel Expansion | Endocrinology clinic kiosk placement locks in glycemic-conscious consumer loyalty ahead of mass-market competition. |
| Direct-to-Consumer Subscription Launch | Curated sampling boxes compress trial costs and reverse conventional awareness-to-purchase funnels in coastal metros. |
| Flexible Packaging Automation Investment | Digital printing convergence with form-fill-seal equipment enables micro-batch personalization for fitness enthusiast segments. |
| Clean-Label Certification Acceleration | Non-GMO Project and Certified Gluten-Free verification truncates 14-18 month timelines to outpace emerging brand launches. |
Methodological Framework
Direct dialogue with formulation scientists, corporate wellness program procurement directors, specialty pharmacy category managers, and flexible packaging automation engineers grounded qualitative findings. Secondary validation drew from FDA Nutrition Facts label rulemakings, USDA Smart Snacks compliance databases, Nielsen retail audit data, and precision fermentation facility permitting records. Bottom-up SKU-level volume builds triangulated against top-down category expenditure models.
Bottom-up demand modeling aggregated individual product-type, packaging-format, and channel-specific trajectories across the projection horizon. Segmentation dimensions included product matrix (bars, chips, cookies, crackers), packaging tier (pouches, bags, boxes, containers), distribution channel (specialty stores, online, supermarkets, convenience), and target audience (diabetics, fitness enthusiasts, health-conscious consumers, weight watchers). CAGRs derived from trend-line extrapolation of historical volume patterns adjusted for regulatory compliance cost inflections and corporate wellness program adoption curves.
Inputs from FDA rulemaking dockets and state-level sugar tax legislative tracking were available through the study window; gaps in real-time allulose producer capacity utilization data introduce uncertainty bands around input cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Fat Crackers Market
Snacks
South America Energy Bar Market
Snacks
Low Fat Protein Snacks Market
Snacks
Germany Snack Bar Market
Snacks
South Africa Snack Bar Market
Snacks
United States Popcorn Market
Snacks
High Carb Low Fat Snack Market
Snacks
Low Fat Sweet Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
Crackers Market
Snacks
Europe Popcorn Market
Snacks
Forti Flakes Market
Snacks
Popcorn Market
Snacks
Asia Pacific Snack Food Market
Snacks
Kale Chips Market