
 Europe Energy Bar Market | 2026-2036
Europe Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Energy Bar Market Foresight
Germany is rewriting production dynamics for the Europe energy bar category through expanded clean-label manufacturing capacity. Nestlé S.A. leverages its R&D intensity to dominate plant-protein formulations. Clif Bar & Company anchors its position through organic ingredient sourcing and outdoor-athlete brand alignment. Mondelēz International Inc competes via shelf-stable distribution economics and impulse-channel control.
An energy bar is a shelf-stable, nutrient-dense food product typically comprising 10–30 grams of protein, complex carbohydrates, and binding syrups, manufactured through cold-press extrusion or baked slab-and-cut processes, designed to deliver rapid glycemic response and sustained satiety for active or time-constrained consumers. Protein bars occupy the largest margin pool due to sports-nutrition positioning and premium pricing power, while online retailers represent the fastest-growing distribution vector as subscription models and direct-to-consumer personalization displace traditional grocery velocity. Meal replacement bars remain structurally mature in Western European markets where satiety claims face EFSA scrutiny.
EFSA novel food assessments, EU Green Deal packaging mandates, and national sugar-tax regimes in France and the UK collectively elevate reformulation costs and reshape permissible health claims. REACH compliance for synthetic flavor compounds adds material qualification burdens that favor suppliers with established European substance dossiers. Stakeholders must monitor evolving EFSA guidance on protein-source sustainability claims and calibrate portfolio mixes between indulgence-positioned snack bars and performance-tier protein formats.
Market Dynamics
EFSA novel food assessments and EU Green Deal packaging mandates are compressing permissible ingredient palettes and forcing wholesale reformulation of binding syrups and protein isolates across European manufacturing lines.
Growth Catalysts
- Clean-label protein diversification:Pea and fava bean isolates are displacing soy concentrates in German and Dutch production facilities as EFSA guidance on protein-source sustainability claims tightens.
- France's national sugar tax regime:The levy on added sugars is accelerating maltitol and allulose adoption in reformulated bars targeting reduced-glycemic positioning.
- Subscription commerce infrastructure:Direct-to-consumer personalization platforms in the UK and Scandinavia are capturing repeat purchase velocity previously locked in grocery impulse channels.
Market Restraints
- REACH compliance burdens:Synthetic flavor compound dossier requirements favor established European suppliers with pre-registered substance libraries, raising barriers for new market entrants.
- Organic ingredient supply concentration:Austrian and Swiss oat protein suppliers command premium positions, creating input cost volatility for mid-tier manufacturers.
- EFSA satiety claim restrictions:Meal replacement bars face structural limitations on health positioning in Western European markets where substantiation thresholds remain prohibitive.
Strategic Opportunities
- Polish and Romanian retail expansion:Organized retail density gaps in these markets present first-mover advantages for premium bar penetration before local competitor consolidation.
- EU packaging sustainability directives:Home-compostable wrapper mandates are creating technology convergence opportunities between bio-polymer innovators and cold-press extrusion equipment suppliers.
- Outdoor-athlete segment whitespace:Nordic hiking and cycling communities remain underpenetrated by performance-tier protein formats relative to German fitness culture saturation.
Industry Challenges
- Reformulation capex intensity:Cold-press extrusion line upgrades to handle novel binding syrups require capital deployment that strains mid-cap balance sheets.
- EFSA novel food approval timelines:Insect protein and precision-fermented ingredient dossiers face 18-24 month assessment windows that compress product launch cadences.
- Multi-jurisdiction labeling complexity:Divergent national sugar-tax thresholds between France, UK, and Germany fragment pack copy requirements and SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Energy Bar Market |
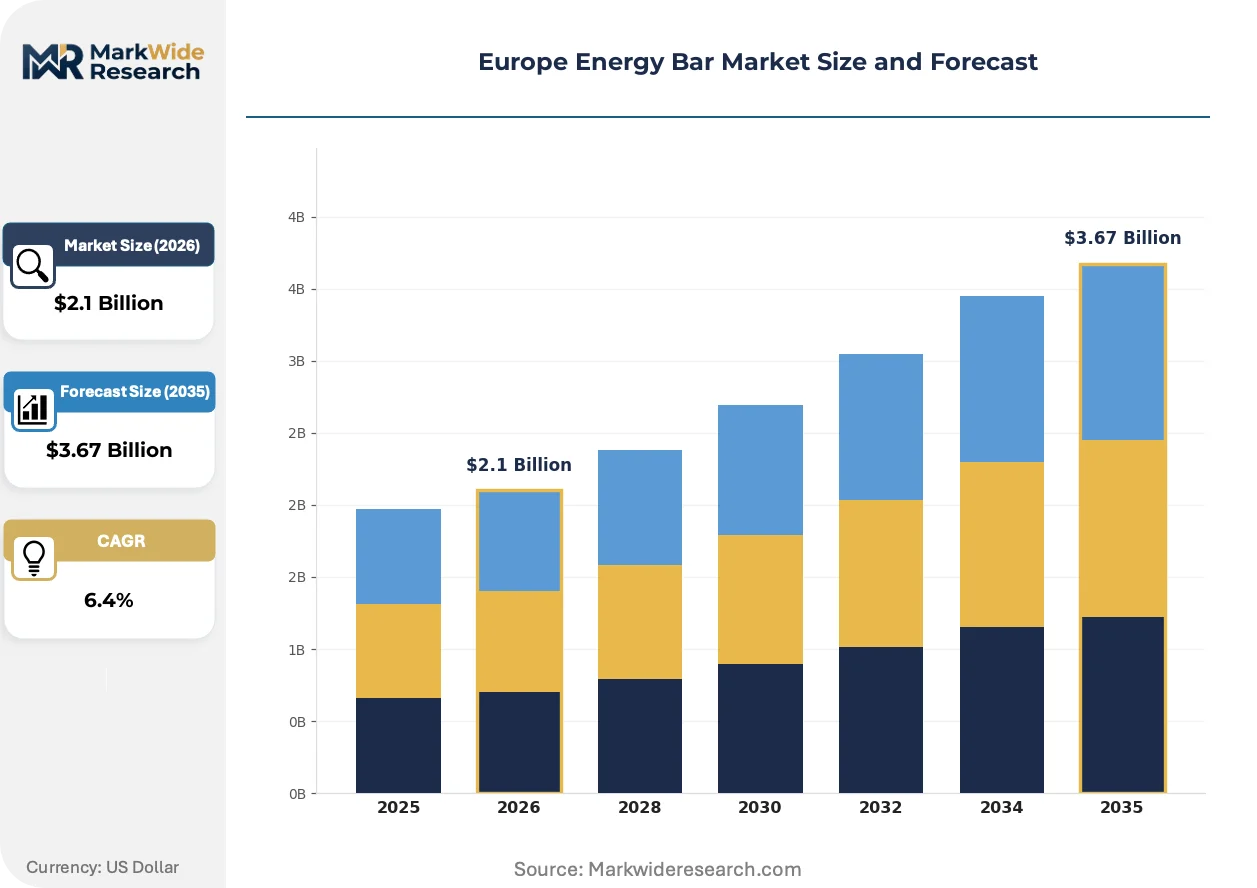
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Meal Replacement Bars, Snack Bars Ingredient Type: Nuts, Seeds, Fruits, Protein Isolates Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Fitness Centers End User: Athletes, Health Conscious Consumers, Busy Professionals, Students |
| Companies Covered | General Mills Inc, PepsiCo Inc, Nestlé S.A., Mars Inc, Mondelēz International Inc, Kellanov, The Hershey Company, Glanbia plc, Clif Bar & Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Energy Bar Market Shifts & Advancements
Extrusion technology advances and bio-polymer packaging breakthroughs are compressing production economics while regulatory pressure on health claims forces portfolio repositioning toward indulgence-adjacent formats.
Cold-press extrusion with twin-screw precision temperature control is rendering obsolete traditional baked slab-and-cut processes for high-protein formulations. German and Dutch contract manufacturers are retrofitting lines at pace to capture plant-protein texture optimization. This shift is rendering obsolete the capacity advantages of legacy baked-bar specialists who lack extrusion expertise.
EFSA's evolving guidance on protein-source sustainability claims is tightening permissible marketing language across the bloc. Manufacturers must now substantiate environmental assertions with lifecycle data that few suppliers currently possess. Sports-nutrition positioned bars face the steepest compliance burden as they pivot from carbon-neutral to regenerative agriculture sourcing narratives.
Busy professionals in London, Paris, and Berlin are consolidating convenience nutrition purchases into subscription bundles that displace single-unit grocery velocity. Direct-to-consumer platforms capture preference data that enables flavor personalization at batch scale. This pattern is most visible in UK urban corridors where delivery density supports chilled last-mile economics for fresh-format bars.
Europe Energy Bar Market Segmentation
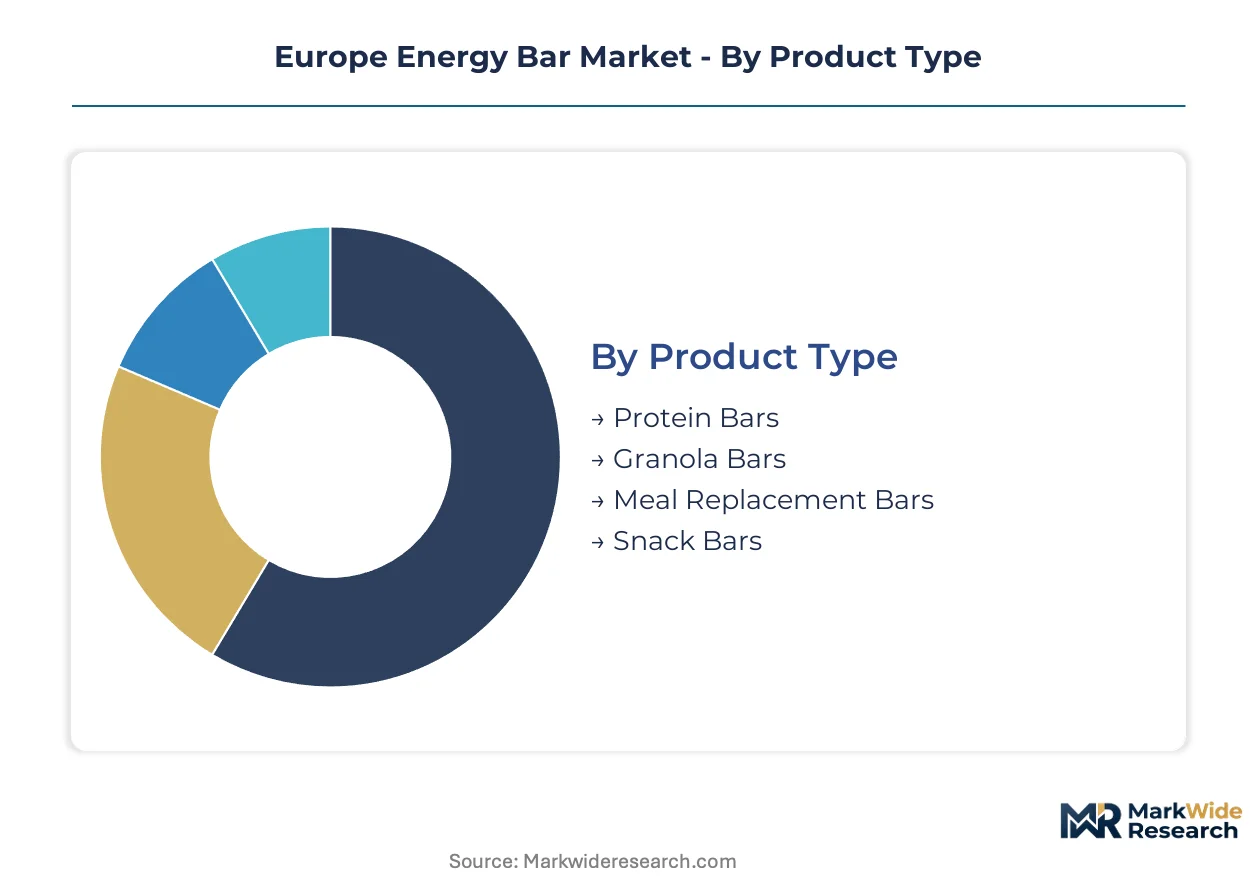
Energy bar manufacturers calibrate portfolio composition across four intersecting dimensions. Product format and ingredient sourcing decisions cascade into channel strategy and end-user targeting. EFSA novel food assessments and EU packaging mandates reshape permissible combinations across every axis.
Product Type:
Mature formats face margin compression while emerging categories capture reformulation premiums.
- Protein Bars:Cold-press extrusion delivers 10-30g protein isolates with glycemic modulation. German fitness culture and organized retail density concentrate demand for performance-tier positioning. EFSA novel food assessments on alternative protein sources elevate substantiation burdens for sustainability claims.
- Meal Replacement Bars:Satiety-optimized formulations with micronutrient fortification target time-constrained professionals. EFSA health claim restrictions in France and UK limit permissible positioning, constraining expansion in Western European markets where substantiation thresholds remain prohibitive.
- Granola Bars:Baked oat and honey clusters with lower protein density serve indulgence-adjacent occasions.
- Snack Bars:Smaller-format, lower-calorie variants target impulse channels and convenience retail.
Protein bars retain volume leadership; snack bars hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity inputs from premium-positioned functional ingredients.
- Protein Isolates:Pea and fava bean isolates displace soy concentrates in Dutch and German production facilities. EFSA guidance on protein-source sustainability claims tightens permissible marketing language, forcing lifecycle data substantiation that few suppliers currently possess.
- Nuts:Almond and cashew bases command premium pricing in organic-positioned bars. Austrian and Swiss suppliers concentrate supply, creating input cost volatility for mid-tier manufacturers lacking long-term procurement contracts.
- Seeds:Chia and pumpkin seed inclusions deliver omega-3 positioning and texture differentiation.
- Fruits:Dried berry and date syrups function as binding agents and natural sweeteners in clean-label formulations.
Nuts anchor premium tier pricing; protein isolates are climbing the fastest on reformulation demand.
Distribution Channel:
Volume concentration shifts from brick-and-mortar velocity toward digital subscription economics.
- Online Retailers:Direct-to-consumer platforms capture repeat purchase velocity through subscription bundles and flavor personalization. UK urban corridors with delivery density support chilled last-mile economics for fresh-format bars, displacing traditional grocery impulse channels.
- Supermarkets:Shelf-stable distribution economics and impulse-channel control dominate mass-market penetration. Mondelēz International leverages this infrastructure for economy-tier positioning across German and French retail networks.
- Health Food Stores:Curated assortments serve organic-seeking consumers with premium price acceptance.
- Fitness Centers:Proximity-to-occasion placement captures immediate post-workout consumption with minimal brand switching.
Supermarkets retain volume leadership; online retailers gain share fastest on personalization capabilities.
End User:
Application intensity separates performance-driven consumption from convenience-motivated purchasing.
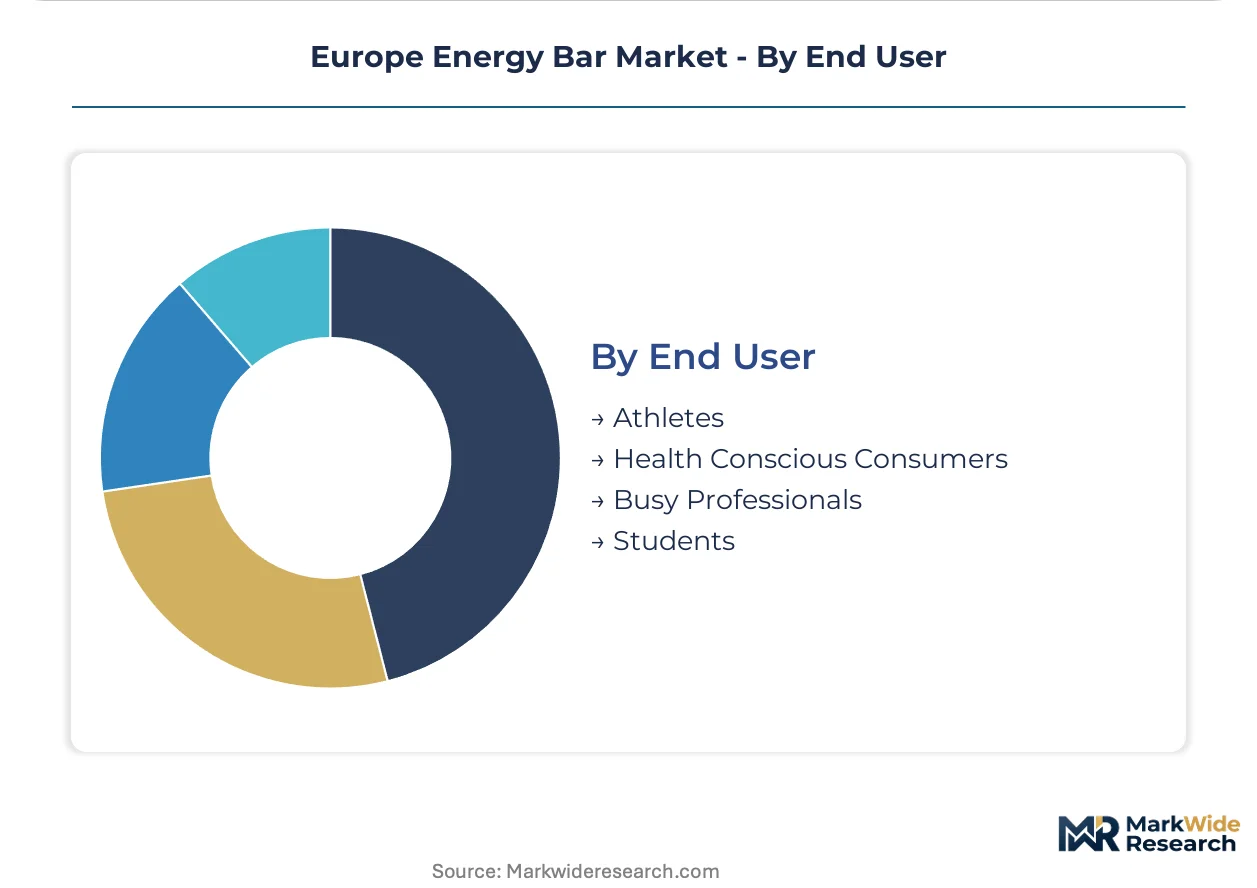
- Athletes:Sports-nutrition positioning demands rapid glycemic response and sustained satiety. German fitness culture saturation concentrates demand, while Nordic hiking and cycling communities remain underpenetrated relative to this benchmark.
- Busy Professionals:Time-constrained consumers in London, Paris, and Berlin consolidate convenience nutrition into subscription bundles. Direct-to-consumer platforms capture preference data enabling batch-scale flavor personalization.
- Health Conscious Consumers:Clean-label and organic certifications drive purchase decisions with price inelasticity for verified claims.
- Students:Budget-sensitive demand concentrates in snack-bar formats through discount retail and campus convenience stores.
Athletes retain volume leadership; busy professionals hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing capacity clusters in Germany and the Netherlands, with cold-press extrusion lines retrofitting at pace to capture plant-protein texture optimization. This supply-side concentration funnels reformulated output toward Western European consumption corridors while Eastern European retail density gaps attract first-mover premium bar penetration.
Germany
Fitness culture saturation and organized retail density concentrate demand for performance-tier protein positioning. EFSA novel food assessments on alternative protein sources elevate substantiation burdens for sustainability claims. Bavaria and North Rhine-Westphalia host the densest contract manufacturing clusters, where twin-screw extrusion line upgrades handle novel binding syrups at industrial scale.
United Kingdom
Busy professionals in London consolidate convenience nutrition into subscription bundles that displace single-unit grocery velocity. The national sugar-tax regime fragments pack copy requirements and forces SKU proliferation across England, Scotland, and Wales. Direct-to-consumer platforms in Greater London capture preference data enabling batch-scale flavor personalization for fresh-format bars.
France
The national sugar levy on added sugars accelerates maltitol and allulose adoption in reformulated bars targeting reduced-glycemic positioning. EFSA satiety claim restrictions limit permissible meal replacement bar positioning, constraining expansion in Île-de-France and Auvergne-Rhône-Alpes. Paris-based subscription commerce infrastructure captures repeat purchase velocity through personalized nutrition bundles.
Netherlands
Pea and fava bean isolates displace soy concentrates in Dutch production facilities as EFSA guidance on protein-source sustainability claims tightens. REACH compliance for synthetic flavor compounds raises barriers for new market entrants without established European substance dossiers. The Randstad corridor anchors clean-label manufacturing capacity serving export markets across the Benelux region.
Poland
Organized retail density gaps present first-mover advantages for premium bar penetration before local competitor consolidation. EU Green Deal packaging mandates create technology convergence opportunities between bio-polymer innovators and extrusion equipment suppliers. Warsaw and Kraków retail corridors show accelerating demand for convenience nutrition among urban professionals.
Europe Energy Bar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between multinational CPG conglomerates with shelf-stable distribution economics and mid-cap organic specialists with clean-label ingredient sourcing. Three archetypes dominate: R&D-intensive plant-protein formulators, organic-outdoor brand aligners, and impulse-channel mass-market controllers. Competitive moves center on cold-press extrusion line acquisitions and direct-to-consumer platform buildouts.
Within the R&D-intensive tier, Nestlé S.A. and Glanbia plc exemplify platform-scale investment in novel protein isolate substantiation. Among organic-positioned specialists, Clif Bar & Company occupies a position aligned with outdoor-athlete segment targeting. At the mass-market end, Mondelēz International Inc and General Mills Inc anchor impulse-channel control through supermarket shelf economics. These groupings represent archetype concentration rather than exhaustive market coverage.
| Leading Market Players |
|---|
| General Mills Inc |
| PepsiCo Inc |
| Nestlé S.A. |
| Mars Inc |
| Mondelēz International Inc |
| Kellanov |
| The Hershey Company |
| Glanbia plc |
| Clif Bar & Company |
| Others |
Supply & Pricing Matrix
Austrian and Swiss oat protein suppliers anchor premium-tier input costs, concentrating margin capture upstream while mid-tier manufacturers absorb volatility through shorter procurement cycles. This supplier concentration funnels pricing power toward organic-certified finished goods, leaving conventional-positioned bars exposed to cost compression.
Pricing Analysis
EFSA novel food assessments dictate the pricing tier structure across the Europe energy bar market. Three-tier pricing separates performance-tier protein formats from standard snack bars and economy impulse-positioned products. Price differentiation rests on certification grade and cold-press extrusion capability. Cost compression in the standard tier is intensifying because Dutch and German contract manufacturers retrofit lines at pace. Students remain the most price-sensitive segment, while health-conscious consumers show least sensitivity for verified organic claims.
Supply Chain Analysis
REACH compliance for synthetic flavor compounds limits flows from non-European suppliers without established substance dossiers. Manufacturing capacity clusters in Germany, the Netherlands, and Poland. Raw material dependencies center on pea and fava bean isolates, Austrian oat proteins, and maltitol sweeteners. Single-source vulnerability runs through Swiss organic nut suppliers. Distribution feeds from contract manufacturers through supermarket retail networks and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
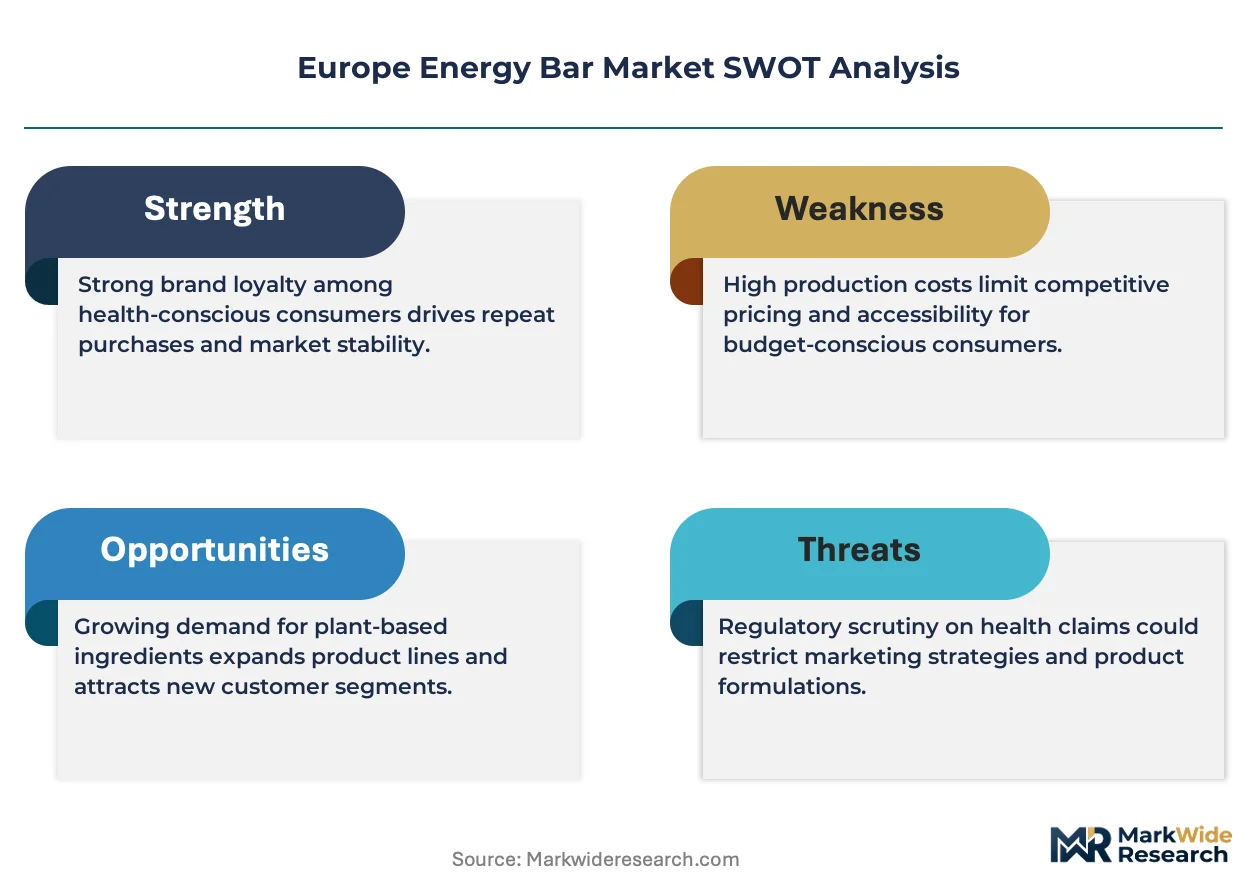
The Europe energy bar market represents high-growth disruption as EFSA novel food assessments and EU Green Deal packaging mandates force wholesale reformulation across manufacturing lines.
For Market Incumbents: Build regulatory dossier depth as a moat against mid-tier challengers. Nestlé S.A. and Glanbia plc should accelerate cold-press extrusion line acquisitions in Bavaria and North Rhine-Westphalia to capture plant-protein texture optimization. Certification investment in regenerative agriculture sourcing narratives defends against EFSA sustainability claim scrutiny. For New Entrants and Emerging Players: Pursue Nordic hiking and cycling communities as underpenetrated whitespace relative to German fitness saturation. Polish and Romanian retail density gaps offer first-mover premium bar penetration before local competitor consolidation. Direct-to-consumer subscription platforms in Greater London provide the most viable go-to-market angle for fresh-format bars. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing twin-screw extrusion expertise but lacking brand equity. Long-term viability over a 5-10 year window favors platforms with established EFSA substance dossiers. The signal to watch is EFSA approval timeline compression for precision-fermented protein isolates.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Line Acquisition | German manufacturers capture plant-protein texture optimization as baked-bar capacity becomes obsolete. |
| Direct-to-Consumer Platform Buildout | UK subscription bundles displace grocery impulse velocity through batch-scale flavor personalization. |
| Regenerative Agriculture Sourcing | Sustainability narratives pivot from carbon-neutral to lifecycle-substantiated claims under EFSA guidance. |
| Home-Compostable Packaging Transition | EU Green Deal mandates create technology convergence between bio-polymer innovators and equipment suppliers. |
| Polish Retail Corridor Expansion | Warsaw and Kraków organized retail gaps attract premium bar penetration before local consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at retailers, channel sales heads, and supply planners and refined through secondary validation. Primary interviews combined with EFSA novel food guidance documents, EU Green Deal packaging mandate filings, Nielsen retail audit data, and customs trade records. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Demand-supply balance dynamics anchored the analytical framework throughout the projection horizon. Segmentation dimensions spanned product format, ingredient sourcing tier, distribution channel, and end-user application intensity. CAGRs derived from trend extrapolation calibrated against contract manufacturer capacity expansion announcements and EFSA approval pipeline velocity.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and input commodity prices would shift the trajectory. Forecasts reflect assumptions on regulatory timeline stability and clean-label ingredient substitution rates. Material shifts in EFSA novel food assessment windows or REACH substance dossier requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Poland Snack Bar Market
Snacks
Marshmallow Market
Snacks
Low Calorie Snacks Market
Snacks
UK Snack Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Mushroom Based Jerky Market
Snacks
Energy Bar Market
Snacks
High Fiber Snack Foods Market
Snacks
Germany Snack Bar Market
Snacks
Thailand Snack Bar Market
Snacks
Better for You Snacks Market
Snacks
United Kingdom Energy Bar Market
Snacks
Low Calorie Dip Market
Snacks
Spain Energy Bar Market
Snacks
South America Snack Bar Market
Snacks
Europe Nuts and Cereal Snacks Bar Market