
 North America Marshmallow Market | 2026-2036
North America Marshmallow Market Size, Share, and Industry Trends Forecast 2026-2036
North America Marshmallow Market Intelligence
Clean-label mandates from major retail buyers is rebalancing procurement priorities across the North American marshmallow supply chain. Doumak leverages its longstanding manufacturing scale to sustain conventional volume contracts with mass-market retailers. Campfire Marshmallows anchors its position through geographic dominance in private-label and co-manufacturing relationships. Dandies Marshmallows differentiates through vegan certification and allergen-free positioning, competing for shelf space in natural channel outlets.
Marshmallows are aerated confectionery products composed of sugar syrup, gelatin or plant-based hydrocolloids, and whipped air, typically containing 15-20% moisture and setting through starch mogul or extrusion processes; they function as standalone sweets, recipe ingredients, or beverage toppings across foodservice and retail channels. Gourmet marshmallows command premium price positioning in specialty food stores, while vegan marshmallows represent the fastest-growing product type as dietary restrictions expand. Snacking applications dominate volume, though baking ingredients capture disproportionate margin pools through seasonal demand concentration.
The FDA governs ingredient labeling and food safety standards, while USDA organic certification shapes access to premium distribution channels; Health Canada enforces bilingual labeling and additive restrictions that influence cross-border product formulations. The FDA's evolving guidance on added sugars disclosure is forcing reformulation timelines. Stakeholders must monitor plant-based gelatin alternatives and state-level packaging waste regulations to anticipate cost and compliance trajectories.
Market Dynamics
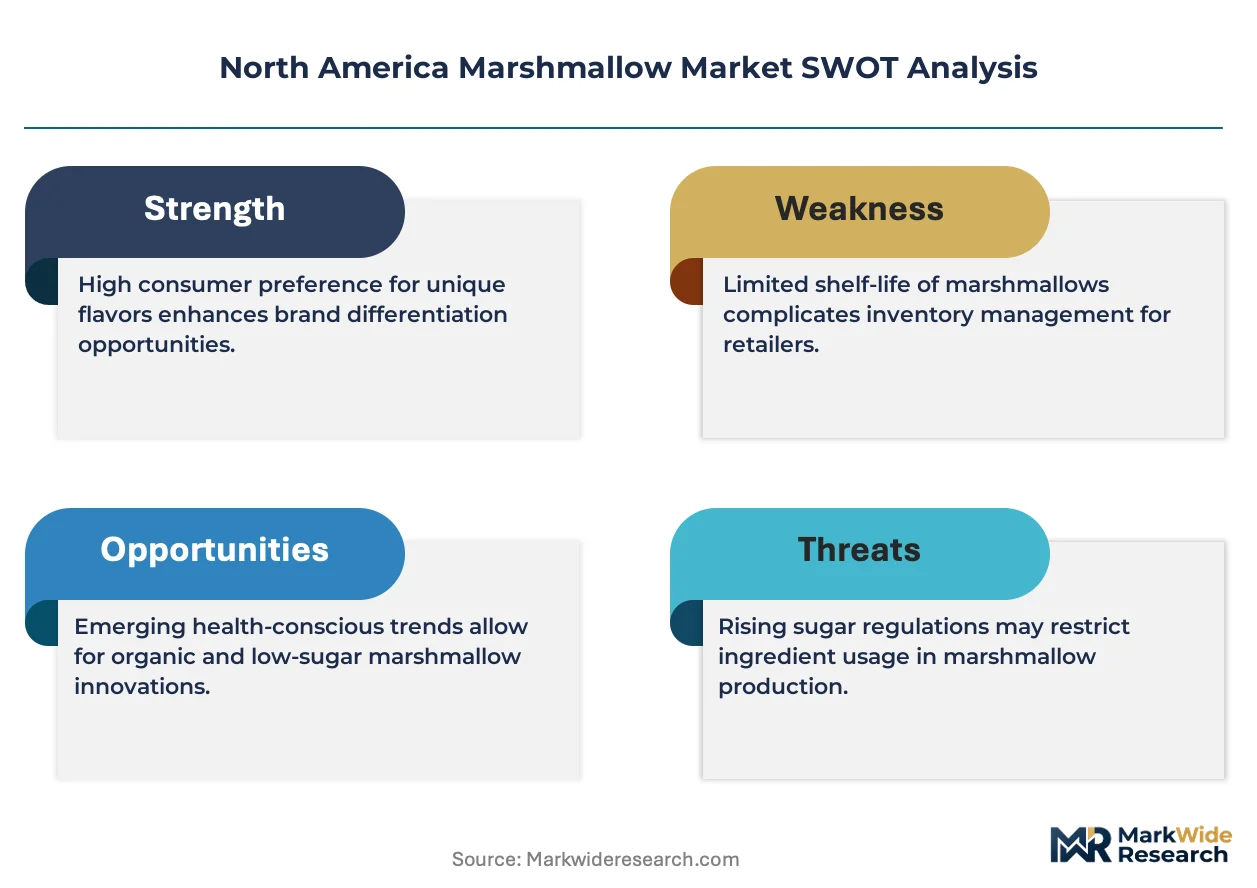
Clean-label procurement mandates from major retail buyers are rebalancing supplier relationships across the North American marshmallow supply chain, forcing reformulation investments and reshaping competitive positioning between conventional and plant-based producers.
Growth Catalysts
- Pacific Northwest Premium Snacking Culture:Specialty food retailers in Seattle and Portland are expanding artisanal confectionery shelf space, creating pull-through for small-batch marshmallow producers.
- FDA Added Sugars Disclosure Rules:Evolving guidance on nutrition labeling is accelerating tapioca syrup and reduced-sugar reformulations that qualify for cleaner ingredient panels.
- Plant-Based Hydrocolloid Innovation:Carrageenan-free binding systems using agar-agar and pectin are unlocking vegan certification pathways previously blocked by texture limitations.
Market Restraints
- Gelatin Supply Concentration:Pork and beef gelatin sourcing depends on concentrated Midwestern rendering facilities, exposing producers to livestock cycle volatility and input cost spikes.
- USDA Organic Certification Barriers:Three-year transition requirements for conventional corn syrup suppliers block rapid portfolio pivots toward premium organic positioning.
- Confectionery Substitution Threat:Gummy candies and fruit snacks compete for identical impulse purchase occasions and baking ingredient use cases at lower price points.
Strategic Opportunities
- Southern California Beverage Topping Channel:Artisanal coffee chains in Los Angeles and San Diego are adopting house-made marshmallows for specialty hot chocolate and latte programs.
- Health Canada Bilingual Labeling Compliance:Cross-border formulation harmonization creates first-mover advantage for US producers achieving simultaneous FDA and Health Canada clearance.
- Direct-to-Consumer Subscription Models:Seasonal flavor rotations and gift-box assortments bypass conventional retail slotting fees while capturing premium price realization.
Industry Challenges
- Starch Mogul Equipment Obsolescence:Depositing and curing systems designed for gelatin-based recipes require costly retrofitting to handle plant-based hydrocolloid setting behaviors.
- Clean-Label R&D Talent Scarcity:Food scientists with expertise in aerated confectionery texture engineering without synthetic stabilizers command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Marshmallow Market |
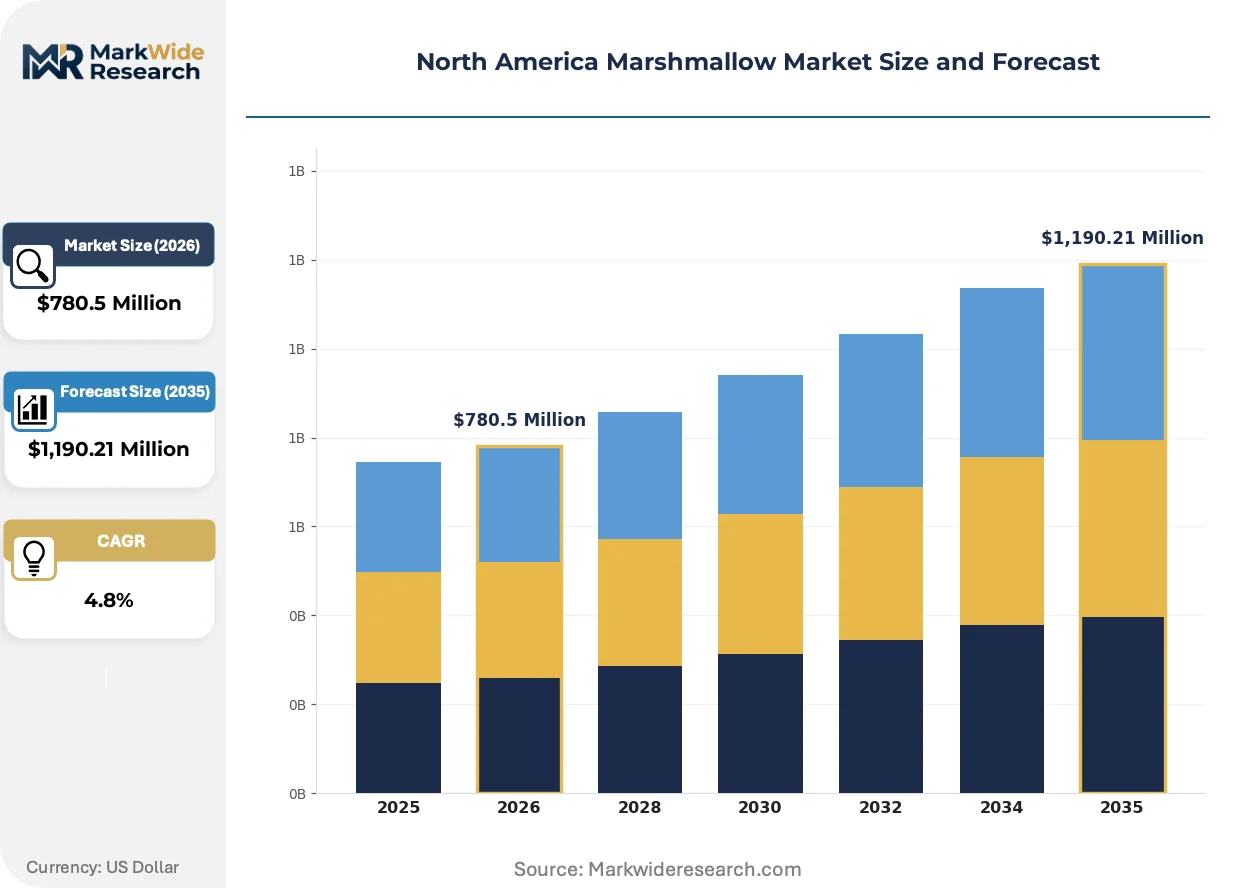
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,190.21 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Marshmallows, Gourmet Marshmallows, Miniature Marshmallows, Flavored Marshmallows, Vegan Marshmallows Application: Snacking, Baking Ingredients, Hot Beverages Topping, Confectionery Decorations, Party Favors Packaging Type: Plastic Bags, Cardboard Boxes, Bulk Bags, Stand-up Pouches, Flow Wraps Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retailers, Specialty Food Stores, Foodservice Distributors |
| Companies Covered | Doumak, Campfire Marshmallows, Mondelez International, Kraft Heinz, Dandies Marshmallows, General Mills, Stuffed Puffs, Marshmallow Fluff, Just Born, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Marshmallow Market Strategic Shifts & Innovations
Reformulation chemistry and retail procurement standards are actively reshaping competitive advantage in North American marshmallow production, compressing timelines between innovation and shelf placement while elevating transparency requirements.
Agar-agar and pectin-based aeration systems are converging with traditional starch mogul processing lines, enabling texture parity between vegan and conventional products. Natural channel retailers in California and Oregon are adopting these reformulations at accelerated pace. The technology is converging with clean-label mandates to compress the premium pricing window for early movers.
The FDA's evolving added sugars disclosure framework is forcing ingredient declaration changes that expose high-fructose corn syrup content to consumer scrutiny. Reformulation costs are concentrating among mid-tier producers lacking R&D scale. Baking ingredient segments targeting seasonal demand are responding fastest with tapioca and brown rice syrup substitutions.
Specialty coffee shop procurement is rotating toward in-house marshmallow programs that displace packaged retail alternatives. Third-wave roasters in Portland and Austin are building direct supplier relationships with small-batch confectioners. This channel shift is most visible in Pacific Coast metropolitan markets where beverage premiumization outpaces conventional grocery velocity.
North America Marshmallow Market Segmentation
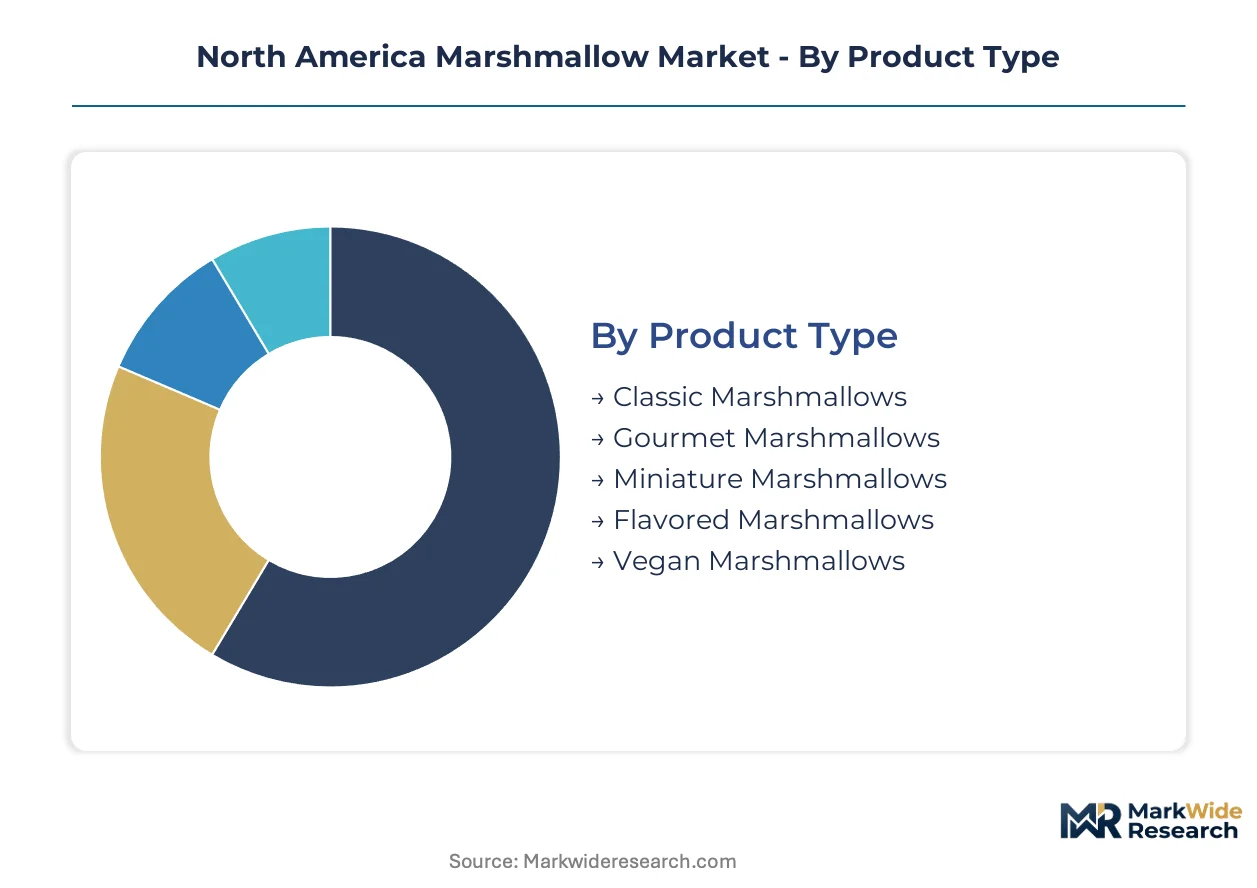
Marshmallow segmentation in North America reflects divergent margin architectures between commodity volume plays and premium positioning strategies. Clean-label procurement mandates from retailers like Whole Foods and Kroger are reshaping how producers allocate R&D across product tiers. Each segment category carries distinct capital intensity and shelf-life constraints that govern competitive entry.
Product Type:
Volume concentration sits with gelatin-based classics, while premium expansion concentrates in plant-based alternatives targeting dietary-restricted households.
- Classic Marshmallows:Standard gelatin-based formulations with 15-20% moisture content dominate campfire and s'mores applications. Midwestern mass retailers move these SKUs in seasonal surges tied to summer outdoor activity and holiday baking cycles.
- Vegan Marshmallows:Agar-agar and pectin-based aeration systems achieve texture parity with conventional products. Pacific Northwest specialty grocers and California natural channel outlets are expanding shelf space fastest for certified allergen-free alternatives.
- Gourmet Marshmallows:Small-batch production with artisan flavor profiles commands 3-4x price multiples over conventional equivalents.
- Miniature Marshmallows:Optimized for hot cocoa and RTE cereal integration with accelerated dissolution properties.
- Flavored Marshmallows:Seasonal rotations and limited editions target gift-box and subscription channel velocity.
Mature deployment sits with Classic Marshmallows. Newer deployment is concentrated in Vegan Marshmallows.
Application:
Snacking generates baseline volume, while baking ingredients capture disproportionate margin through seasonal demand spikes.
- Snacking:Direct consumption drives year-round replenishment cycles with highest absolute tonnage. Convenience store and gas station channels in Texas and Florida sustain grab-and-go velocity for single-serve pillow packs.
- Baking Ingredients:Rice Krispies treats, fudge, and seasonal confections require specific density and melt characteristics. Thanksgiving-through-Christmas demand concentration forces producers to carry inventory buffers that compress annual margin profiles.
- Hot Beverages Topping:Third-wave coffee shops in Los Angeles and Seattle are building direct supplier relationships with small-batch confectioners for house-made programs.
- Confectionery Decorations:Cake toppers and fondant alternatives require structural rigidity and extended ambient stability.
- Party Favors:Themed shapes and custom colors serve event planning and corporate gifting verticals with irregular order patterns.
Volume leadership sits with Snacking. Margin expansion is climbing the fastest in Baking Ingredients.
Packaging Type:
Cost per unit and shelf visibility tradeoffs determine format selection across retail versus foodservice channels.
- Plastic Bags:Polyethylene pillow packs dominate mass-market velocity with lowest unit economics. Walmart and Target private-label programs standardize on this format for everyday replenishment SKUs.
- Stand-up Pouches:Resealable barrier films extend shelf life for premium and natural channel positioning. REI and specialty outdoor retailers favor this format for camping-focused assortments.
- Cardboard Boxes:Seasonal gift sets and multi-flavor assortments leverage structural rigidity for retail display.
- Bulk Bags:Foodservice and manufacturing customers optimize per-pound economics with 10-50 lb industrial formats.
- Flow Wraps:Individual portion control serves hospitality and institutional feeding programs with precise serving compliance.
Scale concentration sits with Plastic Bags. Premium migration is gaining share fastest in Stand-up Pouches.
Distribution Channel:
Slotting fee structures and inventory risk allocation vary sharply between conventional grocery and emerging direct-to-consumer pathways.
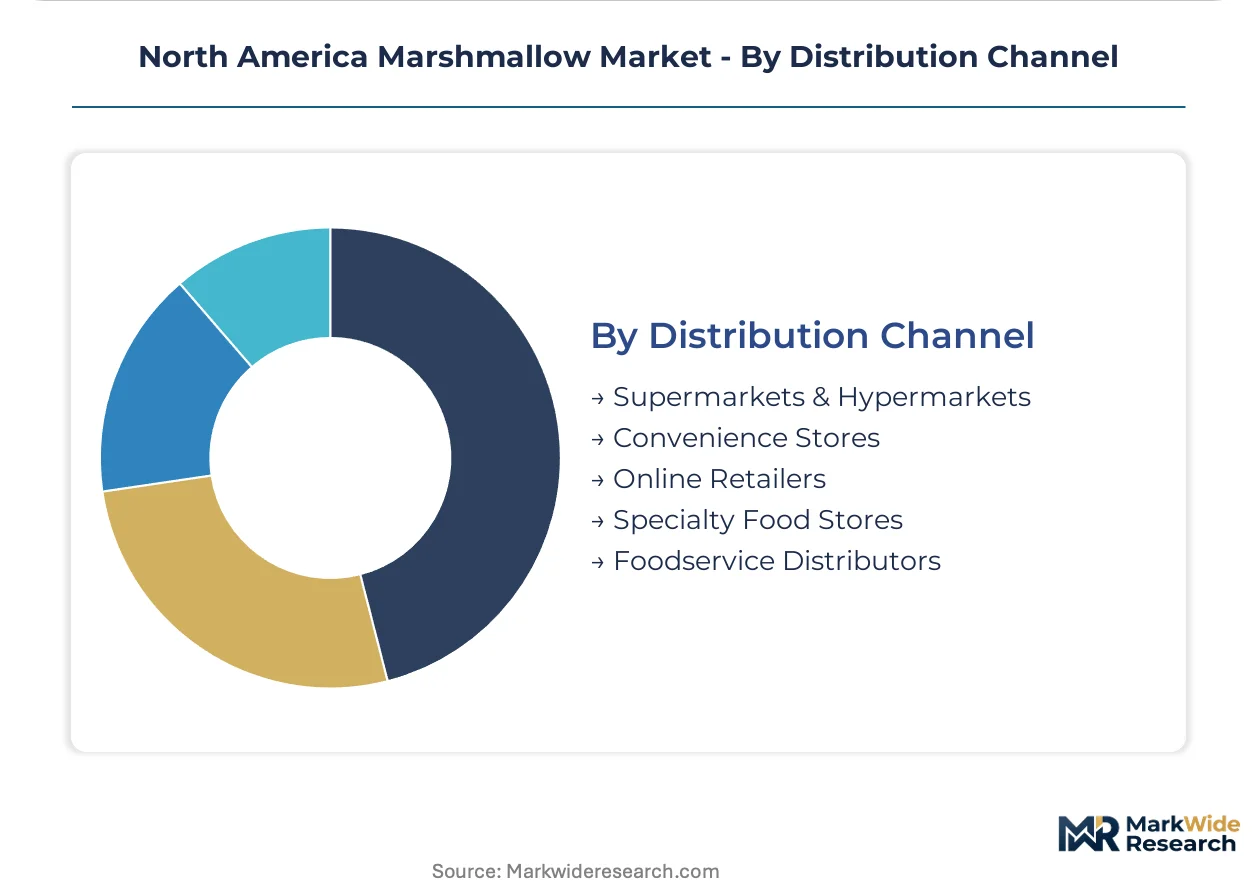
- Supermarkets & Hypermarkets:Kroger, Safeway, and Publix control shelf placement through category management fees and promotional fund commitments. Clean-label mandates from these buyers are forcing reformulation investments across supplier bases.
- Specialty Food Stores:Whole Foods and regional co-ops in Portland and Austin curate artisanal and certified vegan SKUs with localized assortment authority.
- Online Retailers:Amazon and Thrive Market enable subscription models that bypass traditional slotting economics.
- Convenience Stores:7-Eleven and Circle K prioritize impulse placement with seasonal and limited-edition velocity.
- Foodservice Distributors:Sysco and US Foods route bulk formats to restaurant and hospitality accounts with specification-driven procurement.
Established volume sits with Supermarkets & Hypermarkets. Channel expansion is steepest in Specialty Food Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American marshmallow innovation through its third-wave coffee shop density and premium snacking culture, while Pacific Northwest cities and Southern metropolitan areas drive divergent demand patterns across the United States and Canada.
United States
Pacific Northwest specialty grocers in Seattle and Portland are expanding artisanal confectionery shelf space fastest, while Southern California beverage topping channels absorb small-batch production. FDA added sugars disclosure rules are accelerating tapioca syrup reformulations among mid-tier producers. Chicago and Detroit industrial corridors retain mass-market manufacturing scale for conventional gelatin-based volume contracts.
Canada
Health Canada bilingual labeling requirements and additive restrictions are forcing cross-border formulation harmonization for US exporters targeting Toronto and Vancouver natural channel outlets. Prairie provinces sustain bulk ingredient demand through foodservice distributors serving hospitality accounts. Montreal's specialty food retail cluster is adopting vegan-certified alternatives at accelerated pace.
Mexico
Mexico City metropolitan area convenience store chains are rotating toward impulse-placement marshmallow SKUs for seasonal velocity. SAMR-aligned importers navigate FDA-Health Canada compliance standards for re-export positioning. Guadalajara's food processing corridor is developing co-manufacturing relationships with US brands seeking nearshore capacity.
North America Marshmallow Market Key Industry Players
The competitive structure tilts toward tiered specialization between mass-market volume players and premium-positioned artisans. Conventional producers dominate private-label and co-manufacturing relationships through Midwestern manufacturing scale, while plant-based specialists capture natural channel shelf space through vegan certification. Strategic moves concentrate on clean-label reformulation investments and direct-to-consumer subscription bypass of traditional slotting economics.
Among established North American producers, Doumak occupies a position exemplifying conventional manufacturing scale, Campfire Marshmallows anchors geographic dominance in private-label relationships, and Dandies Marshmallows represents the plant-based specialist archetype competing for natural channel distribution.
| Leading Market Players |
|---|
| Doumak |
| Campfire Marshmallows |
| Mondelez International |
| Kraft Heinz |
| Dandies Marshmallows |
| General Mills |
| Stuffed Puffs |
| Marshmallow Fluff |
| Just Born |
| Others |
Cost & Logistics Intelligence
Starch mogul-to-extrusion equipment retrofitting for plant-based hydrocolloid recipes is compressing capital recovery timelines while concentrating production scale among Midwestern contract manufacturers with legacy gelatin-based asset bases. This technological transition simultaneously elevates entry barriers for artisanal entrants and reinforces price discipline among volume leaders serving Kroger and Walmart private-label programs.
Pricing Analysis
Certification-grade pricing anchors the North American marshmallow market, with USDA Organic and vegan-certified SKUs commanding substantial premia over conventional equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient transparency and retail channel positioning. Price differentiation hinges on clean-label compliance and geographic delivery radius to natural channel outlets. Cost compression in mid-tier conventional segments is intensifying because of tapioca syrup reformulation investments and slotting fee escalation at mass retailers. Convenience store buyers exhibit highest price sensitivity, while specialty coffee shop procurement shows lowest elasticity due to beverage premiumization mandates.
Supply Chain Analysis
Single-source vulnerability sits with Midwestern pork and beef gelatin rendering facilities, where concentrated livestock processing infrastructure exposes producers to input cost volatility. Geographic supply concentration centers on Illinois, Iowa, and Indiana for conventional gelatin-based production, with Pacific Northwest and Southern California emerging for plant-based alternatives. Raw material dependencies draw from corn syrup refineries, tapioca starch processors, and agar-agar importers. Tariff exposure on Southeast Asian seaweed-derived hydrocolloids threatens margin stability for vegan-certified producers. Distribution runs through Sysco and US Foods for foodservice bulk formats, with direct-to-consumer subscription models bypassing traditional retail slotting economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American marshmallow market functions as a cost-of-compliance arena where FDA added sugars disclosure rules and Health Canada bilingual labeling mandates erect regulatory moats favoring incumbents with dedicated regulatory affairs capabilities.
For Market Incumbents: Deploy backward integration into tapioca syrup supply to secure clean-label input cost stability against corn syrup price volatility. Campfire Marshmallows and Doumak should consolidate private-label manufacturing relationships through capacity guarantees in Chicago-Detroit industrial corridors. Certification investment in simultaneous FDA-Health Canada clearance creates cross-border procurement advantages as Canadian natural channel expansion accelerates. For New Entrants and Emerging Players: Specialty coffee shop direct-supplier relationships represent the most penetrable channel wedge, with Los Angeles and Seattle third-wave roasters seeking house-made marshmallow programs outside conventional packaged retail. Target Southern California beverage topping applications where premiumization outpaces grocery velocity. White-space exists in seasonal subscription gift-box assortments with flavor rotation capabilities that bypass slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with plant-based specialists given Health Canada additive restrictions accelerating vegan certification requirements across North American natural channels. Acquisition focus should center on mid-tier producers with USDA Organic transition pipelines and established Pacific Northwest distribution. Watch for FDA final guidance on added sugars disclosure as inflection indicator for reformulation investment cycles and consolidation pressure on conventional-only players.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Tapioca syrup substitution aligns Doumak and Campfire with Whole Foods procurement mandates. |
| Cross-Border Regulatory Harmonization | Simultaneous FDA-Health Canada clearance unlocks Toronto and Vancouver natural channel expansion. |
| Direct-to-Consumer Subscription Launch | Seasonal flavor rotations bypass Kroger slotting fees while capturing premium price realization. |
| Specialty Coffee Shop Supply Partnership | Direct relationships with Portland and Austin roasters displace packaged retail in beverage topping. |
| Plant-Based Hydrocolloid R&D Scale-Up | Agar-agar texture parity investment defends Dandies against conventional producer vegan line extensions. |
Research Approach
Independent corroboration across FDA labeling guidance documents, Health Canada additive restriction filings, and Nielsen retail audit data underwrites the qualitative findings. Primary interviews with confectionery R&D directors, natural channel category buyers at Whole Foods and regional co-ops, and contract manufacturing procurement leads at Midwestern production facilities were synthesized with secondary validation from USDA organic certification databases, SEC 10-K disclosures of publicly traded parent companies, and customs records of tapioca starch and agar-agar import flows. Bottom-up SKU-level volume builds were cross-checked against top-down category expenditure estimates.
Rate-of-change decomposition across product type, application, packaging format, and distribution channel dimensions structures the analytical framework. CAGRs were derived from segment-level growth trajectories modeled across the analysis window, incorporating price elasticity assumptions for conventional versus plant-based alternatives and seasonal demand concentration factors for baking ingredient applications. Inputs include Pacific Northwest specialty grocer expansion rates, FDA regulatory timeline assumptions, and third-wave coffee shop procurement survey data.
Caveats apply where FDA final rulemaking on added sugars disclosure, Health Canada enforcement intensity on bilingual labeling, or Midwestern livestock cycle volatility could materially shift the outlook. Forecasts assume continued clean-label procurement mandate diffusion without reversal. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Fat Free Candy Market
Confectionery
Vegan Candies Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Chocolate Confectionery Market
Confectionery
Japan Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Global Mochi Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
US Confectionery Market
Confectionery
Liquorice Shellac Market