
 Italy Snack Bar Market | 2026-2036
Italy Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Snack Bar Market Foresight
Multi-source ingredient procurement is expanding as Italian snack bar manufacturers diversify away from single-origin nut and dried fruit suppliers. Ferrero Group leverages its established hazelnut supply chains to anchor premium nut bar production in Piedmont. Nestlé S.A. competes through specialized R&D facilities near Milan that sustain rapid formulation iteration for protein-enriched lines.
An Italian snack bar denotes a shelf-stable, individually packaged food item typically composed of cereals, nuts, dried fruits, binders such as honey or syrup, and functional additives including protein isolates or fiber, manufactured through cold-pressed extrusion or baked slab-and-cut processes for on-the-go consumption. Protein bars capture the fastest-growing margin pool as athletic and fitness-oriented demand intensifies across Italian metropolitan gyms and cycling clubs. Granola bars dominate volume through deep supermarket penetration, though fruit bars face margin compression from volatile southern European dried fruit input costs.
Italy's Ministry of Health enforces compositional standards aligned with EU Regulation 1169/2011 on food information to consumers, while EFSA evaluates health claim substantiation for protein and fiber marketing. These frameworks compel reformulation investment and restrict unsubstantiated functional positioning. Stakeholders must monitor evolving EU packaging waste directives and Italy's extended producer responsibility schemes to anticipate compliance cost trajectories.
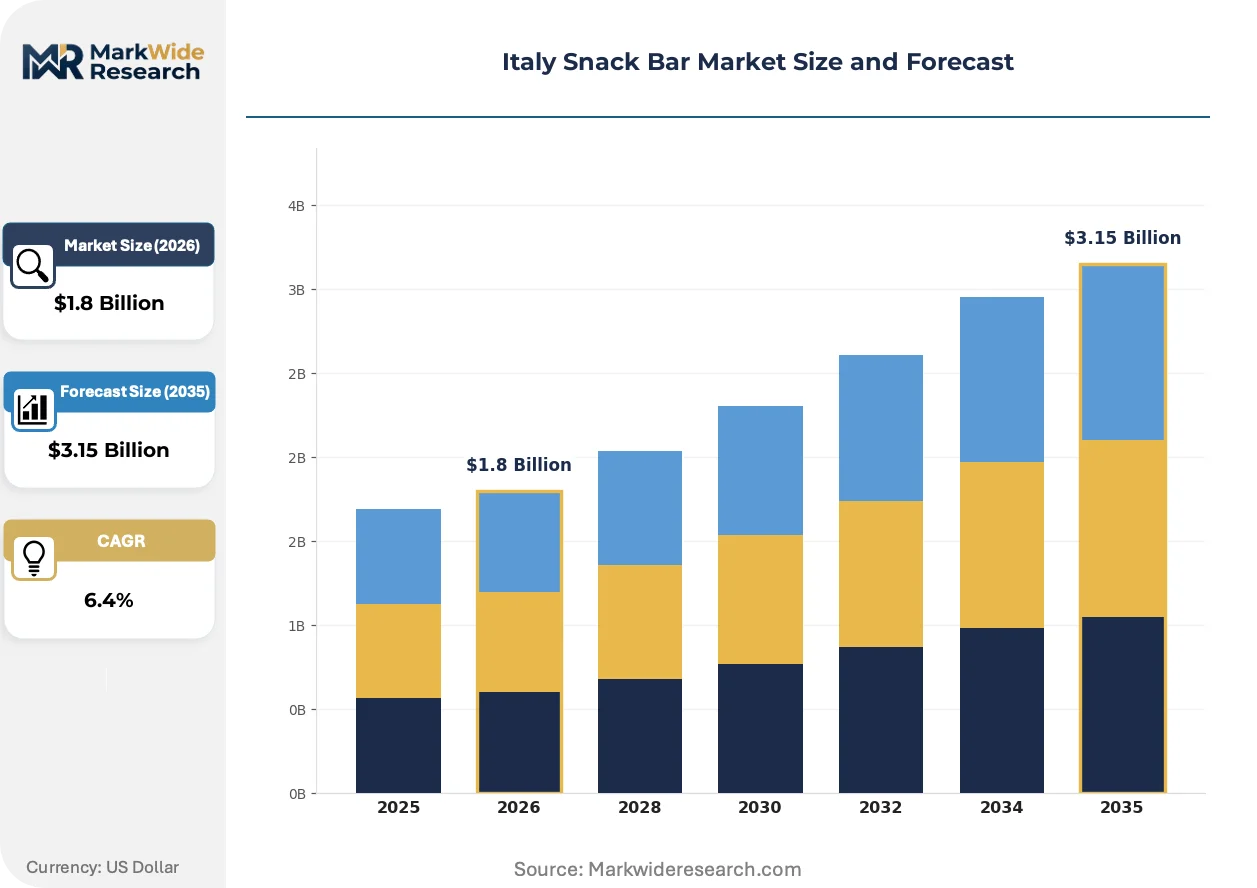
Market Dynamics
Italy's snack bar sector confronts a structural pivot where EU nutrition labeling mandates under EFSA guidance force simultaneous reformulation investment and premium positioning compression, while northern Italy's fitness culture intensifies protein-fortified demand concentration.
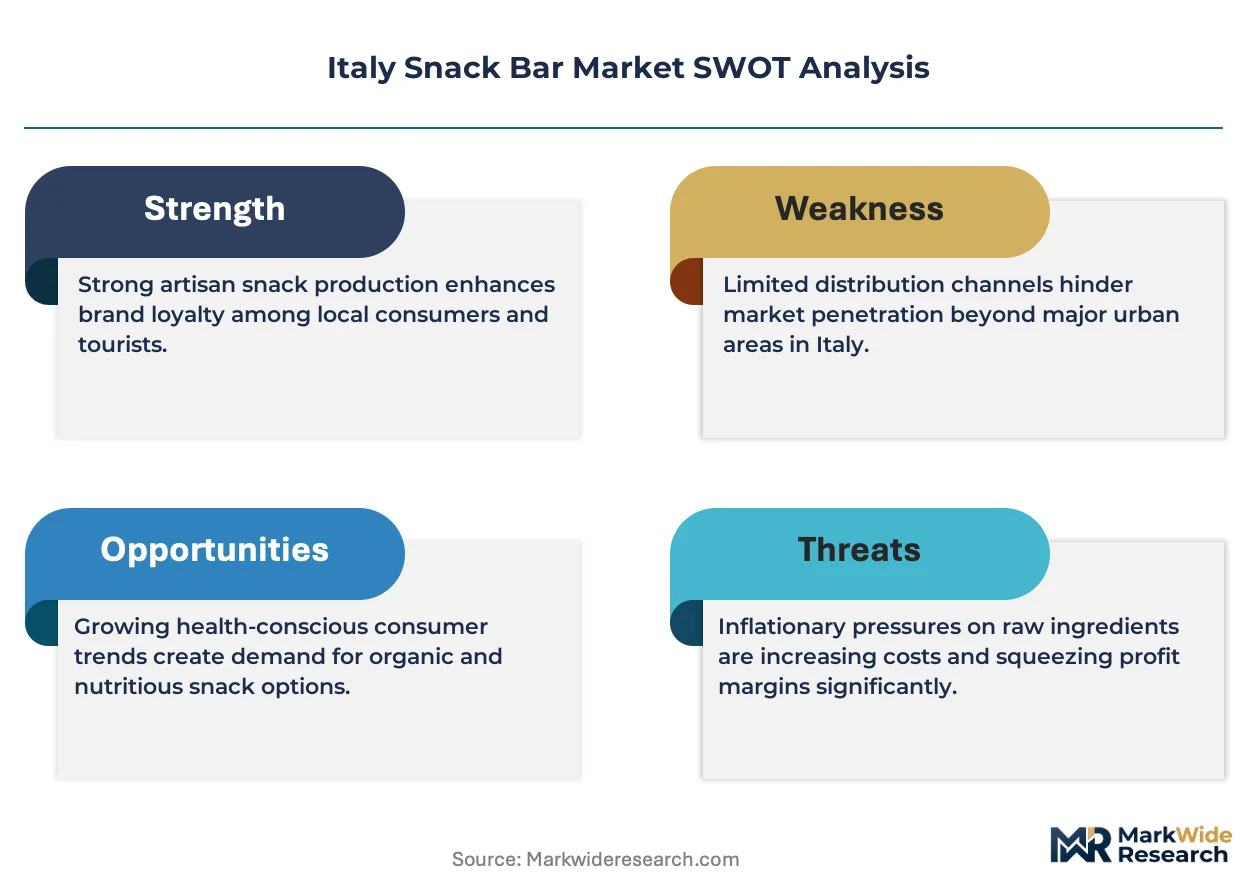
Growth Catalysts
- EFSA Health Claim Framework:Substantiated protein and fiber positioning enables premium tier capture as manufacturers validate functional benefits through clinical dossiers.
- Lombardy Fitness Cluster:Milan's dense gym and cycling club networks generate concentrated demand for performance-oriented formats with elevated protein content.
- Cold-Pressed Extrusion:This manufacturing process preserves heat-sensitive micronutrients, allowing clean-label positioning that commands shelf space in Italian premium retail.
Market Restraints
- Southern European Dried Fruit Volatility:Input cost swings for apricots and figs from Spanish and Greek suppliers compress fruit bar margins unpredictably.
- Single-Origin Nut Dependency:Piedmont hazelnut supply concentration creates vulnerability to regional climate shocks and pollinator population fluctuations.
- EU Packaging Waste Directive:Extended producer responsibility schemes impose compliance cost trajectories that disproportionately burden mid-tier manufacturers.
Strategic Opportunities
- Central Italy Underpenetration:Rome and Florence exhibit lower snack bar per-capita consumption than Milan, presenting whitespace for format localization.
- Pharmacy Channel Expansion:Italy's parafarmacia network offers regulated distribution for clinically positioned digestive health and diabetic-friendly lines.
- Italy's National Health Service Wellness Initiatives:Preventive health programming creates institutional procurement pathways for medically endorsed snacking interventions.
Industry Challenges
- Reformulation Talent Scarcity:Protein isolate stability and clean-label binder chemistry expertise concentrates in Milan's specialized R&D corridors, creating recruitment bottlenecks.
- EFSA Dossier Timeline Compression:Health claim substantiation cycles extend 18-24 months, delaying market entry for novel functional positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Snack Bar Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Fruit Bars, Nut Bars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Customer Type: Health-Conscious Consumers, Busy Professionals, Students, Athletes Price Tier: Premium, Mid-Range, Budget, Value Packs |
| Companies Covered | PepsiCo, Inc., Associated British Foods plc, Nestlé S.A., Clif Bar & Company, Kind Snacks, Ferrero Group, General Mills Inc., Post Holdings, Inc., Kellogg Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Snack Bar Market Shifts & Advancements
Italian snack bar manufacturing is experiencing a technology-driven bifurcation where cold-processing methods and precision fermentation reshape ingredient sourcing, while regulatory transparency requirements and channel fragmentation redefine competitive advantage.
Precision fermentation-derived proteins are integrating into Piedmont production facilities, enabling whey-alternative formulations that bypass dairy supply volatility. Sports nutrition buyers in Turin and Milan cycling clubs adopt these formats rapidly. This technology is integrating cost structures previously anchored to commodity dairy cycles into controlled bioreactor economics.
EFSA's updated guidance on nutrition and health claims under EU Regulation 1924/2006 tightens substantiation thresholds for protein content marketing. Manufacturers must now compile human intervention studies rather than relying on compositional data alone. Protein-fortified lines targeting athletic segments face the steepest compliance investment, with several Italian brands withdrawing marginal claims pending dossier completion.
Direct-to-gym distribution models bypass traditional retail slotting fees, capturing margin from Milan's boutique fitness studios and Rome's CrossFit affiliates. Specialized distributors now maintain refrigerated vans for fresh-format protein bars with shortened shelf life. This channel rotation concentrates in northern Italy's premium fitness corridor before diffusing southward.
Italy Snack Bar Market Segmentation
Segmentation in Italy's snack bar market reveals how functional positioning and channel economics create distinct competitive arenas. Manufacturers must align formulation investment with precise customer workflows rather than pursuing undifferentiated volume.
Product Type:
Standardization dominates commodity formats while customization concentrates in performance-oriented lines targeting Lombardy's fitness clusters.
- Granola Bars:Baked oat and honey formulations with moderate protein content serve family breakfast routines and school lunchboxes. Demand concentrates in northern Italy's supermarket chains, where private-label penetration compresses branded margins and rewards scale manufacturing.
- Protein Bars:Cold-pressed extrusion preserves isolate integrity in formulations exceeding 20g protein per serving. Milan's cycling clubs and CrossFit affiliates drive adoption of whey-alternative and precision-fermented variants, with EFSA health claim substantiation separating premium positioning from commodity protein fortification.
- Fruit Bars:Apricot and fig-dominant compositions face southern European input volatility from Spanish and Greek suppliers.
- Nut Bars:Piedmont hazelnut supply chains anchor premium positioning through Ferrero Group's captive sourcing infrastructure.
Most installed capacity flows through Granola Bars. Expansion is steepest in Protein Bars.
Distribution Channel:
Channel selection determines margin capture, with refrigerated logistics requirements fragmenting economics across temperature-controlled and ambient-stable formats.
- Supermarkets:Deep penetration across Esselunga and Coop banners in Lombardy and Piedmont sustains volume leadership for granola and mid-tier protein formats. Slotting fees and promotional calendars favor established suppliers with multi-SKU portfolios.
- Convenience Stores:Autogrill and local tabaccheria networks capture impulse purchases during commuting hours in Rome and Milan metropolitan corridors.
- Online Retail:Amazon Italia and specialized sports nutrition platforms enable direct-to-consumer subscription models for clinically positioned digestive health lines.
- Specialty Shops:Boutique fitness studios and parafarmacia channels in Turin bypass traditional retail markups for fresh-format protein bars with shortened shelf life.
Volume concentrates in Supermarkets. Margin expansion is most rapid in Specialty Shops.
Customer Type:
Usage occasion and nutritional literacy create divergent willingness-to-pay curves across demographic cohorts.
- Health-Conscious Consumers:Clean-label scrutiny and EFSA claim awareness drive premium tier adoption in Rome and Florence urban centers.
- Busy Professionals:Meal-replacement functionality during Milan's extended commuting windows sustains demand for 200-250 calorie formats with sustained-release carbohydrates.
- Students:Price sensitivity and portability requirements favor value-pack granola formats distributed through university-adjacent convenience retail.
- Athletes:Turin and Milan cycling clubs generate concentrated demand for clinically substantiated protein-to-carbohydrate ratios with rapid glycemic recovery profiles.
Health-Conscious Consumers anchor premium pricing. Athletes are expanding most quickly as gym density increases across central Italy.
Price Tier:
Cost stratification reflects ingredient provenance, manufacturing complexity, and regulatory compliance investment rather than simple brand premium extraction.
- Premium:Single-origin Piedmont hazelnut and precision-fermented protein formulations command shelf space in Milan's specialty fitness channels and pharmacy networks.
- Mid-Range:Standard protein isolates and EU-sourced dried fruit compositions balance EFSA compliance costs with accessible positioning for health-conscious professionals.
- Budget:Commodity oat and syrup binders with minimal functional additives serve price-sensitive student and rural segments through discount supermarket banners.
- Value Packs:Multi-unit pricing structures in Esselunga and Coop hypermarkets reduce per-unit cost for family pantry stocking occasions.
Mid-Range captures the broadest customer base. Premium is climbing the fastest as clinical positioning and clean-label certification expand addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's fitness corridor anchors Italian snack bar demand concentration, with Milan's cycling culture and dense gym networks driving protein-fortified adoption. Regional fragmentation across Italy's north-south divide creates divergent growth trajectories.
Lombardy
Milan's boutique fitness studios and CrossFit affiliates generate concentrated demand for cold-pressed protein formats with clinical positioning. EFSA health claim substantiation requirements shape product development timelines for local manufacturers. The city's R&D corridors house specialized formulation talent for isolate stability and clean-label binder chemistry.
Piedmont
Turin's cycling clubs and alpine sports culture sustain premium nut bar consumption through single-origin hazelnut supply chains. EU packaging waste directives impose extended producer responsibility costs on regional manufacturers. Ferrero Group's captive sourcing infrastructure dominates hazelnut procurement in the Alessandria and Cuneo provinces.
Lazio
Rome's pharmacy networks and National Health Service wellness initiatives create institutional procurement pathways for medically endorsed formats. Italy's Ministry of Health compositional standards align with EU Regulation 1169/2011 on food information. Per-capita consumption lags Milan, presenting whitespace for format localization targeting busy professionals.
Veneto
Verona and Padua exhibit emerging demand for precision-fermented protein alternatives among university-adjacent health-conscious cohorts. EFSA guidance on nutrition and health claims tightens substantiation thresholds for regional entrants. Cold-pressed extrusion manufacturing preserves heat-sensitive micronutrients for clean-label positioning in specialty retail.
Emilia-Romagna
Bologna's food science research clusters support reformulation investment for digestive health and diabetic-friendly lines. Italy's extended producer responsibility schemes anticipate compliance cost trajectories for mid-tier manufacturers. Supermarket penetration through Coop banners sustains granola bar volume for family breakfast routines.
Italy Snack Bar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-fermented alternatives and direct-to-gym distribution channels. The vendor base stratifies across multinational scale operations, regional specialty houses, and biotech-enabled challengers. Three archetypes dominate: captive supply integrators, clinical positioning specialists, and agile format innovators. Competitive intensity concentrates on M&A for R&D talent and strategic partnerships for cold-chain logistics.
Among multinational scale operators, Nestlé S.A. and Ferrero Group exemplify divergent sourcing strategies. Nestlé's Milan-adjacent R&D facilities anchor rapid protein formulation iteration. Ferrero's Piedmont hazelnut infrastructure represents backward integration into premium nut bar inputs. PepsiCo, Inc. occupies a position balancing mass-market granola volume with sports nutrition line extensions.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Associated British Foods plc |
| Nestlé S.A. |
| Clif Bar & Company |
| Kind Snacks |
| Ferrero Group |
| General Mills Inc. |
| Post Holdings, Inc. |
| Kellogg Company |
| Others |
Supply & Pricing Matrix
Premium-to-commodity bifurcation between cold-pressed protein formats and baked granola lines manifests in divergent margin structures and sourcing footprints across northern Italy. EFSA health claim substantiation costs concentrate in Milan's premium tier while commodity oat-syrup formulations compete on scale economics through Piedmont's industrial bakery clusters.
Pricing Analysis
Input-cost pass-through from volatile southern European dried fruit markets compresses fruit bar margins unpredictably while protein isolate premiums sustain elevated pricing in athletic channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from EU packaging waste directive compliance costs that disproportionately burden mid-tier manufacturers. Students and rural consumers exhibit highest price sensitivity; pharmacy-channel health-conscious buyers demonstrate lowest.
Supply Chain Analysis
Italy's National Health Service wellness procurement criteria and EU origin labeling preferences reshape sourcing toward domestic hazelnut and alpine dairy inputs. Geographic supply concentration centers on Spain and Greece for dried apricots and figs, Piedmont for hazelnuts, and northern EU for whey isolates. Raw material dependencies include pollinator-sensitive nut crops, climate-exposed stone fruits, and bioreactor-cultivated precision-fermented proteins. Single-source vulnerability in Piedmont hazelnut supply chains creates regional climate shock exposure. Distribution runs through refrigerated logistics for fresh-format protein bars and ambient networks for shelf-stable granola.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Lombardy fitness culture and EFSA clinical positioning requirements concentrate demand toward premium specifications with validated functional claims.
For Market Incumbents: Lock in Piedmont hazelnut supply through long-term grower contracts before climate volatility intensifies. Acquire Milan-adjacent R&D talent pools specializing in isolate stability chemistry to defend against precision-fermented protein challengers. Prioritize EFSA dossier completion for existing protein claims to maintain shelf access against reformulation-ready competitors. For New Entrants and Emerging Players: Enter via Rome's underpenetrated professional segment with meal-replacement formats targeting extended commuting windows. Exploit whitespace in central Italy's parafarmacia channel for medically endorsed digestive health lines. Deploy direct-to-gym distribution through boutique fitness studios to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with biotech-enabled challengers possessing precision-fermentation capabilities and clean-label certification infrastructure. Long-term viability over the projection horizon favors acquisition targets with captive sourcing relationships and completed EFSA health claim portfolios. Monitor EFSA guidance timeline compression as inflection indicator for premium positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Completion | Clinical substantiation unlocks pharmacy channel access and premium pricing tiers. |
| Precision Fermentation Scale-Up | Bioreactor economics displace commodity dairy cycles in Piedmont production facilities. |
| Direct-to-Gym Distribution Launch | Bypasses Autogrill and supermarket slotting fees in Milan's boutique fitness corridor. |
| Piedmont Hazelnut Supply Contracting | Backward integration secures premium nut bar inputs against pollinator population volatility. |
| Parafarmacia Channel Expansion | Rome's pharmacy networks offer regulated distribution for diabetic-friendly and digestive health lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with snack bar brand managers, category buyers at Esselunga and Coop, R&D formulation specialists, and parafarmacia procurement officers with secondary validation against EFSA guidance documents, EU Regulation 1924/2006 filings, and Italian Ministry of Health compositional standards. Nielsen retail audit data, customs import records for dried fruit inputs, and gym membership density statistics anchored bottom-up demand estimation. Top-down triangulation cross-checked manufacturer capacity disclosures and extended producer responsibility compliance cost disclosures.
Historical reference periods anchored the forecast window to pre-pandemic baseline consumption patterns and post-EFSA guidance reformulation cycles across the modeling period. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and price tier alongside regional fitness infrastructure density. CAGRs were derived from slope analysis of normalized per-capita consumption curves. Industry-specific forecast inputs incorporated EFSA dossier approval timelines and precision-fermentation capacity buildout schedules.
Inputs from retail audit databases and regulatory filing repositories were available through the study window; gaps in real-time gym channel sell-through data introduce uncertainty bands around athletic segment projections. Forecasts reflect documented assumptions regarding EFSA enforcement consistency and climate stability in southern European growing regions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Nutritional Bar Market
Snacks
United Kingdom Energy Bar Market
Snacks
Jerky Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Global Fruit Snacks Market
Snacks
Meat Protein Chips Market
Snacks
Organic Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
South America Frozen Snacks Market
Snacks
North America Savory Snacks Market
Snacks
High Fiber Snack Foods Market
Snacks
United Kingdom Snack Bar Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Pretzel Salts Market
Snacks
Corn Chips Market
Snacks
Asia Pacific Snack Food Market