
 Vegan Collagen Powder Market | 2026-2036
Vegan Collagen Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Collagen Powder Market Insights
Beauty consumers is rotating toward vegan collagen powders faster than conventional fitness buyers, reshaping how brands allocate R&D and marketing resources. Vital Proteins leverages its established collagen brand equity to cross-sell plant-derived lines through premium positioning. Geltor anchors the supply side with microbial fermentation platforms that produce bio-identical collagen peptides without animal agriculture. Sunwarrior differentiates through raw, sprouted protein blends that appeal to ingredient-conscious buyers seeking minimal processing.
Vegan collagen powder comprises amino acid profiles—glycine, proline, and hydroxyproline—synthesized through microbial fermentation or extracted from plant proteins, then formulated to mimic the structural support functions of animal-derived collagen in skin, joint, and connective tissue applications. Powder formulations dominate unit economics due to lower shipping weights and flexible dosing protocols, while liquid and gummy formats capture trial-oriented beauty consumers through convenience positioning. Seaweed extract sources command premium shelf placement as marine-origin positioning aligns with clean-beauty narratives, though pea protein volumes anchor mainstream accessibility through cost-efficient supply chains.
The FDA oversees dietary supplement labeling and structure-function claims in the United States, while the USDA Organic certification and Non-GMO Project verification shape consumer trust and retail access for plant-based nutrition products. EFSA in Europe evaluates novel food applications for fermented collagen alternatives, creating compliance timelines that favor established biotech suppliers over new entrants. Stakeholders must monitor how evolving clean-label standards and fermentation-derived ingredient classifications interact with existing supplement regulatory frameworks to anticipate reformulation requirements and market access barriers.
Market Dynamics
Microbial fermentation platforms are compressing production timelines for bio-identical collagen peptides, shifting competitive advantage from agricultural supply chains toward biotech R&D capabilities and IP portfolios.
Growth Catalysts
- Clean-label certification frameworks:USDA Organic and Non-GMO Project verification accelerate retail shelf access for plant-based nutrition products in United States mass-market channels.
- Beauty segment demand rotation:Skincare and wellness consumers now outpace traditional sports nutrition buyers in trial rates for vegan collagen powders.
- Yeast fermentation technology:Precision fermentation enables scalable production of amino acid profiles matching animal-derived collagen without livestock inputs.
Market Restraints
- Input cost volatility:Sugar feedstock prices for microbial fermentation fluctuate with agricultural commodity markets, squeezing margin structures.
- Supply concentration risk:Biotech fermentation capacity clusters in limited contract manufacturing facilities, creating bottlenecks for scale-up.
- Regulatory friction:EFSA novel food approval timelines for fermented collagen alternatives delay European market entry by 18-24 months versus conventional supplements.
Strategic Opportunities
- Underpenetrated geography:Germany's pharmacy channel remains underserved by vegan collagen powders despite strong clean-beauty consumer base.
- Regulatory tailwind:EU Green Deal agricultural transition incentives favor fermentation-derived proteins over animal agriculture inputs.
- Technology convergence:AI-driven strain optimization combined with continuous fermentation bioreactors promises 40% yield improvements.
Industry Challenges
- Specialized talent scarcity:Industrial biologists with both fermentation scale-up and food-grade regulatory experience command premium compensation.
- Certification timeline compression:Dual certification for USDA Organic and NSF Sport requires 14-18 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Collagen Powder Market |
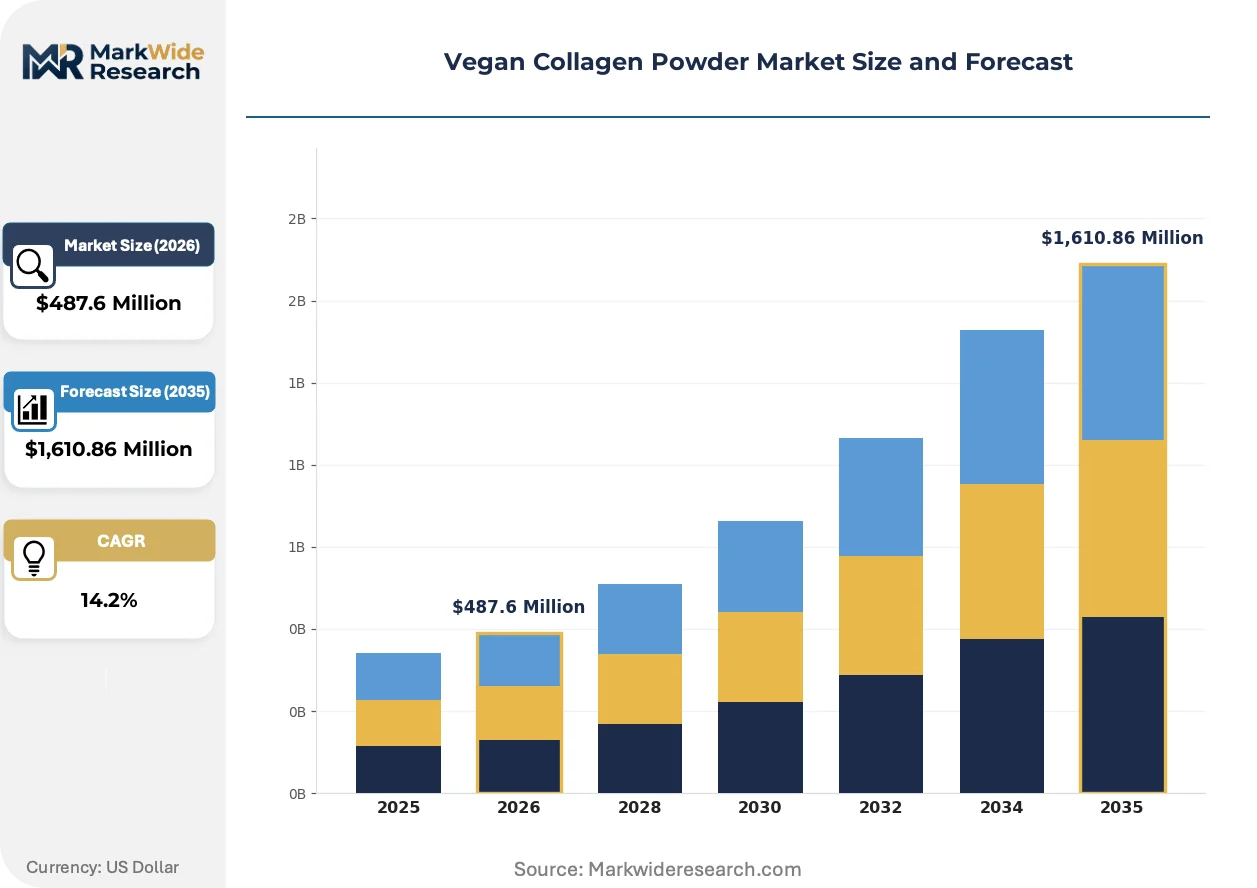
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Liquid, Gummies Source: Pea Protein, Rice Protein, Seaweed Extract, Corn Protein End User: Fitness Enthusiasts, Athletes, Vegans, Beauty Consumers Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Shops |
| Companies Covered | Vital Proteins, Garden of Life, Sunwarrior, Moon Juice, Geltor, Ancient Nutrition, Orgain, NeoCell, Revive Collagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Collagen Powder Market Trends and Innovations
Biotechnology maturation is splitting the competitive landscape between precision-fermentation specialists and plant-extraction incumbents, each pursuing distinct cost and positioning strategies.
Precision fermentation is bifurcating the supply base. Geltor-style microbial platforms produce bio-identical collagen peptides with exact amino acid sequencing. Beauty brands with clean-science positioning adopt these inputs fastest. This technology is compressing the premium pricing power of marine collagen suppliers.
EFSA's evolving novel food guidance for fermentation-derived proteins is reshaping European go-to-market strategies. The regulatory body now requires extended safety dossiers for recombinant yeast strains. Smaller brands lacking biotech regulatory expertise are withdrawing from EU launch timelines.
Subscription-direct models are displacing traditional supplement retail. Beauty consumers now expect personalized dosing protocols and auto-replenishment. This channel shift concentrates in United States urban markets where influencer-driven discovery dominates trial generation.
Vegan Collagen Powder Market Segmentation
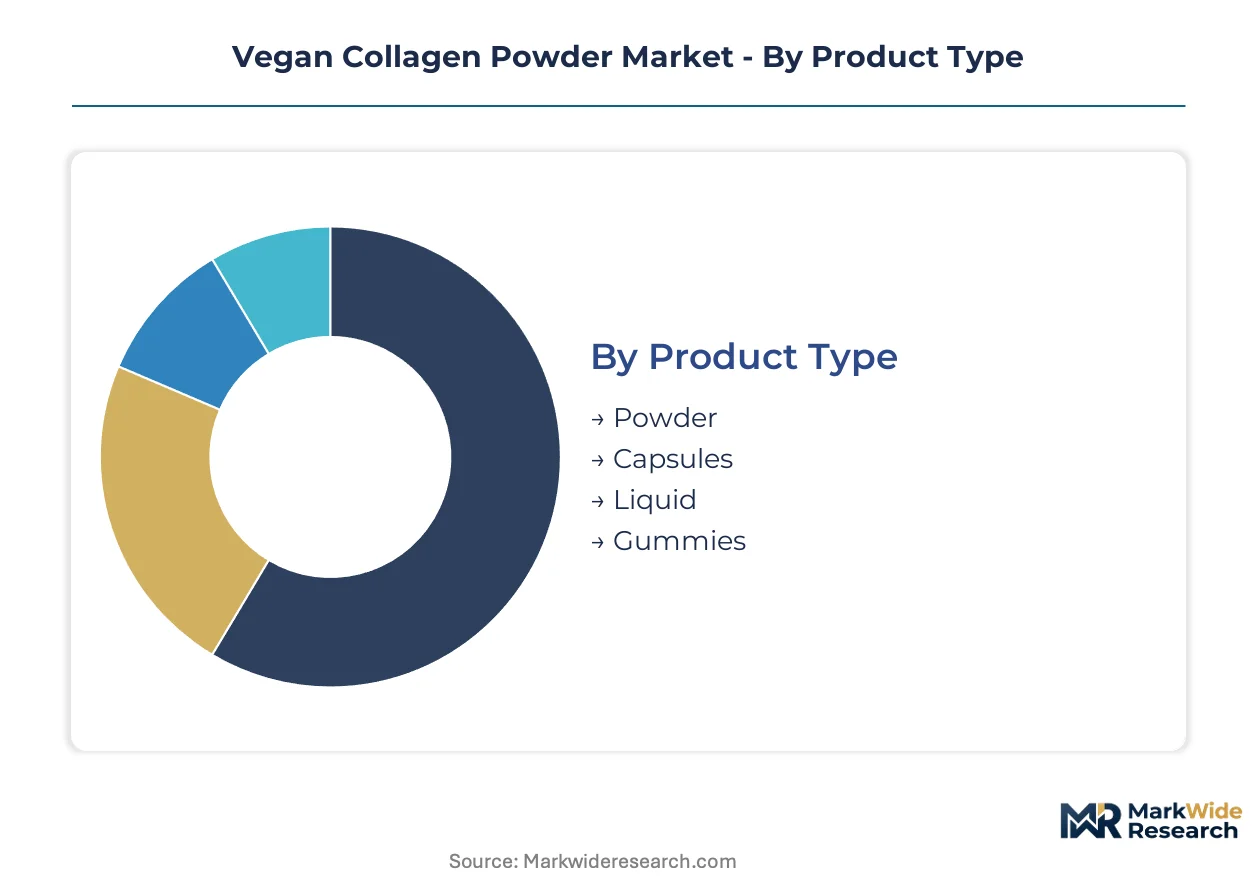
Vegan collagen powder segmentation reveals how formulation choices, sourcing strategies, and channel access determine pricing power and customer acquisition costs across distinct buyer cohorts. Manufacturers must align R&D investments with the specific technical and positioning requirements of each segment cluster.
Product Type:
Powder formulations dominate domestic manufacturing footprints across North American and European facilities, while liquid and gummy formats increasingly ship from contract manufacturers in Asia-Pacific to serve export-led beauty markets.
- Powder:Glycine-proline-hydroxyproline amino acid matrices delivered in bulk format enable flexible dosing and cost-efficient unit economics. Demand concentrates in United States fitness and wellness segments where consumers self-blend into smoothies and beverages, driven by subscription-direct replenishment models that reward format standardization.
- Liquid:Ready-to-drink collagen shots with stabilized peptide suspensions target convenience-oriented beauty consumers seeking on-the-go consumption. European pharmacy channels and United States urban wellness boutiques drive trial, constrained by shorter shelf lives and cold-chain shipping requirements that inflate landed costs.
- Capsules:Encapsulated vegan collagen builders deliver pre-measured amino acid doses for precision-focused supplement regimens.
- Gummies:Confectionery-format delivery systems mask functional ingredients with flavor-forward positioning for reluctant pill-takers.
Powder commands the established base. The steepest expansion runs through Gummies.
Source:
Cost tier stratification separates commodity plant proteins from precision-fermented inputs, with margin structures diverging by an order of magnitude between agricultural extraction and biotech platforms.
- Pea Protein:Yellow split pea isolate provides cost-efficient glycine and proline precursors through mechanical separation and enzymatic hydrolysis. Volume concentrates in mass-market United States retailers where price-per-serving sensitivity dominates purchase decisions, constrained by incomplete amino acid profiles requiring formulation fortification.
- Seaweed Extract:Marine-derived polysaccharides and mineral complexes deliver clean-beauty positioning with ocean-origin storytelling. Premium skincare brands in France and South Korea drive adoption, supported by sustainable harvesting certifications that command shelf placement in prestige channels.
- Rice Protein:Brown rice hydrolysate offers hypoallergenic alternatives for legume-intolerant consumers across Asian and North American markets.
- Corn Protein:Zein-derived amino acid fractions leverage abundant North American feedstock for cost-optimized mainstream formulations.
Pea Protein anchors volume accessibility. The fastest value capture runs through Seaweed Extract.
End User:
Application intensity varies dramatically across user types, with beauty consumers driving repeat purchase frequency that exceeds traditional sports nutrition cohorts by multiples.
- Beauty Consumers:Skincare-focused buyers seeking dermal elasticity and anti-aging outcomes through ingestible collagen support. Demand clusters in United States coastal metropolitan markets and German urban centers where influencer-driven wellness culture accelerates trial-to-habit conversion, constrained by efficacy skepticism requiring clinical substantiation investments.
- Fitness Enthusiasts:Recreational athletes prioritizing joint recovery and connective tissue resilience alongside protein intake. United States CrossFit and yoga practitioner communities sustain volume, though growth rates lag beauty segments as functional positioning proves harder to differentiate.
- Athletes:Competitive and professional sports participants requiring NSF Sport or Informed Sport certification for anti-doping compliance.
- Vegans:Ethically motivated consumers rejecting all animal-derived inputs regardless of functional equivalence claims.
Fitness Enthusiasts represent the legacy core. Beauty Consumers deliver the steepest expansion trajectory.
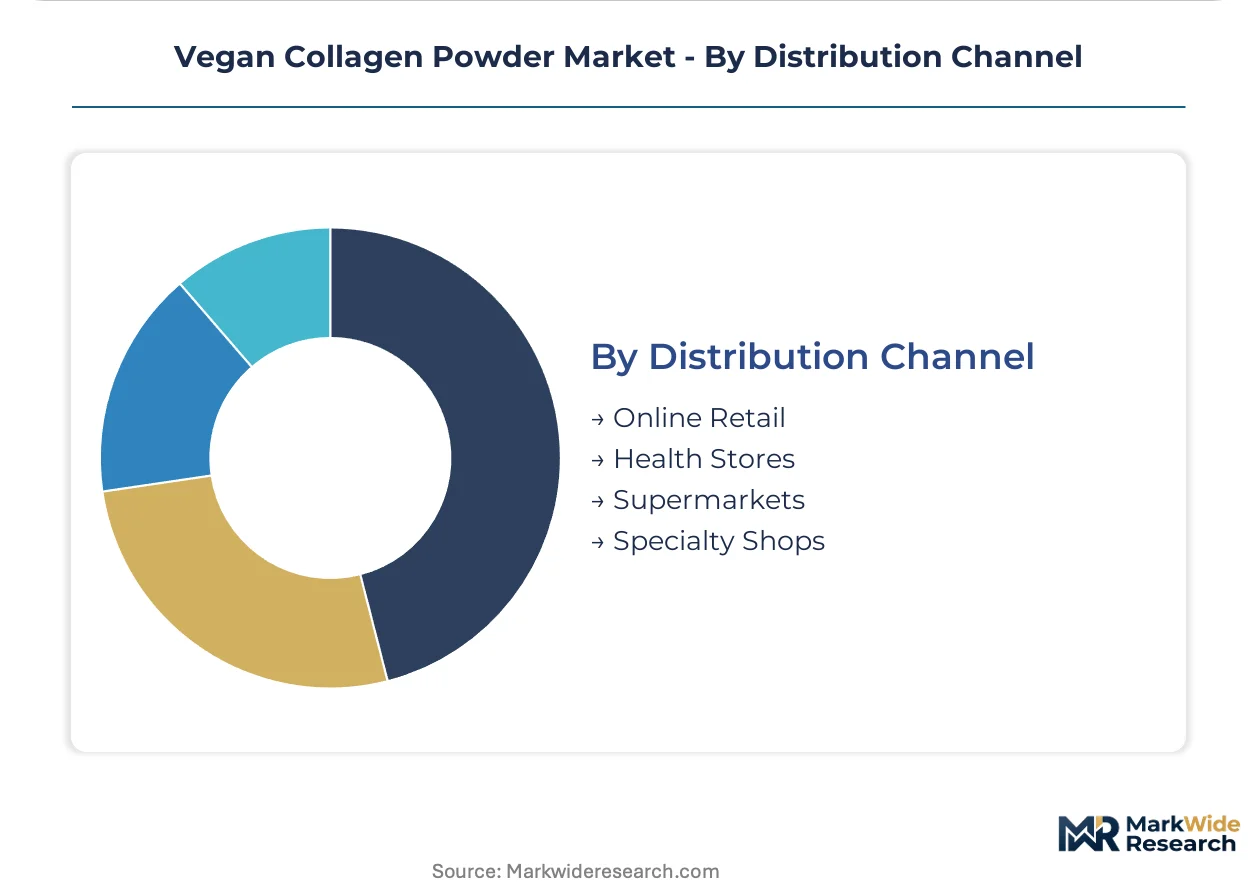
Distribution Channel:
Customer type concentration shapes channel economics, with digitally native beauty brands capturing lifetime value through subscription retention while brick-and-footprint retailers secure impulse trial.
- Online Retail:Direct-to-consumer and marketplace platforms enabling personalized dosing protocols and auto-replenishment scheduling. United States urban millennials and Gen Z buyers drive disproportionate share, with influencer affiliate codes and TikTok discovery mechanics reducing customer acquisition costs versus traditional advertising.
- Health Stores:Specialized supplement retailers staffed by trained associates capable of explaining fermentation-derived collagen science. Germany's pharmacy-adjacent Reformhäuser and United States regional chains like Sprouts anchor presence, constrained by slotting fee structures that disadvantage emerging brands.
- Supermarkets:Mass-market grocery placement democratizing access through everyday shopping missions.
- Specialty Shops:Curated beauty boutiques and clean-lifestyle concept stores prioritizing editorial merchandising over SKU breadth.
Health Stores secure the established premium base. Online Retail captures the fastest volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotech fermentation capacity clusters in contract manufacturing facilities across three continents, with regulatory divergence creating 18-24 month entry gaps between the United States and European Union markets. Consumer trial rates vary dramatically by geography, driven by clean-label certification maturity and influencer ecosystem density.
United States
Beauty consumers in coastal metropolitan markets drive trial-to-habit conversion faster than fitness segments, with subscription-direct models capturing lifetime value through auto-replenishment. FDA dietary supplement labeling requirements and structure-function claim oversight shape formulation decisions, while USDA Organic certification accelerates mass-market retail access. California's Los Angeles-San Francisco corridor anchors influencer-driven wellness culture, where TikTok discovery mechanics reduce customer acquisition costs for digitally native brands.
Germany
Pharmacy-adjacent Reformhäuser sustain premium positioning for plant-based nutrition products despite underpenetration of vegan collagen powders in the channel. EFSA novel food approval timelines for fermented collagen alternatives delay market entry, though EU Green Deal agricultural transition incentives favor biotech proteins over livestock inputs. Bavaria's Munich-Stuttgart industrial corridor concentrates precision fermentation R&D facilities serving European beauty brands.
France
Prestige skincare brands in Paris drive adoption of marine-origin collagen alternatives with clean-beauty storytelling and sustainable harvesting certifications. ANSM oversight of novel food ingredients intersects with EU-wide EFSA safety dossier requirements for recombinant yeast strains. The Île-de-France region anchors formulation science partnerships between biotech suppliers and luxury cosmetics houses.
South Korea
Seoul's beauty innovation ecosystem accelerates ingestible collagen product development, with consumers showing high receptivity to fermentation-derived functional ingredients. MFDS novel food regulatory frameworks evaluate microbial collagen alternatives alongside traditional supplement categories. The Seoul Capital Area concentrates contract manufacturing capacity serving export-led beauty markets across Asia-Pacific.
United Kingdom
London's wellness boutique density supports trial-oriented beauty consumers seeking convenience-positioned collagen formats, though post-Brexit regulatory divergence from EU novel food approvals creates compliance complexity. The Food Standards Agency evaluates fermented protein safety dossiers independently of EFSA timelines. Southeast England's Greater London-Cambridge corridor anchors clean-label supplement brand headquarters and direct-to-consumer logistics infrastructure.
Vegan Collagen Powder Market Competitive Landscape
Concentration sits with established wellness brands leveraging existing collagen equity to cross-sell plant-derived lines, while biotech specialists anchor the supply side through microbial fermentation IP. The competitive structure splits between premium-positioned beauty nutrition players and cost-optimized mass-market protein suppliers. Three archetypes dominate: legacy collagen brands diversifying into vegan portfolios, precision-fermentation technology licensors, and raw-ingredient plant protein formulators. Dominant competitive moves include portfolio diversification into adjacent beauty-from-within categories and strategic partnerships between consumer brands and biotech ingredient suppliers.
Within the legacy wellness brand tier, Vital Proteins and Garden of Life exemplify archetypes of established collagen equity holders extending into plant-derived offerings. Sunwarrior occupies a position among raw-ingredient specialists targeting ingredient-conscious buyers through minimal processing narratives. Geltor anchors the precision-fermentation supply tier as a technology licensor enabling bio-identical peptide production without agricultural inputs.
| Leading Market Players |
|---|
| Vital Proteins |
| Garden of Life |
| Sunwarrior |
| Moon Juice |
| Geltor |
| Ancient Nutrition |
| Orgain |
| NeoCell |
| Revive Collagen |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity utilization rates above eighty percent in United States contract manufacturing facilities create scale economies that compress unit costs for bio-identical collagen peptides, concentrating pricing power among biotech suppliers while squeezing margin structures for brands dependent on agricultural protein extraction.
Pricing Analysis
Volume-discount tiering structures separate subscription-direct replenishment models from mass-market retail, with beauty consumers accepting fifteen to twenty percent premiums for personalized dosing protocols and auto-replenishment scheduling. Price differentiation hinges on certification grade—USDA Organic and NSF Sport validation—and brand equity derived from influencer endorsement density. Pricing pressure intensifies in the pea protein segment as commodity feedstock volatility transmits through mechanical separation supply chains. Fitness enthusiasts exhibit highest price sensitivity per-serving, while prestige beauty consumers demonstrate lowest elasticity for marine-origin positioning.
Supply Chain Analysis
United States and Germany anchor precision fermentation R&D and contract manufacturing capacity for microbial collagen platforms, while China and South Korea concentrate plant-protein extraction and gummy-format contract manufacturing for export-led beauty markets. Raw material dependencies center on sugar feedstocks for yeast fermentation, yellow split pea isolate for mass-market formulations, and sustainably harvested seaweed polysaccharides for premium positioning. Single-source vulnerability concentrates in recombinant yeast strain IP held by limited biotech licensors. Distribution runs through subscription-direct platforms capturing lifetime value, with health stores and pharmacy-adjacent retailers securing impulse trial in Germany and United States urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan collagen powder incumbents face substitution defense imperatives as precision-fermented bio-identical peptides displace both animal-derived collagen and commodity plant proteins across beauty and wellness applications.
For Market Incumbents: Compound brand equity in established collagen categories to cross-sell plant-derived lines through premium positioning that leverages existing consumer trust. Secure captive fermentation capacity through backward integration into United States biotech manufacturing or exclusive offtake agreements with Geltor-style platform licensors. Defend against precision-fermentation specialists by accelerating clinical substantiation investments that address efficacy skepticism among beauty consumers.
For New Entrants and Emerging Players: Lead with underpenetrated geography in Germany's pharmacy-adjacent Reformhäuser channel, where clean-beauty consumer density exceeds vegan collagen powder availability. Target white-space in liquid and gummy formats for European convenience-oriented beauty consumers constrained by cold-chain shipping requirements that disadvantage incumbent powder specialists. Deploy influencer affiliate codes and TikTok discovery mechanics to reduce customer acquisition costs versus traditional advertising in United States urban markets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-fermentation platform licensors with recombinant yeast strain IP and regulatory submission expertise over commodity plant-protein formulators facing margin compression. Long-term viability across the next decade hinges on EFSA novel food approval navigation capabilities and AI-driven strain optimization R&D pipelines. Monitor EFSA safety dossier acceptance rates for recombinant yeast strains as the critical inflection signal distinguishing scalable biotech suppliers from stranded plant-extraction incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Licensing | Enables bio-identical peptide production without agricultural inputs, anchoring supply-side defensibility. |
| Dual Certification Investment | USDA Organic plus NSF Sport validation accelerates mass-market retail access and athlete segment penetration. |
| Subscription-Direct Channel Buildout | Captures lifetime value through auto-replenishment and personalized dosing protocols for beauty consumers. |
| Clinical Substantiation Partnership | Addresses efficacy skepticism through dermatological study investments that support structure-function claims. |
| AI-Driven Strain Optimization | Promises yield improvements through machine learning applied to recombinant yeast metabolic pathway engineering. |
Research Methodology
The analysis maps precision-fermentation technology platforms, plant-protein extraction supply chains, and beauty-from-within distribution channels, each validated through fermentation scientists, supplement brand product developers, health store category buyers, and regulatory affairs specialists. Primary interview intelligence triangulates against FDA structure-function claim filings, EFSA novel food submission databases, USDA Organic certification registries, and Nielsen retail audit data tracking supplement velocity in United States mass-market channels. Bottom-up segment sizing reconciles with top-down market value estimates across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including customs records for plant-protein imports, contract manufacturing capacity disclosures, and beauty supplement subscription growth metrics. The analytical framework models product type, source material, end-user application, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-level growth rate synthesis applied to base-year sizing, with inputs including sugar feedstock price indices, influencer marketing spend trajectories, and clean-label certification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EFSA regulatory clarity, stable fermentation input costs, and continued influencer-driven wellness culture traction would require recalibration. Forecasts reflect documented assumptions regarding biotech scale-up timelines and consumer trial-to-habit conversion rates. Recalibration cycles align with material shifts in novel food approval timelines, precision-fermentation yield breakthroughs, and subscription-direct channel economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Smart Nutrition Scale Market