
 Snack Pellets Market | 2026-2036
Snack Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Pellets Market Intelligence
Expanded production capacity in Southeast Asian countries, including Vietnam and Indonesia, is fragmenting the traditional European-centric supply base for snack pellets. Intersnack Group GmbH & Co. KG sustains its dominant European market position through extensive, long-standing distribution networks. Limagrain Ingredients differentiates itself by specializing in functional cereal ingredients, particularly novel pulse-based and ancient grain formulations. LIVEN S.A. leverages its significant manufacturing scale in extrusion to supply multinational food manufacturers with consistent, high-volume products.
Snack pellets are non-expanded, intermediate food products manufactured primarily through the process of extrusion cooking. These dense, semi-finished items, typically composed of starches from corn, wheat, or potato, require a final expansion step like frying or hot air puffing. Pulse-based formulations are rapidly gaining share over traditional corn-based pellets, meeting demand from food manufacturers for higher protein content. Extruded pellets represent the largest product type, forming the backbone of supply for branded retail snack products.
Regulations from the U.S. FDA and the European Food Safety Authority (EFSA) govern allowable ingredients, processing aids, and mandatory allergen labeling. In tandem, GB standards in China and FSSAI rules in India influence formulation choices related to salt, fat, and contaminants. Producers must now decide whether to invest in flexible manufacturing lines for diverse raw materials or to specialize in high-volume, single-ingredient pellet production.
Market Dynamics
The fundamental market dynamic is the tension between high-volume, low-cost production of traditional corn and potato-based pellets and the formulation shift towards higher-value, nutrient-dense pulse-based alternatives. This transition is driven by food manufacturer demand for healthier intermediate products to meet consumer wellness preferences.
Growth Catalysts
- Foodservice Expansion:Growth in the global quick-service restaurant industry creates sustained demand for snack pellets as inputs for side dishes, meal kits, and convenience snack offerings that require rapid, final-stage preparation like frying.
- Pulse-Based Formulations:The development of novel pellets using lentils, chickpeas, and peas directly addresses consumer and food manufacturer demand for snacks with higher protein content, cleaner labels, and gluten-free attributes.
- Emerging Market Demand:Snack manufacturers in Brazil and India are increasing procurement of pellets, creating demand for formulations tailored to local taste profiles and regional raw material availability, moving beyond globally standardized products.
Market Restraints
- Raw Material Price Volatility:Fluctuation in the pricing of key agricultural commodities, including corn, wheat, and pulses, directly impacts production costs and profit margins for pellet manufacturers, creating financial instability.
- Regulatory Compliance Burden:Navigating the divergent and complex food safety regulations of the FDA, EFSA, and FSSAI concerning ingredients, processing aids, and contaminants increases the cost and time-to-market for new products.
- Substitution from Direct Extrusion:Large snack manufacturers may opt for in-house direct extrusion of finished snacks, bypassing the need for intermediate pellets and thus posing a significant substitution threat to pellet suppliers.
Strategic Opportunities
- Ancient Grain Formulations:Developing pellets from ancient grains like quinoa, amaranth, and sorghum offers a pathway to differentiate products with unique textures, nutritional benefits, and compelling marketing narratives beyond the current pulse trend.
- Southeast Asian Market Penetration:Beyond being production hubs, countries like Indonesia and Vietnam represent significant untapped consumer markets with a growing middle class and increasing appetite for packaged, convenient snacks.
- Functional Ingredient Specialization:There is an opportunity for suppliers to specialize in pellets fortified with functional ingredients such as fiber, probiotics, or vitamins, targeting niche health and wellness snack categories.
Industry Challenges
- Manufacturing Flexibility Investment:Producers face the costly decision of whether to invest in flexible extrusion lines capable of handling diverse raw materials or to specialize in high-volume, single-ingredient production, risking market agility.
- Allergen Management Complexity:Adhering to mandatory allergen labeling laws from regulators like the EFSA requires stringent, costly production scheduling and cleaning protocols to prevent cross-contamination, especially on multi-product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Pellets Market |
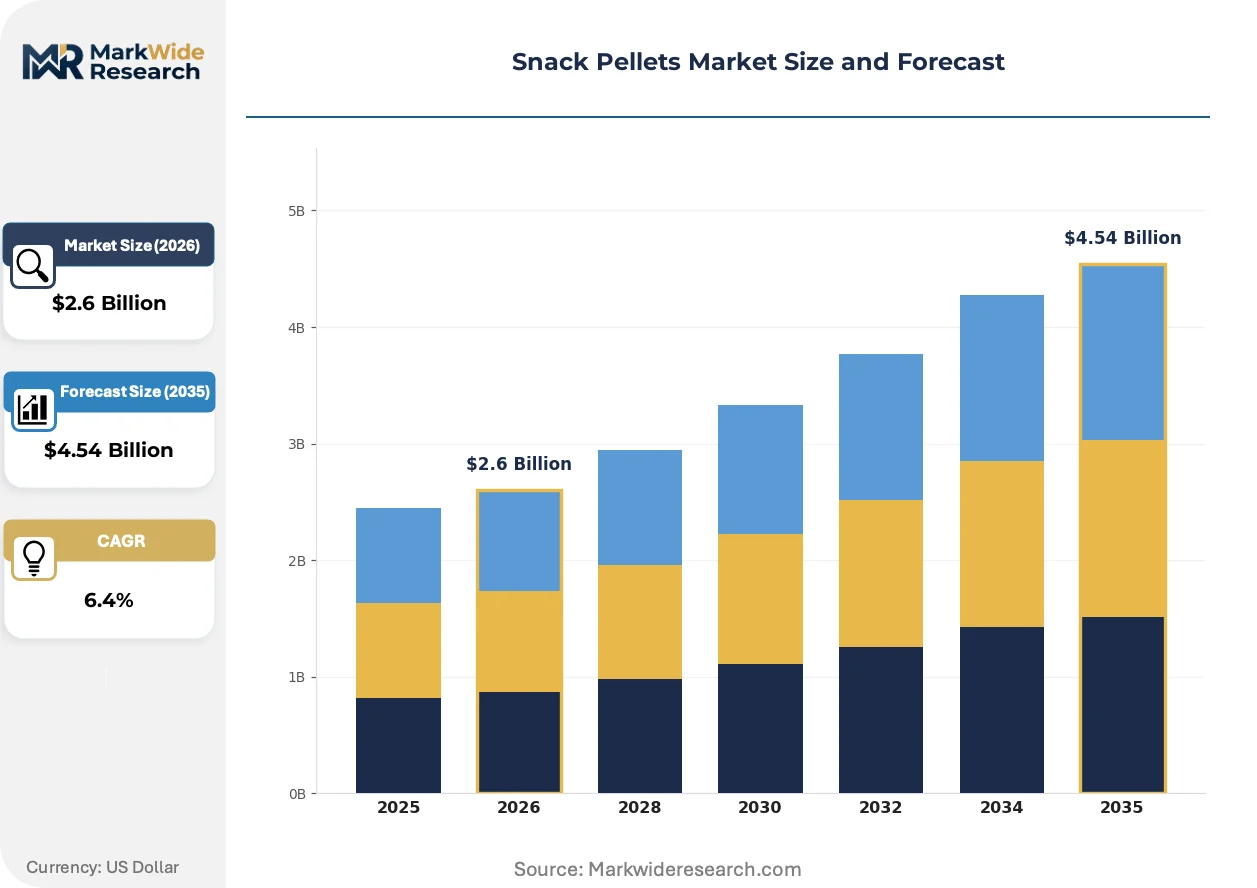
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Pellets, Puffed Pellets, Baked Pellets, Fried Pellets, Flavored Pellets Formulation: Corn-Based, Rice-Based, Wheat-Based, Mixed Grain, Pulse-Based Application: Retail Snacks, Institutional Catering, Foodservice Industry, Convenience Foods, Ready-to-Eat Products Customer Type: Food Manufacturers, Snack Distributors, Vending Operators, Hospitality Chains, Specialty Stores |
| Companies Covered | LIVEN S.A., Intersnack Group GmbH & Co. KG, Limagrain Ingredients, Akkel Group, Le Caselle, J.R. Short Milling Company, Quality Pellets A/S, Dalmaza Food Industries Company, Pasta Foods Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Pellets Market Strategic Shifts & Innovations
Ingredient science and extrusion process advancements are converging, enabling the creation of snack pellets with precisely engineered textures and nutritional profiles. This allows food manufacturers to meet specific consumer demands for both indulgence and health, moving beyond traditional commodity-based products.
Multi-grain and vegetable-based formulations, combining ingredients like corn, rice, and spinach powder in a single pellet, are a key product evolution. Snack brands targeting health-conscious millennials and families are rapidly adopting these composite pellets for their new product lines. This technology is hybridizing the familiar texture of traditional snacks with enhanced nutritional value, creating a new class of permissible indulgence items.
Front-of-pack nutritional labeling schemes, including the EU's Nutri-Score and similar systems in Latin America, are influencing pellet formulation. These regulations compel manufacturers to reduce sodium, saturated fat, and sugar to achieve more favorable consumer-facing scores. Potato and corn-based pellet producers are most impacted, accelerating their investment in formulations compatible with hot air puffing over traditional deep frying.
A demand-side shift toward clean-label products is altering procurement patterns for snack pellets. Major food brands now require pellets made from simple, recognizable ingredients, avoiding artificial colors, flavors, and preservatives. This disrupts the commodity supply model, favoring pellet producers who can provide certified non-GMO or organic raw materials with full traceability. This trend is most pronounced in North American and Western European retail markets.
Snack Pellets Market Segmentation
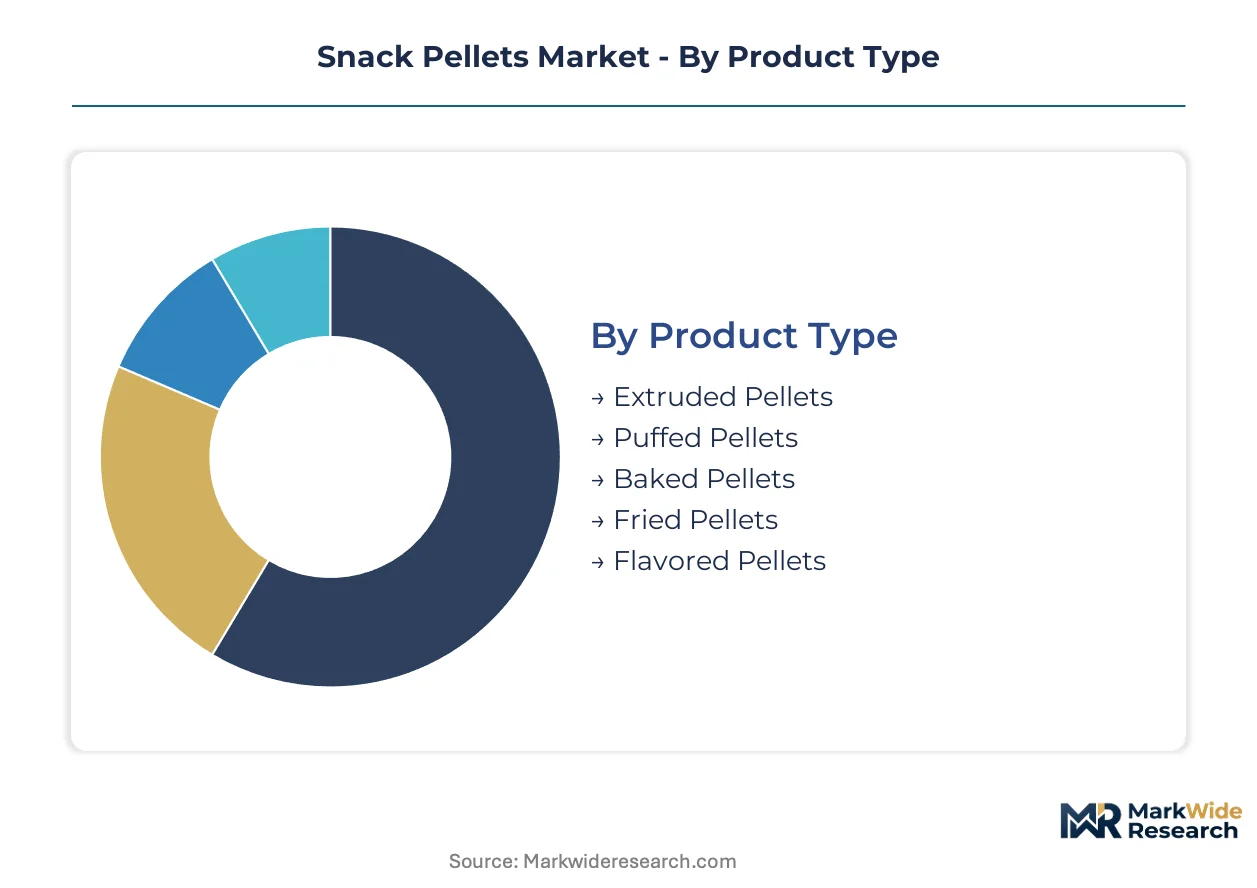
The Snack Pellets Market segmentation reveals diverse product types, formulations, applications, and customer bases. Understanding these segments is crucial for manufacturers to tailor offerings, optimize production processes, and target specific demand pockets. This granular view helps identify areas of high growth and competitive intensity.
Product Type:
The spectrum of snack pellet products reflects varying processing methods and desired final textures for consumer snacks.
- Extruded Pellets:These dense, semi-finished items are manufactured through extrusion cooking, primarily composed of starches from corn, wheat, or potato. They form the backbone of supply for branded retail snack products, driven by their versatility and consistent quality for multinational food manufacturers.
- Puffed Pellets:These pellets are designed for final expansion via hot air puffing, resulting in a light, airy texture and lower fat content. Demand concentrates in North American and Western European markets, influenced by front-of-pack nutritional labeling schemes pushing for reduced fat.
- Baked Pellets:These pellets are processed for a crisp texture through baking, appealing to health-conscious consumers seeking non-fried options.
- Fried Pellets:These traditional pellets are designed for deep frying as a final preparation step, delivering a rich, indulgent texture.
- Flavored Pellets:These pellets incorporate flavorings directly during manufacturing, offering a ready-to-consume or semi-finished flavored snack base.
The dominant share belongs to Extruded Pellets, while Puffed Pellets are closing the gap fastest.
Formulation:
Pellet formulation strategies are increasingly influenced by raw material availability and evolving nutritional preferences.
- Pulse-Based:These formulations utilize legumes like lentils, chickpeas, and peas, providing higher protein content and often gluten-free attributes. Food manufacturers drive demand for these healthier intermediate products, particularly in markets like India and Brazil, to meet consumer wellness preferences.
- Corn-Based:Formulations primarily derived from corn starch, representing a traditional and high-volume raw material for snack pellet production. These pellets are widely used in the foodservice industry for quick-service and convenience food applications due to their cost-effectiveness and versatility.
- Rice-Based:Rice-based formulations offer a gluten-free alternative, contributing to diverse textures for snack products.
- Wheat-Based:Wheat-based pellets provide a familiar texture and are a staple in many traditional snack applications.
- Mixed Grain:These formulations combine multiple grains, such as corn and rice, to achieve unique textural and nutritional profiles for snack brands.
The shift towards healthier options positions Pulse-Based formulations for significant expansion, while Corn-Based formulations maintain their foundational role.
Application:
The varied end-use scenarios for snack pellets reflect the diverse channels through which consumers access snack products.
- Retail Snacks:This application involves pellets supplied to snack brands for final processing into packaged, shelf-stable consumer products sold in supermarkets. It represents the largest segment, driven by consumer appetite for convenience and new product innovation in North American and European retail markets.
- Foodservice Industry:Pellets are provided to quick-service restaurants, cafes, and institutional kitchens for on-demand preparation into side dishes or meal components. Growth in the global quick-service restaurant industry creates sustained demand for rapid, final-stage preparation.
- Convenience Foods:Pellets are integrated into meal kits and ready-to-heat products, catering to consumers seeking easy and quick meal solutions.
- Ready-to-Eat Products:This application covers pellets that undergo final expansion and flavoring to be consumed directly without further preparation.
- Institutional Catering:Pellets are supplied to large-scale catering operations for schools, hospitals, and corporate cafeterias, providing cost-effective snack components.
Demand concentration remains high within Retail Snacks, with the Foodservice Industry showing consistent expansion.
Customer Type:
Procurement patterns for snack pellets vary significantly across different customer types, reflecting their scale, distribution needs, and product portfolios.
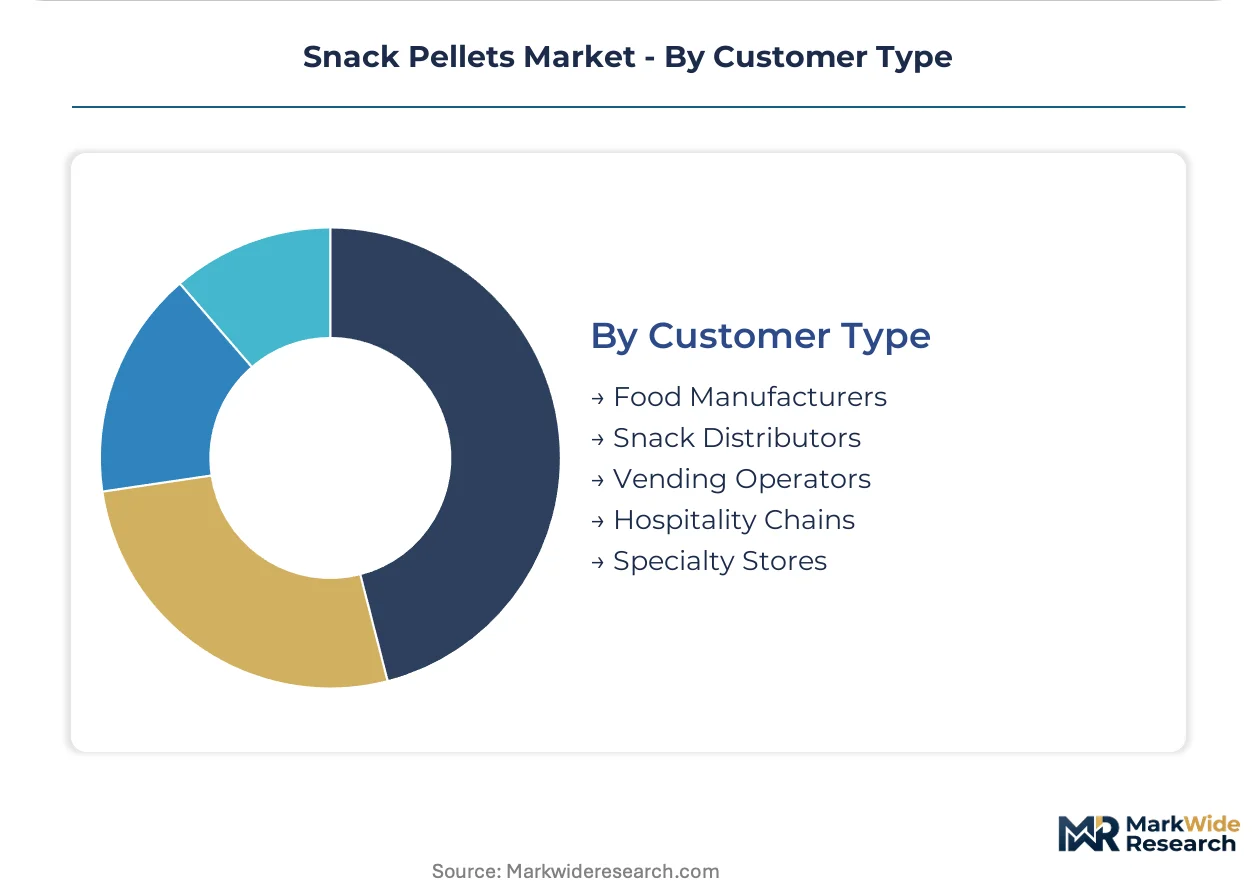
- Food Manufacturers:These customers are large-scale producers of branded snack products, requiring consistent, high-volume supply of intermediate pellets for their manufacturing lines. Their demand for novel pulse-based formulations is driving innovation in healthier intermediate products to meet consumer wellness preferences.
- Snack Distributors:These entities purchase pellets in bulk and distribute them to smaller snack producers, regional brands, or specialized retailers. They play a critical role in reaching diverse market segments, particularly in fragmented markets or those with complex logistics.
- Vending Operators:These customers procure pellets for final processing into snacks suitable for vending machines, focusing on convenience and shelf life.
- Hospitality Chains:Hotels, resorts, and cruise lines utilize snack pellets for in-house snack preparation or as components in their food offerings.
- Specialty Stores:These retailers often source unique or niche pellet formulations, including organic or ancient grain varieties, to cater to specific consumer preferences.
The market relies heavily on Food Manufacturers, while Snack Distributors facilitate broader market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix differential for snack pellets varies significantly across geographies, with some regions prioritizing healthier, pulse-based options while others maintain demand for traditional corn and potato formulations. This market dynamic influences procurement patterns and production investments in specific countries. Emerging markets are also driving demand for locally tailored taste profiles.
United States
Demand for snack pellets in the United States is driven by health-conscious consumers seeking clean-label products and high-protein snacks within the retail segment. U.S. FDA regulations govern allowable ingredients, processing aids, and mandatory allergen labeling for food products. Food innovation hubs in California are actively developing novel formulations and textures for the domestic market.
India
Snack manufacturers in India are increasing procurement of pellets, creating demand for formulations tailored to local taste profiles and regional raw material availability. FSSAI rules influence formulation choices related to salt, fat, and contaminants in packaged snacks. Major food processing clusters in Mumbai and Delhi are concentrating efforts on pulse-based pellet production to meet consumer wellness preferences.
Germany
The German market sustains a strong demand for snack pellets, particularly for traditional European snack applications, supported by extensive distribution networks. The European Food Safety Authority (EFSA) mandates stringent allergen labeling and ingredient compliance for all food products. Intersnack Group GmbH & Co. KG, based in Düsseldorf, maintains a dominant European market position.
Brazil
Food manufacturer demand in Brazil is shifting towards healthier intermediate products, including pulse-based snack pellets, to meet evolving consumer preferences. ANVISA (Brazil's National Health Surveillance Agency) influences ingredient and processing standards for food items. Snack manufacturers in São Paulo are actively procuring pellets tailored to regional tastes and dietary trends.
Vietnam
Vietnam is experiencing expanded production capacity for snack pellets, driven by a growing middle class and increasing appetite for packaged, convenient snacks. The country's Ministry of Health sets food safety and quality standards for processed food products. Ho Chi Minh City is emerging as a significant production and export hub for snack pellets in Southeast Asia.
Snack Pellets Market Key Industry Players
Capability concentration sits with one tier, particularly for specialized ingredient innovation, while scale advantage sits with another, enabling high-volume, cost-effective production. The snack pellets market exhibits a tiered structure, with global multinational suppliers, regional specialists, and niche ingredient innovators comprising the main archetypes. Capacity expansion and portfolio diversification represent dominant competitive moves.
At the scale-driven end, LIVEN S.A. leverages its significant manufacturing scale in extrusion to supply multinational food manufacturers with consistent, high-volume products. Intersnack Group GmbH & Co. KG exemplifies a company sustaining a dominant European market position through extensive, long-standing distribution networks. Limagrain Ingredients represents a specialist in functional cereal ingredients, particularly novel pulse-based and ancient grain formulations.
| Leading Market Players |
|---|
| LIVEN S.A. |
| Intersnack Group GmbH & Co. KG |
| Limagrain Ingredients |
| Akkel Group |
| Le Caselle |
| J.R. Short Milling Company |
| Quality Pellets A/S |
| Dalmaza Food Industries Company |
| Pasta Foods Ltd. |
| Others |
Cost & Logistics Intelligence
Expanded production capacity in Southeast Asian countries like Vietnam and Indonesia drives competitive supplier behavior and influences pricing posture across the snack pellets market. This increased regional capacity provides more cost-effective production options for global food manufacturers.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-volume snack pellet procurement, providing stability for large food manufacturers. Price differentiation stems from certification levels, such as non-GMO or organic, and the customization level for specific taste profiles. Pricing softness emerges from increased global supply, though raw material price volatility for pulses and grains creates upward cost pressure. Food manufacturers seeking commodity corn-based pellets exhibit high price sensitivity, while brands requiring specialized pulse-based formulations are less sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the working capital needs of snack pellet manufacturers, particularly in emerging production hubs. Geographic supply concentration includes Southeast Asia (Vietnam, Indonesia) for production volume and India and Brazil for demand-side manufacturing. Raw material dependencies center on corn, wheat, potato starches, lentils, and chickpeas. Commodity price volatility presents a structural supply chain risk. Distribution occurs directly to large food manufacturers or through snack distributors to smaller regional producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the sustained penetration of convenience food offerings into new consumer demographics. Demand for healthier snack options continues to grow globally.
For Market Incumbents: Harden core market positions by investing in flexible manufacturing lines capable of processing diverse raw materials, mitigating the threat of substitution from direct extrusion. Expand distribution networks, particularly in high-growth emerging markets like Southeast Asia, to leverage existing scale. Develop R&D capabilities for novel pulse-based and ancient grain formulations to meet evolving consumer preferences for healthier, clean-label products.
For New Entrants and Emerging Players: Establish a beachhead in niche health and wellness snack categories, focusing on pellets fortified with functional ingredients such as fiber or probiotics. Target the Southeast Asian consumer market with formulations tailored to local tastes, capitalizing on a growing middle class and increasing packaged snack consumption. Specialize in certified non-GMO or organic raw materials, offering full traceability as a key go-to-market angle for discerning food brands.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialized extrusion capabilities, favoring players with advanced technology for diverse raw materials. The long-term viability of the snack pellets market remains strong, supported by persistent consumer demand for convenient and healthier snack options. Target mid-sized specialists possessing proprietary extrusion technology or unique ingredient expertise in pulse-based or ancient grain formulations. Watch for regulatory shifts, such as stricter front-of-pack nutritional labeling schemes, as a signal of accelerated industry transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Increases cost-effective production and supports regional market penetration. |
| Product Diversification into Ancient Grains | Attracts health-conscious consumers with unique textures and nutritional profiles. |
| Investment in Flexible Manufacturing | Enables producers to adapt to diverse raw materials and evolving formulation demands. |
| Enhanced Traceability and Certification | Meets clean-label demands from major food brands in developed markets. |
| Strategic Partnerships with Ingredient Suppliers | Secures consistent supply of novel pulse-based and specialized raw materials. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings and quantitative projections within this analysis. The methodology combines insights from food manufacturers, snack distributors, extrusion technology providers, and ingredient suppliers. Secondary data sources include regulatory body publications (FDA, EFSA, FSSAI), agricultural commodity reports, and relevant industry association statistics. This approach facilitates bottom-up and top-down triangulation for comprehensive market sizing.
The analytical framework is calibrated to assess market size and growth across the analysis window. Segmentation dimensions modeled include product type, formulation, application, customer type, and regional consumption patterns. Compound annual growth rates (CAGRs) are derived from historical growth patterns and projected demand drivers, accounting for shifts in consumer preferences. Key forecast inputs include raw material availability and regulatory changes in food labeling standards across major markets.
Stress conditions across raw material price volatility and regulatory enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements in extrusion and evolving consumer wellness trends. Unforeseen shifts in global agricultural commodity prices or new food safety regulations could alter projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Granola Bars Market
Snacks
Argentina Snack Bar Market
Snacks
Cereal Bars Market
Snacks
Global Protein Snack Market
Snacks
South Africa Snack Bar Market
Snacks
United States Snack Bar Market
Snacks
Baked Savoury Snacks Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Allergy-Free Snacks Market
Snacks
Cheese Snacks Market
Snacks
Italy Energy Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Meat Protein Chips Market
Snacks
Nachos Market
Snacks
Sweet Potato Chips Market
Snacks
Roasted Corn Market