
 Europe Frozen Snacks Market | 2026-2036
Europe Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Snacks Market Foresight
Premium clean-label tiering is unwinding across the Europe Frozen Snacks Market as consumers reject artificial preservatives and extended ingredient lists. Nestlé S.A. leverages its European R&D network to reformulate classic lines with shorter declarations. Nomad Foods anchors its portfolio through Birds Eye brand strength in the United Kingdom and Nordic markets. Dr. Oetker dominates frozen pizza innovation with specialized stone-baked platforms that compete on restaurant-quality positioning.
Europe frozen snacks comprise pre-cooked or partially prepared food items preserved at sub-zero temperatures, typically formulated with moisture content below ice-crystal damage thresholds and reheated via convection or microwave to restore texture and flavor. The category serves commercial food service operators and retail households seeking extended shelf stability without sacrificing sensory performance. Frozen pizza and meat snack segments command the deepest margin pools due to premiumization potential and protein-forward positioning. Vegetable-based frozen lines represent the fastest-growing structural category as plant-forward dietary patterns expand across Northern European markets. Single-serve container packaging is gaining share within food service channels where portion control and waste reduction drive procurement decisions.
EFSA governs nutritional and health claim substantiation across the European Union, while REACH regulates chemical safety in food-contact packaging materials. The EU Green Deal's packaging waste directives are forcing tray and film conversions toward mono-material recyclable structures, raising compliance costs but creating first-mover advantages for reformulated portfolios. National regulators in France and Germany enforce stricter origin labeling than baseline EU requirements, fragmenting market access rules. Stakeholders must monitor the interplay between Ecodesign packaging standards and consumer willingness to absorb green premium pricing across divergent national retail environments.
Market Dynamics
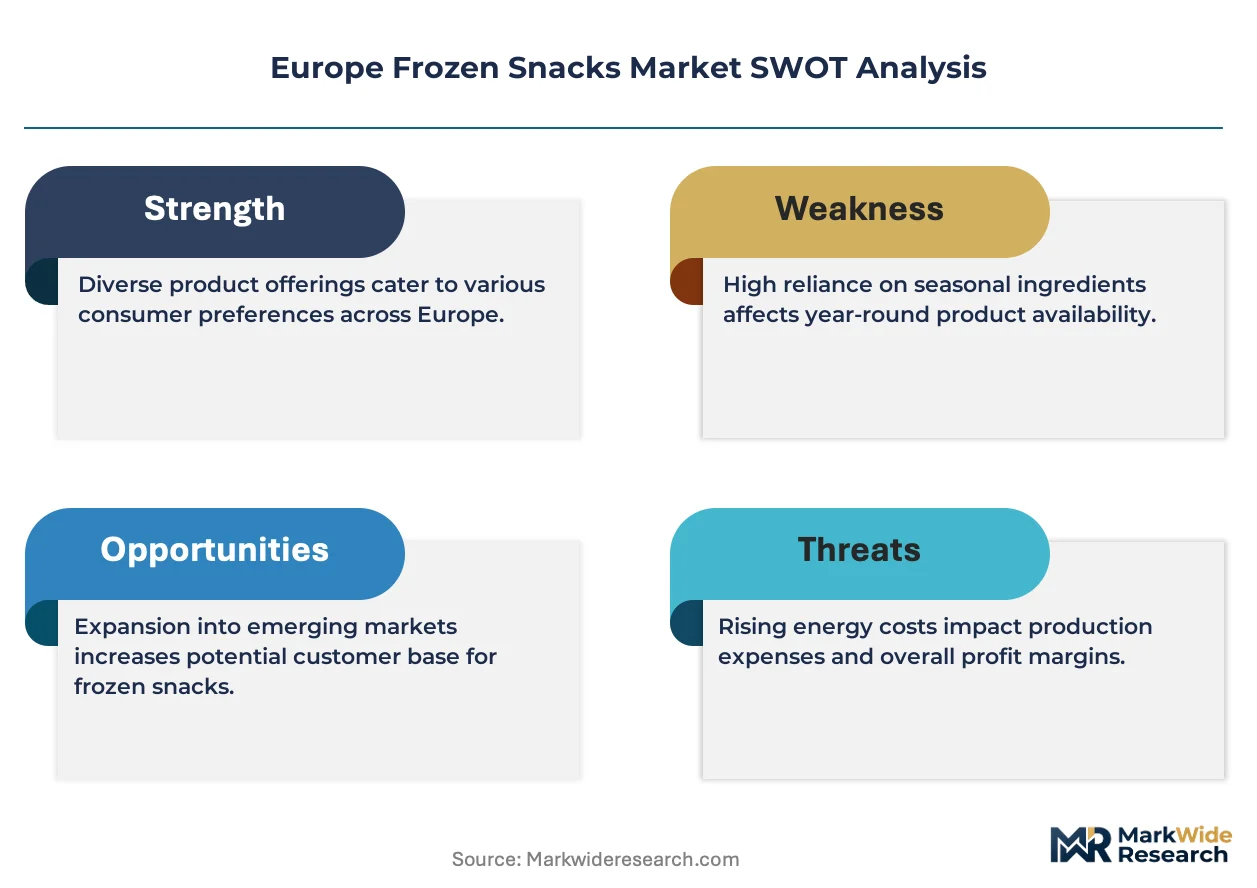
The EU Green Deal's packaging waste directives are forcing a wholesale conversion of frozen snack trays and films toward mono-material recyclable structures, compressing margins for laggards while rewarding early reformulators with retail shelf access and green premium pricing power.
Growth Catalysts
- EFSA nutrition labeling mandates:Clean-label reformulation is accelerating as manufacturers strip artificial preservatives to comply with substantiation rules, opening shelf space for shorter-declaration portfolios.
- Dual-income household concentration in German and French urban centers:Time-scarcity is expanding the addressable market for premium frozen pizza and vegetable lines that restore texture via convection reheating.
- Stone-baked platform technology:Restaurant-quality positioning through specialized oven replication is capturing trade-up demand from food service operators seeking portion-controlled solutions.
Market Restraints
- Mono-material packaging conversion costs:REACH-compliant film and tray redesigns are raising per-unit packaging expenditures by 15-25% before scale economies emerge.
- Energy price volatility:Cold-chain logistics and blast-freezing operations face margin compression from natural gas and electricity input cost swings across Nordic and Central European distribution hubs.
- Private-label substitution:Discounter chains in Germany and the Netherlands are deploying quality-parity frozen snacks at 30-40% price discounts, compressing branded volume.
Strategic Opportunities
- Nordic plant-forward penetration:Sweden and Denmark show underdeveloped frozen vegetable snack per-capita consumption relative to Southern European pizza penetration, creating white space for protein-forward positioning.
- EU Ecodesign standard alignment:Early compliance with forthcoming packaging recyclability benchmarks will unlock preferential listing terms with sustainability-scoring retailers.
- Food service single-serve containerization:Portion-control procurement in French and British institutional channels favors frozen snack formats that reduce plate waste.
Industry Challenges
- Reformulation R&D timeline compression:Accelerated clean-label transitions are straining European food science talent pools and pilot-scale testing capacity.
- Legacy cold-chain asset stranding:Existing blast-freezing infrastructure in older Central European plants faces integration friction with energy-efficient ammonia replacement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Snacks Market |
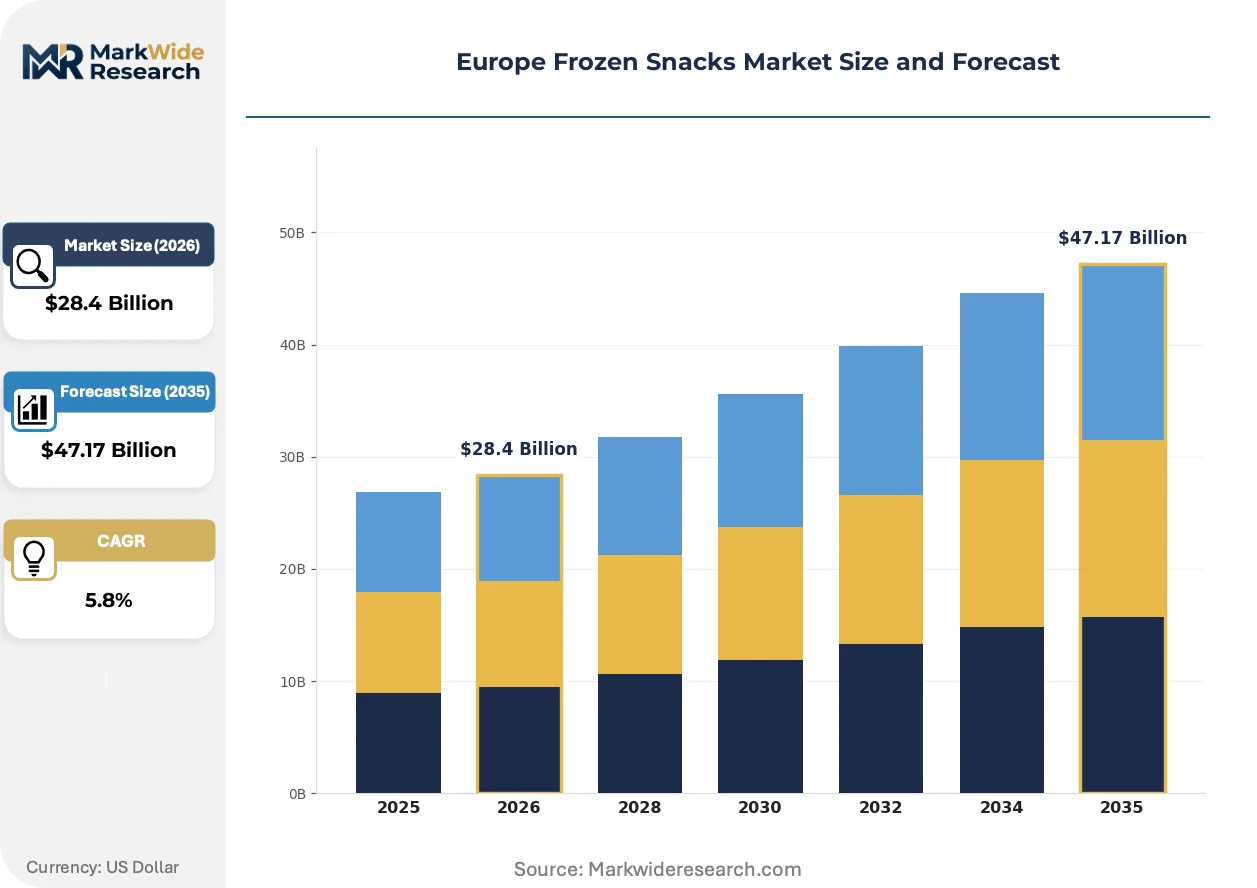
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pizzas, Vegetables, Fruits, Meat Snacks End User: Households, Food Service, Retailers, Catering Services Packaging Type: Frozen Bags, Boxes, Trays, Single-Serve Containers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Nestlé S.A., Nomad Foods, Dr. Oetker, McCain Foods, Orkla ASA, FRoSTA AG, Conagra Brands, General Mills, Unilever PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Snacks Market Shifts & Advancements
Clean-label ingredient substitution and packaging material science are converging to redefine competitive advantage, with regulatory compliance becoming inseparable from product architecture rather than an after-market overlay.
High-pressure processing is displacing traditional thermal pasteurization in premium frozen vegetable lines. Nordic and British retailers are adopting these platforms at accelerated rates to deliver extended shelf stability without chemical preservatives. This shift is compressing the reformulation timeline advantage enjoyed by early clean-label movers and raising the capital barrier for mid-tier manufacturers.
REACH chemical safety assessments for food-contact materials are tightening scrutiny of multi-layer laminated films. Industrial consequence includes forced migration toward mono-material polypropylene or polyethylene structures that satisfy mechanical and barrier requirements without adhesive layers. Frozen pizza manufacturers in Germany and Italy are responding fastest, locking in supply agreements with film converters ahead of 2025 implementation milestones.
Direct-to-food-service procurement platforms are fragmenting traditional distributor gatekeeper roles. British and French institutional buyers are sourcing frozen snacks through digital procurement channels that bypass legacy wholesaler markups. This disintermediation is most visible in urban catering contracts where waste-reduction KPIs favor single-serve frozen formats with transparent origin documentation.
Europe Frozen Snacks Market Segmentation
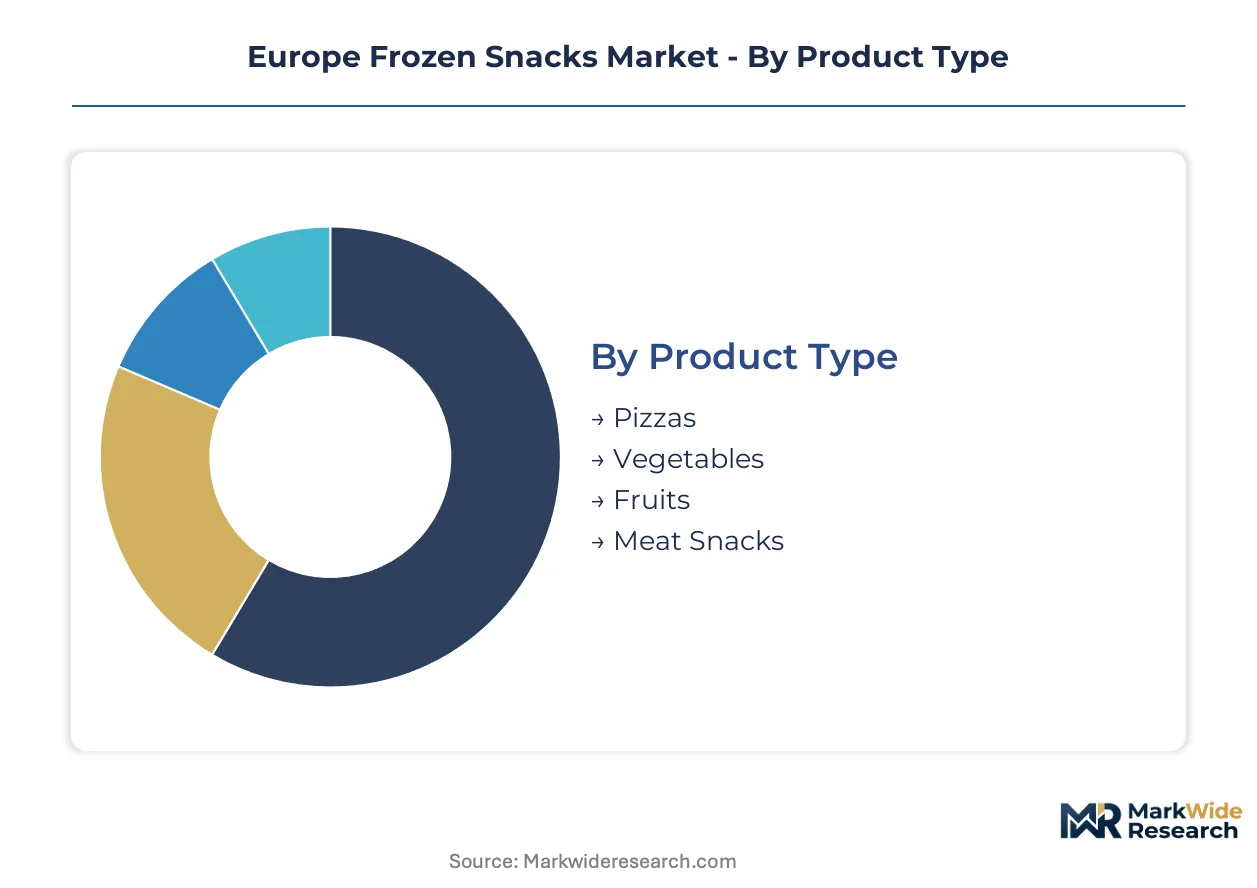
Segmentation in the Europe Frozen Snacks Market reveals how regulatory pressure and channel economics fragment commercial strategy. EFSA labeling rules and EU Green Deal packaging mandates hit different product formats and end-use channels with uneven compliance burdens, forcing portfolio prioritization.
Product Type:
EFSA substantiation requirements for nutrition claims create divergent reformulation timelines across frozen snack formats, with protein-forward and plant-based lines facing distinct technical validation paths.
- Pizzas:Stone-baked and wood-fired platforms command premium positioning through specialized crust technologies that replicate restaurant texture after convection reheating. German and Italian households drive volume concentration, though margin compression from private-label discounter competition in the Netherlands and Belgium limits pricing power expansion.
- Vegetables:High-pressure processing adoption is accelerating across Nordic and British retail channels, delivering clean-label shelf stability without chemical preservatives. Sweden and Denmark show underdeveloped per-capita penetration relative to Southern European markets, creating structural white space for protein-fortified frozen vegetable platforms.
- Fruits:Smoothie-ready frozen fruit blends concentrate in British and French urban retail with breakfast substitution positioning.
- Meat Snacks:Breaded and battered poultry platforms dominate food service procurement in French institutional catering channels.
Pizzas handle the majority of throughput; vegetables are gaining share fastest on plant-forward dietary shifts.
End User:
Cold-chain economics and portion-control requirements segment frozen snack demand across household, commercial, and institutional channels with distinct packaging and logistics specifications.
- Households:Dual-income urban families in German and French metropolitan areas prioritize time-saving meal solutions with convection-ready texture restoration. REACH-compliant mono-material tray adoption is accelerating as retailers impose sustainability scoring on listed suppliers.
- Food Service:Digital procurement platforms are fragmenting traditional distributor gatekeeper roles in British and French urban catering contracts. Waste-reduction KPIs favor single-serve frozen formats with transparent origin documentation and portion-controlled presentation.
- Retailers:Discounter chains in Germany and the Netherlands deploy quality-parity frozen snacks at sharp price discounts, compressing branded manufacturer volume.
- Catering Services:Institutional buyers in French school and hospital channels source through centralized procurement frameworks with strict Ecodesign packaging compliance requirements.
Households absorb the dominant share of frozen snack volume; food service is expanding most quickly on digital procurement disintermediation.
Packaging Type:
EU Green Deal waste directives and REACH chemical safety assessments are forcing structural conversion of frozen snack packaging toward mono-material recyclable architectures with uneven cost recovery timelines.
- Frozen Bags:Multi-layer laminated films face tightening ECHA scrutiny, driving migration toward mono-material polyethylene structures for frozen vegetable lines. Nordic retailers are adopting these platforms at accelerated rates ahead of 2025 implementation milestones.
- Boxes:Paperboard frozen pizza packaging in Italy and Germany locks in supply agreements with converters capable of barrier coating without adhesive layers. Stone-baked platform manufacturers prioritize box rigidity for crust protection through distribution.
- Trays:Mono-material polypropylene conversion is raising per-unit expenditures by 15-25% before scale economies emerge across Central European production networks.
- Single-Serve Containers:Portion-control procurement in French and British institutional channels favors formats that reduce plate waste and simplify origin traceability.
Trays carry the heaviest compliance burden; single-serve containers are climbing the fastest on food service waste-reduction mandates.
Distribution Channel:
Channel economics and regulatory transparency requirements segment frozen snack access, with sustainability scoring and digital procurement reshaping traditional wholesale relationships.
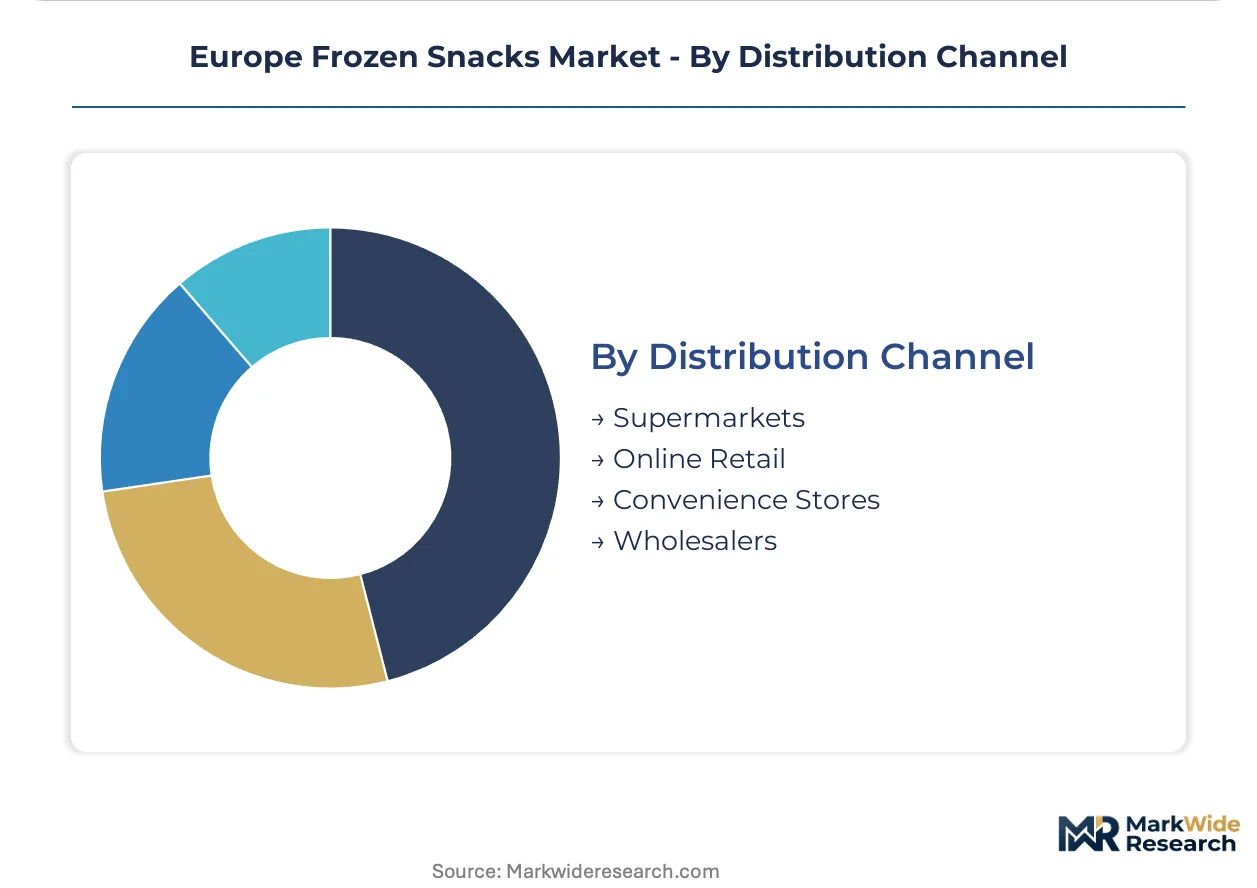
- Supermarkets:Ecodesign standard alignment unlocks preferential listing terms with sustainability-scoring retailers in Germany and France. Clean-label reformulation and mono-material packaging conversion are becoming baseline entry requirements.
- Online Retail:Cold-chain last-mile logistics face margin compression from energy price volatility across Nordic and Central European distribution hubs. Direct-to-consumer frozen snack penetration remains constrained by delivery cost structures.
- Convenience Stores:Urban grab-and-go positioning in British and French city centers favors single-serve frozen formats with microwave-ready preparation.
- Wholesalers:Traditional distributor gatekeeper roles are fragmenting as British and French institutional buyers source through digital procurement channels that bypass legacy markups.
Supermarkets dominate frozen snack throughput; online retail shows the steepest expansion trajectory on platform investment, though profitability remains elusive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blast-freezing infrastructure clusters in Germany and Italy anchor European frozen snack manufacturing capacity, while Nordic markets present underdeveloped penetration for plant-forward lines relative to Southern European pizza consumption baselines.
Germany
Dual-income households in Berlin and Munich drive premium frozen pizza and vegetable line expansion through time-scarcity meal substitution. REACH chemical safety assessments for food-contact packaging materials mandate mono-material tray conversions by 2025. The North Rhine-Westphalia industrial corridor hosts concentrated blast-freezing capacity serving pan-European distribution networks.
France
Urban catering contracts in Paris and Lyon prioritize single-serve frozen formats with transparent origin documentation and waste-reduction KPIs. ANSM enforces stricter origin labeling than baseline EU requirements, fragmenting market access rules for imported lines. The Île-de-France region anchors institutional procurement frameworks with Ecodesign packaging compliance mandates.
United Kingdom
Birds Eye brand strength penetrates retail and food service channels with clean-label reformulated portfolios. EFSA nutrition labeling rules accelerate artificial preservative stripping across frozen vegetable lines. Greater London hosts digital procurement platform adoption that fragments traditional wholesaler gatekeeper roles in urban catering.
Italy
Stone-baked and wood-fired pizza platforms command premium positioning through specialized crust technologies replicating restaurant texture. EU Green Deal packaging waste directives force paperboard barrier coating conversions without adhesive layers. The Emilia-Romagna cluster locks in supply agreements with film converters ahead of implementation milestones.
Sweden
Underdeveloped per-capita frozen vegetable snack consumption relative to Southern European markets creates structural white space for protein-fortified platforms. High-pressure processing adoption accelerates across Nordic retail channels delivering clean-label shelf stability. The Stockholm-Uppsala corridor concentrates R&D talent for plant-forward formulation innovation.
Europe Frozen Snacks Market Competitive Landscape
Concentration sits with diversified multinational food conglomerates and specialized frozen food purists competing across tiered price positioning. The vendor base spans Swiss and Anglo-Dutch conglomerates with broad portfolio diversification, Nordic specialists with regional brand equity, and German family-owned enterprises with pizza platform specialization. Strategic archetypes include clean-label reformulators leveraging European R&D networks, private-label discounters compressing branded volume through quality-parity positioning, and sustainability-first movers capturing green premium pricing through Ecodesign alignment. Dominant competitive moves encompass mono-material packaging conversion partnerships with film converters and high-pressure processing technology licensing for clean-label shelf stability extension.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever PLC exemplify portfolio breadth spanning frozen snacks alongside adjacent categories, while Nomad Foods occupies a position as a frozen food purist with concentrated brand equity in Northern European markets. Dr. Oetker represents the family-owned specialist archetype with geographic origin signaling German manufacturing heritage. These three anchors illustrate divergent strategic postures: broad diversification against category focus, multinational scale against regional depth, and conglomerate resource allocation against founder-led operational intensity.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Nomad Foods |
| Dr. Oetker |
| McCain Foods |
| Orkla ASA |
| FRoSTA AG |
| Conagra Brands |
| General Mills |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Blast-freezing capacity utilization in Germany and Italy anchors cost structures across the Europe Frozen Snacks Market, concentrating supply-side scale economies that compress unit economics for mid-tier producers while elevating price floors for premium stone-baked platforms. REACH-compliant mono-material packaging conversions and EFSA labeling mandates feed directly into tiered cost positions, with early reformulators capturing retail shelf access that late adopters forfeit.
Pricing Analysis
EFSA nutrition labeling mandates dictate the pricing tier structure across the Europe Frozen Snacks Market, forcing artificial preservative stripping that separates clean-label premium portfolios from standard-tier lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient declaration length and packaging sustainability scoring. Cost compression in economy tiers intensifies because private-label discounter competition in Germany and the Netherlands deploys quality-parity products at sharp discounts. Branded manufacturers show least price sensitivity in stone-baked pizza platforms with restaurant-quality positioning, while institutional catering buyers in France exhibit highest sensitivity to per-unit cost in high-volume contracts.
Supply Chain Analysis
Strategic stockpiling of polypropylene and polyethylene resin inventories dominates frozen snack supply chain management, buffering against REACH chemical safety assessment implementation deadlines and film converter capacity constraints. Germany, Italy, and the Netherlands concentrate blast-freezing infrastructure and mono-material tray production, drawing from wheat flour, cheese, and vegetable input markets. Single-source vulnerability concentrates in specialized film converters serving paperboard pizza packaging with barrier coating capabilities. Distribution runs through supermarket retail chains with sustainability scoring procurement frameworks, bypassing traditional wholesaler markups in British and French urban catering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh meal-kit delivery platforms and quick-service restaurant delivery apps pose acute substitution threats to frozen snack incumbents, demanding defensive repositioning around convenience and texture restoration performance that substitutes cannot replicate.
For Market Incumbents: Shield stone-baked platform market share through exclusive supply agreements with film converters capable of REACH-compliant mono-material barrier coatings. Prioritize backward integration into high-pressure processing technology for clean-label shelf stability extension, neutralizing private-label discounter quality-parity advances in Nordic and British retail channels.
For New Entrants and Emerging Players: Anchor in Swedish and Danish frozen vegetable snack white space, where per-capita penetration lags Southern European pizza consumption baselines. Target protein-fortified plant-forward platforms with institutional procurement angles emphasizing waste-reduction KPIs and transparent origin documentation in French school and hospital channels.
For Investors and Strategic Acquirers: Family-owned German pizza specialists with stone-baked platform specialization and locked film converter relationships present acquisition targets with durable margin structures. Long-term viability hinges on Ecodesign standard alignment ahead of packaging recyclability benchmark implementation. Monitor digital procurement platform adoption rates in British and French urban catering as inflection indicator for food service channel disintermediation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA nutrition labeling mandates strip artificial preservatives to unlock retail shelf access. |
| Mono-Material Packaging Conversion | EU Green Deal waste directives force recyclable tray adoption ahead of implementation milestones. |
| High-Pressure Processing Licensing | Nordic and British retailers adopt chemical-free shelf stability extension for vegetable lines. |
| Digital Procurement Platform Integration | French and British institutional buyers bypass legacy wholesaler markups through direct channels. |
| Stone-Baked Platform Capacity Expansion | German and Italian households drive premium positioning through restaurant-quality texture replication. |
Research Methodology
Desk research of EU regulatory filings, EFSA guidance documents, and REACH chemical safety assessments preceded structured interviews with frozen food category buyers, supply chain directors at film converters, R&D leads at diversified conglomerates, and procurement officers at French institutional catering operators. Secondary validation drew from customs trade data, Nielsen retail audit records, and cold-chain logistics operator disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic consumption trend analysis.
Variance decomposition across product type, end user channel, packaging format, and distribution channel segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation anchored in historical volume trajectories and elasticity-adjusted demand modeling. Industry-specific forecast inputs encompassed energy price volatility assumptions for blast-freezing operations and private-label substitution rate scenarios in German and Dutch discounter channels.
Underlying assumptions cover REACH implementation timeline adherence and Ecodesign standard enforcement consistency, with deviation risk concentrated in energy input cost swings and film converter capacity bottlenecks. Revision becomes warranted when mono-material packaging conversion cost thresholds exceed retailer green premium absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Cereal Bar Market
Snacks
South America Frozen Snacks Market
Snacks
Premium Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Low Calorie Crackers Market
Snacks
UAE Cereal Bar Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Roasted Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Germany Energy Bar Market
Snacks
North America Extruded Snack Food Market
Snacks
Nachos Market
Snacks
Seafood Snacks Market
Snacks
Argentina Snack Bar Market