
 Animal-Derived Ingredients Market | 2026-2036
Animal-Derived Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Animal-Derived Ingredients Market Analysis
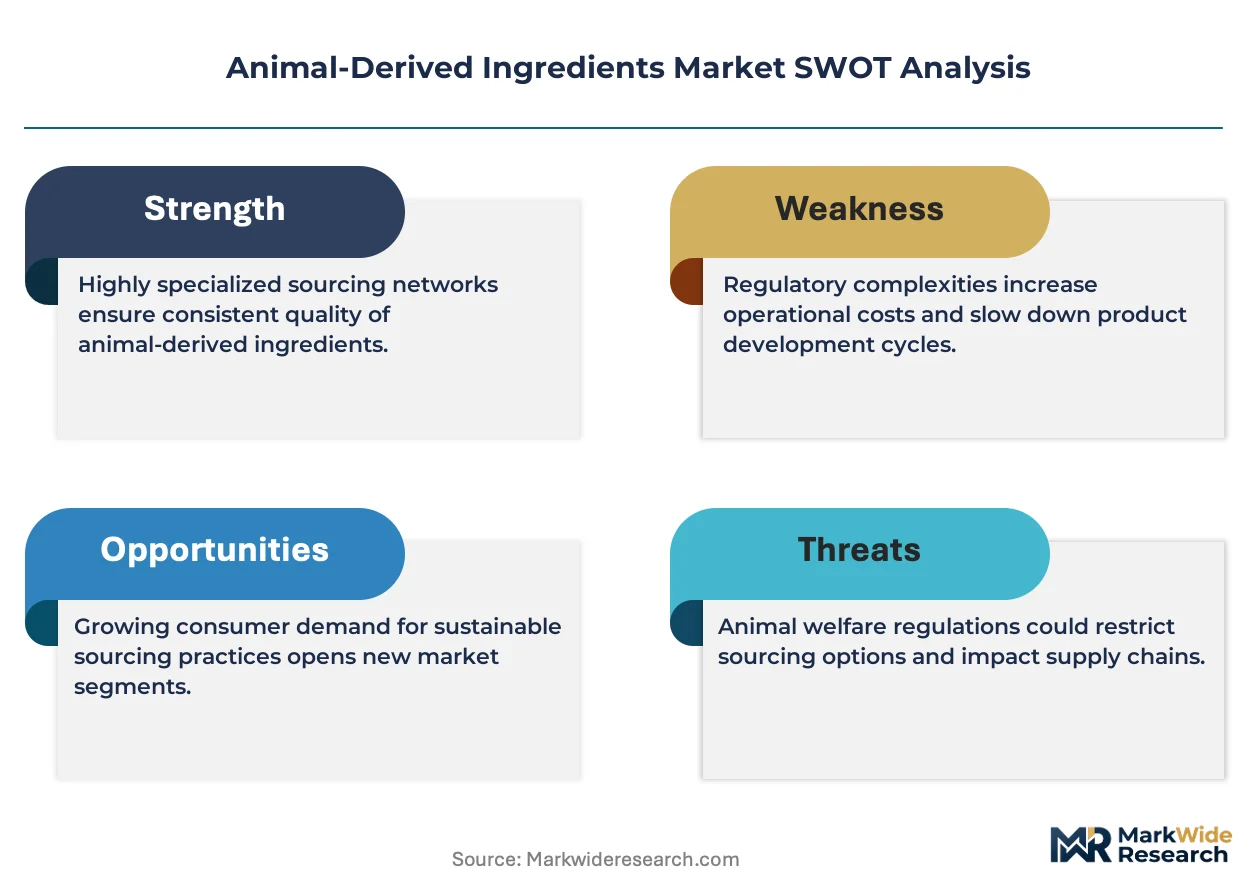
The EU Green Deal is consolidating sustainability requirements across animal-derived ingredient supply chains, forcing processors to document carbon intensity and circular sourcing. Darling Ingredients leverages vertical integration across rendering and collagen recovery to secure feedstock control. Cargill anchors North American gelatin supply through its integrated protein processing network. BASF SE differentiates via pharmaceutical-grade collagen peptide R&D for drug delivery matrices.
Animal-derived ingredients encompass proteins, lipids, minerals, and bioactive compounds extracted from livestock, poultry, and marine sources through rendering, hydrolysis, or solvent extraction, typically specified by ash content below 3% and molecular weight distributions tailored to end-use functionality. Collagen and gelatin command the largest revenue pool due to established pharmaceutical capsule demand, while nutraceutical applications in powder form represent the fastest-expanding margin segment as dietary supplement companies seek clean-label protein fortification. Dairy derivatives maintain mature volume positions in food manufacturing, though growth rates trail collagen peptides in beauty and clinical nutrition channels.
EMA pharmaceutical guidelines, FDA food additive regulations, and REACH chemical registration requirements collectively shape product purity thresholds and market access conditions for animal-sourced inputs. EFSA safety assessments for bovine-derived materials influence import acceptance across European member states. Stakeholders must monitor evolving BSE-related geographic eligibility restrictions and alternative protein substitution threats when allocating capital across rendering and precision fermentation capacity.
Market Dynamics
EU Green Deal carbon-accounting mandates and REACH traceability requirements are restructuring procurement relationships across animal-derived ingredient supply chains, forcing processors to document feedstock origin and circular sourcing credentials.
Growth Catalysts
- Pharmaceutical capsule demand:Gelatin specifications for hard-shell and soft-gel applications are tightening purity thresholds, pulling premium-grade collagen into drug delivery matrices.
- REACH compliance:European chemical registration requirements are standardizing documentation protocols, creating competitive advantage for processors with pre-certified supply chains.
- Marine sourcing expansion:Fish-derived collagen peptides are penetrating beauty and clinical nutrition channels as bovine alternatives face BSE-related geographic restrictions.
Market Restraints
- Feedstock price volatility:Rendering input costs fluctuate with livestock cycle variations and energy-intensive hydrolysis requirements.
- European supply concentration:Gelatin processing capacity clusters in France, Germany, and Belgium, exposing buyers to single-source disruption risks.
- Precision fermentation substitution:Microbial collagen production is advancing toward commercial scale, threatening traditional extraction economics.
Strategic Opportunities
- China domestic production:Local collagen peptide manufacturing is scaling for nutraceutical export markets, offering co-investment partnerships for technology transfer.
- Wound-care biologics:Collagen matrices for chronic wound management represent underdeveloped therapeutic applications with reimbursement tailwinds.
- Clean-label powder formats:Dietary supplement brands are specifying single-ingredient protein fortification, bypassing multi-component blends.
Industry Challenges
- Cross-species contamination control:Rendering facilities must segregate bovine, porcine, and poultry streams to satisfy religious certification requirements.
- Legacy ERP integration:Batch-level traceability systems require capital deployment to connect with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal-Derived Ingredients Market |
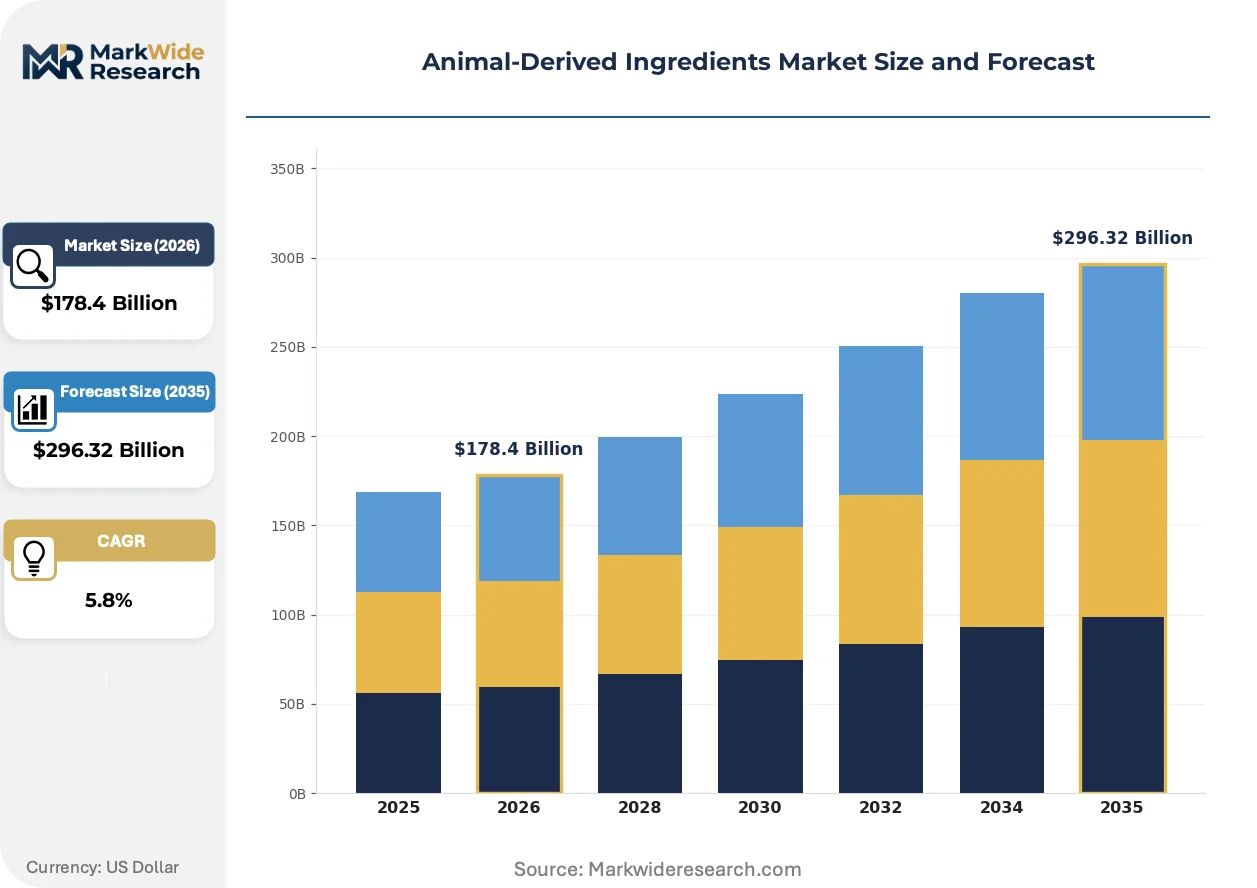
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $296.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Gelatin, Dairy, Egg Derivatives Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Beauty Brands, Healthcare Providers, Dietary Supplement Companies Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Darling Ingredients, Cargill, BASF SE, Archer Daniels Midland, DSM, Tyson Foods, Symrise, Kemin Industries, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal-Derived Ingredients Market Emerging Trajectories
Enzymatic hydrolysis and membrane filtration advances are compressing production timelines for pharmaceutical-grade collagen peptides, while regulatory pressure on carbon intensity is reshaping processor investment priorities.
Membrane filtration technology is consolidating control over molecular weight distribution in collagen peptide production. Pharmaceutical formulators are specifying narrow polydispersity ranges for drug delivery applications. This precision is consolidating high-margin supply relationships with certified processors capable of batch-level documentation.
EU Green Deal carbon-border adjustment mechanisms are tightening documentation requirements for imported animal-derived ingredients. Processors must now quantify embedded emissions across rendering, hydrolysis, and drying stages. Pharmaceutical and nutraceutical buyers in Germany and France are prioritizing suppliers with verified circular sourcing credentials.
Direct-procurement relationships between nutraceutical brands and rendering cooperatives are compressing traditional distributor margins. Large supplement manufacturers are establishing captive supply agreements for specified ash content and amino acid profiles. This disintermediation is most visible in China, where domestic collagen producers are integrating backward into rendering operations.
Animal-Derived Ingredients Market Segmentation
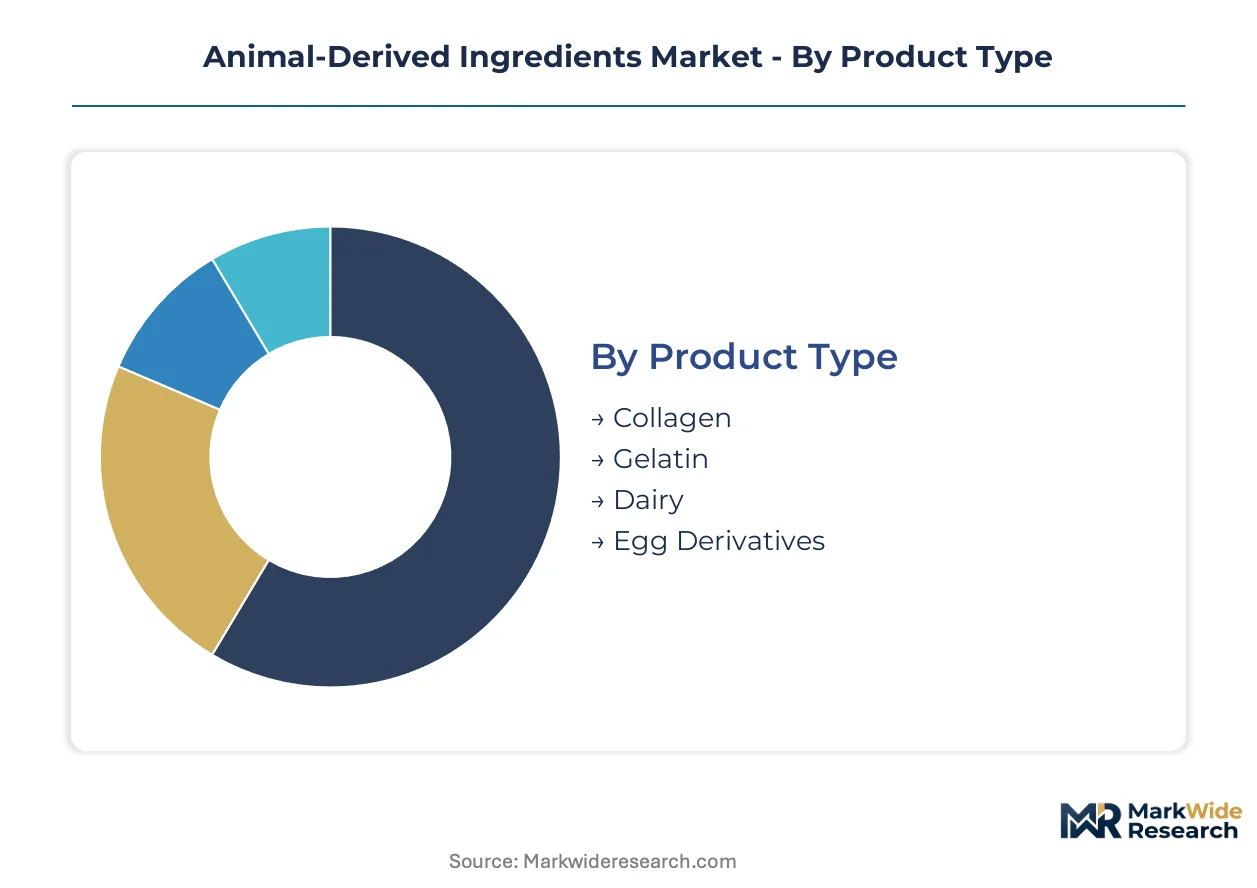
Animal-derived ingredient procurement varies sharply by integration depth. Standalone applications demand certified purity and documented provenance, while embedded systems prioritize cost-efficient functional performance within complex formulations.
Product Type:
Standalone collagen and gelatin products command premium positioning through pharmaceutical-grade certification and batch-level traceability. Embedded dairy and egg derivatives compete on functional cost efficiency within processed food matrices.
- Collagen:Hydrolyzed peptides with molecular weight distributions below 10 kDa enable targeted absorption profiles. Demand concentrates in German and French nutricosmetic brands seeking EFSA-compliant skin health claims alongside Chinese domestic production scaling for export markets.
- Gelatin:Denatured collagen with specified bloom strength (150-250g) determines capsule shell integrity. Pharmaceutical formulators in the United States and Italy specify hard-shell and soft-gel grades with endotoxin limits below 10 EU/g.
- Dairy:Casein and whey protein isolates serve infant formula and sports nutrition applications with standardized protein content above 90%.
- Egg Derivatives:Lysozyme and phospholipid fractions function as natural preservatives and emulsifiers in baked goods and mayonnaise production.
Volume placements concentrate in Gelatin; the faster expansion belongs to Collagen.
Application:
Cost-tier stratification separates regulated pharmaceutical channels from discretionary beauty and wellness segments. Nutraceutical applications occupy the middle tier with accelerating clean-label specifications.
- Food & Beverage:Gelatin provides gelling and stabilizing functionality in confectionery and dairy desserts with specified viscosity ranges. Processors in Brazil and Mexico source bovine-derived grades for cost-sensitive applications.
- Pharmaceuticals:Hard-shell capsules and tablet coatings require halal and kosher certification compliance. FDA drug master file submissions and EMA variations drive supplier qualification timelines exceeding 18 months.
- Cosmetics:Marine collagen peptides penetrate Korean and Japanese skincare formulations as bovine alternatives face import restrictions.
- Nutraceuticals:Powder-format collagen fortification targets joint health and beauty positioning with single-ingredient labeling preferred by North American direct-to-consumer brands.
Revenue weighting favors Pharmaceuticals; Nutraceuticals are climbing the fastest.
End User:
Customer-type fragmentation creates divergent procurement patterns. Large-scale manufacturers negotiate long-term supply agreements while specialized brands prioritize certified small-batch sourcing.
- Food Manufacturers:Industrial bakeries and confectioners specify gelatin with controlled mesh size for consistent hydration rates in automated production lines.
- Beauty Brands:Premium skincare houses in France and Japan contract directly with marine collagen processors for peptide sequences targeting dermal matrix signaling.
- Healthcare Providers:Hospital wound-care units specify collagen sponge matrices with defined pore structures for chronic ulcer management.
- Dietary Supplement Companies:Powder contract manufacturers in China and the United States integrate backward into rendering cooperatives to secure specified ash content below 2%.
Procurement scale concentrates in Food Manufacturers; Healthcare Providers show the steepest expansion trajectory.
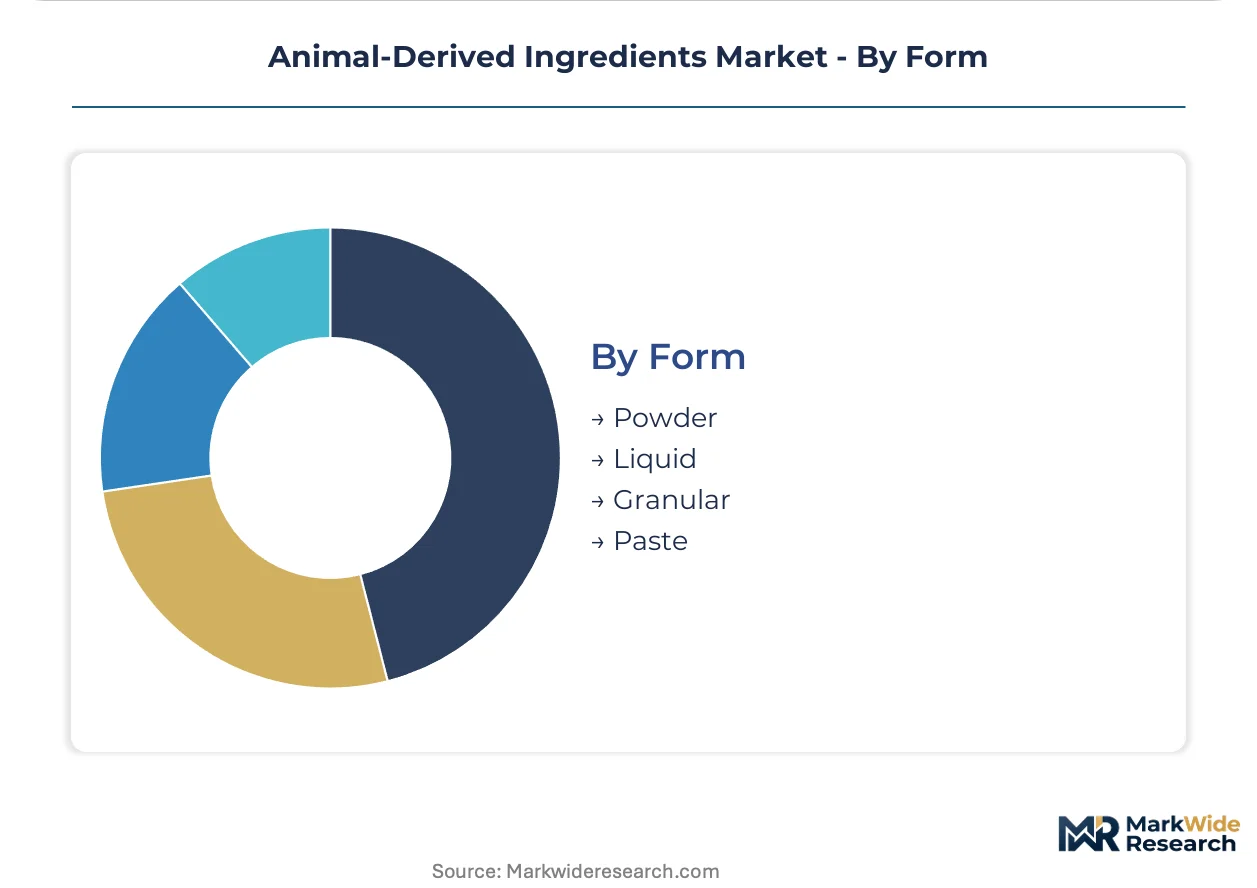
Form:
Supply concentration in powder processing reflects drying technology economies and shelf stability requirements. Liquid and paste formats serve niche fresh and refrigerated applications.
- Powder:Spray-dried collagen peptides with moisture content below 6% enable bulk handling and extended storage. Nutraceutical brands in Germany and Australia specify instantized grades for ready-to-mix applications.
- Liquid:Hydrolyzed collagen concentrates with 10-20% solids content serve ready-to-drink formulations requiring cold-chain distribution.
- Granular:Agglomerated gelatin with defined particle size distribution improves dispersibility in high-speed blending operations.
- Paste:Semi-moist egg yolk and plasma fractions function as binding agents in pet food extrusion with specified water activity below 0.85.
Production capacity clusters in Powder; Liquid formats are gaining share fastest among functional beverage startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of collagen peptides for export while the United States and Europe absorb premium pharmaceutical grades. This production-consumption divide shapes trade flows and regulatory compliance investments across major economies.
United States
FDA drug master file submissions drive 18-month supplier qualification timelines for hard-shell capsule gelatin. The agency's BSE-related geographic eligibility restrictions block certain feedstock origins. Rendering cooperatives in the Midwest supply bovine-derived inputs to pharmaceutical formulators in New Jersey and Illinois.
Germany
REACH traceability requirements and EU Green Deal carbon-accounting mandates force processors to document embedded emissions. EMA pharmaceutical guidelines tighten purity thresholds for wound-care collagen matrices. Industrial clusters in North Rhine-Westphalia concentrate enzymatic hydrolysis capacity for pharmaceutical-grade peptide production.
China
Domestic collagen peptide manufacturing scales rapidly for nutraceutical export markets. SAMR registration requirements and GB standards govern food additive specifications. Zhejiang and Shandong provinces host backward-integrated operations linking rendering facilities to spray-drying plants.
France
ANSM oversight of pharmaceutical excipients reinforces EMA safety assessments for bovine-derived materials. Clean-label powder demand from German and Australian nutraceutical brands pulls premium-grade production. The Hauts-de-France region maintains gelatin processing heritage with modernized membrane filtration installations.
Brazil
ANVISA regulates animal-sourced inputs for pharmaceutical applications with import substitution priorities. Cost-sensitive food manufacturers source bovine gelatin for confectionery applications. São Paulo state anchors rendering capacity serving both domestic food processors and export-oriented collagen peptide refiners.
Animal-Derived Ingredients Market Vendor Landscape
The competitive structure tilts toward vertically integrated rendering specialists with captive feedstock control. Three to five conglomerates anchor pharmaceutical-grade supply through certified processing networks, while mid-scale regional processors compete on cost efficiency for food applications. Two dominant archetypes emerge: integrated agribusiness conglomerates spanning protein extraction to finished ingredient supply, and specialized collagen peptide refiners focused on narrow molecular weight specifications. Capacity expansion and strategic partnerships constitute the primary competitive moves, with technology licensing for enzymatic hydrolysis representing a secondary vector.
Within the integrated conglomerate tier, Darling Ingredients and Cargill occupy positions defined by upstream rendering control and downstream pharmaceutical certification. BASF SE exemplifies the specialized refinement archetype through its pharmaceutical-grade collagen peptide positioning. These three entities anchor distinct competitive vectors: feedstock security, geographic coverage, and technical specification depth respectively.
| Leading Market Players |
|---|
| Darling Ingredients |
| Cargill |
| BASF SE |
| Archer Daniels Midland |
| DSM |
| Tyson Foods |
| Symrise |
| Kemin Industries |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-accounting mandates gate qualified supply access and premium-tier pricing power, forcing processors to document embedded emissions across rendering, hydrolysis, and drying stages before pharmaceutical and nutraceutical buyers in Germany and France will contract. This environmental compliance layer stratifies the market into certified suppliers commanding specification premiums and uncertified processors competing on spot-market terms.
Pricing Analysis
Pharmaceutical-grade yield performance anchors value-based pricing, with collagen peptide specifications below 10 kDa molecular weight commanding tiered premiums based on batch-level purity documentation and endotoxin certification. Price differentiation rests on halal/kosher compliance tiers and geographic proximity to rendering cooperatives, with North American buyers absorbing transport premiums for European-sourced gelatin. Cost compression in standard food-grade bovine gelatin is intensifying because Brazilian and Mexican processors are expanding volume exports. Dietary supplement contract manufacturers exhibit highest price sensitivity due to backward integration pressures, while wound-care biologics purchasers prioritize specification certainty over unit economics.
Supply Chain Analysis
Rendering by-product recovery flows from slaughterhouse operations back into collagen peptide refineries constitute the dominant reverse-logistics architecture, with spent processing streams repurposed for pet food and fertilizer applications. Feedstock supply concentrates in the United States, Brazil, and China, with Midwestern rendering cooperatives supplying bovine-derived inputs to New Jersey pharmaceutical formulators. Raw material dependencies center on cattle hide and bone stocks, poultry by-products, and marine processing discards. Single-source vulnerability pervades European gelatin processing, where capacity clusters in France, Germany, and Belgium expose buyers to disruption. Distribution runs through long-term offtake agreements between integrated agribusiness conglomerates and pharmaceutical capsule manufacturers, compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with feedstock security and pharmaceutical certification timelines serving as the decisive levers separating consolidated incumbents from margin-pressured challengers.
For Market Incumbents: Extend membrane filtration capacity in North Rhine-Westphalia and Zhejiang to capture pharmaceutical-grade peptide demand before precision fermentation substitutes reach commercial scale. Secure captive rendering agreements with Midwestern cooperatives to defend bovine-derived feedstock access against Chinese domestic production expansion. EMA pharmaceutical guideline tightening around BSE-related geographic eligibility represents the critical regulatory threat requiring pre-certified supply chain documentation.
For New Entrants and Emerging Players: Enzymatic hydrolysis technology licensing offers a technology-first wedge into wound-care collagen matrices, where reimbursement tailwinds outpace pharmaceutical capsule qualification barriers. Target chronic ulcer management applications in German and French hospital systems, where ANSM and EMA safety assessments have created supplier qualification gaps. Pursue direct-procurement partnerships with Australian and German nutraceutical brands seeking clean-label powder formats with specified ash content below 2%.
For Investors and Strategic Acquirers: SAMR registration completion for Chinese collagen peptide exporters is the leading indicator that backward-integrated rendering-to-drying operations have achieved regulatory viability for premium-tier market access. Over the projection horizon, vertically integrated specialists with certified pharmaceutical-grade capacity and documented circular sourcing credentials will consolidate food-grade processors unable to meet EU Green Deal traceability mandates. Monitor EFSA safety assessment outcomes for novel marine collagen sources as the signal for bovine alternative substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Operations | Darling Ingredients and Cargill secure feedstock control against Chinese domestic production scaling. |
| Pharmaceutical-Grade Certification Investment | BASF SE differentiates via EMA-compliant collagen peptide R&D for drug delivery matrices. |
| Membrane Filtration Capacity Expansion | Processors in Hauts-de-France capture narrow polydispersity specifications for pharmaceutical formulators. |
| Marine Collagen Sourcing Diversification | Korean and Japanese beauty brands bypass BSE-related geographic restrictions on bovine materials. |
| Direct-Procurement Relationship Development | Large supplement manufacturers compress distributor margins through captive supply agreements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning rendering cooperative managers, pharmaceutical procurement directors, nutraceutical brand formulators, and EMA regulatory affairs specialists. Bottom-up triangulation against top-down sector sizing validated volume estimates, with FDA drug master file submissions, REACH registration databases, and SAMR food additive specifications providing compliance benchmarks.
Granularity-level modeling disaggregated revenue and volume across product type, application, end user, and form dimensions, with additional segmentation by molecular weight distribution tier and certification grade. CAGRs were derived from fitted growth curves applied to historical trade flows and projected capacity expansion announcements across the analysis window. Forecast inputs incorporated livestock cycle variations, enzymatic hydrolysis yield improvements, and regulatory eligibility restriction shifts.
Several conditions sit outside the modeled scope, including precision fermentation collagen commercialization timelines and potential BSE-related geographic eligibility expansions or contractions. Forecasts reflect documented assumptions regarding feedstock price stability and pharmaceutical qualification timeline consistency. Practitioners should monitor EFSA safety assessment outcomes, SAMR registration completion rates, and EU Green Deal carbon-border adjustment implementation for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Non-GMO Oil Market
Ingredients
Wheat Malt Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Vegan Ingredients Market
Ingredients
Boysenberry Extract Market
Ingredients
Global Dietary Fibers Market
Ingredients
Textural Food Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Sea Salt Market
Ingredients
Banana Flour Market
Ingredients
Instant Dry Yeast Market
Ingredients
Almond Ingredients Market
Ingredients
Synephrine Market
Ingredients
Industrial Starch Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Specialty Starch Market