
 South Korea Snack Bar Market | 2026-2036
South Korea Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Snack Bar Market Analytics
A shift from outsourced ingredient sourcing toward captive supply chains is pivoting how domestic manufacturers secure oat, whey, and nut inputs. Haitai Confectionery & Foods Co., Ltd. leverages its legacy distribution network to maintain shelf dominance in traditional retail channels. Samlip Food Co., Ltd. anchors its position through specialized bakery-bar production lines that serve both private-label and branded contracts. Lotte Confectionery Co., Ltd. competes by extending its confectionery R&D capabilities into functional snack bar formulations with added probiotics and fiber.
A South Korea snack bar is a compressed, shelf-stable food product typically combining cereals, proteins, nuts, or fruit binders into a hand-held format, with caloric density ranging from 150 to 300 kcal per serving and moisture content controlled below 10 percent to ensure ambient stability without refrigeration. These products serve as meal replacements, pre-workout fuel, or between-meal satiety solutions for time-constrained consumers across urban centers. Protein bars lead the product type category due to alignment with gym culture and corporate wellness programs, while granola bars sustain steady volume through breakfast substitution habits among working adults. Online distribution channels represent the fastest-growing structural segment, driven by subscription models and direct-to-consumer sampling that bypasses the slotting fees dominant in offline retail.
MFDS enforces strict nutritional labeling and health claim verification for functional snack products, compelling manufacturers to substantiate protein content and sugar reduction claims through certified laboratory testing. The Ministry of Food and Drug Safety also regulates novel ingredient approvals, which shapes how quickly companies can introduce imported superfood additives or alternative protein sources into bar formulations. Stakeholders must monitor evolving clean-label expectations and the potential tightening of sugar taxation policies that could force rapid portfolio reformulation decisions.
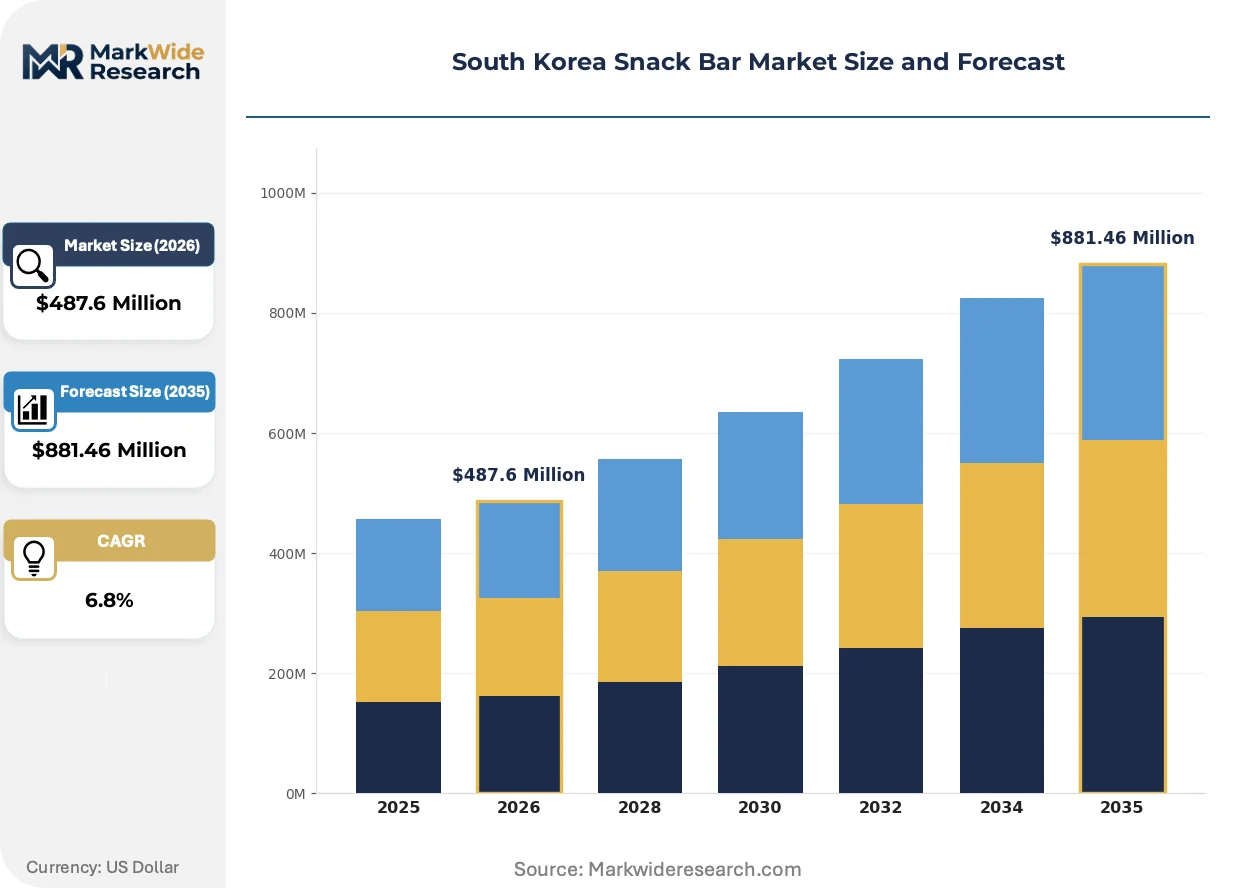
Market Dynamics
MFDS sugar disclosure mandates are compressing formulation timelines while forcing manufacturers to rebuild supply chains around domestic oat cultivation and alternative protein sourcing. This regulatory pressure intersects with Seoul's corporate wellness procurement standards to reshape competitive positioning across the value chain.
Growth Catalysts
- MFDS Nutritional Labeling:Mandatory sugar content disclosure accelerates reformulation toward reduced-sugar recipes, creating first-mover advantages for compliant manufacturers.
- Corporate Wellness Programs:Health-conscious office workers in Gangnam and Songdo drive protein-fortified format adoption through employer-subsidized canteen contracts.
- Captive Supply Chains:Domestic oat and whey sourcing reduces import dependency and shortens lead times for functional bar production.
Market Restraints
- Input Cost Volatility:Almond and cashew prices fluctuate with California drought cycles, compressing margin buffers on nut-dense formulations.
- Regulatory Friction:MFDS novel ingredient approval timelines delay superfood additive launches by 12-18 months versus benchmark jurisdictions.
- Substitution Threat:Fresh convenience store bento boxes and rice ball formats compete for the same 150-300 kcal meal-replacement occasions.
Strategic Opportunities
- Busan-Ulsan Corridor:Underpenetrated manufacturing zones offer lower logistics costs for exporters targeting Japan and Southeast Asia.
- Subscription Direct-to-Consumer:Bypassing CU and GS25 slotting fees through monthly protein bar boxes captures higher lifetime value per subscriber.
- PLI-Aligned Domestic Sourcing:Government incentives for agricultural processing equipment support backward integration into oat milling and whey concentration.
Industry Challenges
- Food Science Talent Scarcity:Formulation chemists with dual expertise in shelf-stable texture systems and sports nutrition claims command premium wages.
- Clean-Label Certification Lag:Third-party non-GMO and organic verification backlog extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Snack Bar Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Energy Bars, Nut Bars Flavor Profile: Chocolate, Vanilla, Peanut Butter, Fruit Consumer Age Group: Children, Teens, Adults, Seniors Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | Haitai Confectionery & Foods Co., Ltd., Samlip Food Co., Ltd., Lotte Confectionery Co., Ltd., Korea Yakult Co., Ltd., Maeil Dairies Co., Ltd., Orion Confectionery Co., Ltd., Binggrae Co., Ltd., CJ CheilJedang Corporation, Crown Confectionery Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Snack Bar Market Evolving Landscape
Reformulation pressure from MFDS disclosure rules is converging with gym culture maturation to reshape how protein and granola bars are engineered, positioned, and distributed across Korean urban centers.
Enzymatic hydrolysis of plant proteins is expanding into mainstream bar production to improve amino acid bioavailability without bitter off-notes. Fitness-focused consumers in Seoul's Yeouido and Jamsil districts now prioritize digestibility claims over raw protein gram counts. This shift is compressing the competitive window for legacy whey-dominant formulations that lack enzymatic processing capabilities.
MFDS tightened its health claim substantiation framework for functional snack products in 2023, requiring certified laboratory verification of protein content and sugar reduction assertions. Manufacturers must now submit batch testing documentation before marketing materials receive approval. Small and mid-sized producers in Gyeonggi Province face disproportionate compliance burdens relative to integrated conglomerates with captive testing facilities.
Corporate procurement departments now mandate clean-label snack options for employee wellness programs, displacing traditional confectionery from office canteen contracts. This buyer concentration in Seoul's Teheran-ro and Gwanghwamun corridors forces suppliers to reformulate around shortened ingredient decks. The shift is most visible in Songdo's international business district, where multinational tenants import EFSA-aligned standards into local vendor selection criteria.
South Korea Snack Bar Market Segmentation
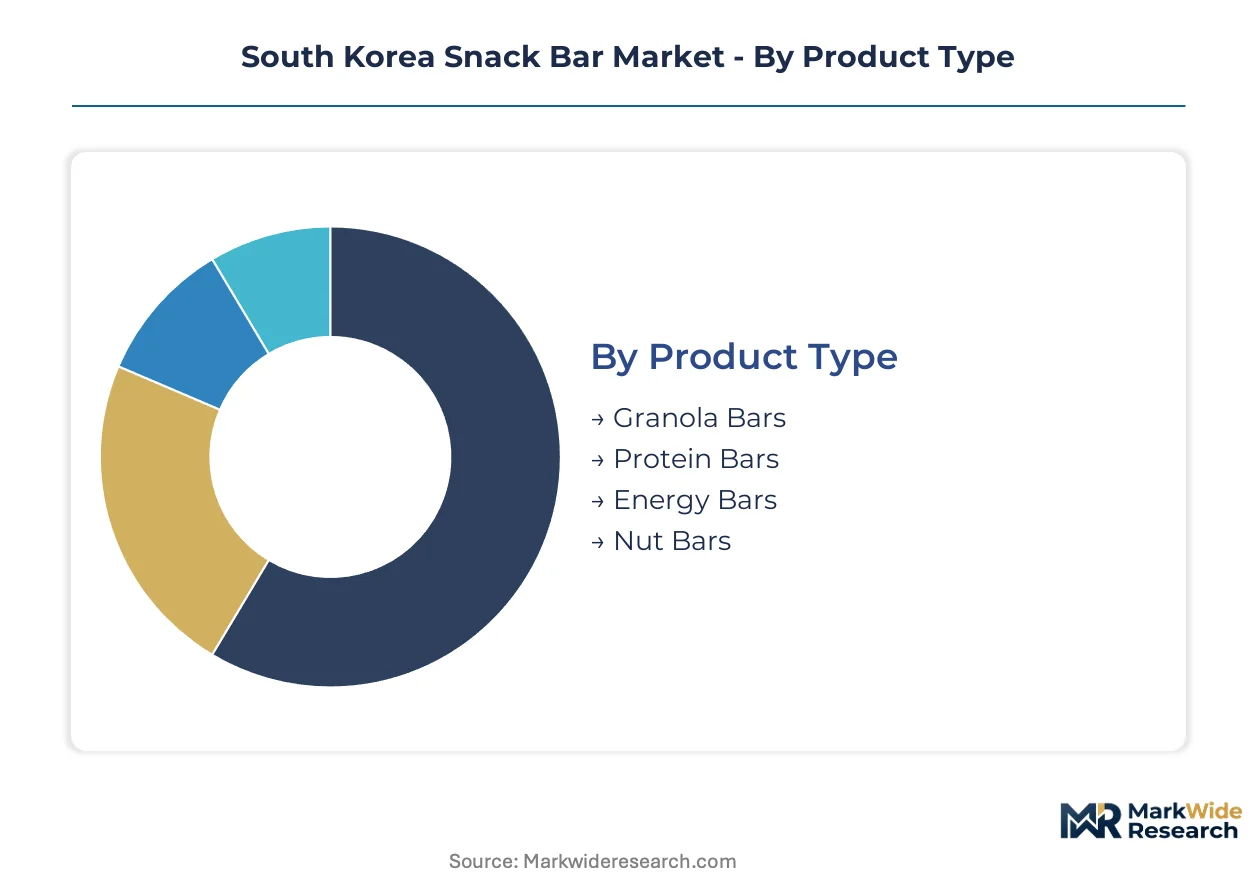
Segmentation in the South Korea snack bar market reveals how MFDS compliance costs, gym culture density, and corporate procurement standards reshape competitive priorities across distinct buyer clusters. Understanding these fault lines exposes where formulation investment and channel strategy deliver disproportionate returns.
Product Type:
Buyers in this category diverge sharply by nutritional literacy and consumption occasion, separating fitness enthusiasts seeking macronutrient precision from time-pressed professionals prioritizing convenience.
- Protein Bars:Compressed formulations delivering 15-25g protein per serving through whey, casein, or enzymatically hydrolyzed plant isolates. Demand concentrates in Gangnam and Songdo wellness clusters where corporate wellness programs subsidize pre-workout and meal-replacement consumption among health-conscious office workers.
- Granola Bars:Oat-based matrices bound with honey or alternative sweeteners, typically 150-200 kcal with moderate fiber content. Breakfast substitution habits among Seoul's working adults sustain steady volume through convenience store and supermarket channels despite protein bar encroachment.
- Energy Bars:Carbohydrate-dense formulations targeting rapid glycogen replenishment for endurance athletes. Cyclists and marathon runners in Busan's outdoor recreation districts drive niche adoption.
- Nut Bars:Almond, cashew, or mixed nut cores with minimal processing, positioned as clean-label alternatives. Premium pricing in specialty retailers reflects California drought-driven input cost volatility.
Granola bars lead volumes today; protein bars are gaining share fastest.
Flavor Profile:
Flavor selection tracks distribution channel sophistication, with mass retail favoring familiar profiles and direct-to-consumer platforms enabling experimental variants.
- Chocolate:Dominant profile across all channels, leveraging Korean consumers' established preference for cocoa-based confectionery. MFDS sugar disclosure mandates are accelerating reformulation toward reduced-sugar dark chocolate coatings.
- Peanut Butter:Secondary staple with strong alignment to protein bar positioning. Import dependency on US peanut paste creates margin pressure during currency fluctuations.
- Vanilla:Neutral base supporting clean-label marketing and ingredient transparency claims. Preferred by corporate procurement departments specifying shortened ingredient decks for employee wellness programs.
- Fruit:Dried cranberry, yuzu, and domestic persimmon variants targeting female demographics and senior consumers. Yeongnam region fruit processors supply localized inputs.
Chocolate dominates shelf presence; fruit profiles are expanding most quickly in subscription channels.
Consumer Age Group:
Age-based segmentation maps directly onto channel strategy and health claim substantiation requirements, with adult segments driving functional positioning and younger cohorts determining impulse placement.
- Adults:Core revenue base comprising fitness enthusiasts and corporate employees. Employer-subsidized canteen contracts in Seoul's Teheran-ro corridor mandate MFDS-compliant nutritional labeling and clean-label certification.
- Teens:Secondary volume driver through school-adjacent convenience stores. Price sensitivity and social media influence shape trial and brand switching behavior.
- Children:Regulated segment with strict MFDS limits on sugar content and portion sizing. Parental gatekeeping limits growth despite breakfast substitution potential.
- Seniors:Emerging target for soft-texture, low-glycemic formulations addressing chewing difficulty and blood glucose management. Pharmacy and specialty retail channels dominate.
Adults anchor revenue today; seniors show the steepest expansion trajectory.
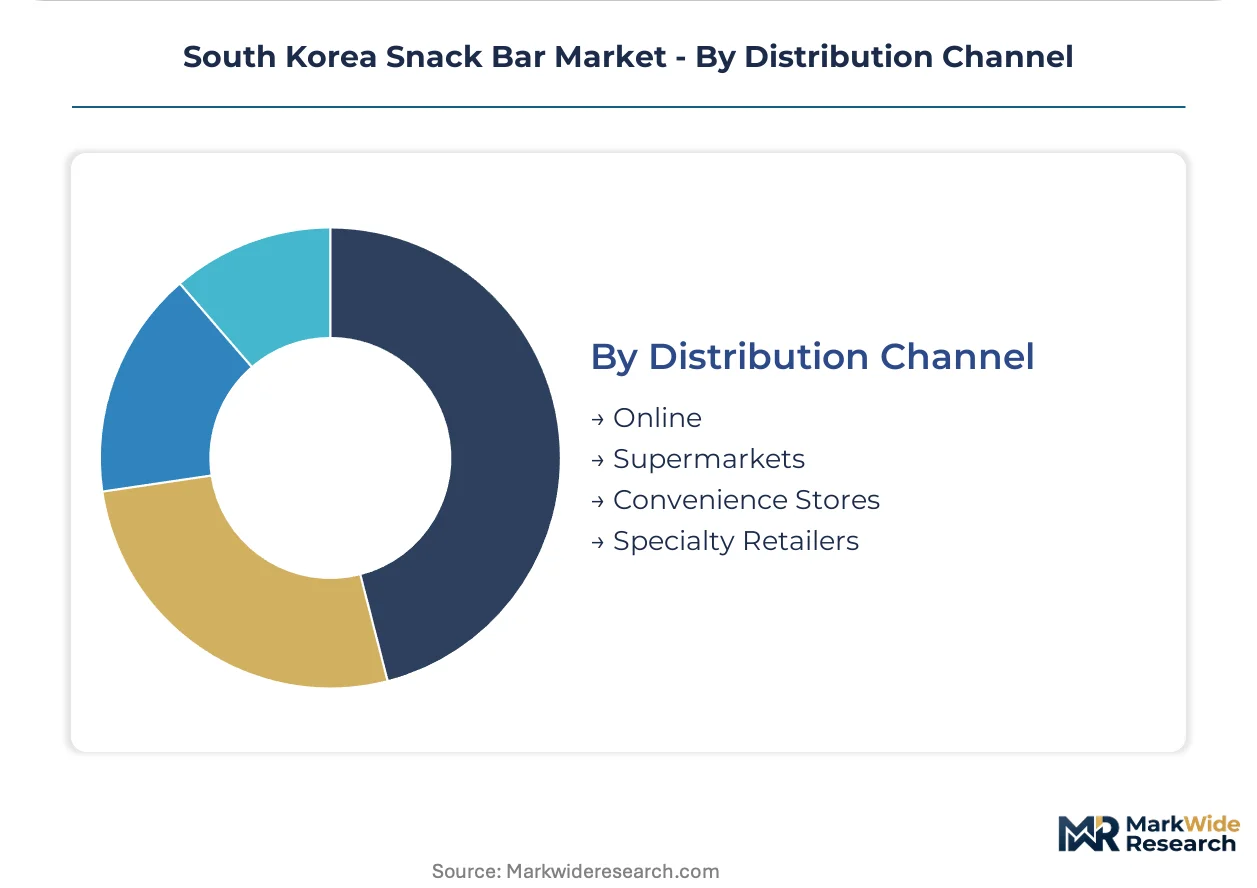
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics, with offline dominance eroding as subscription models bypass slotting fee barriers.
- Online:Direct-to-consumer platforms and subscription boxes capturing lifetime value through automated replenishment. Bypasses CU and GS25 slotting fees that compress margins for emerging brands.
- Convenience Stores:CU, GS25, and 7-Eleven networks dominate impulse and meal-replacement occasions. Limited shelf space enforces fierce competition for facings and promotional support.
- Supermarkets:E-Mart, Lotte Mart, and Homeplus drive family-pack volume and promotional pricing. Category management favors established conglomerates with legacy distribution relationships.
- Specialty Retailers:Olive Young and fitness-focused chains support premium positioning and ingredient storytelling. Higher per-unit margins offset lower throughput.
Convenience stores move the most units; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates the highest snack bar consumption density, driven by corporate wellness procurement and fitness culture maturation across Gangnam and Songdo districts. Domestic manufacturers anchor production capacity here to minimize logistics costs for premium distribution channels.
Seoul Capital Area
Corporate canteen contracts in Teheran-ro and Gwanghwamun corridors mandate MFDS-compliant nutritional labeling and clean-label certification. Employer-subsidized wellness programs displace traditional confectionery from office pantries. Gangnam and Songdo wellness clusters drive protein-fortified format adoption among health-conscious office workers.
Busan-Ulsan Corridor
Underpenetrated manufacturing zones offer lower logistics costs for exporters targeting Japan and Southeast Asia. Port infrastructure supports raw material imports for oat and whey processing. Local producers leverage this positioning to serve regional convenience store networks with reduced lead times.
Daegu-Gyeongbuk
Yeongnam region fruit processors supply localized inputs for dried cranberry and persimmon bar variants. Agricultural processing equipment incentives under PLI-aligned programs support backward integration. Specialty retailers in this cluster emphasize domestic ingredient provenance for premium positioning.
Daejeon-Sejong
Government research institutes anchor food science talent development for shelf-stable texture systems. MFDS regulatory expertise concentrates here, accelerating novel ingredient approval navigation. Mid-sized producers establish pilot facilities to test enzymatic hydrolysis capabilities before scaling.
Gwangju-Honam
Soft-texture formulation development targets senior consumers with chewing difficulty and blood glucose management needs. Pharmacy channel penetration exceeds national averages for low-glycemic product distribution. Regional brands compete on digestibility claims rather than raw protein gram counts.
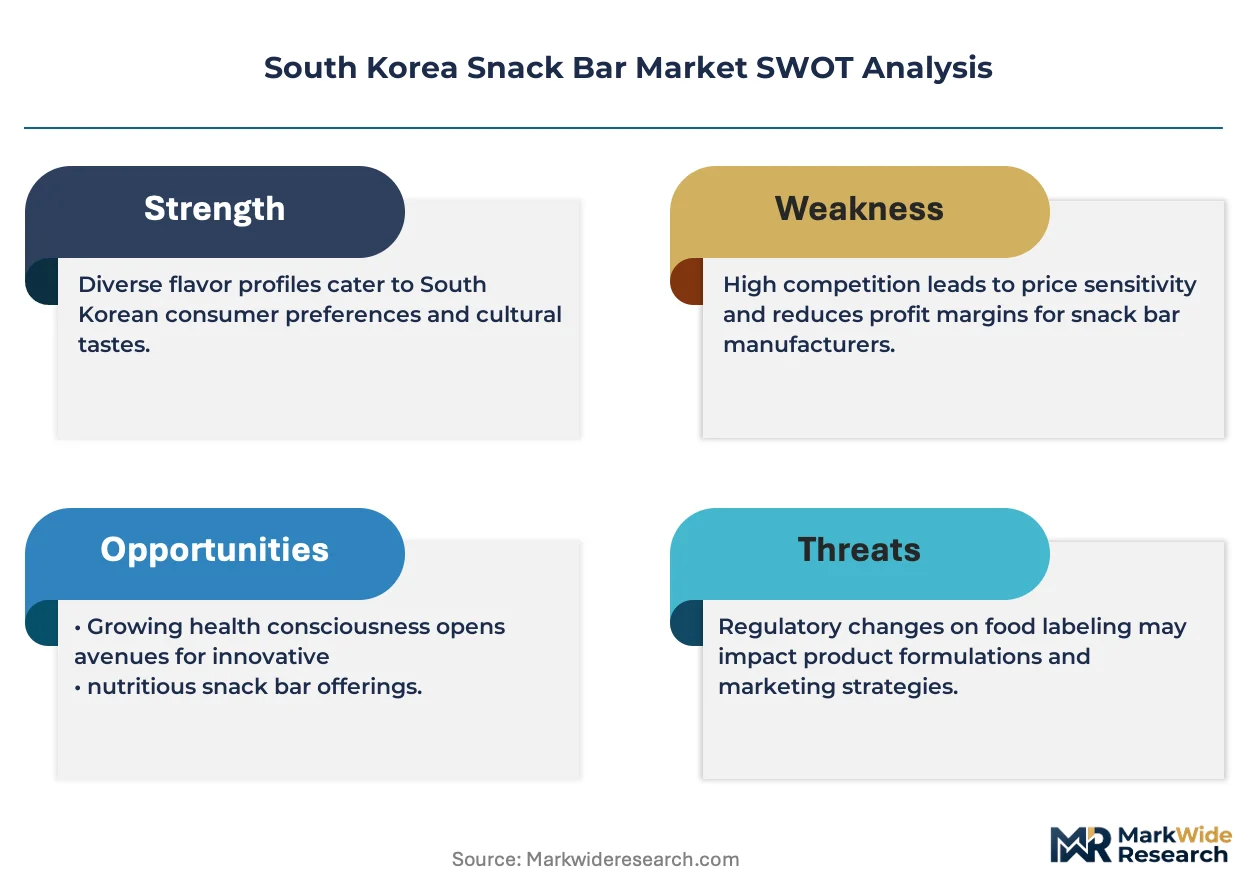
South Korea Snack Bar Market Competitive Landscape
Global majors compete with regional champions across distribution network depth and regulatory compliance speed. The market structure tilts toward integrated conglomerates with captive testing facilities and legacy retail relationships. Three archetypes dominate: diversified confectionery conglomerates extending into functional formats, specialized bakery-bar producers serving private-label contracts, and dairy-derived nutrition specialists leveraging fermentation expertise. Competitive moves center on backward integration into domestic oat milling and subscription direct-to-consumer models that bypass convenience store slotting fees.
Within the diversified conglomerate tier, Haitai Confectionery & Foods Co., Ltd., Lotte Confectionery Co., Ltd., and Orion Confectionery Co., Ltd. represent the established anchor positions. Haitai leverages its legacy distribution network to maintain shelf dominance in traditional retail channels. Lotte extends confectionery R&D capabilities into functional formulations with added probiotics and fiber. Orion occupies a position balancing mass-market volume with emerging wellness positioning. These three exemplify how scale-driven players compress compliance timelines through captive laboratory testing facilities.
| Leading Market Players |
|---|
| Haitai Confectionery & Foods Co., Ltd. |
| Samlip Food Co., Ltd. |
| Lotte Confectionery Co., Ltd. |
| Korea Yakult Co., Ltd. |
| Maeil Dairies Co., Ltd. |
| Orion Confectionery Co., Ltd. |
| Binggrae Co., Ltd. |
| CJ CheilJedang Corporation |
| Crown Confectionery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
MFDS sugar disclosure mandates gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant manufacturers while rewarding early reformulators with shelf positioning in corporate wellness channels. Buyers in Seoul's Teheran-ro corridor now demand certified clean-label documentation as a baseline procurement requirement, bifurcating the market between validated premium suppliers and commodity-tier competitors.
Pricing Analysis
Input-cost pass-through from California almond and cashew price volatility compresses margin buffers on nut-dense formulations, forcing manufacturers to absorb fluctuations or reformulate around domestic oat and whey substitutes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and ingredient provenance, with enzymatically hydrolyzed plant protein bars commanding the widest spreads. Pricing pressure stems from CU and GS25 slotting fee escalation, which disproportionately burdens emerging brands lacking legacy distribution relationships. Corporate procurement departments show least price sensitivity, while teen consumers through school-adjacent convenience stores drive volume at compressed per-unit economics.
Supply Chain Analysis
Single-source vulnerability sits with California nut suppliers exposed to drought cycles, compelling Korean manufacturers to diversify into Australian and Vietnamese cashew sourcing. Raw material dependencies center on domestic oat cultivation, imported whey isolates, and enzymatically processed pea protein from Chinese processors. Supply chain risk concentrates in MFDS novel ingredient approval timelines, which delay superfood additive launches and extend product development cycles. Distribution runs through integrated conglomerate networks serving CU, GS25, and 7-Eleven, with direct-to-consumer subscription models emerging as a bypass channel for margin recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where protein bar specifications are hardening toward enzymatic hydrolysis and digestibility claims, displacing legacy whey-dominant formulations from corporate wellness contracts.
For Market Incumbents: Anchor shelf dominance through captive laboratory testing facilities that compress MFDS compliance timelines versus mid-sized competitors. Defend against subscription-based entrants by locking multi-year corporate canteen contracts in Songdo and Gangnam wellness clusters. Deepen backward integration into domestic oat milling to insulate margin structures from import price volatility. For New Entrants and Emerging Players: Enzymatic hydrolysis capabilities offer a technology-first wedge into the adult fitness segment, where digestibility claims now outweigh raw protein gram counts in purchase decisions. Target underpenetrated senior consumers in Gwangju-Honam through soft-texture, low-glycemic formulations distributed via pharmacy channels. Launch direct-to-consumer subscription boxes to bypass CU and GS25 slotting fees entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Gyeonggi Province producers facing disproportionate MFDS compliance burdens relative to integrated conglomerates. Long-term viability favors acquisition targets with established enzymatic processing capabilities and existing clean-label certification backlogs. Watch for inflection in government PLI scheme expansion toward agricultural processing equipment as a signal of policy-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Captures digestibility-premium positioning in Seoul corporate wellness procurement. |
| Domestic Oat Milling Integration | Reduces California drought exposure and shortens lead times for functional bar production. |
| Direct-to-Consumer Subscription Launch | Bypasses CU and GS25 slotting fees while capturing higher lifetime value per subscriber. |
| Clean-Label Certification Investment | Secures placement in employer-subsidized canteen contracts mandating shortened ingredient decks. |
| Busan-Ulsan Manufacturing Footprint | Lowers logistics costs for Southeast Asia export targeting through port infrastructure leverage. |
Research Methodology
Bottom-up fitness enthusiast and corporate procurement modeling reconciled against top-down oat and whey supply tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at CU and GS25, supply planners, and formulation chemists were cross-validated against secondary sources including MFDS regulatory filings, customs import records for nut and protein inputs, and Nielsen retail audit data. Triangulation between demand-side consumption patterns and supply-side production capacity ensures segment-level precision.
Historical trendline analysis across protein bar, granola bar, and energy bar categories established baseline growth trajectories, with projection modeling incorporating product type, flavor profile, consumer age group, and distribution channel dimensions. CAGRs were derived from segmented demand curves and supply capacity expansion plans. Forecast inputs included MFDS regulatory evolution timelines, corporate wellness program adoption rates, and enzymatic hydrolysis technology penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sugar taxation policy tightening and California drought recurrence patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Rice Snacks Market
Snacks
Germany Snack Bar Market
Snacks
Extruded Cereals Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Corn Chips Market
Snacks
South America Cereal Bar Market
Snacks
Better for You Snacks Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
India Energy Bar Market
Snacks
Mushroom Based Jerky Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Popcorn Market
Snacks
Low Calorie Biscuits Market
Snacks
Italy Energy Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Baked Chips Market