
 Corn Chips Market | 2026-2036
Corn Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Chips Market Analysis
Available tortilla-production labor is collapsing across major U.S. manufacturing corridors, constraining output at facilities supplying both retail and food service channels. PepsiCo leverages its vertically integrated corn sourcing and masa-processing infrastructure to sustain volume leadership in North American distribution. Calbee anchors its competitive position through specialized Japanese-style corn chip formulations that occupy premium shelf space across Asian retail networks.
Corn chips are thin, fried or baked snack products manufactured from nixtamalized corn masa or dry corn flour, typically seasoned and crisped to a moisture content below three percent for shelf stability and texture retention. Traditional and tortilla product types dominate volume sales in mainstream retail, while organic variants command margin premiums through certified non-GMO ingredient sourcing and clean-label positioning. Flavored segments compete on R&D intensity, with chili-lime, jalapeño, and craft-spice profiles driving repeat purchase rates among younger demographics.
FDA nutrition-labeling rules and USDA organic-certification standards govern ingredient disclosure, sodium-content claims, and non-GMO verification that manufacturers must navigate for retail placement. State-level extended producer responsibility frameworks in California and New York are forcing packaging-format decisions across bags, pouches, and boxes as brands anticipate broader compliance obligations. Stakeholders must monitor biodegradable-film cost curves and regional composting-infrastructure buildouts to decide timing on sustainable-packaging transitions before mandates harden.
Market Dynamics
Labor scarcity across U.S. tortilla-manufacturing corridors is forcing automation investments and capacity consolidation, while FDA sodium-labeling pressure and state-level packaging mandates reshape formulation and material sourcing decisions.
Growth Catalysts
- Clean-label sodium reformulation:FDA guidance on voluntary sodium reduction targets is accelerating R&D investment in potassium-chloride blends and umami-enhancing yeast extracts that maintain flavor intensity without sodium spikes.
- Masa-processing automation:Robotics integration in nixtamalization and sheeting lines is offsetting collapsing tortilla-production labor availability across Texas and California manufacturing clusters.
- Food service menu expansion:QSR and fast-casual operators are embedding corn chips into bowl formats, nacho platforms, and crumbled toppings, driving institutional volume pull-through.
Market Restraints
- White corn supply concentration:U.S. heartland drought cycles and Argentine export volatility are squeezing non-GMO white corn availability for premium masa production.
- California EPR packaging mandates:State-level extended producer responsibility frameworks are forcing immediate compliance spending on biodegradable films before cost curves flatten.
- Substitute snack displacement:Air-popped sorghum crisps and extruded legume snacks are capturing clean-label-seeking households through lower oil content and allergen-free positioning.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in Mumbai, Delhi, and Bangalore is creating shelf space for imported corn chip formats targeting urban snacking occasions.
- Compostable-film regulatory tailwind:New York and Washington state EPR rulemaking timelines are creating first-mover advantage windows for brands with validated biodegradable packaging.
- Pulse-flour masa hybridization:Convergence of extrusion technology and legume-protein processing is enabling fiber-enhanced corn chip lines that qualify for protein content claims.
Industry Challenges
- Nixtamalization skill scarcity:Traditional masa-cooking expertise is aging out of the workforce faster than automated kettle controls can replicate texture consistency.
- Non-GMO certification timelines:USDA organic and Non-GMO Project verification backlogs are delaying clean-label product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Chips Market |
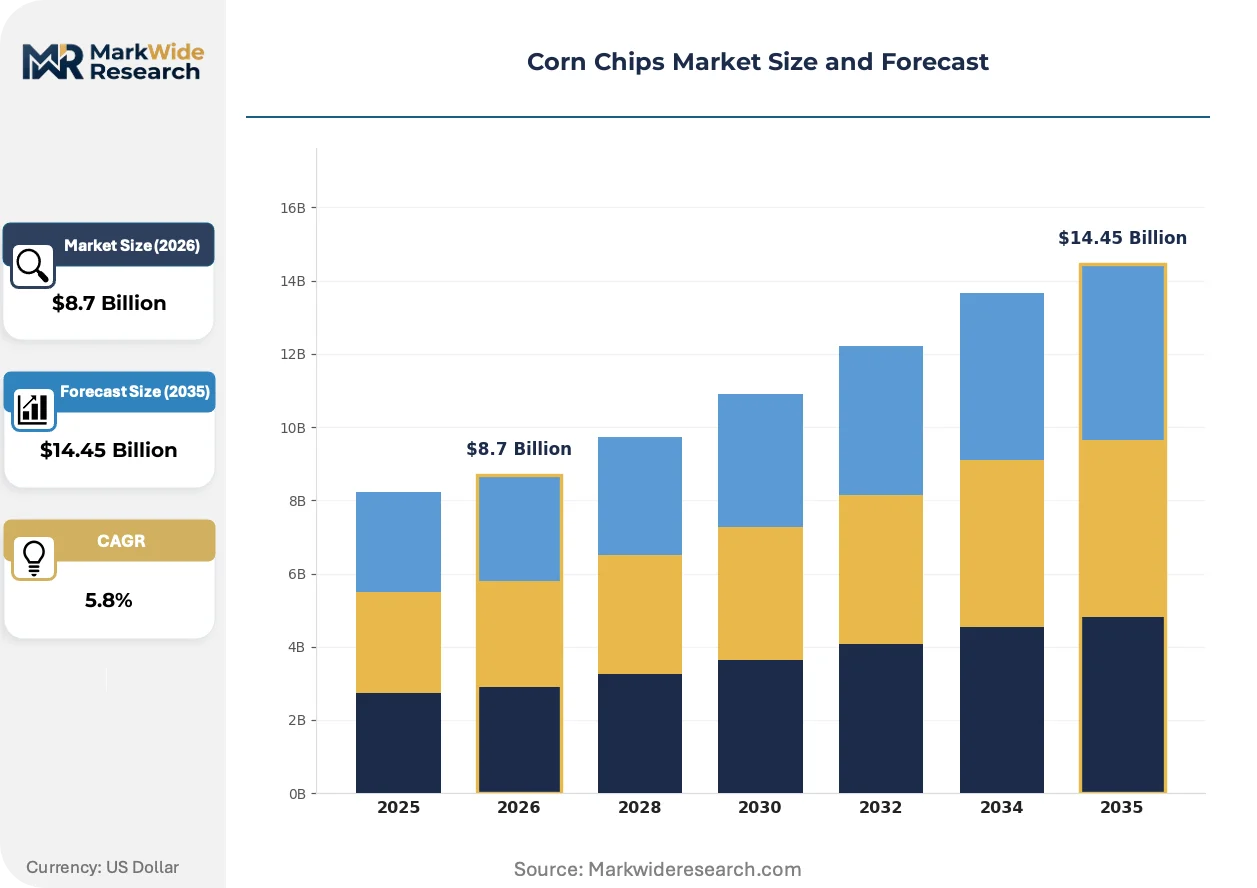
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Tortilla, Flavored, Organic Packaging Type: Bags, Boxes, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores End User: Households, Food Service, Retailers, Snack Manufacturers |
| Companies Covered | Utz Brands, Hain Celestial Group, PepsiCo, Calbee, General Mills, Mondelēz International, Intersnack Group, Conagra Brands, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Chips Market Emerging Trajectories
Processing automation and sustainable-material substitution are compressing legacy production economics while regulatory pressure on sodium and packaging accelerates formulation divergence between mass-market and premium-positioned lines.
High-shear extrusion systems with real-time moisture sensors are fragmenting traditional batch-based nixtamalization. Mid-tier manufacturers in Mexico and the southwestern United States are retrofitting legacy lines with continuous-process equipment to offset labor attrition. The technology is fragmenting capital deployment patterns, splitting investment between greenfield automation and stranded-asset retrofit decisions.
California's extended producer responsibility framework for flexible packaging is forcing immediate material transitions. The regulation mandates 30% recycled content thresholds and end-of-life producer accountability that outpaces national standards. Premium and organic corn chip SKUs are most affected, with brands testing metallized-paper alternatives and home-compostable pouches ahead of 2027 compliance deadlines.
Direct-to-pantry subscription models are displacing traditional warehouse-club bulk purchasing among millennial and Gen-Z households. Specialty retailers and brand-owned digital storefronts are capturing repeat-purchase loyalty through flavor-curation algorithms and limited-drop collaborations. This channel rotation is most visible in coastal U.S. metropolitan markets where convenience-app penetration has normalized scheduled snack replenishment.
Corn Chips Market Segmentation
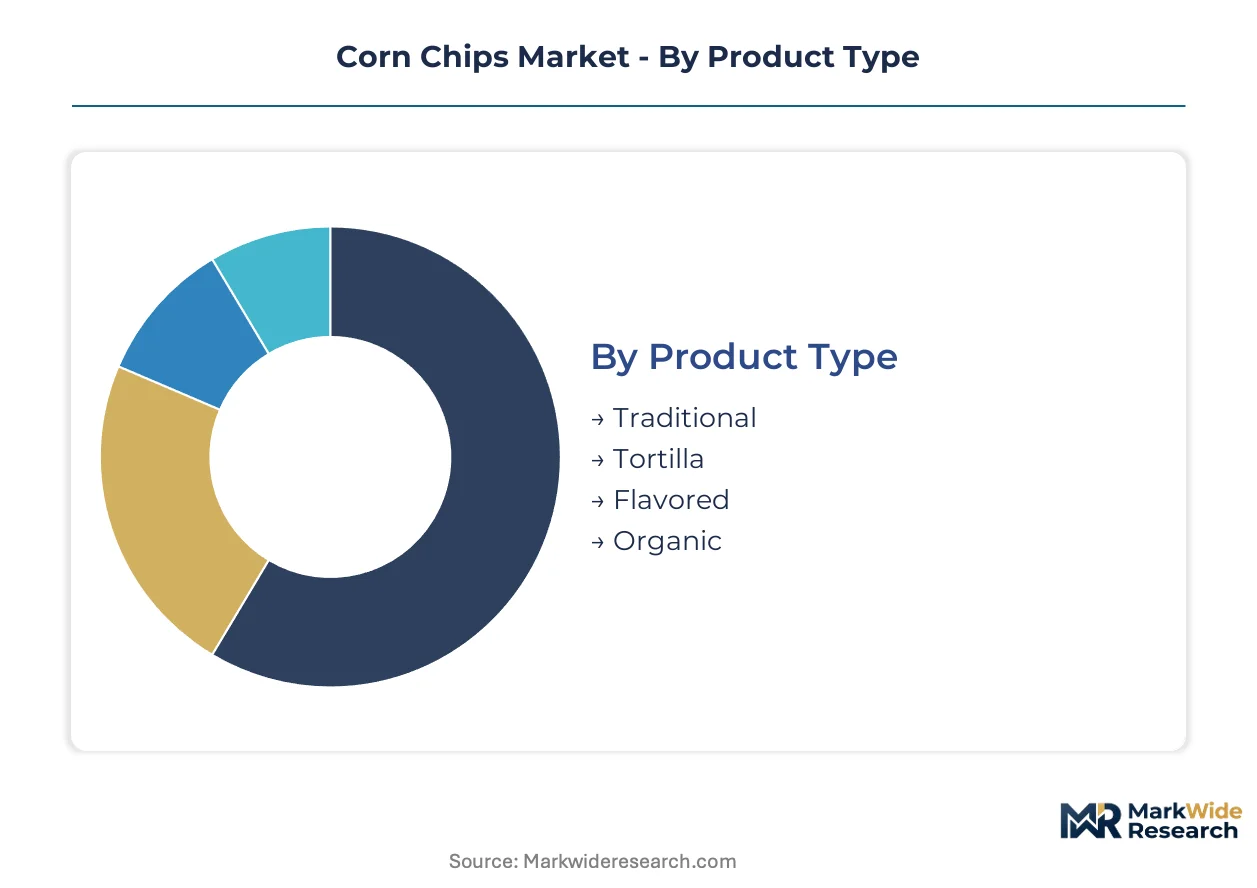
Corn chip manufacturers navigate distinct regulatory pathways across each product category. FDA sodium-labeling thresholds and USDA organic-certification standards create divergent compliance burdens that reshape margin structures and formulation investments.
Product Type:
FDA guidance on voluntary sodium reduction and USDA organic standards fragment competitive positioning across mass-market and premium-positioned lines.
- Traditional:Nixtamalized corn masa forms the base, fried or baked to sub-three-percent moisture for shelf stability. Household demand concentrates in Mexico and the southwestern United States, where masa-based snacking traditions anchor per-capita consumption.
- Tortilla:Thin, crisped rounds or triangles manufactured through continuous sheeting lines dominate food service volume. QSR and fast-casual operators embed these into nacho platforms and bowl formats, driving institutional pull-through amid labor scarcity in tortilla-manufacturing corridors.
- Flavored:Chili-lime, jalapeño, and craft-spice profiles compete on R&D intensity for younger demographic repeat purchase.
- Organic:Certified non-GMO ingredient sourcing and clean-label positioning command margin premiums through extended verification timelines.
Established volume favors Traditional; emerging adoption favors Organic.
Packaging Type:
California and New York extended producer responsibility frameworks force material transitions ahead of national standards, with compliance costs stratifying across format choices.
- Bags:Flexible film dominates retail shelf presence and warehouse-club bulk formats. California's 30% recycled-content threshold and end-of-life accountability mandates accelerate biodegradable-film testing ahead of 2027 deadlines.
- Pouches:Resealable metallized-paper alternatives and home-compostable structures gain traction in premium and organic SKUs. New York state EPR rulemaking creates first-mover advantage windows for validated biodegradable packaging.
- Boxes:Rigid secondary packaging serves multipack retail configurations and direct-to-pantry subscription channels.
- Jars:Airtight rigid containers target specialty retail and gift-format positioning with extended shelf-life claims.
Cost concentration favors Bags; sustainability-driven switching favors Pouches.
Distribution Channel:
Channel economics fragment between high-velocity mass retail and emerging digital replenishment models with divergent margin and working-capital requirements.
- Supermarkets:High-velocity shelf space allocation drives volume leadership through promotional programming and seasonal displays.
- Online Retailers:Flavor-curation algorithms and limited-drop collaborations capture millennial and Gen-Z loyalty in coastal metropolitan markets where convenience-app penetration normalizes scheduled replenishment.
- Convenience Stores:Impulse-oriented single-serve formats target immediate consumption occasions with compressed trade terms.
- Health Food Stores:Clean-label and organic variants access premium household segments with elevated margin structures and slower inventory turns.
Volume concentration favors Supermarkets; digital expansion favors Online Retailers.
End User:
Demand fragmentation separates stable household consumption from institutional growth vectors with distinct specification and procurement patterns.
- Households:Direct-to-pantry subscription models displace traditional warehouse-club bulk purchasing among younger demographics.
- Food Service:QSR and fast-casual operators expand corn chip menu applications into bowl formats, nacho platforms, and crumbled toppings amid rising snacking frequency.
- Retailers:Private-label sourcing programs and shelf-space negotiations concentrate purchasing power among consolidated grocery and club operators.
- Snack Manufacturers:Ingredient and co-manufacturing demand flows to specialized masa-processing facilities with certified production lines.
Stable demand favors Households; menu innovation favors Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium organic corn chips command pricing power in California and New York that mass-market brands cannot replicate in Texas manufacturing corridors. Mexican masa-processing clusters sustain cost advantages through nixtamalization expertise density. Indian urban retail expansion is compressing import-premium windows for foreign brands.
United States
California's EPR packaging mandates and FDA sodium-labeling pressure are forcing material and formulation transitions ahead of national standards. The state's 30% recycled-content threshold accelerates biodegradable-film testing among premium SKUs. Los Angeles and San Diego manufacturing clusters retrofit sheeting lines with continuous-process automation to offset collapsing tortilla-production labor availability.
Mexico
Traditional masa-based snacking traditions anchor per-capita consumption volumes that dwarf U.S. household penetration rates. COFEPRIS food-safety standards govern ingredient disclosure and processing-plant certification for export-bound production. Guadalajara and Monterrey industrial corridors concentrate nixtamalization capacity serving both domestic retail and North American food service channels.
India
Organized retail penetration in Mumbai, Delhi, and Bangalore creates shelf space for imported corn chip formats targeting urban snacking occasions. FSSAI labeling standards and import tariff structures shape landed cost economics for foreign brands. Maharashtra and Karnataka retail clusters show fastest adoption of premium-positioned international snack formats among millennial households.
Japan
Specialized Japanese-style corn chip formulations occupy premium shelf space through texture differentiation and limited-batch positioning. METI food-labeling standards and plastic-resource recycling laws govern packaging-material transitions and ingredient-origin claims. Tokyo-Osaka retail corridors sustain highest per-capita spending on craft-spice and umami-enhanced snack variants.
Germany
Clean-label and organic certification requirements under EU organic regulation and national Lebensmittelrecht fragment competitive positioning between discount and premium channels. ECHA REACH compliance obligations shape additive and flavoring substance approvals for seasoned product lines. Bavaria and North Rhine-Westphalia retail clusters concentrate demand for Non-GMO Project verified and bio-certified corn chip imports.
Corn Chips Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the corn chips market. Vertically integrated masa processors with captive corn sourcing dominate volume economics, while specialized flavor houses and regional craft producers capture margin premiums through R&D intensity and limited-batch positioning. The competitive structure splits between scale-driven commodity players and premium-positioned clean-label specialists. Dominant competitive moves include automation investments to offset labor scarcity and sustainable-packaging transitions ahead of regulatory deadlines.
Within the integrated-scale tier, PepsiCo and General Mills occupy positions defined by upstream control over corn sourcing and North American distribution infrastructure. Among Asia-Pacific specialists, Calbee exemplifies the premium-texture archetype through Japanese-style formulation expertise. Hain Celestial Group sits within the clean-label certification tier, representing organic and non-GMO verification strategies that command retail shelf-space premiums.
| Leading Market Players |
|---|
| Utz Brands |
| Hain Celestial Group |
| PepsiCo |
| Calbee |
| General Mills |
| Mondelēz International |
| Intersnack Group |
| Conagra Brands |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Sixty-day white corn inventory cycles in U.S. heartland elevators directly shape margin structures across premium masa production, concentrating pricing power among vertically integrated processors with captive grain origination while squeezing contract-dependent mid-tier manufacturers.
Pricing Analysis
The customization-premium spread between standard tortilla formulations and certified organic SKUs reaches three-to-one multiples, with USDA organic verification and Non-GMO Project certification driving tier separation. Pricing stratifies across premium, standard, and economy tiers based on ingredient grade, clean-label positioning, and volume scale. Cost compression in mid-tier segments is intensifying because Argentine export volatility and drought-driven U.S. white corn shortages are squeezing non-GMO supply availability. Food service operators show lowest price sensitivity due to menu-embedding requirements, while private-label retail sourcing programs concentrate bargaining power and pressure contract manufacturers.
Supply Chain Analysis
Inbound logistics costs through Gulf Coast port congestion and container availability constraints on Asia-Pacific trade lanes are elevating landed costs for specialty seasoning inputs and processing equipment. Supply concentrates in the United States, Mexico, and Argentina for white corn origination, with nixtamalization expertise clustering in Guadalajara and Monterrey industrial corridors. The chain rests on nixtamalized corn masa, high-oleic frying oils, and metallized packaging films as critical inputs. Single-source vulnerability runs through Argentine non-GMO white corn export channels. Distribution runs through direct-store-delivery networks serving retail and food service channels with divergent replenishment frequencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn chips market sits in early-cycle expansion as clean-label snacking penetration accelerates through direct-to-pantry subscription models and QSR menu embedding.
For Market Incumbents: Compound automation investments in nixtamalization and sheeting lines to offset collapsing tortilla-production labor availability across Texas and California manufacturing clusters. Deepen upstream control over non-GMO white corn origination through captive supply contracts with heartland elevator networks to defend against Argentine export volatility. Prioritize biodegradable packaging validation ahead of California and New York EPR compliance deadlines to secure first-mover shelf positioning. For New Entrants and Emerging Players: Anchor in India organized retail expansion across Mumbai, Delhi, and Bangalore, where modern trade shelf creation offers import-premium compression windows for international formats. Target pulse-flour masa hybridization as the most penetrable white-space, enabling fiber-enhanced lines that qualify for protein content claims among health-seeking urban households. Pursue co-manufacturing partnerships with established masa processors to bypass USDA organic verification backlogs and accelerate speed-to-market. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming snack divisions lacking clean-label certification infrastructure or automation scale. Long-term viability favors processors with captive corn sourcing, verified sustainable packaging pipelines, and food service channel penetration. Watch FDA sodium-labeling rulemaking timelines as the critical inflection signal, with accelerated enforcement triggering consolidation pressure on reformulation-lagged assets.| Strategic Initiative | Industry Significance |
|---|---|
| Masa-Processing Automation | Robotics integration in nixtamalization offsets labor scarcity across southwestern U.S. manufacturing corridors. |
| Biodegradable Packaging Transition | Home-compostable pouch validation secures California EPR compliance ahead of 2027 recycled-content thresholds. |
| Pulse-Flour Hybrid Development | Legume-protein masa convergence enables fiber-enhanced SKUs qualifying for protein content claims. |
| Direct-to-Pantry Channel Launch | Subscription algorithms capture millennial loyalty in coastal metropolitan convenience-app penetration markets. |
| Food Service Menu Embedding | QSR bowl and nacho platform integration drives institutional volume pull-through amid rising snacking frequency. |
Methodological Framework
The analysis maps traditional, tortilla, flavored, and organic product segments, each validated through plant managers at masa-processing facilities, category buyers at consolidated retail operators, supply planners at food service distributors, and regulatory affairs leads navigating FDA sodium-labeling compliance. Primary fieldwork combined structured interviews with secondary validation through FDA guidance documents, USDA organic certification databases, state-level EPR rulemaking filings, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-checked outputs across stakeholder perspectives.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled product type, packaging format, distribution channel, and end-user segmentation dimensions with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation adjusted for adoption curve inflections, with forecast inputs including labor availability indices in tortilla-manufacturing corridors and biodegradable-film cost curve trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label consumer preference and stable FDA sodium-reduction guidance; material deviation would warrant model refresh. Specific risk factors include accelerated EPR mandate expansion, severe drought cycles in white corn production regions, and substitute snack displacement through air-popped sorghum or extruded legume formats. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
North America Energy Bar Market
Snacks
Seaweed Snacks Market
Snacks
United States Snack Bar Market
Snacks
Meat Snacks Market
Snacks
Italy Energy Bar Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Potato Chips Market
Snacks
Extruded Cereals Market
Snacks
High Fiber Snack Foods Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
North America Snack Pellets Market
Snacks
Asia Pacific Snack Food Market