
 North America Baked Chips Market | 2026-2036
North America Baked Chips Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baked Chips Market Insights
Asset-light co-manufacturing partnerships are reshaping competitive entry in the North America baked chips space, allowing emerging brands to scale without capital-intensive fryer-to-oven production conversions. Frito-Lay North America leverages its existing snack distribution infrastructure to secure shelf dominance across mass retail channels. Popchips anchors its position through proprietary popping technology that delivers texture parity with fried alternatives at lower oil content. Shearer’s Foods sustains private-label competitiveness through dedicated baked lines serving retailer-owned brands.
Baked chips are thin, crisp snack products manufactured by drying thinly sliced or extruded dough pieces in forced-air convection ovens rather than immersing them in hot oil, typically achieving fat content below 25% by weight while maintaining structural integrity through controlled moisture removal. Their primary commercial purpose is to satisfy salty-snack demand among consumers seeking reduced-calorie alternatives to conventional fried chips without sacrificing crunch or flavor intensity. Potato-based SKUs still occupy the largest volume share, though multi-grain formulations incorporating quinoa, lentil, or chickpea flour are capturing the fastest expansion as protein-forward positioning resonates with fitness-oriented buyers. Bag and pouch formats dominate retail velocity, but bulk packaging for foodservice and club-channel distribution is deepening margin pools through lower per-unit packaging costs and higher average transaction values.
The FDA enforces nutrition fact panel disclosures and serving-size standardization that directly influence front-of-package health claims and sodium reduction targets across the category. USDA organic certification and Non-GMO Project verification create tiered market access, with certified products commanding differentiated placement in specialty and natural-channel retail. Health Canada’s Food and Drug Regulations impose parallel compositional standards that manufacturers must navigate for cross-border SKU harmonization. Stakeholders must monitor evolving front-of-package warning label proposals and sodium reduction mandates that could force rapid reformulation cycles or channel-specific product line segmentation.
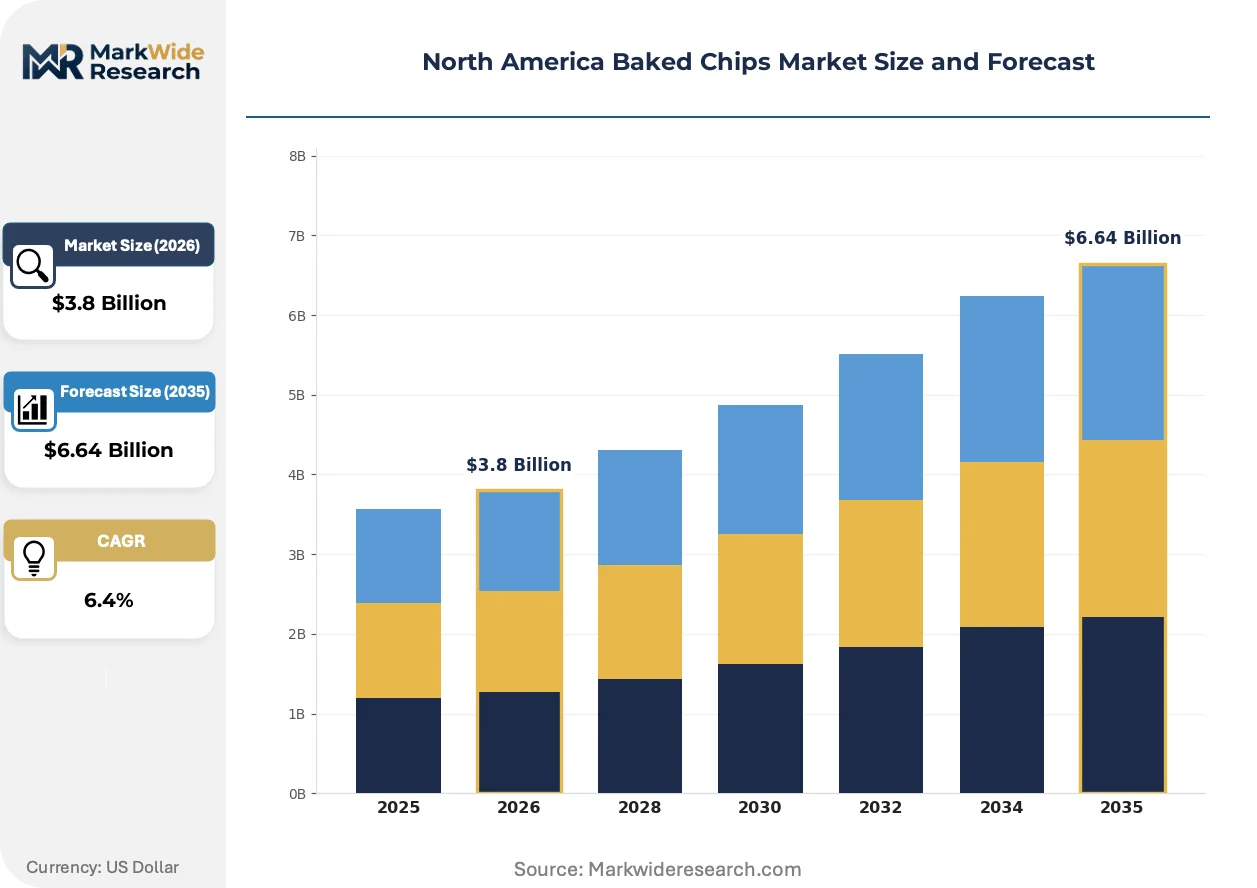
Market Dynamics
The North America baked chips market is restructuring around forced-air convection oven retrofits and co-manufacturing network density, as capital constraints prevent mid-tier brands from owning dedicated baked production lines.
Growth Catalysts
- FDA sodium reduction mandates:The agency's voluntary sodium targets are compelling manufacturers to reformulate recipes, expanding the addressable market for baked variants that achieve flavor parity at lower salt levels.
- Quinoa and chickpea flour adoption:Alternative base materials are enabling protein-forward positioning that commands shelf placement in fitness-oriented retail clusters across California and the US Northeast.
- Online grocery platform expansion:Dedicated snack aisles on Instacart and Amazon Fresh are reducing slotting fee barriers for emerging baked chip brands seeking trial outside conventional convenience store channels.
Market Restraints
- Potato input cost volatility:Weather-driven harvest variability in Idaho and Washington State compresses margin predictability for potato-based SKUs that still dominate volume.
- Oven equipment supplier concentration:German and Italian forced-air convection oven manufacturers control critical baking technology, creating capex bottlenecks for North American capacity expansion.
- Texture parity limitations:Baked products struggle to replicate the mouthfeel of kettle-fried alternatives in thicker-cut formats, constraining premium positioning in the super-premium snack tier.
Strategic Opportunities
- Canadian natural-channel penetration:Health Canada's front-of-package labeling proposals are accelerating retailer demand for cleaner-label baked alternatives in Toronto and Vancouver metropolitan markets.
- Foodservice bulk format development:Club-channel and cinema concession segments represent underdeveloped volume pools for lower-oil alternatives that reduce fryer exhaust compliance burdens.
- USDA organic certification tailwinds:Federal organic cost-share programs are reducing certification barriers for mid-tier brands seeking differentiated placement in Whole Foods and Sprouts Farmers Market.
Industry Challenges
- Food technologist scarcity:Formulation expertise at the intersection of extrusion processing and clean-label ingredient functionality commands premium compensation, constraining R&D velocity for emerging brands.
- Multi-certification timeline compression:Simultaneous pursuit of Non-GMO Project verification, USDA Organic, and gluten-free claims extends go-to-market cycles by 8-14 months.
- Legacy fryer infrastructure stranding:Existing capital equipment in owned manufacturing footprints creates organizational resistance to oven conversion investments despite shifting demand signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baked Chips Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato, Corn, Multi-grain, Vegetable Flavor Profile: Cheddar, Barbecue, Sea Salt, Sour Cream Packaging Type: Bag, Pouch, Box, Bulk Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Shops |
| Companies Covered | General Mills, PepsiCo, Frito-Lay North America, The Kellogg Company, Calbee North America, Popchips, Herr’s Food, Shearer’s Foods, Snyder’s-Lance, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baked Chips Market Trends and Innovations
Forced-air convection technology is migrating from batch to continuous processing architectures, while regulatory pressure on sodium and trans-fat content accelerates formulation science investment across the category.
Extrusion-based forming technology is migrating from single-screw to twin-screw systems that enable precise moisture control and structural uniformity in lentil and chickpea flour matrices. Mid-tier manufacturers in Texas and Illinois are adopting these systems to reduce dependency on sliced-potato supply chains. The shift is migrating from niche organic producers to mainstream private-label suppliers, compressing the technology premium that previously separated premium from mass-market positioning.
The FDA's updated Nutrition Facts label requirements and forthcoming front-of-package warning label proposals are forcing sodium disclosure transparency that disadvantages legacy formulations. Manufacturers must now reformulate or segment product lines by channel to maintain velocity in schools and healthcare facilities where sodium limits are binding. California and New York school nutrition standards are most affected, driving accelerated R&D partnerships between baked chip producers and ingredient suppliers.
Millennial and Gen Z buyers are consolidating snack purchases through subscription-based replenishment models on Thrive Market and direct-to-brand portals, bypassing traditional impulse-driven convenience store distribution. This pattern concentrates demand forecasting accuracy requirements on a smaller cohort of high-volume digital accounts. The shift is most visible in coastal urban clusters where same-day delivery infrastructure supports fresh-format baked chip logistics.
North America Baked Chips Market Segmentation
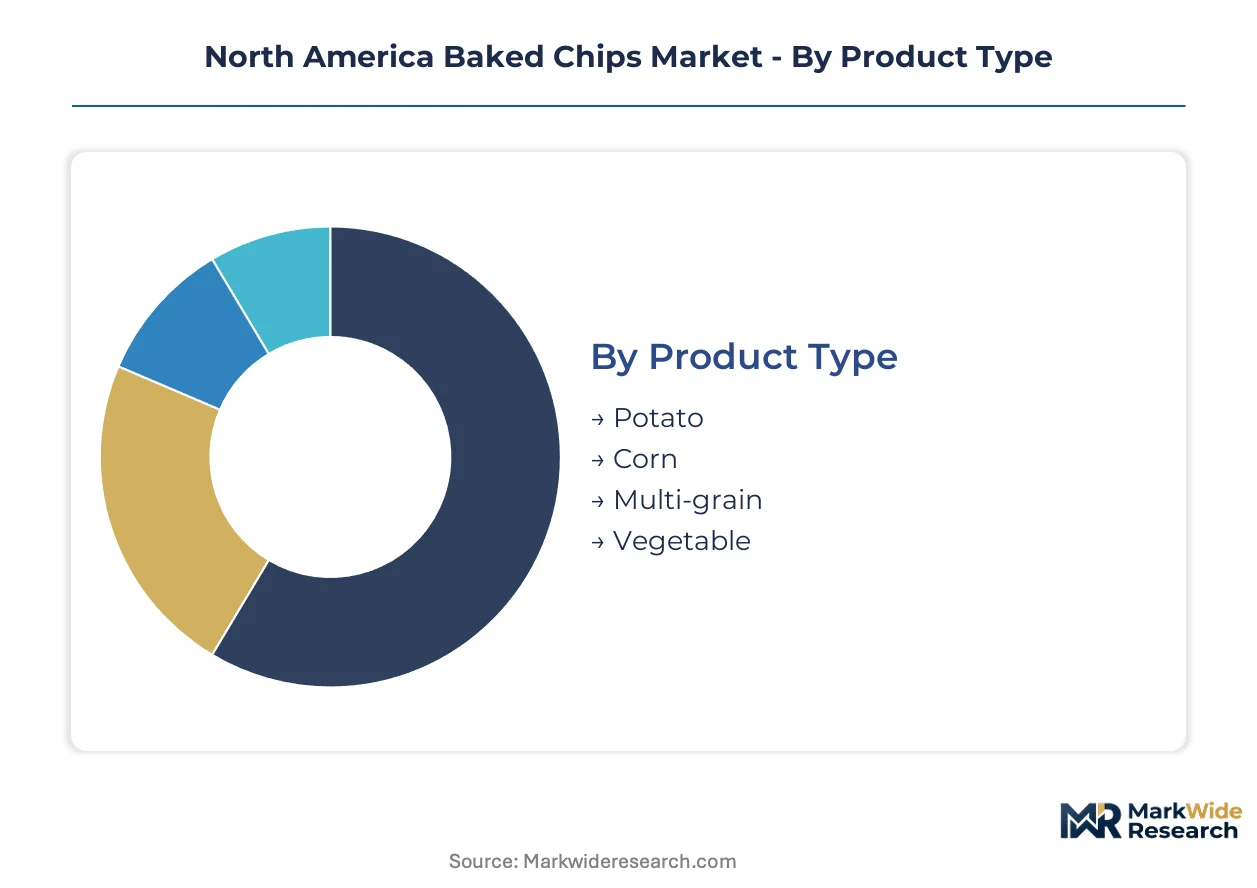
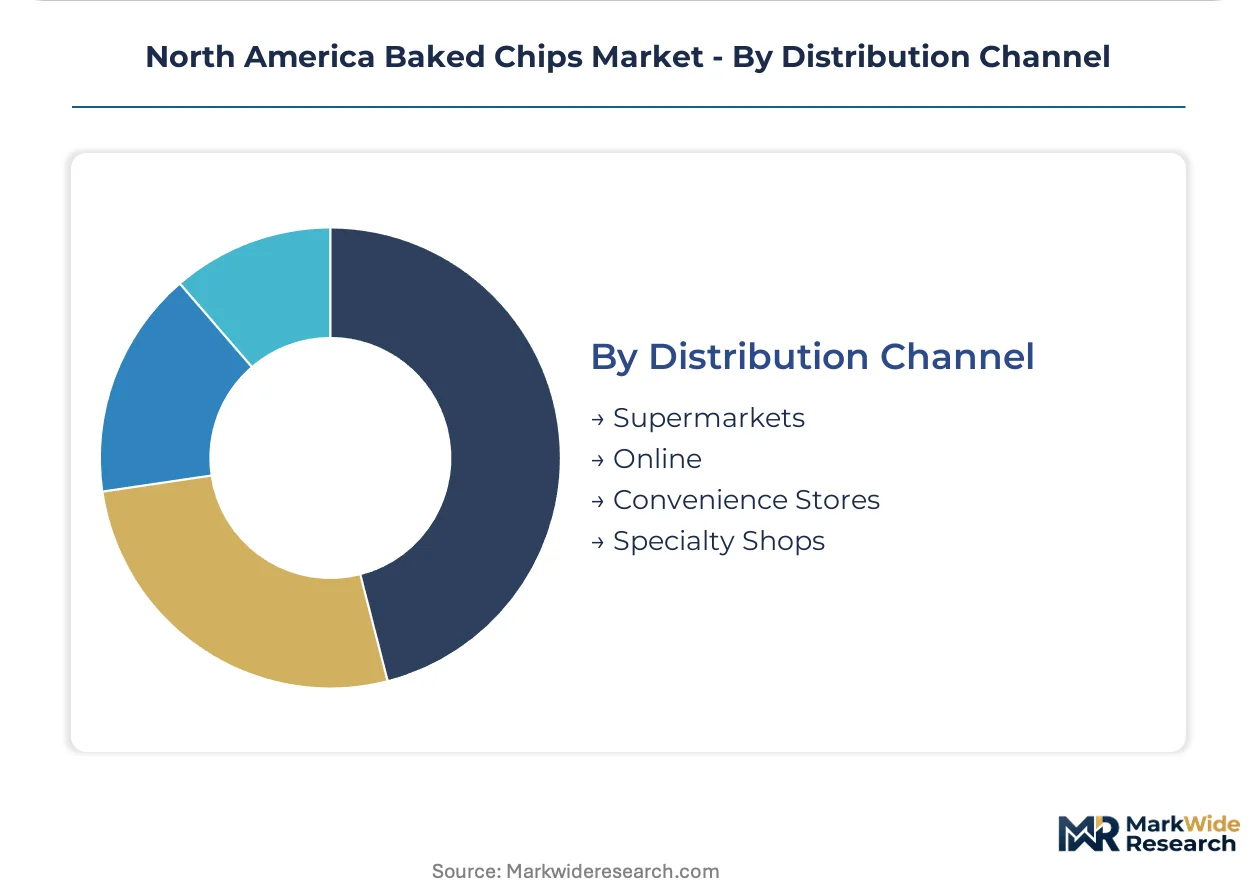
Segmentation in the North America baked chips market reveals how formulation choices, flavor engineering, and channel access determine margin capture. Product type and distribution channel splits expose where capital concentrates versus where emerging brands find entry points.
Product Type:
Cost tier differentiation separates commodity potato bases from premium-positioned alternative grains that command shelf placement in natural-channel retail.
- Potato:Thin-sliced tuber bases processed through forced-air convection ovens achieve sub-25% fat content while maintaining structural integrity through controlled moisture removal. Demand concentrates in mass retail across the US Northeast and Midwest, where price-sensitive households prioritize familiarity over nutritional novelty.
- Multi-grain:Formulations incorporating quinoa, lentil, or chickpea flour enable protein-forward positioning that resonates with fitness-oriented buyers in California and Toronto metropolitan markets. This segment is climbing the fastest as USDA organic certification and Non-GMO Project verification create tiered access to Whole Foods and Sprouts Farmers Market.
- Corn:Extruded masa bases deliver neutral flavor carriers for bold seasoning applications, occupying mid-tier price positioning in club-channel assortments.
- Vegetable:Root vegetable and beet-infused variants target color-driven purchase decisions in specialty retail, though texture parity limitations constrain mainstream penetration.
Potato holds installed capacity. Multi-grain is rotating up the share rankings.
Flavor Profile:
Application context determines flavor intensity requirements, with on-the-go consumption favoring bold profiles and home pantry stocking preferring versatile bases.
- Sea Salt:Minimal seasoning loads align with sodium reduction mandates from the FDA, enabling placement in school nutrition programs and healthcare facilities where binding limits apply. Demand concentrates in California and New York school districts driving reformulation partnerships between producers and ingredient suppliers.
- Barbecue:Smoked tomato and molasses-based coatings deliver the highest flavor intensity in the category, anchoring convenience store velocity through impulse-driven purchase triggers. This segment is expanding most quickly as millennial and Gen Z buyers consolidate snack purchases through subscription replenishment models.
- Cheddar:Cheese powder adhesion requires modified starch systems that complicate clean-label positioning, constraining penetration in natural-channel retail.
- Sour Cream:Dairy-derived tang targets repeat-purchase loyalty in family-format packaging, though lactose-free alternatives are displacing traditional formulations in specialty shops.
Sea Salt maintains formulation flexibility. Barbecue is gaining share fastest through digital channel expansion.
Packaging Type:
Volume scale and margin structure diverge sharply between single-serve impulse formats and bulk formats that reduce per-unit packaging costs.
- Bag:Pillow-pack configurations with nitrogen flush dominate retail velocity, accounting for the majority of supermarket and convenience store facings. Demand concentrates in urban retail clusters where shelf space constraints favor vertical stacking efficiency.
- Bulk:Club-channel and cinema concession formats represent underdeveloped volume pools, with lower per-unit packaging costs deepening margin pools through higher average transaction values. This segment shows steepest expansion trajectory as foodservice operators seek fryer exhaust compliance reductions.
- Pouch:Stand-up configurations with resealable closures target pantry stocking behavior, commanding premium placement in online grocery platforms.
- Box:Rigid secondary packaging enables multi-pack bundling for warehouse club distribution, though corrugated material costs compress margins versus flexible alternatives.
Bag holds installed capacity. Bulk is rotating up the share rankings.
Distribution Channel:
Customer type and purchase occasion fragmentation determines where emerging brands can bypass incumbent slotting fee barriers.
- Supermarkets:Traditional grocery dominates absolute volume, with baked chip placement in perimeter fresh sections and center-store snack aisles requiring separate buyer relationships. Demand concentrates in US Northeast and California urban retail clusters where premium and multi-grain variants command dedicated shelf space.
- Online:Instacart and Amazon Fresh dedicated snack aisles reduce slotting fee barriers for emerging brands seeking trial outside conventional channels. This segment is climbing the fastest as same-day delivery infrastructure supports fresh-format logistics in coastal metropolitan markets.
- Convenience Stores:Impulse-driven purchase patterns favor single-serve bags with bold flavor profiles, though space constraints limit SKU breadth.
- Specialty Shops:Natural-channel and gourmet retailers demand multi-certification compliance that extends go-to-market cycles by 8-14 months.
Supermarkets hold installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border ingredient sourcing and finished goods distribution between the United States and Canada dominate regional trade flows, with Mexican import volumes rising as contract manufacturers expand oven capacity in Baja California and Querétaro to serve US Southwest demand.
United States
Millennial and Gen Z health-conscious snacking in California and the US Northeast drives premium multi-grain adoption. FDA sodium reduction mandates and updated Nutrition Facts labeling requirements compel reformulation investments. Chicago and Dallas-Fort Worth metropolitan clusters concentrate co-manufacturing partnerships that enable emerging brands to bypass capital-intensive oven ownership.
Canada
Toronto and Vancouver metropolitan markets exhibit accelerating demand for cleaner-label baked alternatives ahead of Health Canada's front-of-package labeling proposals. The country's Food and Drug Regulations impose compositional standards that require cross-border SKU harmonization for US exporters. Montreal and Calgary retail clusters increasingly demand Non-GMO Project verification for natural-channel placement.
Mexico
Querétaro and Baja California manufacturing corridors attract US brand owners seeking nearshore oven capacity expansion without German equipment supplier lead times. Mexican consumers in Mexico City and Monterrey metropolitan areas demonstrate rising trial rates for lower-fat snack alternatives through modern trade channels. PROFECO consumer protection standards influence packaging claim substantiation requirements for imported baked chip products.
North America Baked Chips Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient technology and oven equipment supply. The North America baked chips market exhibits consolidated mass-retail dominance alongside fragmented natural-channel entry points. Three archetypes define competitive positioning: diversified snack conglomerates with fryer-to-oven conversion capabilities, emerging brands leveraging asset-light co-manufacturing, and private-label specialists serving retailer-owned brand programs. Capacity expansion through co-manufacturing network density and portfolio diversification into alternative grain bases represent the dominant competitive moves.
Within the diversified snack conglomerate tier, Frito-Lay North America and General Mills occupy positions defined by existing distribution infrastructure and scale economics. Among emerging brand archetypes, Popchips exemplifies proprietary technology differentiation. Private-label competitiveness concentrates around Shearer's Foods as a dedicated baked line operator serving retailer programs.
| Leading Market Players |
|---|
| General Mills |
| PepsiCo |
| Frito-Lay North America |
| The Kellogg Company |
| Calbee North America |
| Popchips |
| Herr's Food |
| Shearer's Foods |
| Snyder's-Lance |
| Others |
Pricing and Supply Chain Analysis
German and Italian forced-air convection oven manufacturers anchor upstream equipment supply, concentrating margin capture with co-manufacturing networks that emerging brands must access to bypass capital-intensive oven ownership.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the North America baked chips market. Price differentiation hinges on certification grade—USDA Organic and Non-GMO Project verification command placement premiums in Whole Foods and Sprouts Farmers Market—and volume scale, with club-channel bulk formats reducing per-unit costs. Pricing pressure stems from potato input cost volatility in Idaho and Washington State, compressing margins for commodity potato-based SKUs. Mass retail buyers in the US Midwest exhibit highest price sensitivity, while fitness-oriented consumers in California and Toronto metropolitan markets show lowest sensitivity for protein-forward multi-grain variants.
Supply Chain Analysis
Co-manufacturing concentration sits with Shearer's Foods and regional contract operators in Texas and Illinois that hold dedicated baked production lines. Geographic supply draws from Idaho and Washington State for potato inputs, Saskatchewan and Manitoba for pulse flour alternatives, and Querétaro and Baja California for nearshore oven capacity expansion. Raw material dependencies center on tuber harvests, quinoa and chickpea flour supply chains, and nitrogen flush packaging films. Single-source vulnerability runs through German and Italian oven equipment suppliers, creating capex bottlenecks for North American capacity expansion. Distribution feeds from co-manufacturing nodes through Frito-Lay's existing snack infrastructure to mass retail channels, with Instacart and Amazon Fresh emerging as direct-to-consumer alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America baked chips market operates as a substitution defense against kettle-fried alternatives and emerging air-popped formats that threaten to displace oven-baked positioning.
For Market Incumbents: Pre-empt air-popped substitute encroachment by accelerating proprietary texture technology investments that maintain mouthfeel parity at lower oil content. Secure exclusive co-manufacturing partnerships in Chicago and Dallas-Fort Worth clusters to constrain emerging brand capacity access. Anchor shelf position through backward integration into alternative grain flour milling, reducing dependency on volatile potato supply chains. For New Entrants and Emerging Players: Canadian natural-channel retail in Toronto and Vancouver metropolitan markets offers underpenetrated white space ahead of Health Canada's front-of-package labeling implementation. Foodservice bulk formats for cinema concessions and club channels represent secondary entry points with lower slotting fee barriers. Pursue USDA organic certification cost-share programs to unlock differentiated placement in coastal urban clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed co-manufacturing specialists holding dedicated baked lines and established retailer relationships. Long-term viability across the analysis window favors platforms with multi-grain formulation capabilities and cross-border SKU harmonization infrastructure. Monitor FDA sodium reduction mandate progression as the critical inflection signal for reformulation-driven consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Manufacturing Partnership Expansion | Asset-light capacity access enables emerging brands to bypass German oven equipment lead times. |
| Alternative Grain Base Diversification | Quinoa and chickpea flour sourcing reduces dependency on Idaho potato harvest variability. |
| USDA Organic Certification Investment | Federal cost-share programs unlock premium placement in Sprouts Farmers Market and Whole Foods. |
| Foodservice Bulk Format Development | Club-channel and cinema concession segments reduce fryer exhaust compliance burdens for operators. |
| Direct-to-Consumer Platform Launch | Thrive Market and brand-owned portals bypass convenience store slotting fee structures. |
Research Methodology
Desk research of FDA guidance documents, USDA organic certification databases, and Nielsen retail audit data preceded structured interviews with baked chip brand managers, co-manufacturing operations directors, category buyers at mass retail chains, and ingredient supplier technical R&D leads. Primary fieldwork combined with secondary validation from Health Canada regulatory filings and customs trade records. Bottom-up volume modeling triangulated against top-down category expenditure estimates across the projection horizon.
Assumptions held FDA sodium reduction targets and Health Canada front-of-package labeling proposals as baseline regulatory trajectories, with alternative grain adoption rates and co-manufacturing network expansion as variable demand-side drivers. Segmentation modeling incorporated product type, flavor profile, packaging format, and distribution channel dimensions alongside certification tier as an industry-specific stratifier. CAGRs derived from trend extrapolation of historical velocity patterns adjusted for channel shift acceleration in online grocery platforms.
Practitioners should monitor potato harvest yield reports, German oven equipment order backlogs, and FDA front-of-package warning label rulemaking for early signals of forecast revision. Quarterly review of alternative grain flour pricing indices and co-manufacturing capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
Grass-Fed Jerkies Market
Snacks
Sweet Potato Chips Market
Snacks
No Fat Snacks Market
Snacks
India Energy Bar Market
Snacks
Cheese Snacks Market
Snacks
UAE Snack Bar Market
Snacks
Europe Snack Pellets Market
Snacks
Europe Extruded Snack Food Market
Snacks
North America Savory Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Energy Bar Market
Snacks
Low Fat Crackers Market
Snacks
Baked Chips Market