
 Italy Food Colorants Market | 2026-2036
Italy Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Colorants Market Foresight
Italian natural extract production capacity is hardening as domestic growers of spirulina and beetroot concentrates expand cultivation hectares. Sensient Technologies leverages its Milan-based technical center to develop plant-derived color solutions for regional pasta and sauce brands. AromataGroup SRL anchors its position through backward integration into Mediterranean botanical sourcing. Chr. Hansen Holdings specializes in fermentation-based natural reds for Italian dairy applications.
Food colorants comprise pigments and dyes added to edible products to restore, enhance, or standardize visual appearance, with natural variants typically extracted via aqueous or solvent methods from fruits, vegetables, insects, or minerals and specified for light stability, pH tolerance, and thermal resistance. Synthetic colorants, though mature in Italy, face structural decline as EFSA safety reassessments drive reformulation costs upward. Natural colorants capture expanding margin pools across beverage applications, where turmeric and anthocyanin formulations command premium positioning in functional drink lines. Powder forms dominate industrial-scale bakery operations, while liquid concentrates gain traction in artisanal confectionery workshops requiring precise dosing control.
EFSA purity protocols and the EU's Food Improvement Agents Package govern additive authorization, with Italy's Ministry of Health enforcing national surveillance through regional veterinary and hygiene services. ECHA REACH compliance adds supply chain documentation burdens for imported pigment intermediates. Stakeholders must monitor pending EFSA opinions on titanium dioxide alternatives and copper chlorophyllin restrictions, as these rulings will force immediate formulation pivots across Italy's processed food sector.
Market Dynamics
EFSA's tightening purity protocols on synthetic additives are forcing Italian manufacturers into accelerated reformulation cycles, compressing development timelines while elevating natural extract procurement as a strategic priority for competitive positioning.
Growth Catalysts
- Clean-label confectionery demand:Northern Italian artisanal chocolate and pastry producers are expanding natural colorant specifications to meet retailer sustainability mandates.
- REACH documentation convergence:ECHA compliance requirements for imported pigment intermediates are standardizing supply chain transparency across Emilia-Romagna's industrial food corridor.
- Fermentation-derived reds:Dairy applications in Lombardy's cheese-producing regions are adopting microbial pigment systems for stable color performance in aged products.
Market Restraints
- Spirulina cultivation seasonality:Domestic blue-green algae production faces yield volatility from Mediterranean climate fluctuations, constraining year-round supply security.
- Beetroot concentrate input costs:Agricultural land competition from sugar beet and biofuel crops elevates raw material pricing for red colorant formulations.
- Light stability technical ceiling:Anthocyanin-based solutions degrade under UV exposure, limiting shelf-life extension in transparent beverage packaging.
Strategic Opportunities
- Sicilian citrus peel valorization:Untapped carotenoid extraction from orange processing waste offers circular economy positioning for southern Italian producers.
- Pasta sauce clean-label differentiation:Tomato-based product lines in Parma and Modena are creating specification pull for chlorophyll-copper alternatives.
- Artisanal gelato channel expansion:Small-batch frozen dessert workshops in Florence and Bologna represent concentrated demand for liquid concentrate precision dosing systems.
Industry Challenges
- Natural colorant formulation expertise gap:Food technologists with cross-functional knowledge of plant chemistry and thermal processing are scarce in Veneto's industrial zones.
- EFSA opinion tracking latency:Pending rulings on titanium dioxide substitutes require pre-positioned R&D investments before regulatory certainty emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Colorants Market |
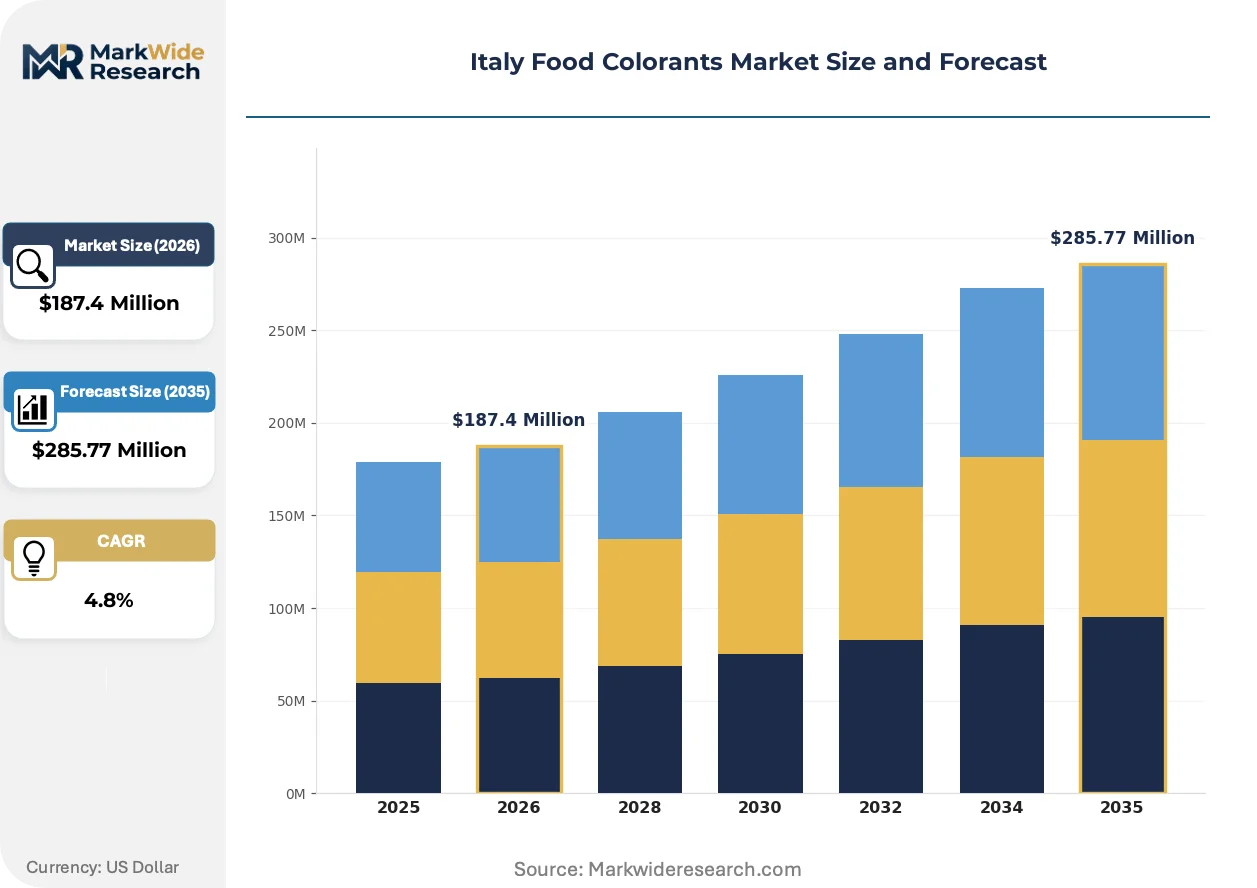
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Organic Colorants, Inorganic Colorants Application: Beverages, Bakery Products, Confectionery, Dairy Products Form: Powder, Liquid, Gel, Paste End User: Food Manufacturers, Beverage Producers, Confectionery Makers, Restaurants |
| Companies Covered | Sensient Technologies, AromataGroup SRL, BASF SE, Koninklijke DSM N.V., Barentz International B.V., Chr. Hansen Holdings, Dohler Group SE, Nactarome S.p.A., GNT International B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Colorants Market Shifts & Advancements
Microencapsulation technologies and fermentation-based production systems are compressing the performance gap between natural and synthetic colorants, while regulatory surveillance intensifies supply chain documentation requirements across Italian food manufacturing.
Encapsulated turmeric and paprika oleoresin systems are modularizing colorant delivery for beverage applications, enabling pH-stable dispersion in functional drink formulations. Milan-based formulation labs are adopting these systems at accelerated rates for probiotic and kombucha product lines. The technology is modularizing supplier relationships as compounders assume integrated stability-testing responsibilities previously held by end-manufacturers.
EFSA's pending re-evaluation of copper chlorophyllin additives is compressing authorization timelines for green colorant alternatives. Italian Ministry of Health surveillance protocols now require enhanced purity documentation for imported chlorophyll derivatives. Pasta and ready-meal producers in the Po Valley are accelerating reformulation programs to preempt potential usage restrictions.
Direct procurement relationships between colorant specialists and regional agricultural cooperatives are displacing traditional distributor intermediaries. Beverage manufacturers in Trentino-Alto Adige are contracting directly with spirulina growers for traceable supply chains. This pattern concentrates most visibly in organic-certified product lines where ingredient provenance commands shelf-space premiums.
Italy Food Colorants Market Segmentation
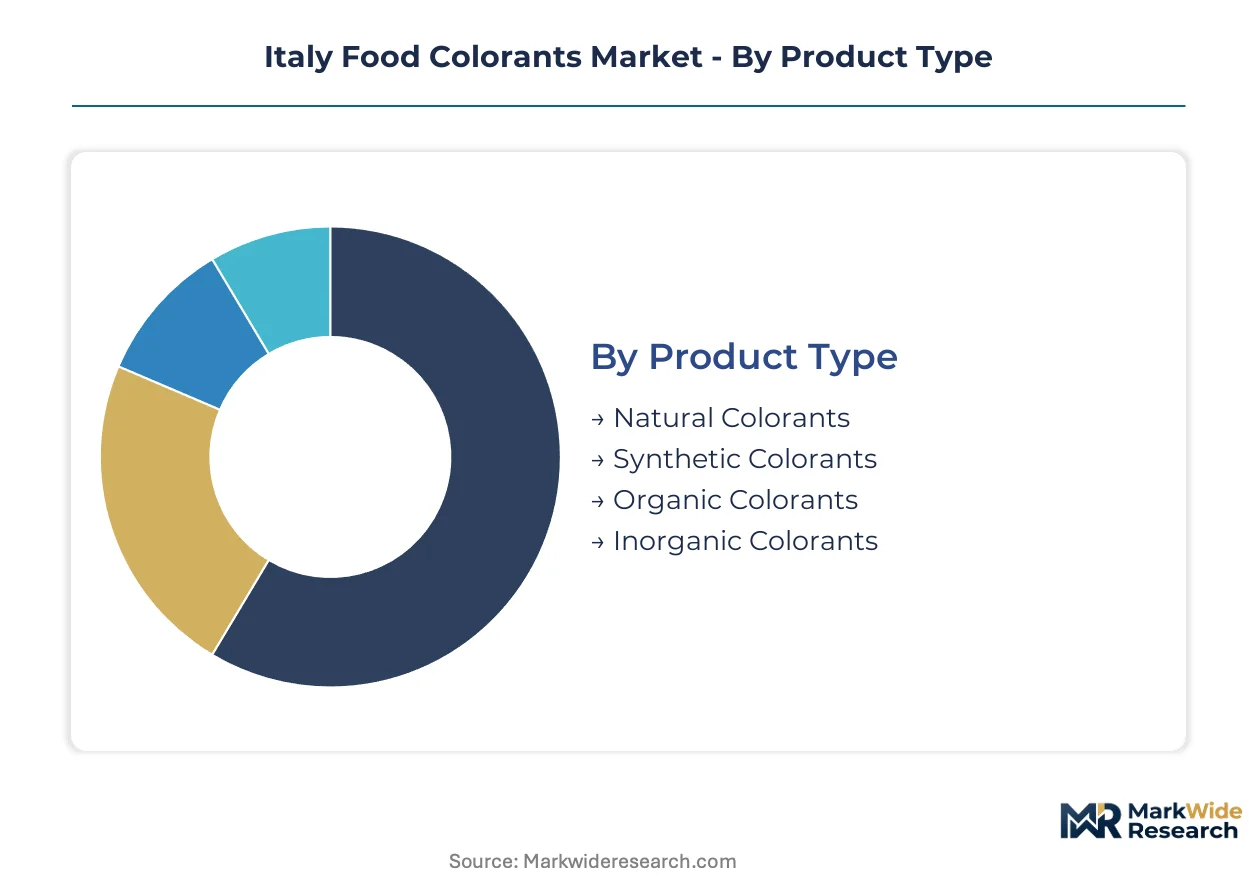
Food colorant procurement patterns across Italy diverge sharply by processing scale and regulatory exposure. Northern industrial corridors favor bulk powder systems, while artisanal producers in Tuscany and Emilia-Romagna drive demand for precision liquid formats.
Product Type:
Capital intensity peaks with fermentation infrastructure for microbial pigments, followed by solvent extraction equipment for botanical concentrates.
- Natural Colorants:Anthocyanin, carotenoid, and chlorophyll derivatives extracted via aqueous or supercritical CO2 methods. Beverage applications in Milan's functional drink cluster absorb the highest volumes, though light stability limitations constrain shelf-life claims in transparent packaging.
- Synthetic Colorants:Azo dyes and triphenylmethane compounds manufactured through petrochemical synthesis. EFSA purity protocol tightening has compressed margins as reformulation costs mount; demand now concentrates in private-label confectionery where price positioning overrides clean-label specifications.
- Organic Colorants:Certified organic extracts from spirulina, beetroot, and turmeric meeting EU 2018/848 standards. Premium gelato producers in Bologna specify these for traceability documentation.
- Inorganic Colorants:Mineral-based pigments including titanium dioxide and iron oxides. EFSA's pending titanium dioxide re-evaluation has frozen new product development across Italy's ready-meal sector.
Natural colorants absorb the bulk of installed capacity; organic-certified variants are expanding most quickly.
Application:
Volume concentration aligns with Italy's regional food manufacturing specializations, from Lombardy's dairy belt to Sicily's citrus processing zones.
- Beverages:Functional drinks, juices, and probiotic formulations requiring pH-stable color systems. Turmeric and spirulina concentrates dominate Trentino-Alto Adige's organic beverage cluster.
- Bakery Products:Industrial-scale bread, pastry, and biscuit operations in Veneto favor powder colorants for dough integration efficiency.
- Confectionery:Artisanal chocolate and sugar confectionery across Turin and Perugia drives demand for heat-stable natural reds and gold shimmer effects.
- Dairy Products:Aged cheeses and yogurts in Lombardy and Piedmont specify fermentation-derived carotenoids for consistent color through maturation.
Beverage applications command the steepest expansion trajectory as functional drink lines proliferate.
Form:
Customer scale determines format selection, with powder dominating high-throughput operations and liquid concentrates penetrating craft production.
- Powder:Spray-dried or milled pigments for industrial dosing systems. Parma's pasta sauce manufacturers specify these for dry-mix integration.
- Liquid:Concentrated solutions with standardized color strength. Florence's gelato workshops require these for batch-to-batch consistency.
- Gel:Viscous suspensions for decorative applications. Limited uptake outside specialty cake decoration supply chains.
- Paste:High-pigment-load formulations for intense color saturation. Regional sausage producers in Calabria utilize these for casing tinting.
Powder formats retain the largest installed base; liquid concentrates are gaining share fastest among artisanal channels.
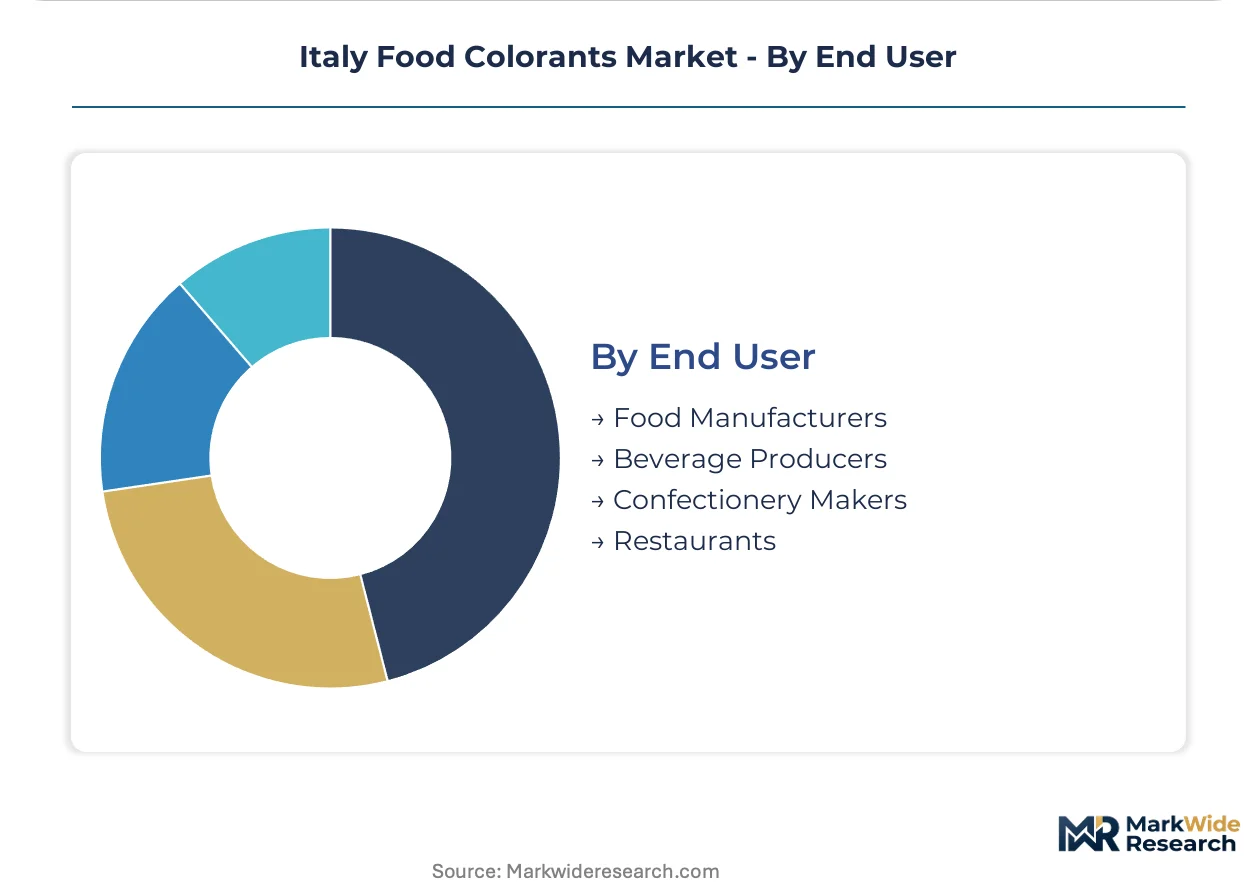
End User:
Procurement sophistication varies by buyer scale, from multinational documentation requirements to small-batch flexibility needs.
- Food Manufacturers:Industrial processors across Emilia-Romagna's packaged goods corridor. These buyers enforce REACH-compliant supply chain documentation and audit natural extract provenance.
- Beverage Producers:From multinational bottlers to regional kombucha startups. Northern Italian organic beverage specialists prioritize direct contracts with spirulina growers.
- Confectionery Makers:Artisanal chocolate houses in Turin and industrial sugar confectionery in Milan. Clean-label specifications now standard across both tiers.
- Restaurants:High-end dining and pastry shops requiring small-volume, high-flexibility supply. Limited colorant volume but premium pricing tolerance.
Food manufacturers absorb the bulk of procurement volume; beverage producers are climbing the fastest as functional drink launches accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirulina cultivation in Trentino-Alto Adige and beetroot farming across the Po Valley anchor Italy's natural colorant feedstock geography, with processing infrastructure clustering along the Milan-Parma-Bologna industrial corridor.
Lombardy
Dairy applications in the provinces of Cremona and Lodi drive fermentation-derived carotenoid demand for aged cheese color stability. EFSA purity protocols on synthetic additives compel reformulation investments across the region's dairy cooperatives. Milan's technical formulation labs serve as the primary development hub for beverage colorant systems targeting functional drink lines.
Emilia-Romagna
Pasta sauce manufacturers in Parma and Modena specify chlorophyll-copper alternatives for clean-label differentiation in tomato-based products. REACH documentation requirements for imported pigment intermediates standardize supply chain transparency across the region's industrial food corridor. Bologna's gelato workshops concentrate demand for liquid concentrate precision dosing systems in artisanal frozen dessert production.
Piedmont
Artisanal chocolate houses in Turin expand natural colorant specifications for heat-stable reds and gold shimmer effects in premium confectionery. The Italian Ministry of Health enforces national surveillance through regional veterinary services, elevating documentation burdens for imported botanical extracts. The province anchors northern Italy's specialty confectionery colorant procurement.
Veneto
Industrial-scale bakery operations across Verona and Vicenza favor powder colorants for dough integration efficiency in high-throughput bread and biscuit manufacturing. ECHA compliance requirements for pigment intermediates reshape procurement relationships toward direct supplier contracts. The region's food technologist shortage constrains formulation expertise for plant chemistry and thermal processing integration.
Sicily
Citrus processing waste from orange cultivation in the Catania and Syracuse provinces offers untapped carotenoid extraction potential for circular economy positioning. EU 2018/848 organic certification standards govern extract provenance documentation for premium product lines. The island's agricultural cooperatives remain underintegrated into northern Italy's colorant manufacturing supply chain.
Italy Food Colorants Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and agricultural sourcing relationships, producing a tiered structure where multinational chemical conglomerates share terrain with Italian botanical specialists. The vendor base segments into fermentation technology leaders, Mediterranean plant extract specialists, and diversified ingredient distributors. Three archetypes dominate: integrated extract producers with captive agricultural supply, formulation technology licensors, and distribution intermediaries consolidating regional procurement. Capacity expansion in domestic spirulina cultivation and strategic partnerships between colorant specialists and agricultural cooperatives represent the primary competitive vectors.
Among Netherlands-based ingredient conglomerates, Koninklijke DSM N.V. and GNT International B.V. occupy positions emphasizing fermentation and plant-derived technologies respectively. Sensient Technologies, identifiable by its geographic naming, anchors the premium formulation tier through Milan-based technical operations. German chemical major BASF SE exemplifies the diversified industrial supplier archetype with petrochemical synthesis heritage. Within the Italian specialist tier, AromataGroup SRL and Chr. Hansen Holdings represent contrasting approaches—Mediterranean botanical sourcing integration versus microbial pigment systems for dairy applications. Barentz International B.V., Dohler Group SE, and Nactarome S.p.A. populate the distribution and formulation intermediary segment, with the latter's Italian corporate designation indicating regional market embedding.
| Leading Market Players |
|---|
| Sensient Technologies |
| AromataGroup SRL |
| BASF SE |
| Koninklijke DSM N.V. |
| Barentz International B.V. |
| Chr. Hansen Holdings |
| Dohler Group SE |
| Nactarome S.p.A. |
| GNT International B.V. |
| Others |
Supply & Pricing Matrix
Fermentation-based pigment production is compressing cost economics for natural reds while concentrating supply leverage among biotech-equipped manufacturers. This technology shift simultaneously elevates working capital requirements for microbial cultivation infrastructure and rewards scale players with defensible input cost positions against botanical extract volatility.
Pricing Analysis
Service unbundling separates technical formulation support from base pigment supply, with compounders charging separately for stability testing and application-specific customization. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from EFSA-driven reformulation cycles accelerating R&D amortization timelines. Private-label confectionery manufacturers exhibit highest price sensitivity, while organic-certified beverage producers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
EU 2018/848 organic certification and EFSA additive authorization function as procurement gating mechanisms, filtering supplier participation. Raw material sourcing concentrates in Italy for spirulina and beetroot, India for turmeric oleoresin, and China for synthetic pigment intermediates. Critical dependencies include Mediterranean agricultural land for botanical cultivation, fermentation feedstocks for microbial pigments, and petrochemical precursors for azo dyes. Single-source vulnerability runs through Trentino-Alto Adige spirulina cooperatives during seasonal yield contractions. Distribution runs through formulation specialists serving Emilia-Romagna's industrial corridor, with direct contracting displacing traditional distributor layers in organic-certified channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy food colorants market sits in a technology-transition phase where fermentation-derived microbial pigments displace legacy synthetic and botanical extraction methods. This substitution wave rewards biotech capability investments while penalizing pure-play botanical extractors lacking microbial platforms.
For Market Incumbents: Deepen backward integration into captive spirulina cultivation across Trentino-Alto Adige to secure supply continuity against Mediterranean climate volatility. Accelerate Milan-based technical center expansion for microencapsulation formulation services, creating switching costs as compounders absorb stability-testing responsibilities previously held by end-manufacturers. This dual move defends margin position against emerging fermentation specialists and botanical distributors lacking technical service depth.
For New Entrants and Emerging Players: Begin with Sicilian citrus peel valorization partnerships, extracting carotenoids from Catania and Syracuse orange processing waste for circular economy positioning. Target pasta sauce manufacturers in Parma and Modena with chlorophyll-copper alternatives ahead of pending EFSA restrictions. A direct-to-processor go-to-market model bypasses established distributor layers and captures clean-label specification premiums.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation technology specialists given EFSA's synthetic additive purity tightening and dairy sector adoption acceleration. Long-term viability across a 5-10 year window favors microbial pigment platforms over botanical extraction capacity. The acquisition target archetype combines biotech fermentation assets with established Italian dairy customer relationships. Watch EFSA's pending titanium dioxide ruling as the inflection indicator forcing immediate formulation pivots across ready-meal and confectionery sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spirulina Cultivation | Trentino-Alto Adige growers secure supply continuity against Mediterranean yield volatility. |
| Microencapsulation Technology Licensing | Milan-based labs enable pH-stable turmeric dispersion for functional beverage applications. |
| Direct Procurement with Agricultural Cooperatives | Beverage producers in Trentino-Alto Adige capture traceability premiums for organic certification. |
| Fermentation Capacity Expansion | Lombardy dairy applications adopt microbial carotenoids for aged cheese color stability. |
| Circular Economy Feedstock Partnerships | Sicilian citrus processors valorize orange peel waste for carotenoid extraction supply. |
Research Methodology
Independent corroboration across food technology executives, procurement leads at Emilia-Romagna packaged goods manufacturers, R&D directors at Milan-based formulation labs, and regional agricultural cooperative managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EFSA additive authorization databases, Italian Ministry of Health surveillance protocols, EU 2018/848 organic certification records, and customs trade data for pigment intermediate imports. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Rate-of-change decomposition across natural versus synthetic pigment demand trajectories, fermentation versus extraction production economics, and powder versus liquid format adoption curves structured the analytical framework. Segmentation dimensions modeled include colorant source type, application category, physical form, and end-user scale tier. CAGRs derived from regression analysis against historical EFSA regulatory impact timelines and Italian food manufacturing output correlations. Forecast inputs incorporated ECHA REACH compliance cost burdens and spirulina cultivation yield volatility patterns.
Pending EFSA opinions on titanium dioxide alternatives, copper chlorophyllin restrictions, and Mediterranean climate anomaly frequency are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory timelines and agricultural yield stability. A model refresh is warranted upon material change in EFSA additive authorization schedules or structural shift in northern Italian food manufacturing investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
All-Natural Flavors System Market