
 Crackers Market | 2026-2036
Crackers Market Size, Share, and Industry Trends Forecast 2026-2036
Crackers Market Intelligence
Subscription box models for curated snack assortments is consolidating consumer purchasing habits away from single-purchase decisions. This shift favors large-scale manufacturers with diverse portfolios that can fulfill varied subscription boxes. Mondelez International leverages its extensive brand portfolio to capture a wide range of consumer preferences. Meanwhile, Britannia Industries Limited specializes in the South Asian market with tailored flavor profiles, and the Kellogg Company extends its breakfast-cereal brand recognition into the cracker category.
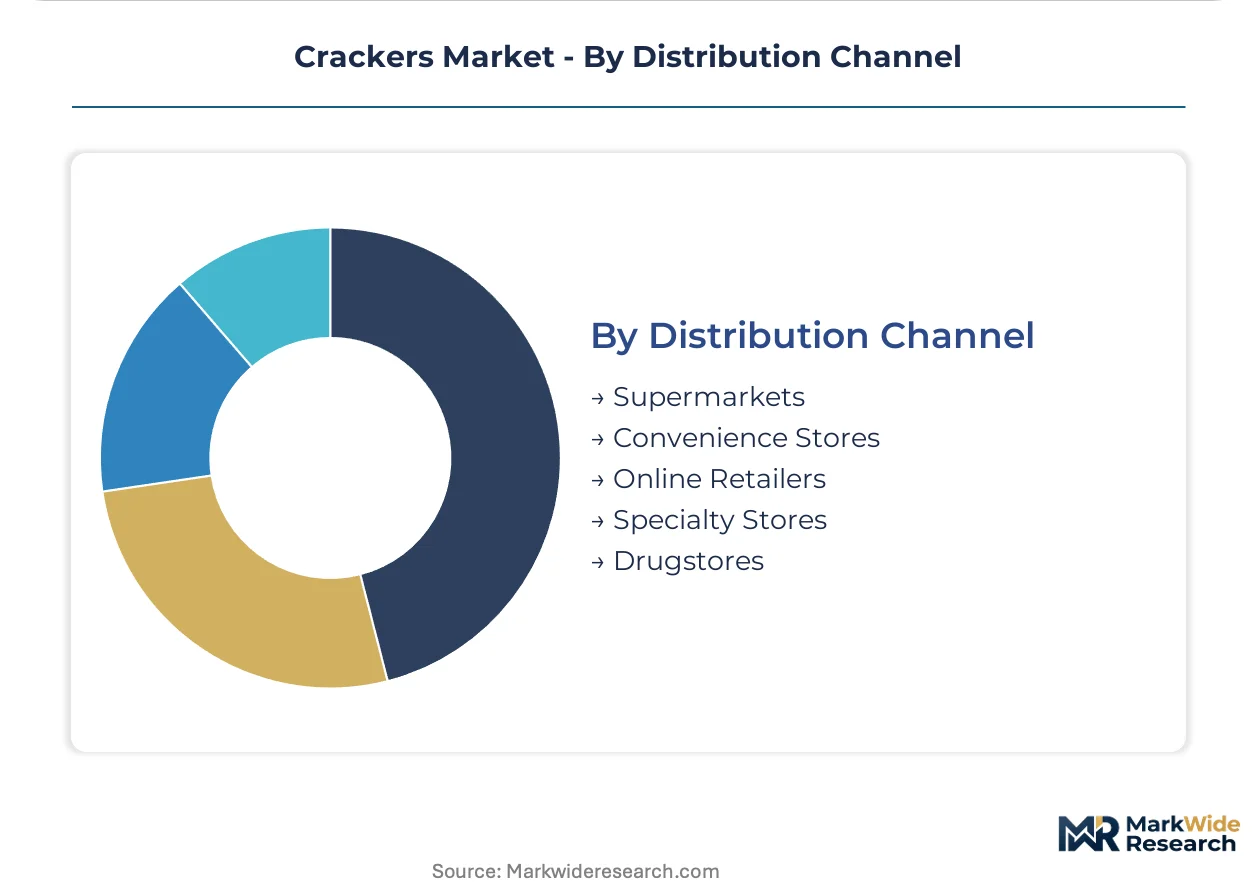
Crackers are flat, dry baked goods typically made from flour, fat, and salt, often leavened with baking soda. The production process involves sheeting and baking at high temperatures to achieve a characteristic crisp texture and low moisture content. These products serve primarily as a snack food or a base for toppings. Within product types, gluten-free and multigrain crackers are expanding market share, while supermarkets remain the dominant distribution channel, closely followed by convenience stores.
Food safety and labeling regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) dictate permissible ingredients, allergen declarations, and health claims. In India, the FSSAI's standards for packaged foods govern market entry and packaging information, influencing product formulation across the subcontinent. Navigating regional variations in consumer taste and evolving dietary guidelines remains the central challenge for manufacturers seeking to expand their footprint.
Market Dynamics
The central force shaping the crackers market is the dual demand for convenience and wellness. This creates tension between traditional, indulgent cracker formulations and the rising consumer expectation for snacks that offer functional benefits, clean labels, and compatibility with specific dietary lifestyles.
Growth Catalysts
- Automated Packaging Lines:Investment in high-speed, automated packaging systems reduces labor costs and contamination risks, while enabling the production of varied pack sizes, from single-servings to family packs, catering to diverse consumption occasions.
- Demand in India:An expanding middle class and the proliferation of organized retail channels in India are driving significant volume growth, particularly for branded crackers positioned as hygienic and modern snacking alternatives.
- Gluten-Free Flour Innovation:Advances in the processing of alternative flours, such as those from almonds, chickpeas, and rice, allow manufacturers to replicate the desirable texture of traditional crackers, opening the market to consumers with celiac disease or gluten sensitivities.
Market Restraints
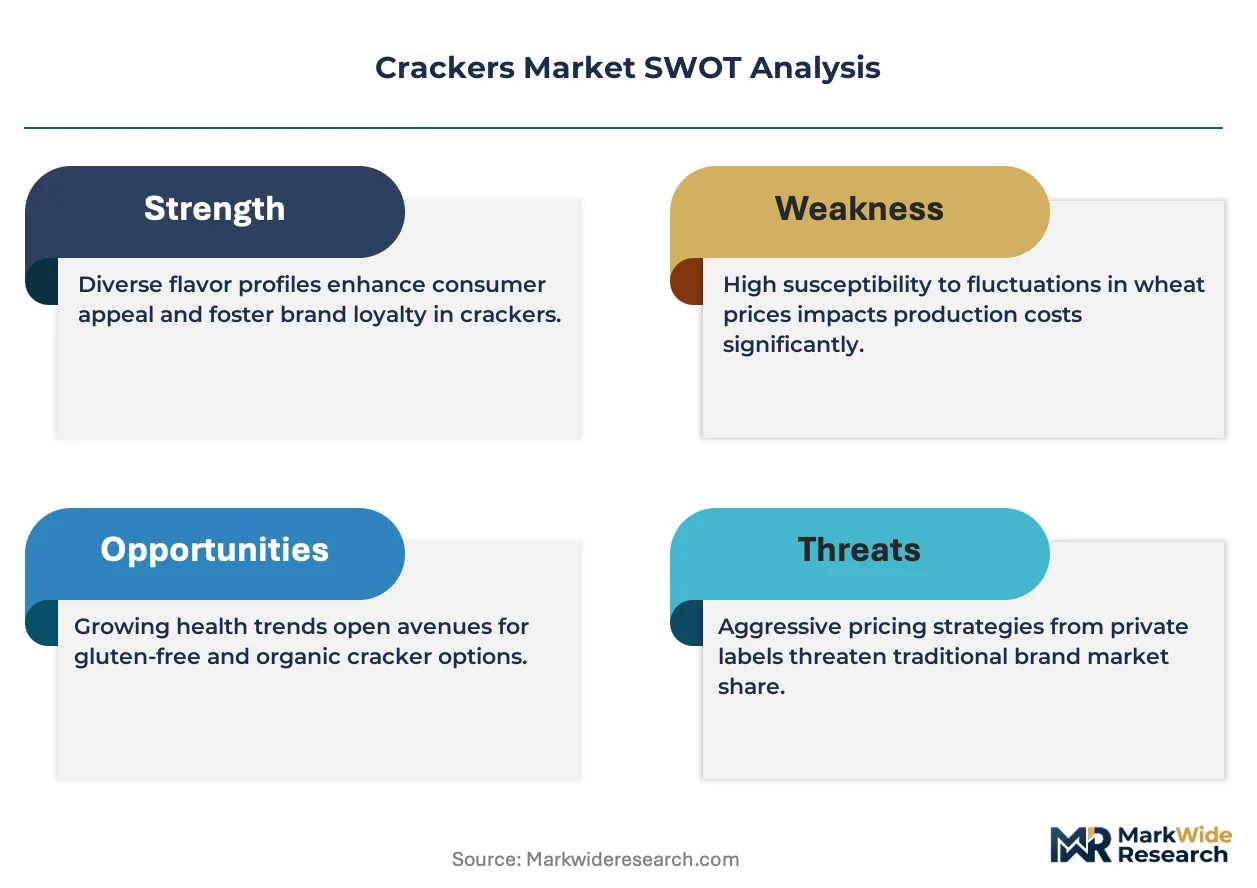
- Input Price Volatility:Fluctuation in the global prices of key agricultural commodities, including wheat, specialty grains, and edible oils, directly impacts production costs and compresses manufacturer margins, especially in the value segment.
- Substitution from Snack Bars:The cracker category faces intense competition from other convenient snacks, such as protein bars, fruit and nut bars, and vegetable crisps, which often market themselves more aggressively on health and functional benefits.
- Complex Health Claim Regulations:Navigating disparate regulations for health and nutrition claims between jurisdictions, such as the U.S. FDA and the European Food Safety Authority (EFSA), creates significant compliance burdens and marketing challenges.
Strategic Opportunities
- Functional Ingredient Fortification:Incorporating functional ingredients like probiotics, prebiotics, fiber, and plant-based proteins into cracker formulations presents an opportunity to create premium, value-added products that appeal to health-conscious consumers.
- Direct-to-Consumer Subscription Models:Developing curated subscription box services allows brands to build direct relationships with consumers, gather valuable preference data, and bypass crowded retail shelves, fostering brand loyalty.
- Expansion in Southeast Asia:Markets in Southeast Asia with rising disposable incomes and developing organized retail sectors represent a significant growth opportunity for both mass-market and premium cracker products tailored to local tastes.
Industry Challenges
- Alternative Flour Sourcing:Securing a consistent, scalable, and cost-effective supply chain for a wide variety of non-traditional flours poses a significant logistical challenge for manufacturers looking to expand their gluten-free and multigrain portfolios.
- Certification Compliance Costs:The expense and time required to obtain and maintain third-party certifications for claims like organic, non-GMO, and gluten-free across multiple international markets can be prohibitive for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crackers Market |
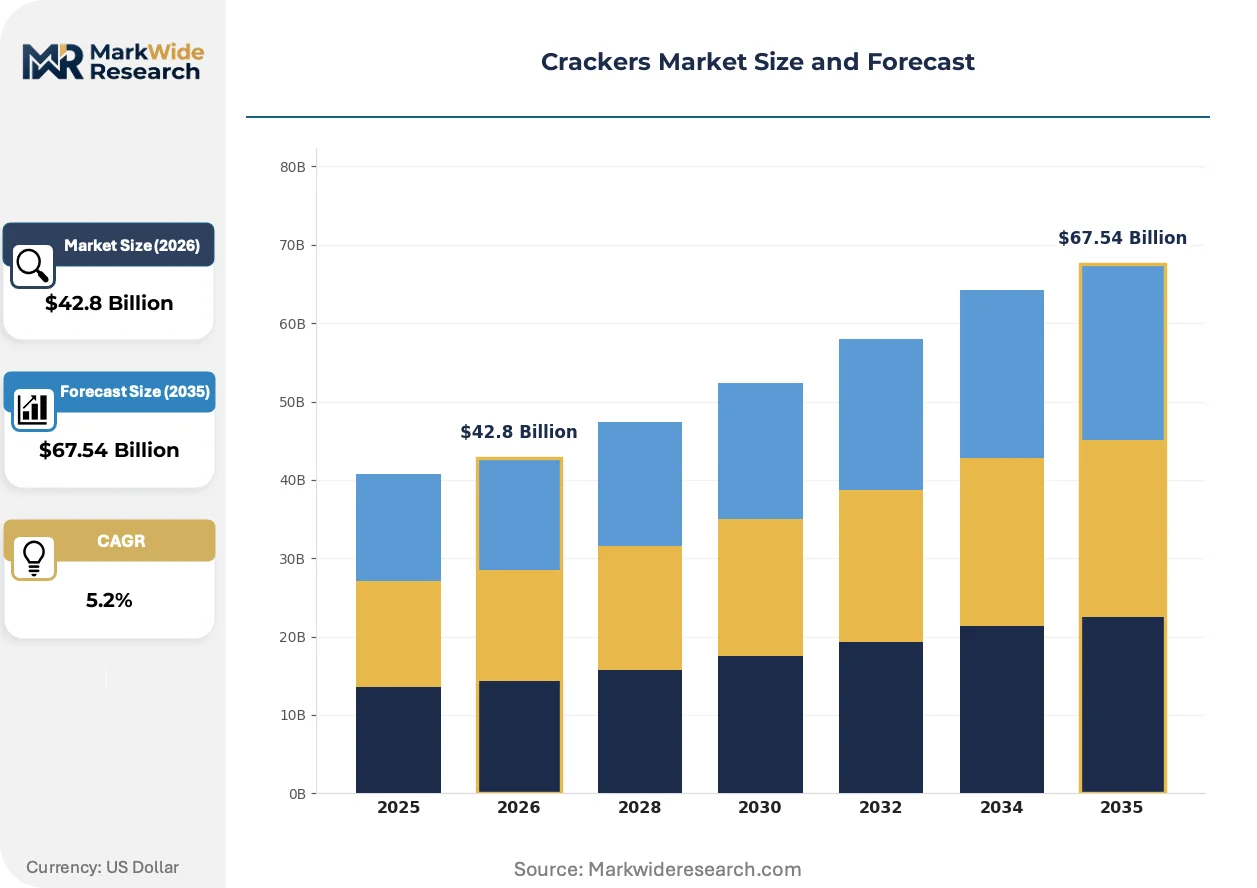
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $67.54 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Savory, Sweet, Multigrain, Gluten-Free, Seeded, Herb-Flavored Consumption Occasion: Snacking, Breakfast, Appetizers, Party, Travel, Office Packaging Format: Box, Pouch, Tray, Bulk, Sleeve, Tin Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Drugstores |
| Companies Covered | Nestlé, Britannia Industries Limited, Mondelez International, General Mills, Parle Products Private Limited, Kellogg Company, Campbell Soup Company, Conagra Brands, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crackers Market Strategic Shifts & Innovations
Product formulation is evolving rapidly to meet new dietary demands, transforming the cracker from a simple carrier for toppings into a standalone, functional snack. This shift is driven by food science advancements and a deeper understanding of consumer wellness priorities.
Technology and Product Evolution
Functional ingredient fortification allows for the inclusion of health-enhancing additives like probiotics, omega-3s, and plant proteins directly into cracker dough. Health-focused consumer segments are actively seeking these products, driving their transition from niche health food stores to mainstream supermarket channels. This development is integrating wellness attributes into a conventional snack category, effectively blurring the lines between treat and nutritional supplement.
Regulatory and Policy Shifts
Front-of-pack labeling (FOPL) systems, such as Europe's Nutri-Score, are gaining traction globally, with similar initiatives under review by the U.S. FDA and India's FSSAI. This regulatory pressure encourages manufacturers to reformulate products by lowering sodium, sugar, and saturated fat to achieve more favorable ratings. Cracker brands targeting families and health-aware shoppers are most affected, as a negative FOPL score can act as a direct purchase deterrent.
Demand-Side and Behavioral Shifts
Consumer purchasing habits are moving towards curated snack discovery through subscription box services. This model often displaces traditional single-item purchases from supermarket shelves, offering consumers variety and convenience. The trend is most visible in urban centers in North America and Europe, where it provides manufacturers with a direct channel to digitally engaged households and a rapid feedback mechanism for new product concepts.
Crackers Market Segmentation
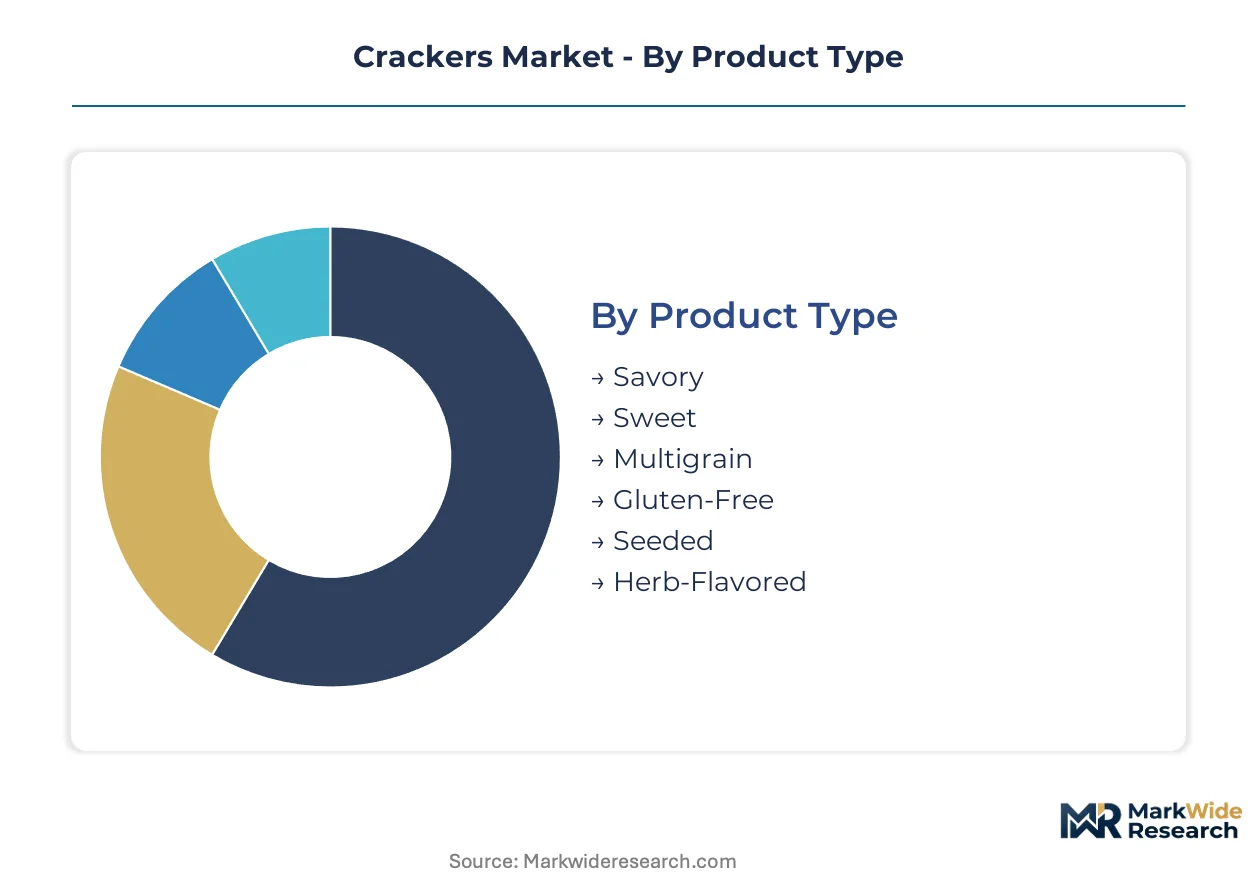
Crackers market segmentation provides a granular view of consumer preferences and operational requirements across different product forms and sales channels. Understanding these distinct segments helps manufacturers tailor product development, optimize supply chains, and deploy targeted marketing strategies to capture specific consumer groups.
Product Type:
Product type segmentation reflects varying capital expenditure requirements, particularly for specialized processing lines and ingredient sourcing.
- Savory:These crackers typically feature herbs, spices, or cheese, serving as versatile bases for toppings or standalone snacks. Demand concentrates in mature markets like the United States and Germany, driven by established consumption habits for appetizers and light meals.
- Sweet:Sweet crackers incorporate sugars, honey, or fruit flavors, often positioned as dessert accompaniments or breakfast items. Urban consumers in Japan and the United Kingdom show a preference for subtly sweet options, integrating them into afternoon tea rituals.
- Multigrain:Formulated with a blend of various whole grains such as oats, rye, and barley, these crackers offer enhanced fiber content and a distinct texture. Health-conscious consumers in Canada and Australia drive demand, seeking snacks with perceived wellness benefits.
- Gluten-Free:These crackers are made from alternative flours like rice, corn, or almond, catering to individuals with celiac disease or gluten sensitivities. The segment is expanding rapidly in European Union countries, supported by increasing diagnostic rates and product availability.
- Seeded:Seeded crackers include ingredients like flax, chia, or sesame seeds, adding nutritional value and a unique texture. Scandinavian markets show strong demand for these nutrient-dense options, aligning with regional health trends.
- Herb-Flavored:Infused with various herbs such as rosemary, thyme, or oregano, these crackers offer distinct aromatic profiles. Mediterranean regions, particularly France and Italy, favor herb-flavored crackers for their culinary versatility.
Most installed capacity flows through Savory. Expansion is steepest in Gluten-Free.
Consumption Occasion:
Consumption occasions delineate cracker utility, from daily routines to specific social events, influencing product development and marketing focus.
- Snacking:Crackers consumed between meals to satisfy hunger or cravings, often in single-serve or convenient formats. Urban professionals in India and the United States frequently choose crackers for on-the-go consumption, valuing convenience and portability.
- Breakfast:Crackers integrated into morning meals, often paired with spreads or cheeses, serving as an alternative to bread. Consumers in the United Kingdom and Australia incorporate crackers into their breakfast routines, seeking quick and easy options.
- Appetizers:Crackers used as a base for various toppings during pre-meal gatherings or light bites. European markets, especially Spain and Italy, show high demand for crackers as part of traditional tapas and antipasti.
- Party:Larger format or variety packs of crackers designed for social gatherings and entertaining. Demand in Germany and Canada is strong for party crackers, where they serve as a staple for hospitality.
- Travel:Portable and individually packaged crackers suitable for consumption during transit or away from home. Air travelers and commuters in China and Brazil increasingly opt for compact cracker packs.
- Office:Crackers kept at workplaces for quick breaks or light lunch alternatives. Corporate environments in the United States and Singapore fuel demand for office-friendly cracker options.
The largest volume of crackers is consumed during Snacking. The Travel segment shows notable growth as convenience gains traction.
Packaging Format:
Packaging format directly impacts unit cost and perceived value, with premium materials often commanding higher margins.
- Box:Rigid cardboard packaging often containing multiple sleeves or trays of crackers, common for family-sized purchases. Supermarkets in the United States and Germany distribute vast volumes of crackers in box formats, catering to household demand.
- Pouch:Flexible film packaging, typically used for single-serve portions or smaller packs, emphasizing portability. Consumers in India and Southeast Asian countries increasingly purchase crackers in pouches for individual snacking.
- Tray:A plastic or paperboard tray holding crackers, often sealed with a film, providing structural integrity and portion control. Deli sections in European supermarkets commonly feature crackers in trays, paired with cheeses.
- Bulk:Large quantities of crackers sold unpackaged or in basic, large containers, primarily for food service or industrial use. Institutional buyers and catering services in the United Kingdom and Australia procure crackers in bulk.
- Sleeve:A paper or plastic wrap directly encasing a stack of crackers, often found within a larger box or as a standalone item. Convenience stores in Japan and South Korea stock crackers in sleeves, targeting individual purchases.
- Tin:Metal containers offering superior protection and a premium aesthetic, often used for specialty or gift crackers. Consumers in France and Italy purchase crackers in tins for their reusability and decorative appeal.
Manufacturers prioritize Box formats for established retail channels. The Pouch format is gaining share due to its portability and portion control.
Distribution Channel:
Distribution channels reflect distinct supply chain configurations, from high-volume retail to niche, curated offerings.
- Supermarkets:Large self-service grocery stores offering a wide range of cracker brands and varieties. These stores in the United States and Germany remain the primary channel for mass-market cracker sales, benefiting from extensive consumer footfall.
- Convenience Stores:Small retail outlets providing quick access to essential goods, often stocking single-serve cracker packs. Urban populations in Japan and South Korea rely on convenience stores for immediate cracker purchases.
- Online Retailers:E-commerce platforms and direct-to-consumer websites facilitating cracker purchases for home delivery. Consumers in the United Kingdom and Australia increasingly use online channels for bulk orders and subscription box services.
- Specialty Stores:Retailers focusing on gourmet, organic, or niche food products, often featuring premium cracker brands. Health food stores in Canada and Sweden cater to consumers seeking artisanal or dietary-specific crackers.
- Drugstores:Pharmacies or health and beauty stores that also carry a selection of packaged snacks, including crackers. Drugstores in the United States and Mexico offer a limited range of crackers, primarily for impulse purchases.
The majority of cracker sales occur through Supermarkets. Online Retailers are experiencing accelerated penetration driven by convenience and curated options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production for crackers increasingly shifts towards regions offering lower operational costs and streamlined regulatory pathways. Manufacturers often navigate a cost-of-compliance gap, leading to strategic investments in new facilities. This arbitrage influences ingredient sourcing and packaging decisions across diverse markets.
India
An expanding middle class and the proliferation of organized retail channels drive significant volume growth for crackers. FSSAI's standards for packaged foods influence product formulation and labeling requirements across the subcontinent. Major production hubs in Maharashtra and Gujarat are expanding capacity for branded, hygienic snacking alternatives.
United States
Consumer demand for convenient, on-the-go snacking options fuels cracker consumption, especially among urban professionals. The U.S. FDA dictates permissible ingredients and allergen declarations, shaping product development. California's food innovation clusters are a focal point for gluten-free and functional cracker development.
Germany
Established consumption habits for appetizers and light meals sustain demand for savory cracker varieties in Germany. European Food Safety Authority (EFSA) regulations govern health claims and food additives for products sold across the EU. The Rhine-Ruhr region, a major logistics hub, facilitates efficient distribution of packaged crackers.
France
Culinary versatility and a preference for distinct aromatic profiles support the market for herb-flavored crackers. French food safety agency ANSM ensures compliance with ingredient and labeling standards for specialty food items. The Rhône-Alpes region, known for its gourmet food industry, sees innovation in premium cracker formulations.
Japan
Urban consumers show a clear preference for subtly sweet cracker options, often integrated into afternoon tea rituals. Japan's Ministry of Health, Labour and Welfare (MHLW) oversees food additive regulations and nutritional labeling. Tokyo's dense retail network supports high demand for individually packaged, convenient cracker formats.
Crackers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry and expansion strategies. The crackers market operates with a tiered structure, where large, diversified food companies compete with agile, niche producers. These archetypes often focus on either volume-driven mass markets or premium, health-oriented categories. Portfolio diversification and strategic acquisitions are common competitive moves observed across the industry.
Global food conglomerates with extensive brand portfolios, such as Mondelez International and the Kellogg Company, anchor the mass-market segment. These companies leverage established distribution networks and brand recognition to capture a wide range of consumer preferences across multiple geographies. Meanwhile, Britannia Industries Limited exemplifies a regional specialist, focusing its strategy on tailoring flavor profiles for the South Asian market. This differentiation allows for deep penetration into specific cultural consumption habits. Such firms often navigate local regulatory frameworks like India's FSSAI with specialized product lines.
| Leading Market Players |
|---|
| Nestlé |
| Britannia Industries Limited |
| Mondelez International |
| General Mills |
| Parle Products Private Limited |
| Kellogg Company |
| Campbell Soup Company |
| Conagra Brands |
| PepsiCo |
Cost & Logistics Intelligence
Supermarket chains' concentrated purchasing power influences the per-unit transactional pricing model for mass-market crackers. This dynamic shapes manufacturer margins and supply chain investments.
Pricing Analysis
Capacity additions in India are reshaping price floors for mass-market cracker varieties. The dominant pricing model remains per-unit transactional for most retail sales, with contract-based long-term offtake agreements common for large supermarket chains. Price differentiation stems from brand premium and specific certifications like gluten-free status. Input price volatility, particularly for wheat and edible oils, exerts downward pressure on manufacturer margins, making value segment consumers highly price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with specialized suppliers of alternative flours, impacting gluten-free cracker production. Geographic supply concentration is notable in India for mass-market products and in Europe's Rhine-Ruhr region for distribution. Raw material dependencies include wheat, edible oils, and specialized grains like almond and chickpea flours. Commodity price volatility presents a structural risk, while distribution primarily runs through supermarkets and convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crackers market functions as a stable compounder, driven by the persistent global demand for convenient snacking options. This ensures consistent volume growth across diverse consumer segments.
For Market Incumbents: Acquire specialized gluten-free flour processing capabilities to mitigate alternative flour sourcing challenges. Consolidate market share through strategic acquisitions of smaller, niche brands with strong functional ingredient portfolios. This diversifies product offerings against the threat of substitution from snack bars. Leverage automated packaging lines to reduce costs and offer varied pack sizes, enhancing channel control.
For New Entrants and Emerging Players: Functional ingredient fortification offers a technology-first wedge into the premium cracker segment. Target health-conscious consumers in urban centers with products incorporating probiotics or plant-based proteins. Develop direct-to-consumer subscription models to bypass crowded retail shelves and build brand loyalty. This approach provides rapid feedback for new product concepts.
For Investors and Strategic Acquirers: Global food conglomerates are the most active acquirers in this space, seeking portfolio diversification. The market offers long-term viability, driven by sustained consumer demand for convenient and wellness-oriented snacks. Target agile, niche producers specializing in gluten-free or functional cracker formulations. Watch for increasing adoption rates of front-of-pack labeling systems as a key inflection indicator for reformulation trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Ingredient Integration | Incorporating probiotics and plant proteins creates value-added products for health-conscious consumers. |
| Automated Packaging Investment | Reduces operational costs and enables diverse pack sizes for various consumption occasions. |
| Southeast Asia Market Entry | Captures new volume growth from rising disposable incomes and developing retail networks. |
| Subscription Model Development | Builds direct consumer relationships and gathers preference data, bypassing traditional retail. |
| Gluten-Free Portfolio Expansion | Addresses specific dietary demands and expands market reach to celiac and sensitive consumers. |
Research Approach
Direct dialogue with R&D directors, procurement leads, and retail category managers formed the primary research foundation. This qualitative input was validated through extensive secondary research, including U.S. FDA guidelines, EFSA reports, and FSSAI standards. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy. Industry association publications also provided critical context.
The quantitative model produced volume and value projections across the analysis window. Segmentation dimensions included product type, consumption occasion, packaging format, and distribution channel, alongside regional market maturity. Compound annual growth rates were derived from historical trends and projected growth drivers. Ingredient price forecasts and regulatory compliance costs served as key industry-specific inputs.
The model holds under current macroeconomic conditions and established regulatory frameworks; deviation in geopolitical events or unforeseen raw material supply disruptions would shift the forecast. Forecasts reflect these underlying assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Popcorn Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Savoury Biscuits Market
Snacks
India Energy Bar Market
Snacks
Crispy Fruit Chips Market
Snacks
UK Snack Market
Snacks
Organic Chips Market
Snacks
Nachos Market
Snacks
Global Tortilla Chips Market
Snacks
Indonesia Snack Bar Market
Snacks
Baked Chips Market
Snacks
Poland Snack Bar Market
Snacks
Germany Snack Bar Market
Snacks
Baked Savoury Snacks Market