
 Marine Grease Market | 2026-2036
Marine Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Grease Market Intelligence
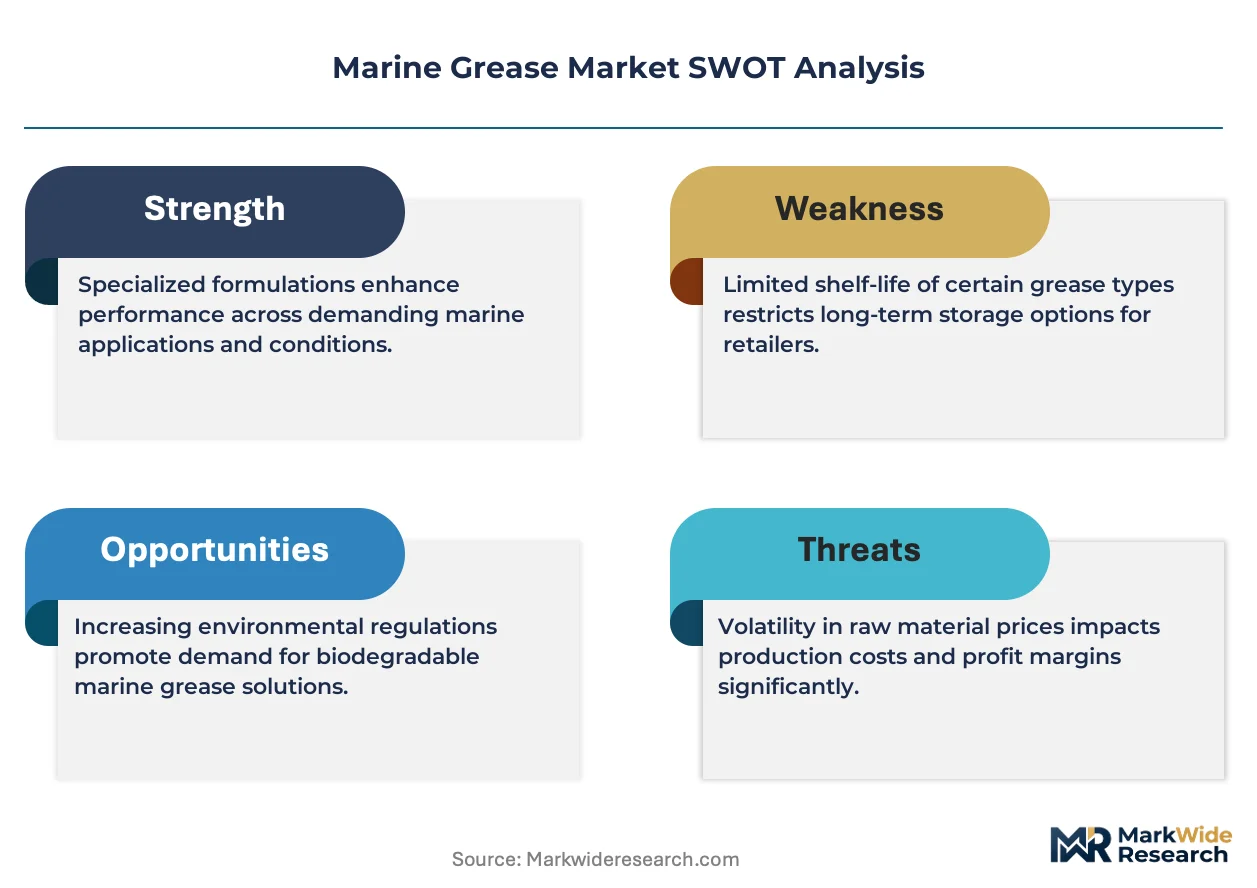
Divergent investment in synthetic base oil R&D and global supply chain infrastructure is bifurcating the competitive landscape. Integrated majors like Shell plc leverage vast distribution networks and brand recognition to serve large fleet operators. Exxon Mobil Corporation differentiates through advanced formulations for extreme temperature and pressure applications. In contrast, specialists such as Lukoil Marine Lubricants DMCC compete by offering tailored solutions for specific regional markets and vessel types.
Marine grease is a semi-solid lubricant formulated from a base oil, a thickening agent like lithium or calcium soap, and performance-enhancing additives. Its primary purpose is to provide long-lasting protection against friction, wear, and corrosion for mechanical components exposed to saltwater, humidity, and heavy loads. Complex grease products, particularly those with superior water resistance and thermal stability, command a price premium. Within applications, the offshore platforms segment requires specialized greases capable of performing under extreme environmental conditions, driving formulation innovation.
Regulations including the U.S. EPA's Vessel General Permit and the European Union's REACH framework mandate the use of environmentally acceptable lubricants in certain applications. These rules, alongside ISO standards for lubricant performance, directly influence product formulation and market access for manufacturers. Successfully navigating the market requires suppliers to balance the development of high-performance, durable greases with evolving environmental compliance and sustainability demands.
Market Dynamics
The mandatory transition toward Environmentally Acceptable Lubricants (EALs), driven by stringent international maritime regulations, is the central force reshaping product formulation, performance benchmarks, and supply chain logistics across the marine grease market.
Growth Catalysts
- Regulatory Mandates:The U.S. EPA's Vessel General Permit and similar frameworks compel operators to adopt EALs, directly stimulating demand for compliant, biodegradable grease formulations for use in equipment with oil-to-sea interfaces.
- Offshore Sector Expansion:Growth in offshore oil, gas, and wind energy projects requires specialized greases that perform under extreme pressure and temperature, boosting the high-performance segment for platforms and support vessels.
- Maritime Hub Activity:Increased shipping volumes through major Asian transshipment ports like Singapore and Busan necessitate greater consumption of greases for routine vessel maintenance, supporting baseline market volume.
Market Restraints
- Base Oil Price Volatility:Fluctuations in the cost of synthetic and mineral base oils, key raw materials, create margin pressure for manufacturers and introduce pricing uncertainty for fleet procurement managers.
- EAL Performance Trade-offs:Certain biodegradable greases exhibit performance limitations in shear stability or load-carrying capacity compared to conventional mineral oil-based products, slowing adoption among some cost-sensitive operators.
- Alternative Lubrication Systems:The adoption of centralized, automated lubrication systems on newer, advanced vessels can reduce the overall volume of manually applied grease required, posing a long-term substitution threat.
Strategic Opportunities
- Offshore Wind Turbine Maintenance:The burgeoning offshore wind energy sector requires long-lasting, corrosion-resistant greases for turbine bearings, pitch systems, and yaw gears, creating a new, high-value application segment.
- Bio-based Material Innovation:Research into novel bio-based thickeners and base oils offers a pathway to develop next-generation EALs with superior performance and sustainability credentials, which can command premium pricing.
- South American Port Development:Expanding port infrastructure in countries like Brazil and Colombia presents an underpenetrated market for specialized marine grease suppliers to establish new distribution and service networks.
Industry Challenges
- Complex Certification Pathways:Navigating the separate and evolving compliance requirements of the EPA's VGP and the EU Ecolabel for lubricants creates significant testing and documentation burdens for manufacturers seeking market access.
- Global Logistics Inefficiencies:Ensuring consistent and timely supply of specialized greases to remote ports or offshore platforms remains a significant logistical challenge, increasing operational costs for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Grease Market |
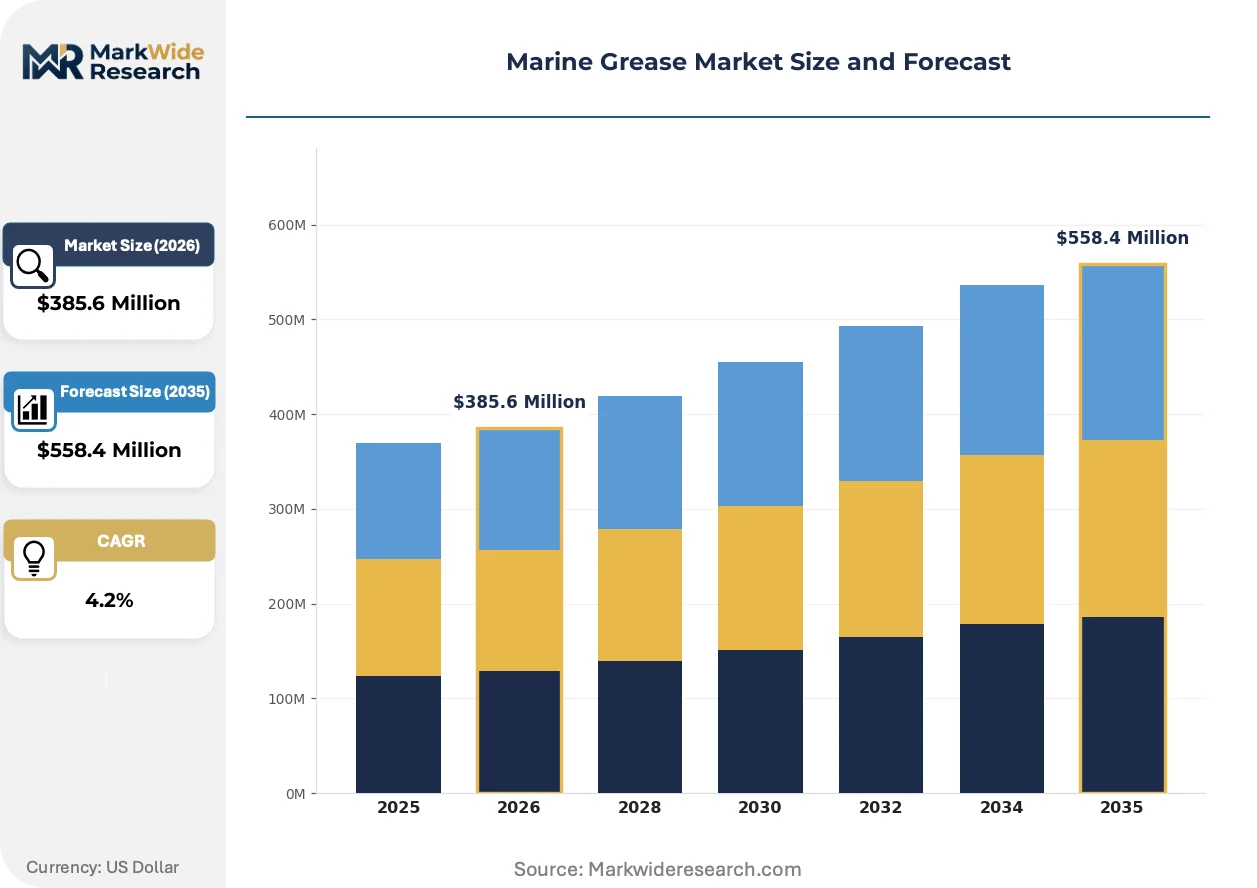
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Grease, Calcium Grease, Complex Grease, Others Application: Boat Maintenance, Shipbuilding, Offshore Platforms, Marine Equipment End User: Commercial Shipping, Recreational Boating, Fisheries, Navy Service Type: Lubrication Services, Maintenance Services, Technical Support, Inspection Services |
| Companies Covered | BP p.l.c., Chevron Corporation, TotalEnergies SE, Shell plc, Exxon Mobil Corporation, ENEOS Corporation, Gulf Oil Marine Ltd, Lukoil Marine Lubricants DMCC, Idemitsu Kosan Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Grease Market Strategic Shifts & Innovations
Formulation science is advancing toward lubricants that reconcile extreme performance demands with stringent environmental regulations. This convergence drives innovation in base oils, thickeners, and additive packages, defining the next generation of marine grease products for the maritime industry.
Advanced complex soap thickeners, such as lithium complex and calcium sulfonate complex, provide superior water resistance, mechanical stability, and high-temperature performance. Vessel operators in demanding segments like LNG carriers and offshore support vessels are adopting these formulations for critical equipment. This technology is displacing traditional simple soap greases in applications where reliability and extended service intervals are paramount.
Regulatory frameworks like the European Union's REACH legislation impose strict evaluation and authorization requirements on chemical substances used in lubricants. This forces manufacturers to conduct extensive toxicological and environmental impact assessments for their grease formulations and additives. As a result, product portfolios are being rationalized, with non-compliant chemical components being phased out, particularly affecting suppliers to European ports.
Fleet operators are shifting from fixed-interval maintenance schedules toward condition-based monitoring for lubrication decisions. This data-driven approach, which utilizes onboard sensors and regular grease analysis, disrupts the traditional model of selling lubricants purely by volume. The trend is most prominent among large container lines and cruise ship operators seeking to optimize operational efficiency and reduce lubricant waste.
Marine Grease Market Segmentation
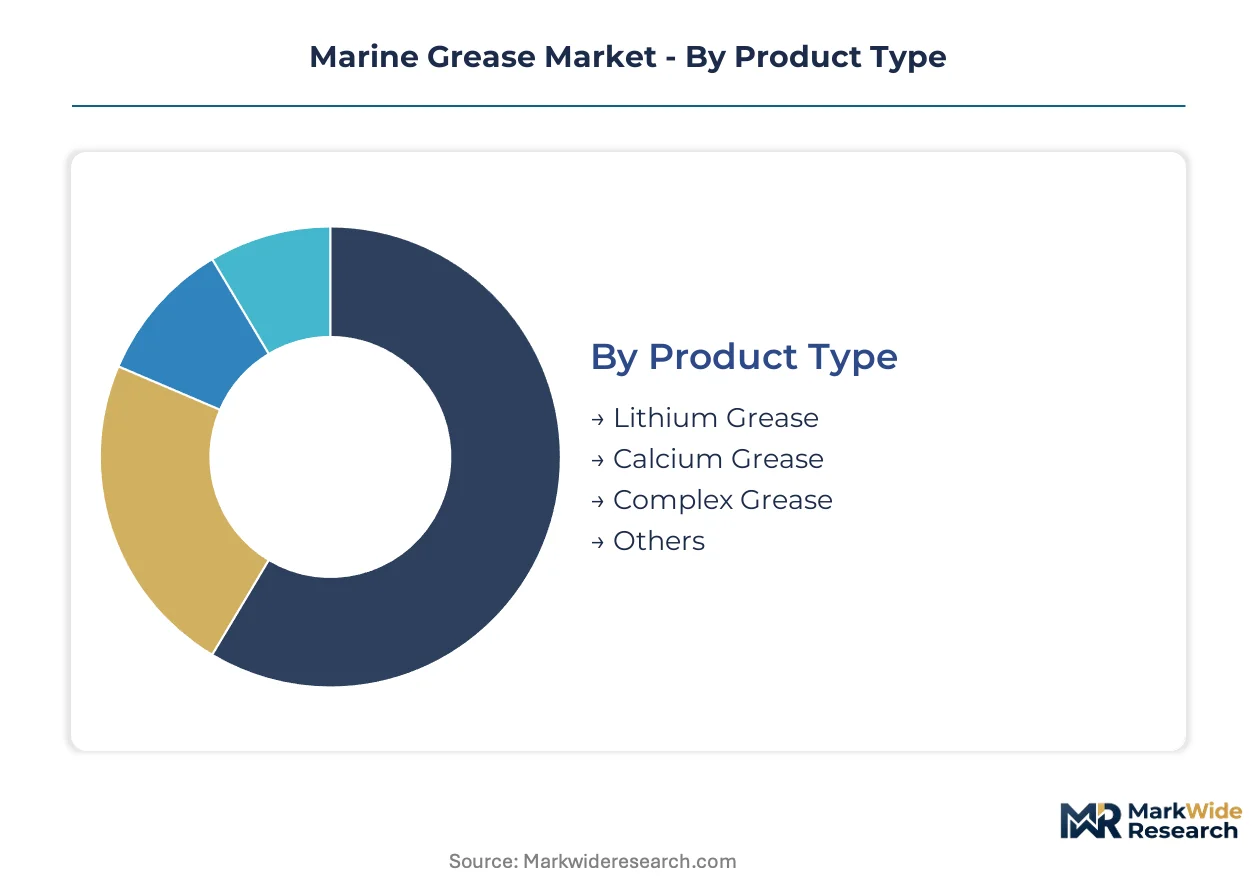
The marine grease market's segmentation reveals distinct demand patterns and value propositions across various product formulations, applications, and end-user requirements. Understanding these divisions is crucial for manufacturers to tailor product development, distribution strategies, and pricing models effectively.
Product Type:
Margin pools within marine grease product types concentrate on specialized formulations for demanding conditions and regulatory compliance.
- Complex Grease:These formulations, often based on lithium complex or calcium sulfonate complex, provide superior water resistance, mechanical stability, and high-temperature performance for critical marine equipment. Demand for complex greases is particularly strong from LNG carriers and offshore support vessels operating in extreme environments.
- Lithium Grease:Formulated with lithium soap thickeners, this type offers good general-purpose lubrication and corrosion protection, making it a widely adopted solution for various vessel components. Its cost-effectiveness and broad utility drive consistent demand across commercial shipping and recreational boating segments.
- Calcium Grease:Known for its excellent water resistance, calcium grease is suitable for applications where exposure to moisture is a primary concern.
- Others:This category includes specialized greases like aluminum complex and polyurea-based formulations, catering to niche applications with unique performance requirements.
The dominant share belongs to Complex Grease, while Lithium Grease is closing the gap fastest.
Application:
Volume concentration across marine grease applications is heavily influenced by routine maintenance needs and extreme operational environments.
- Offshore Platforms:This segment requires specialized greases capable of performing under extreme pressure, temperature, and corrosive saltwater conditions for drilling equipment and structural components. Innovation in advanced formulations for offshore wind energy turbines also drives demand.
- Boat Maintenance:This broad application encompasses routine lubrication for propellers, steering mechanisms, and winches on diverse vessels, from small recreational boats to large commercial ships. High volume consumption for general-purpose and water-resistant greases characterizes this segment.
- Shipbuilding:New vessel construction utilizes marine greases for initial assembly and commissioning of various mechanical systems before deployment.
- Marine Equipment:This category covers specific components such as stern tubes, rudder stocks, and deck machinery, each requiring tailored lubrication solutions.
Offshore platforms drive innovation in high-performance formulations, contrasting with the consistent volume demand from boat maintenance.
End User:
Customer type differentiation shapes the formulation requirements and distribution channels for marine grease products.
- Commercial Shipping:This segment represents the largest consumer of marine grease, encompassing container ships, tankers, bulk carriers, and cruise liners, demanding high-performance lubricants for continuous operation. Stringent regulations like the U.S. EPA's Vessel General Permit influence product selection for commercial fleets.
- Navy:Naval vessels require highly specialized and often military-grade greases for critical systems, emphasizing reliability, stealth, and performance under extreme operational stress. Procurement decisions are often guided by national defense standards and specifications.
- Recreational Boating:This segment includes yachts, sailboats, and personal watercraft, typically requiring smaller volumes of readily available, easy-to-apply greases.
- Fisheries:Fishing vessels utilize marine greases for winches, nets, and engine components, prioritizing durability and resistance to harsh marine conditions.
Commercial shipping represents the largest demand segment, though specific operational needs from naval fleets influence premium product development.
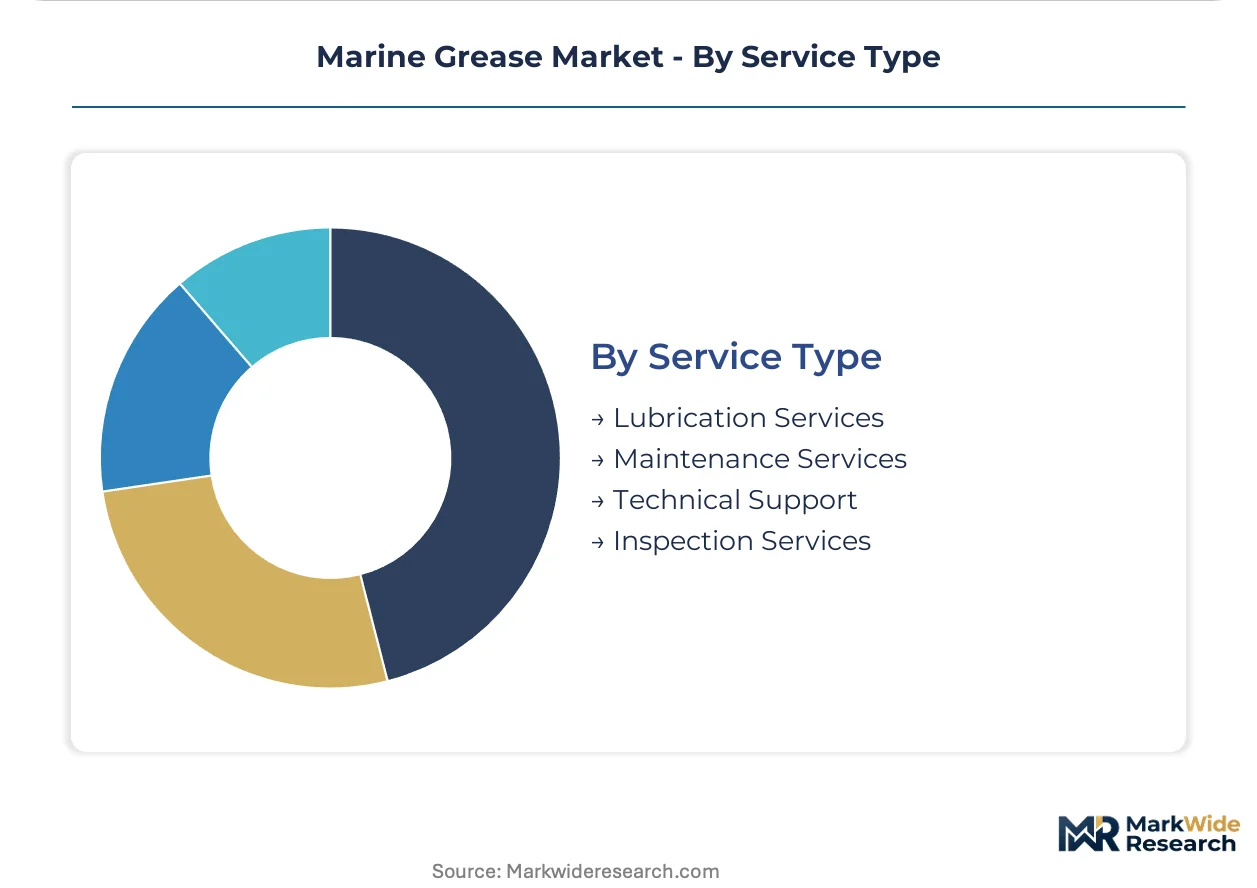
Service Type:
The maturity of offerings in marine grease services ranges from foundational lubrication support to advanced diagnostic capabilities.
- Lubrication Services:These services involve the direct application and replenishment of marine greases, ensuring proper functioning and longevity of mechanical components. They are a fundamental offering, often integrated with broader maintenance contracts.
- Maintenance Services:Beyond simple lubrication, these services include comprehensive equipment checks, preventative maintenance, and repair, where marine greases are a critical consumable. These offerings aim to minimize downtime and extend asset life.
- Technical Support:Manufacturers provide expert advice on grease selection, application techniques, and troubleshooting specific lubrication challenges.
- Inspection Services:These services involve regular assessments of equipment and lubricant condition, often using predictive analytics to optimize grease intervals and prevent failures.
Lubrication services form the essential base, while technical support offerings enhance long-term operational efficiency for fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global marine grease demand reflects the intricate balance of international trade flows and port activity. Countries with significant maritime export and import volumes drive consistent consumption for vessel maintenance and port operations. The strategic locations of major shipping lanes and transshipment hubs heavily influence regional market dynamics.
Singapore
Demand for marine grease in Singapore is driven by its status as a global transshipment hub and major bunkering port. The Maritime and Port Authority of Singapore enforces strict operational standards, influencing lubricant selection. Port of Singapore operations, including extensive vessel maintenance and repair activities, sustain high consumption volumes.
South Korea
South Korea's robust shipbuilding industry and significant commercial shipping activities underpin marine grease consumption. The Ministry of Oceans and Fisheries regulations guide lubricant standards for domestic and international vessels. Busan, a primary port city, sees substantial demand for specialized greases in ship repair yards and container terminals.
United States
United States marine grease requirements stem from its vast coastline, active commercial shipping, and offshore energy sector. The U.S. EPA's Vessel General Permit mandates Environmentally Acceptable Lubricants for oil-to-sea interfaces, shaping product formulation. Major ports like Houston and Los Angeles require substantial volumes for diverse fleet operations.
Germany
Germany's strong industrial base and active North Sea shipping routes contribute significantly to marine grease demand. European Union's REACH framework influences the chemical composition and environmental standards for lubricants sold within the country. Hamburg, a prominent port city, serves as a key distribution point for marine greases across Northern Europe.
Brazil
Brazil's expanding offshore oil and gas exploration, alongside its growing agricultural exports, fuels marine grease consumption. The country's national environmental agency, IBAMA, sets guidelines for lubricants used in coastal and offshore operations. Port complexes like Santos and Rio de Janeiro are experiencing increased demand for high-performance formulations.
Marine Grease Market Key Industry Players
Concentration sits with integrated energy majors leveraging extensive distribution networks and brand recognition for large fleet operators. The marine grease market also features specialized lubricant manufacturers focusing on niche applications and regional expertise. Competitive dynamics involve strategic partnerships for product innovation and geographic expansion into underserved maritime regions. Companies pursue portfolio diversification to meet evolving environmental compliance standards and capture demand for high-performance formulations.
Integrated energy companies like Shell plc and Exxon Mobil Corporation exemplify the archetype of global suppliers, offering comprehensive product lines and vast logistical capabilities to major commercial shipping lines. These entities often anchor the premium segment with advanced formulations for diverse operational requirements. Lukoil Marine Lubricants DMCC, a specialist, occupies a position focused on tailored solutions for specific vessel types and regional maritime markets. This company represents the segment of providers offering customized approaches to lubrication challenges.
| Leading Market Players |
|---|
| BP p.l.c. |
| Chevron Corporation |
| TotalEnergies SE |
| Shell plc |
| Exxon Mobil Corporation |
| ENEOS Corporation |
| Gulf Oil Marine Ltd |
| Lukoil Marine Lubricants DMCC |
| Idemitsu Kosan Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for marine grease provide stability for both manufacturers and large fleet operators, locking in consistent supply access and mitigating raw material price volatility. This structure influences both upstream raw material procurement and downstream product pricing.
Pricing Analysis
Commercial shipping operators anchor contract-based long-term offtake pricing for marine grease. Price differentiation stems from the product's certification level, such as compliance with the U.S. EPA's Vessel General Permit, and bundled technical support services. Margins are tightening due to persistent base oil price volatility. Recreational boating segments exhibit the highest price sensitivity, while naval fleets prioritize performance over cost.
Supply Chain Analysis
Singapore and South Korea anchor critical maritime hub activity and advanced shipbuilding, influencing marine grease supply. The supply chain draws from synthetic base oils, lithium soap thickeners, and specialized performance additives. Global logistics inefficiencies pose a structural risk, particularly for supplying remote ports and offshore platforms. Distribution runs through integrated energy majors with vast networks and specialist manufacturers utilizing tailored regional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine grease market is experiencing a buyer-power shift as large commercial shipping lines consolidate their lubricant procurement. This consolidation increases their leverage over suppliers, demanding more competitive pricing and EAL compliance.
For Market Incumbents: Compound investment in Environmentally Acceptable Lubricant (EAL) research and development to overcome performance trade-offs, particularly in shear stability. Expand distribution networks in growing maritime regions like South America to counter potential market fragmentation. Certification investment for evolving regulations like EU REACH offers a defensive lever against new market entrants. The threat of alternative lubrication systems on advanced vessels requires continuous product innovation.
For New Entrants and Emerging Players: Differentiate on specialized formulations for high-growth, underserved segments such as offshore wind turbine maintenance. The burgeoning offshore wind energy sector presents a penetrable market for long-lasting, corrosion-resistant greases. Bio-based material innovation offers a strong go-to-market angle, providing superior EALs with premium pricing potential. Focus on establishing direct service and distribution networks in developing South American ports.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist lubricant manufacturers possessing advanced Environmentally Acceptable Lubricant formulation capabilities or robust regional distribution networks in key maritime hubs. This market exhibits long-term stability, driven by continuous shipping demand and evolving regulatory frameworks over the next 5-10 years. Increased M&A activity among smaller EAL innovators serves as a key signal to watch for market consolidation. Such targets offer pathways for portfolio diversification and compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| EAL R&D Investment | Drives compliance with environmental regulations and captures demand for high-performance solutions. |
| Geographic Distribution Expansion | Secures supply to growing maritime hubs, enhancing market access for specialized products. |
| Bio-based Material Innovation | Develops next-generation lubricants with superior sustainability credentials, commanding price premiums. |
| Condition-Based Monitoring Integration | Optimizes lubricant usage for fleet operators, reducing waste and extending equipment life. |
| Strategic Partnerships with Shipyards | Ensures early product integration into new vessel construction, securing long-term supply contracts. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry journals, company annual reports, regulatory filings, and maritime trade publications. This involved extensive interviews with lubricant R&D directors, fleet procurement managers, port authorities, and offshore platform maintenance engineers. Data was triangulated using both bottom-up and top-down approaches to ensure robust market sizing. This comprehensive method validated insights across diverse data points.
Product type, application, end-user, service type, and regional maritime activity formed the segmentation dimensions modeled across the analysis window. The analytical framework integrated historical data with future growth projections. Compound Annual Growth Rates were derived from a regression analysis of market drivers and historical performance. Key industry-specific forecast inputs included vessel newbuild orders and Environmentally Acceptable Lubricant adoption rates.
The analysis sits within stated boundaries; outcomes outside unforeseen geopolitical events or rapid technological disruption would require recalibration. Forecasts reflect assumptions regarding global trade fluctuations and environmental regulatory stability. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Graphite Lubricant Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Slideway Oil Market
Lubricants
Gun Lubricant Market
Lubricants
Biolubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
United Kingdom Automotive Lubricants Market