
 Poland Automotive Engine Oils Market | 2026-2036
Poland Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Automotive Engine Oils Market Analytics
The split between premium synthetic formulations and commodity mineral blends is rebalancing as OEM fill specifications tighten and independent workshops face margin compression. PKN ORLEN anchors its position through captive refinery supply and nationwide distribution into both franchised dealers and agricultural cooperatives. LIQUI MOLY differentiates via additive chemistry specialization targeting European OEM approvals. ExxonMobil Corporation extends its reach through integrated supply agreements with heavy-duty fleet operators operating cross-border routes from Poland into Germany and Czechia.
Poland automotive engine oils are lubricating fluids formulated from base oils combined with performance additives to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with synthetic variants typically employing Group III or PAO base stocks meeting SAE J300 viscosity standards. The primary commercial purpose is to protect engine components under thermal and mechanical stress while enabling extended drain intervals that lower fleet operating costs. Synthetic formulations lead value generation as OEMs mandate 0W-20 and 5W-30 grades for new passenger car platforms, while semi-synthetic products occupy the volume-dominant service-fill channel for vehicles outside warranty. Heavy-duty trucks represent the most concentrated margin pool due to bulk procurement contracts and uptime guarantees that favor premium lubricant specifications.
Poland's alignment with EU REACH and RoHS frameworks restricts certain additive chemistries, while the country's national standards body enforces BIS-equivalent conformity assessment for lubricant labeling and performance claims. The EU Green Deal's transport decarbonization trajectory is forcing reformulation investments as stakeholders anticipate tighter limits on lubricant biodegradability and lifecycle carbon intensity. Stakeholders must decide whether to build blending capacity domestically or source finished synthetics from integrated European refiners as specification divergence between ACEA and API sequences accelerates.
Market Dynamics
ACEA sequence tightening and Poland's EU F-Gas alignment are compressing formulation flexibility while extending drain intervals, forcing blenders to recalibrate additive packages for low-viscosity dominance without sacrificing hardware protection.
Growth Catalysts
- ACEA C6 Sequences:The European Automobile Manufacturers Association's tightened specifications for high-temperature high-shear viscosity push OEMs toward 0W-20 and 5W-30 factory fills, creating specification-driven upgrade cycles in passenger car service channels.
- Fleet TCO Programs:Commercial logistics operators operating cross-border routes from Silesia into Germany and Czechia are consolidating lubricant procurement under uptime-guarantee contracts that favor premium synthetic formulations with 100,000-kilometer drain intervals.
- Silesian Manufacturing Corridor:Dense clustering of automotive OEM assembly plants and tier-one component suppliers generates concentrated demand for just-in-time lubricant delivery and technical service support.
Market Restraints
- Group III Base Oil Concentration:European refinery capacity for synthetic-grade base stocks concentrates in Rotterdam and Antwerp hubs, exposing Polish blenders to transport cost volatility and currency-hedging complexity.
- REACH Additive Restrictions:ECHA's evolving candidate list for substances of very high concern threatens zinc dialkyldithiophosphate and certain detergent chemistries, forcing reformulation investments ahead of compliance deadlines.
- Battery Electric Displacement:Warsaw's municipal fleet electrification targets and OEM platform announcements for battery-electric commercial vehicles threaten long-term volume in crankcase lubricants for urban delivery segments.
Strategic Opportunities
- EU Green Deal Transport Decarbonization:Anticipated mandates on lubricant biodegradability and lifecycle carbon intensity create first-mover advantage for blenders investing in re-refined base stocks and renewable feedstocks.
- Independent Workshop Channel:Margin compression among non-franchised repair networks creates white space for private-label synthetic programs with simplified SKU architectures and technical training bundles.
- Agricultural Cooperative Expansion:Poland's farm machinery cooperatives remain underpenetrated by premium lubricant suppliers, presenting volume opportunity through seasonal bulk delivery and harvest-season uptime guarantees.
Industry Challenges
- ACEA-API Specification Divergence:Accelerating misalignment between European and North American sequences forces dual-inventory strategies for blenders serving export-oriented Polish OEM plants.
- Additive Chemistry Talent Scarcity:Specialized formulation expertise for low-viscosity, low-SAPS (sulfated ash, phosphorus, sulfur) packages concentrates among a narrow pool of European technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Automotive Engine Oils Market |
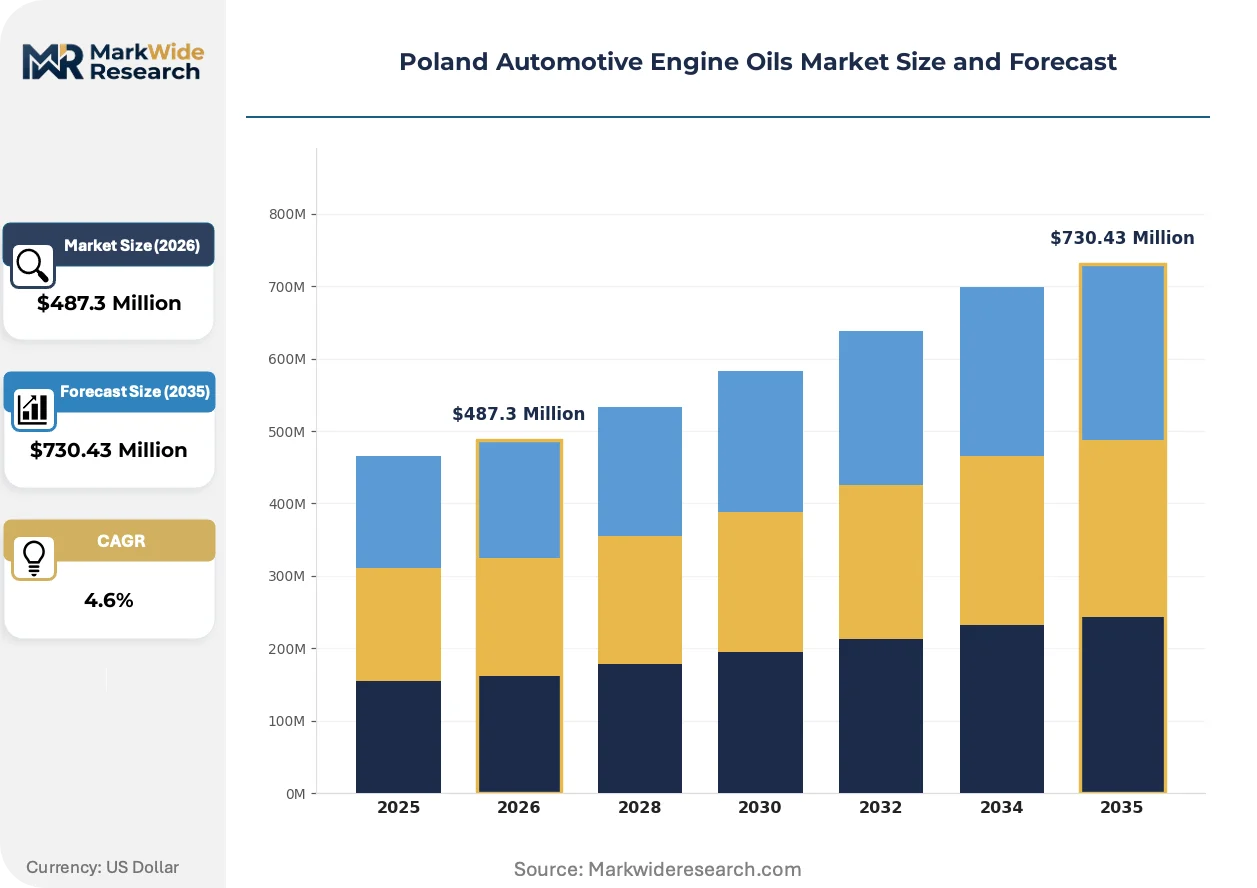
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mineral, Synthetic, Semi-Synthetic, Bio-Based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Application: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Packaging Type: Bottles, Drums, Bulk, Sachets |
| Companies Covered | LOTOS OIL, ExxonMobil Corporation, BP PLC (Castrol), LIQUI MOLY, Shell plc, PKN ORLEN (ORLEN oil), TotalEnergies, Motul, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and procurement logic are diverging simultaneously as hardware protection requirements tighten while fleet buyers consolidate purchasing power around total-cost metrics rather than per-liter pricing.
Polyalphaolefin (PAO) and ester base stocks are converging with advanced friction modifier packages to enable 0W-16 and 0W-20 grades that maintain bearing film strength under turbocharged direct-injection thermal loads. Heavy-duty fleet operators with Poland-Germany-Czechia routes are adopting these formulations fastest, compressing the service-fill window for mineral-based 15W-40 products in long-haul segments.
EU F-Gas Regulation alignment is forcing refrigerant-lubricant compatibility testing for hybrid vehicle air conditioning circuits, adding validation layers to engine oil additive selection. Polish blenders must now certify thermal stability against R-1234yf exposure, with Warsaw-based testing laboratories expanding capacity to serve both domestic formulators and export-bound OEM fill programs.
Fleet procurement departments are consolidating lubricant buying under integrated maintenance contracts that bundle oil analysis, filter supply, and drain-interval optimization. Independent workshops in Poznań and Kraków face disintermediation as direct distributor-fleet relationships bypass traditional jobber networks, compressing aftermarket margin pools and forcing service-channel specialization on diagnostic capabilities lubricant suppliers cannot replicate.
Poland Automotive Engine Oils Market Segmentation
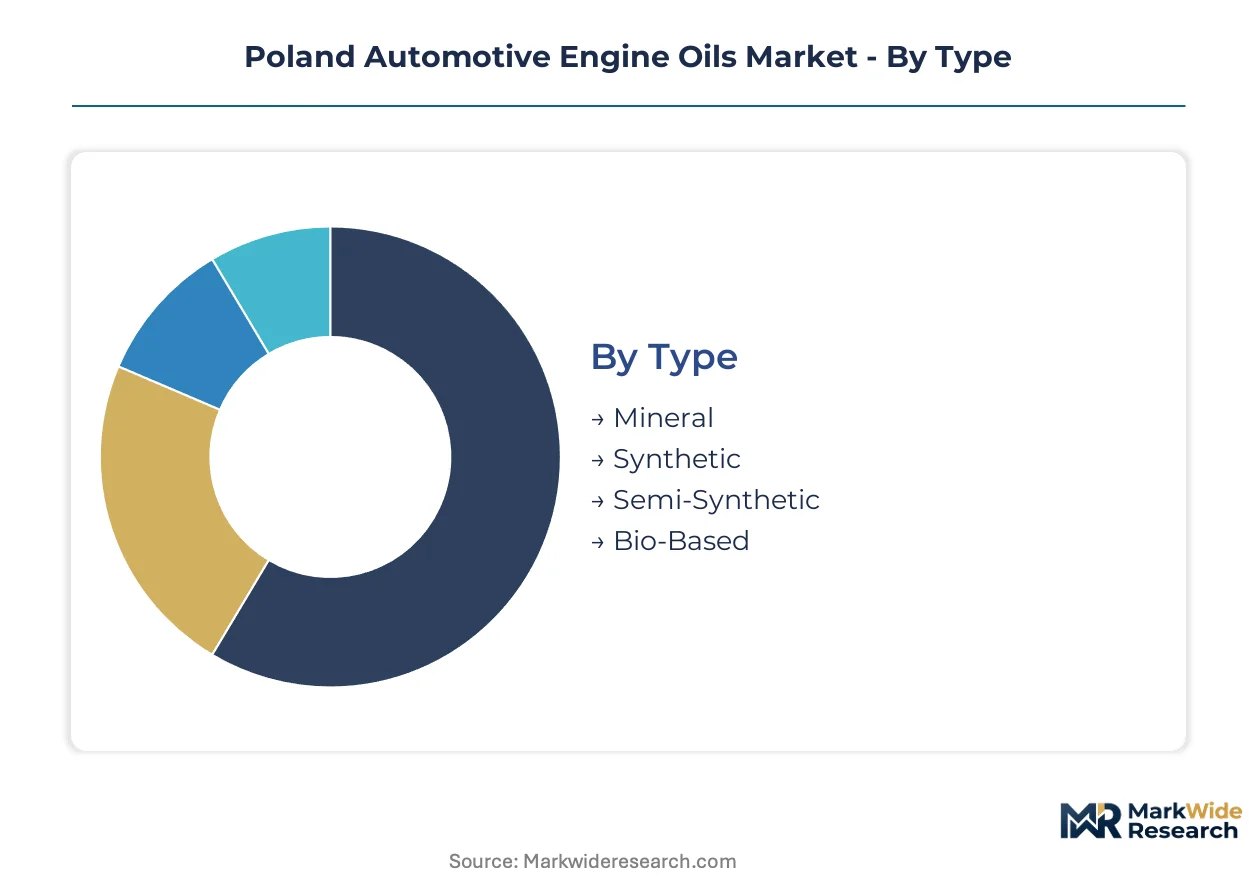
Formulation chemistry and procurement patterns in Poland's automotive engine oils market diverge sharply across lubricant types, viscosity grades, and end-use applications. Fleet consolidation and OEM specification tightening are compressing the addressable market for legacy mineral products while expanding premium synthetic deployment.
Type:
The volume versus premium split in Poland tilts toward synthetics for factory fill and fleet procurement, with mineral blends retaining dominance in price-sensitive service channels.
- Synthetic:Group III and PAO base stocks deliver ACEA C6-compliant high-temperature high-shear performance for turbocharged direct-injection engines. Warsaw-based fleet operators with Germany-Czechia cross-border routes specify these formulations under 100,000-kilometer drain interval contracts.
- Semi-Synthetic:Blends occupy the volume-dominant service-fill position for vehicles outside warranty coverage. Independent workshops in Poznań and Kraków stock these SKUs as the default upgrade path from mineral oils without incurring full synthetic cost.
- Mineral:Group I and II base stocks serve agricultural cooperatives and legacy vehicle populations where drain intervals remain short and specification compliance is less stringent.
- Bio-Based:Ester and vegetable-derived formulations target EU Green Deal biodegradability mandates anticipated for transport sector lubricants.
Mature deployment sits with mineral formulations in agricultural and legacy vehicle segments. Newer deployment is concentrated in synthetic specifications for fleet TCO programs and OEM factory fill.
Viscosity Grade:
Low-viscosity dominance accelerates as ACEA sequences tighten and hardware thermal loads increase across Poland's Silesian manufacturing corridor.
- 0W-20:Ultra-low viscosity grades with advanced friction modifier packages enable cold-start protection and fuel economy gains for hybrid and downsized turbocharged engines. OEM assembly plants near Katowice specify these for factory fill on new passenger car platforms.
- 5W-30:The workhorse specification balances low-temperature pumpability with high-temperature film strength for Poland's continental climate variability. Franchised dealer service channels in Warsaw and Łódź report this grade as the default recommendation for vehicles under warranty.
- 10W-40:Semi-synthetic and mineral blends in this grade serve older vehicle parc and commercial light-duty applications where OEM warranty compliance is not required.
- 15W-50:Heavy-duty mineral formulations persist in agricultural machinery and certain motorcycle applications where shear stability under mechanical stress outweighs fuel economy optimization.
Specification maturity clusters around 10W-40 in independent workshop channels. The steepest expansion trajectory belongs to 0W-20 as ACEA C6 adoption accelerates through OEM fill requirements.
Application:
End-use concentration in Poland mirrors the country's automotive production geography and commercial transport infrastructure.
- Heavy-Duty Trucks:Long-haul fleet operators generate the most concentrated margin pool through bulk procurement contracts and uptime guarantees. Silesia-based logistics companies operating into Germany consolidate lubricant buying under integrated maintenance agreements.
- Passenger Cars:The largest volume segment splits between OEM-controlled dealer service and independent workshop channels. ACEA specification divergence between European and export-bound vehicles forces dual inventory strategies for blenders.
- Commercial Vehicles:Light and medium-duty fleets in urban delivery and municipal service represent a transition zone between passenger car and heavy-duty specifications.
- Motorcycles:Niche demand concentrates in seasonal retail patterns with specialized friction requirements for wet clutch compatibility.
Volume leadership remains with passenger car applications. Margin compression is most severe in commercial vehicles as fleet procurement bypasses traditional distribution tiers.
Packaging Type:
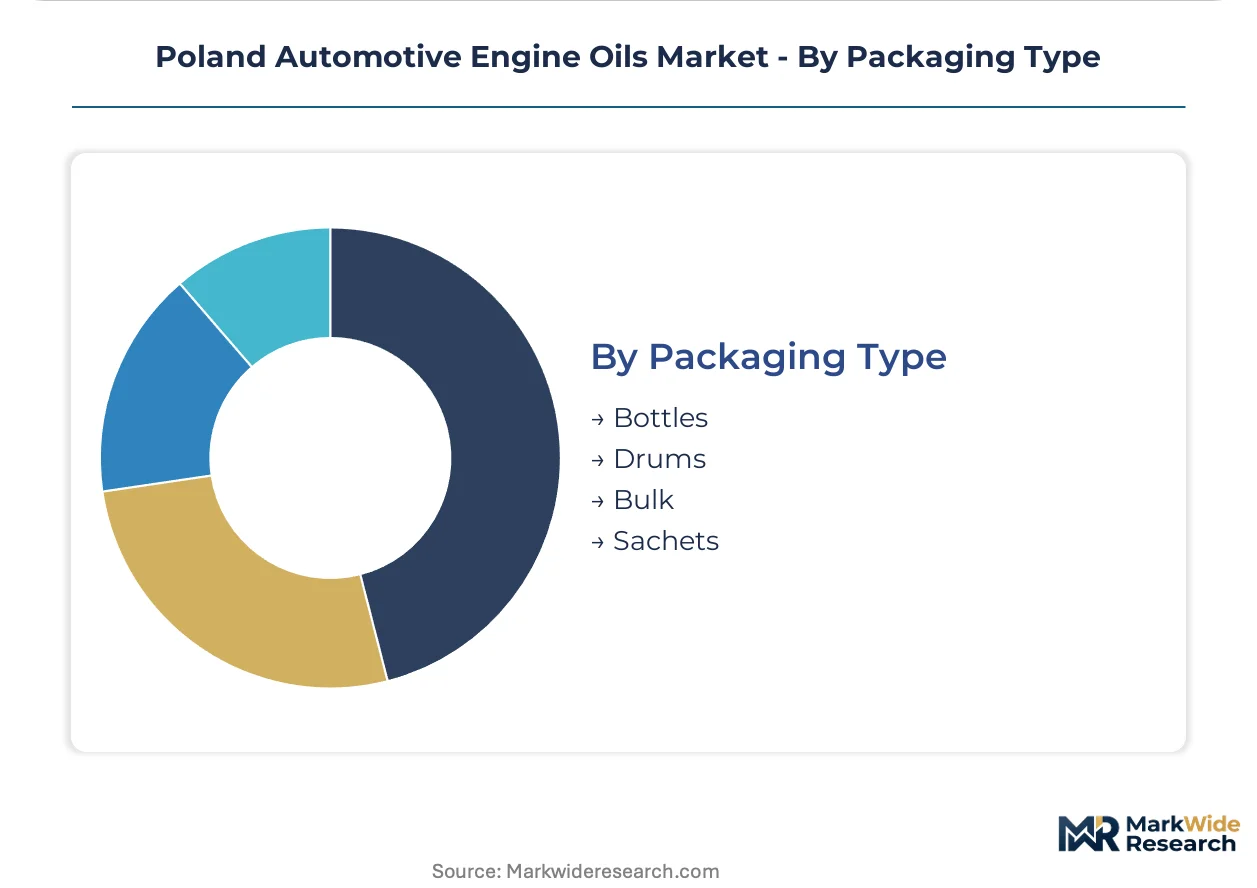
Procurement scale and supply chain efficiency dictate packaging selection across Poland's fragmented service landscape.
- Bulk:Tanker and tote deliveries dominate fleet and agricultural cooperative procurement, eliminating packaging cost and enabling just-in-time inventory at large-scale operators.
- Drums:200-liter steel and plastic drums serve medium-volume workshops and industrial maintenance departments with predictable consumption patterns.
- Bottles:Retail and small workshop channels stock 1-liter to 5-liter polyethylene containers for walk-in consumer purchases and top-off sales.
- Sachets:Single-use foil pouches address emergency roadside and motorcycle touring applications with minimal shelf space requirements.
Established infrastructure favors drum distribution through traditional jobber networks. Bulk delivery is expanding fastest as fleet procurement consolidation eliminates intermediate handling steps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Silesian automotive manufacturing corridor generates Poland's densest concentration of lubricant demand, with Katowice and Gliwice anchoring OEM assembly plants and tier-one supplier networks that require just-in-time technical service support.
Masovian Voivodeship
Warsaw's commercial transport hubs drive fleet procurement consolidation for cross-border logistics routes into Germany and Czechia. The region's municipal electrification targets under EU Green Deal transport decarbonization trajectories threaten long-term crankcase lubricant volumes for urban delivery segments. Fleet operators here specify ACEA C6-compliant 0W-20 formulations under 100,000-kilometer drain interval contracts.
Greater Poland Voivodeship
Poznań anchors independent workshop networks facing margin compression as distributor-fleet relationships bypass traditional jobber channels. REACH additive restrictions from ECHA force reformulation investments ahead of compliance deadlines for zinc dialkyldithiophosphate chemistries. Regional blenders stock semi-synthetic 5W-30 grades as the default upgrade path from mineral oils for vehicles outside warranty coverage.
Lesser Poland Voivodeship
Kraków's service-channel landscape mirrors Poznań's disintermediation pressures, with diagnostic specialization emerging as the surviving margin pool. The voivodeship's alignment with EU F-Gas Regulation forces refrigerant-lubricant compatibility testing for hybrid vehicle air conditioning circuits. Warsaw-based testing laboratories now serve Kraków-area formulators expanding validation capacity for R-1234yf thermal stability certification.
Lower Silesian Voivodeship
Wrocław's industrial machinery base sustains demand for 15W-50 mineral formulations in agricultural applications where shear stability outweighs fuel economy optimization. Poland's national standards body enforces conformity assessment for lubricant labeling equivalent to BIS frameworks. Agricultural cooperatives across the region remain underpenetrated by premium suppliers, presenting volume opportunity through seasonal bulk delivery programs.
Poland Automotive Engine Oils Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and OEM approval coverage, with synthetic-grade specialists commanding pricing power through ACEA sequence compliance while mineral-blend distributors compete on logistics reach. The vendor base splits between integrated European refiners with captive base oil supply and independent additive houses specializing in friction modifier chemistry. Two strategic archetypes dominate: refinery-anchored national champions with nationwide distribution infrastructure, and formulation specialists targeting OEM technical approvals. Competitive moves concentrate on backward integration into Group III base oil sourcing and exclusive supply agreements with heavy-duty fleet operators.
Within the refinery-anchored tier, PKN ORLEN and LOTOS OIL represent Poland's captive supply infrastructure, their positions reinforced by pipeline-connected blending capacity and agricultural cooperative distribution networks. ExxonMobil Corporation and Shell plc exemplify integrated multinational archetypes extending cross-border fleet agreements from Silesia into adjacent EU markets. LIQUI MOLY occupies the specialist position, its additive chemistry focus aligning with European OEM approval requirements for low-SAPS formulations. BP PLC through its Castrol brand and TotalEnergies sit between these poles, combining refinery integration with technical marketing investments in franchised dealer channels.
| Leading Market Players |
|---|
| LOTOS OIL |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| LIQUI MOLY |
| Shell plc |
| PKN ORLEN (ORLEN oil) |
| TotalEnergies |
| Motul |
| FUCHS |
| Others |
Value Network & Pricing Analysis
Group III base oil costs originating from Rotterdam and Antwerp hubs cascade through Poland's blending infrastructure into three-tier pricing structures across premium synthetic, semi-synthetic, and mineral economy levels. Transport cost volatility and currency-hedging complexity from these concentrated supply nodes compress margins for independent blenders while reinforcing pricing power for integrated refinery operators with captive upstream supply.
Pricing Analysis
Uptime-guarantee contracts with 100,000-kilometer drain intervals anchor value-based pricing for heavy-duty fleet operators. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels differentiates by ACEA certification grade and volume procurement scale. Cost compression in the mineral tier intensifies because agricultural cooperatives and legacy vehicle owners exhibit highest price sensitivity. Fleet procurement departments demonstrate lowest price sensitivity as total cost of ownership metrics override per-liter pricing.
Supply Chain Analysis
Poland's alignment with EU REACH and RoHS frameworks functions as de facto local-content rules reshaping additive chemistry sourcing toward ECHA-compliant European suppliers. Group III base oil supply concentrates in the Netherlands and Belgium, while additive packages draw from Germany and France. Single-source vulnerability in Rotterdam-Antwerp base oil corridors exposes Polish blenders to logistics chokepoint risks. Distribution runs through refinery-anchored national champions with pipeline-connected blending capacity and agricultural cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's automotive engine oils market operates as a cost-of-compliance story where EU F-Gas Regulation alignment and REACH additive restrictions erect barrier-to-entry moats favoring blenders with established ECHA certification pathways and reformulation R&D infrastructure.
For Market Incumbents: Lock in exclusive supply agreements with Silesian heavy-duty fleet operators operating cross-border routes into Germany and Czechia before independent additive houses secure footholds. Defend against disintermediation by embedding oil analysis and filter supply into integrated maintenance contracts that bypass traditional jobber networks. Prioritize backward integration into Group III base oil sourcing through Rotterdam hub partnerships to neutralize transport cost volatility. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest-friction entry vector for bypassing entrenched distributor relationships in Warsaw and Poznań. Agricultural cooperatives across Lower Silesian Voivodeship represent the most penetrable white-space segment, currently served by commodity mineral blends with minimal technical service support. Target this segment through seasonal bulk delivery programs bundled with harvest-season uptime guarantees and simplified SKU architectures. For Investors and Strategic Acquirers: Accelerating ACEA-API specification divergence is the leading indicator that dual-inventory capability will command acquisition premiums as export-oriented Polish OEM plants require parallel compliance pathways. The 5-10 year viability window favors blenders with established low-SAPS formulation expertise and refrigerant-lubricant compatibility testing capacity for hybrid vehicle platforms. Acquisition target archetype: mid-cap specialists with Warsaw-based testing laboratory access and ECHA pre-registration for next-generation additive chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Supply | Captive sourcing from Rotterdam-Antwerp hubs neutralizes currency-hedging complexity for Polish blenders. |
| Refrigerant-Lubricant Compatibility Certification | R-1234yf thermal stability validation opens hybrid vehicle service channels under EU F-Gas Regulation. |
| Integrated Fleet Maintenance Contracts | Oil analysis bundling with filter supply locks in heavy-duty operator relationships across Silesia-Germany-Czechia corridors. |
| Agricultural Cooperative Bulk Delivery Programs | Seasonal harvest-season uptime guarantees penetrate underpenetrated farm machinery segments in Lower Silesia. |
| Low-SAPS Formulation R&D Investment | ACEA C6 compliance capability secures OEM factory fill specifications for turbocharged direct-injection platforms. |
Research Methodology
Trade flow databases, ECHA regulatory filings, and ACEA technical documentation formed the secondary backbone for supply-side modeling. Primary interviews with blending plant managers, fleet procurement officers at Silesian logistics operators, agricultural cooperative supply heads, and aftermarket distributor principals combined with secondary validation to triangulate demand patterns. Bottom-up volume builds across formulation types, viscosity grades, and end-use applications were cross-checked against top-down macro indicators from vehicle parc and production data.
Historical trendline analysis tracked specification evolution from ACEA C3 through C6 sequences alongside drain interval extension patterns in commercial fleet operations. Segmentation dimensions modeled included lubricant type, viscosity grade, end-use application, packaging format, and regional procurement cluster. CAGRs were derived from elasticity-adjusted projection of fleet TCO program adoption and OEM fill specification mandates. Industry-specific forecast inputs incorporated EU Green Deal transport decarbonization trajectories and electrification displacement curves for urban delivery segments.
The model holds under sustained ACEA sequence tightening and REACH additive restriction enforcement; deviation in battery electric vehicle penetration rates or F-Gas Regulation rollback would shift volume trajectories. Forecasts reflect documented assumptions regarding specification compliance timelines and fleet consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Malaysia Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Jordan Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
Contact Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Industrial Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Global Finished Lubricant Market