
 Aviation Lubricants Market | 2026-2036
Aviation Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Lubricants Market Intelligence
Synthetic ester base stocks is broadening the performance envelope for turbine engine oils, enabling longer drain intervals and reduced coking in high-bypass turbofans. Exxon Mobil Corporation leverages its integrated polyalphaolefin supply chain to control input costs across formulation tiers. Royal Dutch Shell anchors its position through OEM co-development agreements with engine manufacturers. Castrol competes on technical service intensity, embedding lubrication engineers directly with airline maintenance teams.
Aviation lubricants are specialty fluids engineered to operate across temperature extremes from minus 54 degrees Celsius to above 200 degrees Celsius, with primary functions including friction reduction, wear protection, thermal transfer, and seal compatibility in gas turbine and piston powerplants. Turbine engine oils command the largest value share due to the higher complexity and regulatory burden of jet engine formulations, while synthetic formulations are outpacing mineral-based alternatives as operators prioritize extended service intervals and fuel efficiency gains. The commercial aviation application segment carries the deepest margin pools, reflecting the scale economics of scheduled airline fleet operations versus fragmented general aviation demand.
The FAA mandates SAE AS5780 and MIL-PRF-23699 standards for civil and military turbine lubricants, respectively, creating a dual-compliance burden for suppliers serving both customer bases. REACH restrictions on certain phosphate ester additives in Europe are accelerating reformulation investments by multinational blenders. EASA's evolving sustainability mandates around life-cycle carbon accounting will reshape procurement criteria for airlines operating across EU airspace. Stakeholders must monitor how regulatory divergence between the FAA and EASA affects product platform economics and inventory complexity.
Market Dynamics
The FAA's tightened smoke-point and thermal-stability requirements for turbine engine oils are forcing wholesale formulation upgrades across the supply base, compressing product development cycles and raising qualification barriers for smaller blenders.
Growth Catalysts
- SAE AS5780 compliance mandates:The FAA's updated civil turbine lubricant standards are accelerating replacement demand as airlines retire legacy formulations that no longer meet thermal stability thresholds.
- High-bypass turbofan fleet expansion:Next-generation engines from GE Aerospace and Pratt & Whitney require synthetic ester base stocks capable of extended drain intervals under higher thermal loads.
- United States MRO concentration:Major carriers and independent maintenance providers in the US account for dominant procurement volumes, creating scale incentives for localized blending capacity.
Market Restraints
- Polyalphaolefin feedstock volatility:Synthetic base stock prices track crude oil and natural gas liquids, exposing blenders to input cost swings that compress margin predictability.
- REACH additive restrictions:ECHA limitations on certain phosphate ester anti-wear additives force European-serving suppliers into parallel formulation tracks, raising inventory complexity.
- Technical ceiling on mineral formulations:Conventional petroleum-based turbine oils cannot achieve the 200-plus degree Celsius thermal stability required by new engine architectures, locking suppliers into synthetic-only development paths.
Strategic Opportunities
- Sustainable aviation fuel compatibility:EASA's evolving life-cycle carbon accounting mandates will reshape procurement criteria, favoring lubricant suppliers with verified carbon footprint transparency across EU airspace operations.
- Urban air mobility powerplants:Electric-vertical-takeoff-and-landing hybrid turbines require specialized thermal management fluids, opening formulation contracts with emerging airframe developers.
- Direct airline technical partnerships:Embedding lubrication engineers within carrier maintenance teams creates switching costs and captures volume commitments outside traditional distributor channels.
Industry Challenges
- Tribology specialist scarcity:The pool of engineers qualified in aviation lubricant formulation and engine-specific compatibility testing has not expanded with qualification demand, extending hiring timelines.
- Dual military-civil certification burden:Suppliers serving both FAA civil and MIL-PRF-23699 military specifications must maintain parallel testing protocols, duplicating qualification expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Lubricants Market |
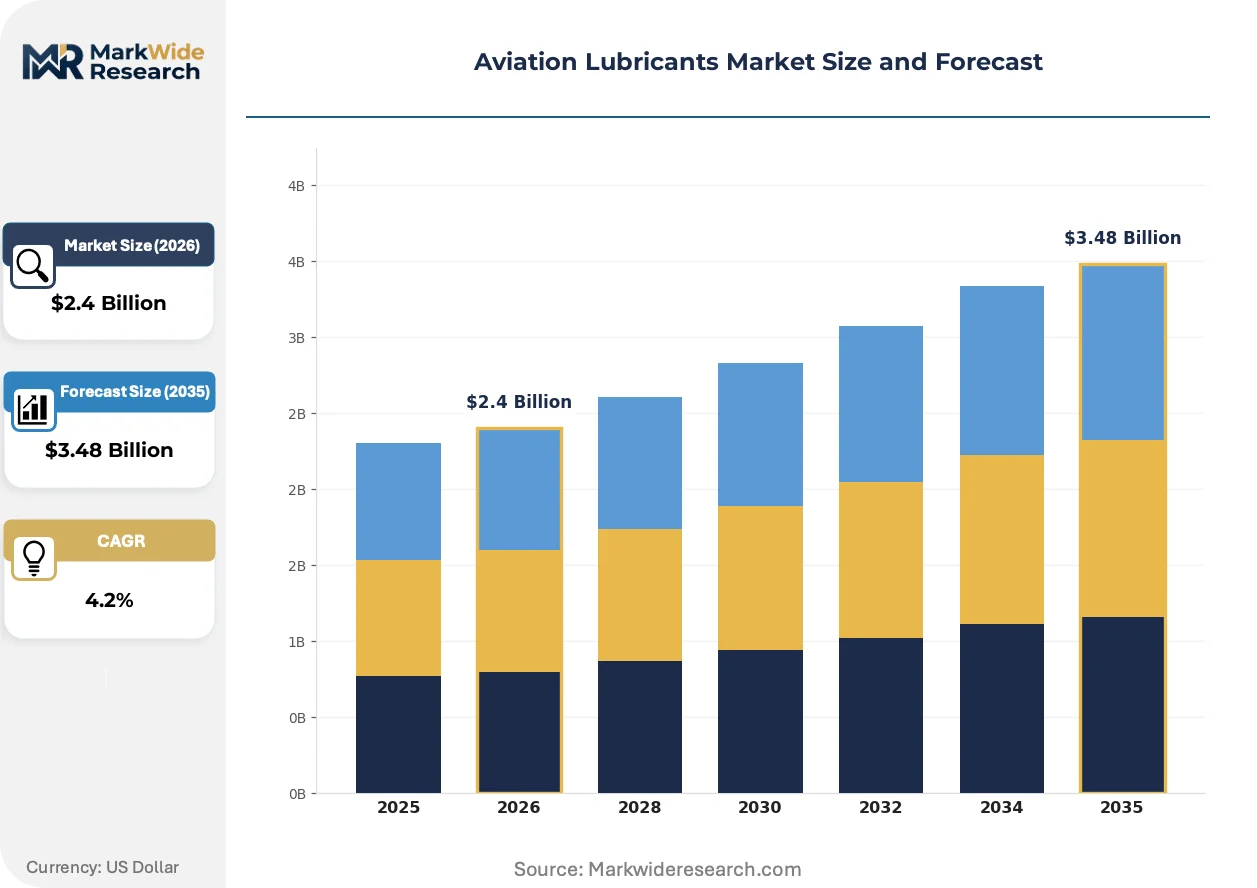
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Engine Oils, Turbine Engine Oils, Gear Oils, Hydraulic Fluids Application: Commercial Aviation, Military Aviation, General Aviation, Aerospace Manufacturing Formulation: Synthetic, Mineral-Based, Biodegradable, Semi-Synthetic End User: Airlines, Charter Services, Maintenance, Repair & Overhaul, Aircraft Manufacturers |
| Companies Covered | Eastman Chemical Company, Phillips 66, Exxon Mobil Corporation, Castrol, NYCO, Total Energies, The Chemours Company, Lukoil, Royal Dutch Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Lubricants Market Strategic Shifts & Innovations
Formulation science is advancing faster than certification frameworks can adapt, creating tension between performance claims and regulatory validation timelines.
Synthetic ester base stocks with enhanced oxidative stability are automating the transition from time-based to condition-based oil changes in commercial airline fleets. Delta Air Lines and United Airlines have piloted sensor-integrated monitoring systems that extend drain intervals by 30-50 percent where thermal degradation thresholds permit. This automation is compressing the revenue-per-gallon model that has sustained lubricant suppliers for decades.
REACH restrictions on phosphate ester additives are forcing reformulation investments by multinational blenders with European exposure. The industrial consequence is a divergence between US and EU product platforms, as ECHA's hazard classifications outpace FAA toxicity evaluations. Suppliers with integrated European blending assets are responding with regional-specific SKUs that sacrifice economies of scale for compliance certainty.
Airline procurement teams are consolidating lubricant contracts under multi-year technical service agreements that bundle fluid supply with used-oil analysis and predictive maintenance support. Traditional distributors are losing share to direct supplier relationships as carriers prioritize technical integration over transactional purchasing. This pattern is most visible among US legacy carriers with centralized fleet management operations.
Aviation Lubricants Market Segmentation
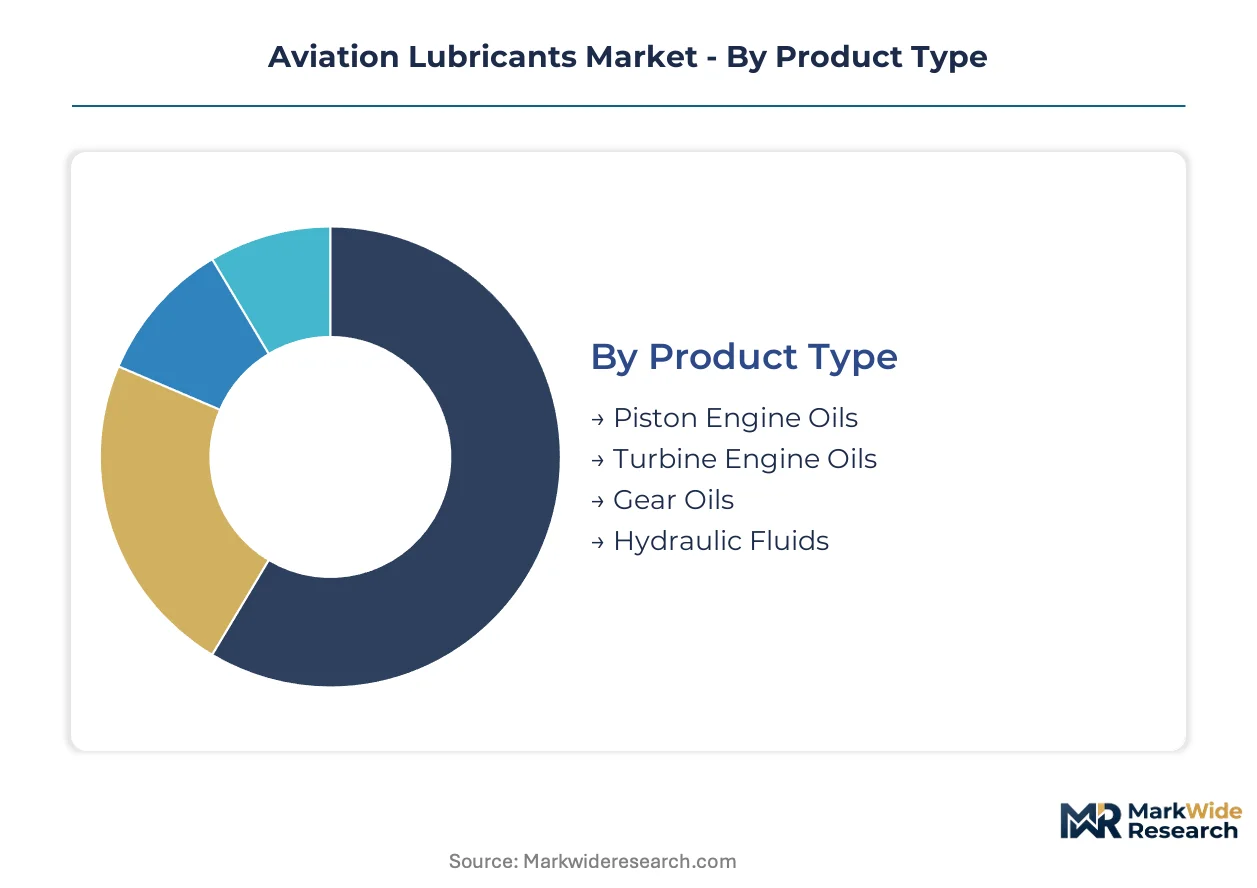
Aviation lubricant procurement follows distinct technical specifications across engine architectures and operational profiles. Fleet operators segment purchases by thermal load requirements, regulatory certification tiers, and maintenance integration depth.
Product Type:
Thermal stability thresholds and drain interval economics separate product categories by engine architecture complexity.
- Turbine Engine Oils:Synthetic ester formulations withstand continuous operation above 200 degrees Celsius in high-bypass turbofans. Demand concentrates among US legacy carriers upgrading fleets to meet FAA AS5780 thermal stability mandates, with drain interval extension driving premium formulation uptake.
- Piston Engine Oils:Ashless dispersant and multi-grade formulations serve reciprocating powerplants in general aviation and training aircraft. Volume procurement clusters with flight schools and charter operators in the United States, where piston fleet hours remain elevated relative to other developed markets.
- Hydraulic Fluids:Fire-resistant phosphate ester formulations operate landing gear and flight control actuators.
- Gear Oils:Extreme-pressure lubricants protect reduction gearboxes in turboprop and helicopter transmissions.
Mature deployment sits with Turbine Engine Oils. Newer deployment is concentrated in synthetic reformulations of legacy mineral-based grades.
Application:
Operational intensity and fleet scale create divergent margin structures across aviation end-uses.
- Commercial Aviation:Scheduled airline operations generate the deepest procurement volumes through centralized technical service agreements. US major carriers consolidate lubricant contracts under multi-year bundles combining fluid supply, used-oil analysis, and predictive maintenance support.
- Military Aviation:MIL-PRF-23699 specification compliance adds qualification burden for suppliers serving defense operators. Dual-certification requirements with civil FAA standards force parallel testing protocols, compressing margins for blenders without dedicated military product lines.
- General Aviation:Fragmented owner-operator demand flows through distributor networks rather than direct supplier relationships.
- Aerospace Manufacturing:Initial fill and break-in lubricants for new airframe production.
Procurement consolidation runs deepest in Commercial Aviation. Technical integration requirements expand fastest in Military Aviation.
Formulation:
Base stock chemistry determines thermal ceiling and regulatory compliance pathway.
- Synthetic:Polyalphaolefin and ester base stocks enable extended drain intervals under higher thermal loads. Next-generation engine architectures from GE Aerospace and Pratt & Whitney mandate synthetic-only formulations, displacing mineral alternatives in new fleet procurement.
- Mineral-Based:Conventional petroleum-derived formulations face technical obsolescence as thermal stability requirements tighten. Remaining demand concentrates in cost-sensitive general aviation segments and older turbine fleets without specification upgrade pressure.
- Semi-Synthetic:Blended formulations balance performance and cost in mid-life fleet applications.
- Biodegradable:Emerging formulations targeting EASA sustainability accounting mandates and potential hydraulic fluid leakage scenarios.
Synthetic formulations anchor new fleet deployment. Mineral-based stocks retain position in legacy piston and aging turbine operations.
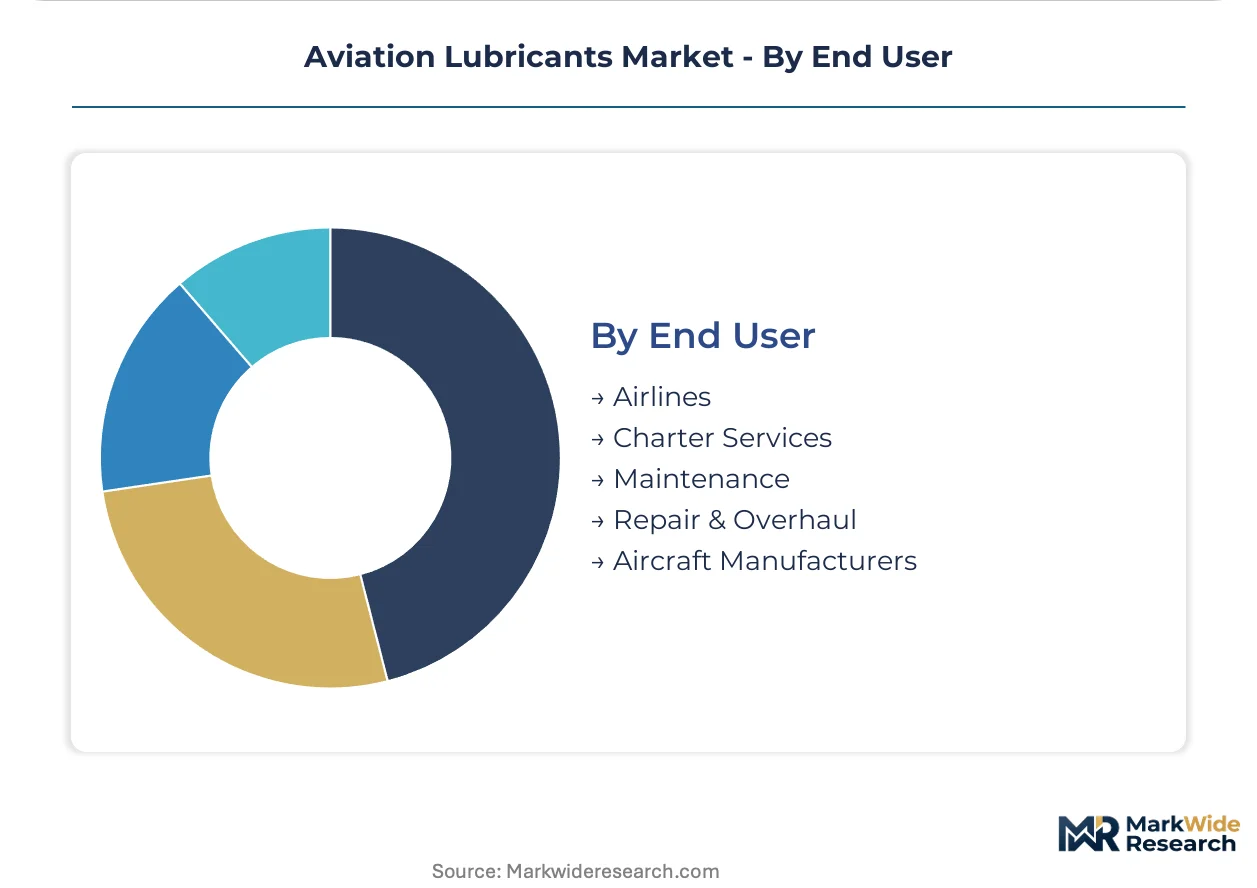
End User:
Technical capability and fleet scale determine purchasing channel preference.
- Maintenance, Repair & Overhaul:Independent MRO providers in the United States aggregate demand from multiple carriers, creating scale incentives for localized blending capacity. Technical service intensity separates competitive positions, with lubricant suppliers embedding engineers directly within maintenance teams.
- Airlines:Major carriers with centralized fleet management operations bypass traditional distributors for direct supplier relationships. Procurement teams prioritize predictive maintenance integration over transactional fluid purchasing.
- Aircraft Manufacturers:Initial fill specifications and factory break-in protocols.
- Charter Services:Fragmented demand through regional distributor networks with limited technical integration.
Direct supplier relationships concentrate with Airlines. Distributor dependency persists with Charter Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial airline fleet operators in the United States generate the dominant share of aviation lubricant procurement volumes, with major carriers and MRO providers concentrating demand in specific metropolitan maintenance clusters. Regulatory divergence between the FAA and EASA is forcing suppliers into parallel formulation tracks that reshape regional competitive positioning.
United States
Legacy carriers including Delta Air Lines and United Airlines are consolidating lubricant contracts under multi-year technical service agreements that bundle fluid supply with predictive maintenance support. The FAA's tightened AS5780 thermal stability mandates are accelerating replacement demand for legacy turbine engine oil formulations. Dallas-Fort Worth and Chicago O'Hare maintenance corridors host the densest concentrations of MRO blending capacity serving domestic fleet operators.
Germany
Lufthansa Technik's centralized fleet management operations drive premium formulation demand for high-bypass turbofan maintenance. ECHA restrictions on phosphate ester additives under REACH regulations are forcing reformulation investments by suppliers serving EU airspace operators. The Hamburg and Frankfurt aviation maintenance clusters anchor lubricant technical service intensity for Central European carriers.
France
Air France-KLM's fleet renewal programs are sourcing synthetic ester formulations compatible with next-generation engine architectures from GE Aerospace and Safran. EASA's evolving life-cycle carbon accounting mandates are reshaping procurement criteria toward verified carbon footprint transparency. The Toulouse aerospace manufacturing corridor generates initial fill demand for factory break-in lubricants on new airframe production lines.
United Kingdom
Rolls-Royce engine maintenance operations at Derby and Bristol drive specialized turbine oil demand for civil and military powerplant overhaul. Dual MIL-PRF-23699 and civil certification requirements compress margins for blenders serving defense operators without dedicated military product lines. London Heathrow's MRO provider network aggregates fragmented charter and cargo operator demand through regional distributor channels.
Singapore
SIA Engineering and ST Aerospace anchor the Asia-Pacific region's largest third-party MRO lubricant procurement volumes for wide-body fleet maintenance. The Civil Aviation Authority of Singapore's adoption of FAA-equivalent thermal stability standards simplifies formulation compliance for US-origin suppliers. Changi Airport's maintenance zone concentrates blending capacity serving Southeast Asian carrier fleets and transit traffic.
Aviation Lubricants Market Key Industry Players
Capacity expansion dominates the current landscape as suppliers build localized blending assets to capture US MRO procurement volumes and simplify REACH compliance for European operations. The vendor base concentrates around integrated petrochemical majors and specialty lubricant blenders with dedicated aviation certification capabilities. Three strategic archetypes define competitive positioning: integrated oil majors controlling base stock supply chains, specialty chemical companies with OEM co-development relationships, and regional blenders competing on technical service intensity. Geographic expansion and portfolio diversification toward sustainable aviation fuel-compatible formulations represent the dominant competitive moves.
Among integrated oil majors, Exxon Mobil Corporation and Royal Dutch Shell exemplify the base-stock-integrated archetype, with Exxon Mobil leveraging captive polyalphaolefin supply chains and Shell anchoring position through engine manufacturer partnerships. Castrol occupies a position within the technical-service-intensive tier, embedding lubrication engineers directly with airline maintenance teams to create switching costs outside traditional distributor channels. These three companies represent distinct competitive vectors: upstream supply control, OEM relationship leverage, and maintenance integration depth.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Phillips 66 |
| Exxon Mobil Corporation |
| Castrol |
| NYCO |
| Total Energies |
| The Chemours Company |
| Lukoil |
| Royal Dutch Shell |
| Others |
Cost & Logistics Intelligence
EASA's evolving life-cycle carbon accounting mandates gate both qualified supply and premium-tier pricing access for aviation lubricant suppliers serving EU airspace operators, compressing margins for blenders lacking verified carbon footprint transparency while rewarding integrated majors with European blending assets and certified formulation portfolios.
Pricing Analysis
The volume-vs-margin split concentrates procurement power among US legacy carriers and MRO providers, with pricing stratifying across AS5780-certified premium formulations, MIL-PRF-23699 military grades, and legacy mineral-based economy tiers. Price differentiation hinges on thermal stability certification thresholds and technical service bundling depth, with predictive maintenance integration commanding 15-25 percent premiums over transactional fluid supply. Cost compression in mineral-based tiers is intensifying because specification obsolescence locks suppliers into synthetic-only development paths. Charter operators and general aviation fleets exhibit highest price sensitivity, while major carriers with centralized technical service agreements prioritize drain interval economics over per-gallon unit costs.
Supply Chain Analysis
Certification and qualification gating under FAA AS5780 and MIL-PRF-23699 standards restricts blendable capacity to suppliers with dedicated aviation testing protocols, concentrating qualified supply in the United States, Germany, and Singapore. Base stock chemistry draws from polyalphaolefin and synthetic ester feedstocks tethered to crude oil and natural gas liquids pricing, with phosphate ester anti-wear additives facing ECHA restriction under REACH regulations. Single-source vulnerability runs through integrated oil majors controlling captive polyalphaolefin supply chains. Distribution feeds from direct supplier relationships with major carriers and technical service agreements with MRO providers, bypassing traditional distributor channels for fleet-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aviation lubricants market is becoming a vertical-integration race, with suppliers pursuing backward integration into synthetic base stock production to secure margin control against polyalphaolefin feedstock volatility and qualification-tightening regulatory cycles.
For Market Incumbents: Anticipate specification divergence between FAA and EASA regulatory frameworks by maintaining parallel formulation tracks and regional blending assets, while embedding lubrication engineers within airline maintenance teams to create switching costs against distributor-channel competitors. Dual military-civil certification burdens compress margins for undifferentiated blenders, making technical service intensity the priority defensive lever. For New Entrants and Emerging Players: Begin with urban air mobility powerplant thermal management fluids, where emerging eVTOL hybrid turbine architectures lack incumbent supplier relationships and formulation standards remain unsettled. Target direct technical partnerships with airframe developers over distributor-dependent general aviation channels, leveraging tribology specialist scarcity to command premium positioning before qualification frameworks mature. For Investors and Strategic Acquirers: FAA-EASA regulatory divergence announcements are the leading indicator that inventory complexity will favor suppliers with integrated European blending footprints over import-dependent competitors. The five-to-ten year viability window rewards acquisition of specialty blenders with established OEM co-development relationships and verified carbon footprint transparency for EASA compliance. Watch for REACH additive restriction expansions as the signal to accelerate due diligence on reformulation-capable assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Exxon Mobil's captive polyalphaolefin supply chain demonstrates margin insulation against feedstock volatility. |
| OEM Co-Development Agreements | Shell's engine manufacturer partnerships anchor specification influence for next-generation turbofan architectures. |
| Regional Blending Asset Expansion | Localized capacity in Dallas-Fort Worth and Hamburg simplifies dual FAA-EASA compliance logistics. |
| Technical Service Embedding | Castrol's lubrication engineer placement with Delta and United maintenance teams creates contractual switching costs. |
| Sustainability Certification Investment | Verified carbon footprint transparency positions suppliers for EASA life-cycle accounting mandate compliance. |
Research Approach
Document review covered FAA certification databases, ECHA REACH restriction filings, and airline technical service agreement disclosures, complemented by interviews with lubricant formulation directors, MRO procurement managers, airline fleet engineering leads, and base stock supply specialists. Secondary validation drew from SEC 10-K filings of integrated oil majors, customs trade data on synthetic ester imports, and ASTM lubricant specification archives. Bottom-up fleet size modeling and top-down procurement volume estimates were triangulated against regional maintenance capacity data.
Market sizing and growth projections were derived from segment-level modeling across turbine engine oils, piston engine oils, hydraulic fluids, and gear oils by formulation chemistry, application intensity, and end-user channel structure over the projection horizon. CAGRs were computed from year-over-year volume and value trajectories, with synthetic formulation displacement rates and drain interval extension assumptions calibrated against carrier pilot program disclosures. Forecast inputs incorporated high-bypass turbofan fleet delivery schedules and REACH regulatory phase-out timelines.
Underlying measurement precision varies by segment; commercial aviation procurement carries tighter precision than fragmented general aviation demand due to centralized contract visibility. Forecasts reflect assumptions on regulatory harmonization, feedstock price stability, and OEM specification evolution. A model refresh is warranted upon material change in FAA-EASA regulatory divergence or sustainable aviation fuel compatibility mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Spain Automotive Lubricants Market
Lubricants
India Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Global Grease Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Biolubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
High Performance Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
North America Lubricants Market
Lubricants
Heavy Equipment Lubricants Market