
 Singapore Commercial Vehicles Lubricants Market | 2026-2036
Singapore Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Commercial Vehicles Lubricants Market Analytics
Fluid analysis subscription programs is recalibrating how fleet operators procure lubricants in Singapore. Shell plc leverages its integrated service network to bundle oil condition monitoring with product supply. Fuchs Singapore anchors its position through specialized technical support for construction equipment fleets. AP Oil competes on localized blending capabilities and rapid turnaround for bus depot contracts.
Singapore commercial vehicles lubricants are formulated base oil and additive packages designed to reduce friction, dissipate heat, and protect engine and drivetrain components under tropical operating conditions with high humidity and stop-start traffic patterns. Engine oil commands the largest volume share given mandatory drain intervals for heavy duty trucks operating under Land Transport Authority regulations. Last-mile delivery vehicles represent the fastest-growing application segment as e-commerce logistics providers expand electric and internal combustion fleets requiring specialized lubricant formulations.
Singapore's National Environment Agency enforces waste oil disposal protocols that incentivize re-refining partnerships between lubricant suppliers and fleet operators. The Land Transport Authority's Vehicle Emissions Scheme directly links lubricant quality to particulate matter compliance for commercial diesel engines. Workshop certification standards administered by the country's automotive trade association shape which products gain preferential placement in service bays. Stakeholders must track how electrification timelines for urban delivery fleets alter lubricant volume assumptions and service revenue models.
Market Dynamics
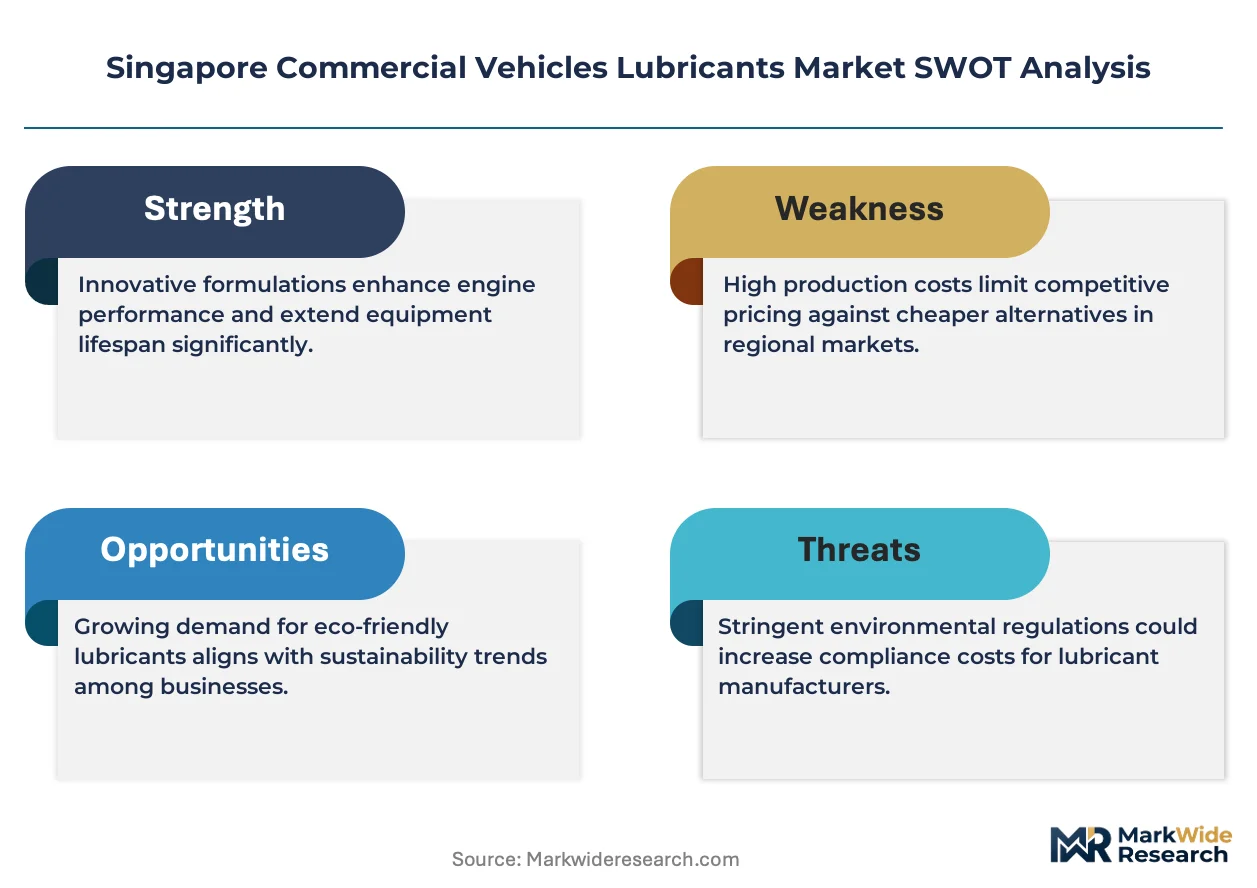
Singapore's Land Transport Authority emission standards are compressing drain intervals for heavy duty trucks, forcing fleet operators into tighter maintenance cycles that amplify lubricant throughput in workshop-direct channels.
Growth Catalysts
- Last-mile delivery fleet expansion:E-commerce logistics providers are scaling internal combustion and electric vehicle fleets, generating demand for specialized lubricant formulations across multiple viscosity grades.
- NEA waste oil protocols:Singapore's National Environment Agency mandates re-refining partnerships, creating recurring revenue streams for suppliers through closed-loop collection programs.
- Preventive maintenance programs:Logistics operators are institutionalizing scheduled fluid analysis, embedding lubricant procurement into long-term service contracts rather than spot purchases.
Market Restraints
- Base oil import dependency:Singapore lacks domestic crude refining for Group II/III base stocks, exposing blenders to freight volatility from Middle Eastern and South Korean suppliers.
- Workshop certification concentration:The country's automotive trade association controls service bay accreditation, limiting product placement for non-affiliated lubricant brands.
- Electric drivetrain lubrication reduction:Battery electric commercial vehicles eliminate engine oil demand entirely, threatening volume assumptions for urban delivery segments.
Strategic Opportunities
- Fluid analysis subscription bundling:Oil condition monitoring services are expanding into construction equipment fleets, capturing data-rich relationships beyond commodity supply.
- Bus depot rapid turnaround contracts:Public transport operators require localized blending capabilities with same-day delivery, favoring suppliers with Jurong Island storage assets.
- Vehicle Emissions Scheme alignment:The Land Transport Authority's particulate matter compliance rules reward high-performance lubricant formulations with preferential fleet procurement status.
Industry Challenges
- Tribology talent scarcity:Specialized lubricant formulation expertise for tropical humidity conditions remains concentrated among senior engineers approaching retirement.
- Electrification timeline uncertainty:Fleet operators are deferring long-term lubricant contracts due to ambiguous Land Transport Authority phase-out schedules for diesel commercial vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Commercial Vehicles Lubricants Market |
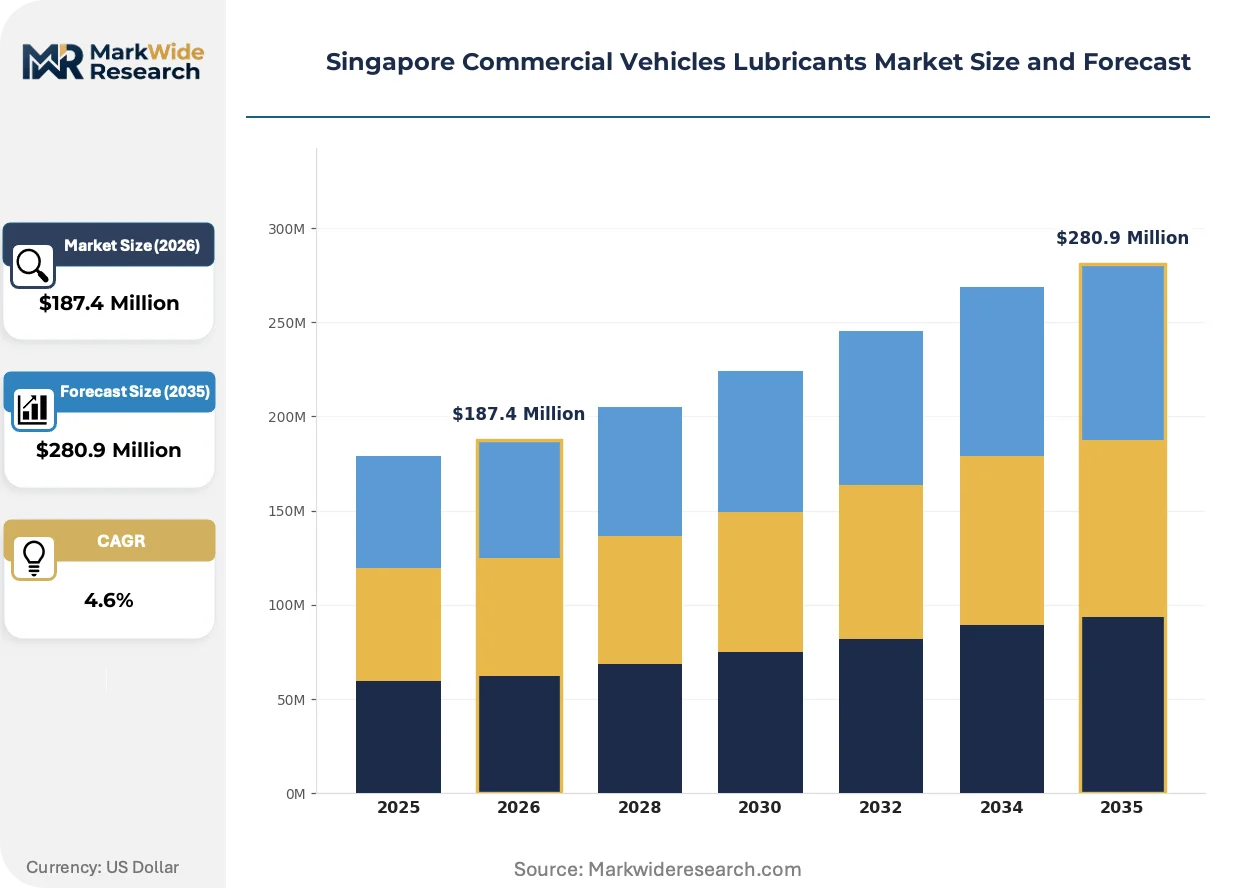
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Greases Application: Light Commercial Vehicles, Heavy Duty Trucks, Buses, Last-Mile Delivery Vehicles End User: Fleet Operators, Logistics Providers, Construction Companies, Transportation Services Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Workshops |
| Companies Covered | BP Plc (Castrol), Chevron Corporation, ExxonMobil Corporation, Shell plc, TotalEnergies, Fuchs Singapore, AP Oil, Sinopec Lubricant Singapore, Idemitsu Kosan Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Commercial Vehicles Lubricants Market Evolving Landscape
Tropical formulation chemistry and digital service integration are redefining how lubricant value is captured in Singapore's commercial vehicle maintenance ecosystem.
Synthetic low-viscosity engine oils formulated for high-humidity, stop-start operating conditions are expanding into heavy duty truck fleets. Logistics operators running Land Transport Authority-regulated vehicles are adopting these formulations to extend drain intervals without violating emission compliance thresholds. The technology is expanding into workshop-direct distribution channels previously dominated by mineral-based products.
Singapore's National Environment Agency waste oil disposal protocols now mandate cradle-to-grave tracking for commercial fleet generators. The regulation forces lubricant suppliers to integrate collection logistics with product supply, raising operational complexity for market entrants. Heavy duty truck workshops face the steepest compliance burden due to higher waste oil volumes per service event.
Fleet procurement teams are consolidating lubricant purchasing under fluid analysis subscription programs that bundle monitoring hardware, laboratory services, and product supply. Workshop-direct channels are capturing this consolidated spend by embedding technical support into long-term agreements. Last-mile delivery operators show the fastest adoption velocity due to tighter vehicle utilization rates and downtime sensitivity.
Singapore Commercial Vehicles Lubricants Market Segmentation
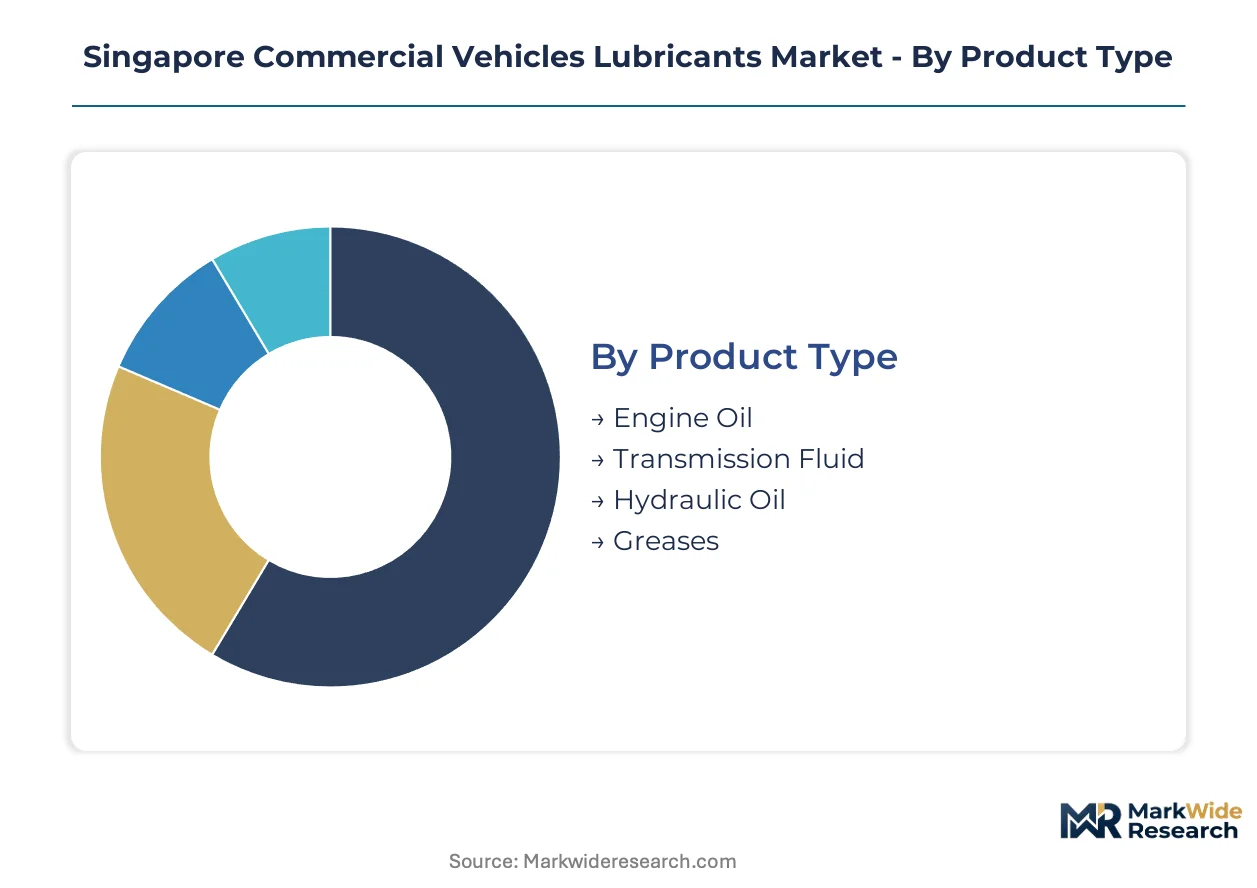
Singapore's commercial vehicles lubricants market fragments across product formulations, vehicle duty cycles, and procurement relationships. Fleet operators navigate these dimensions to balance Land Transport Authority compliance against total cost of ownership in tropical operating conditions.
Product Type:
Fleet procurement teams prioritize viscosity grade selection and additive package performance when specifying lubricants for tropical humidity and stop-start traffic patterns.
- Engine Oil:Formulated with Group II/III base stocks and detergent-dispersant additives to manage soot loading in diesel engines under Land Transport Authority emission standards. Heavy duty truck workshops command the largest procurement volumes due to mandatory drain intervals, though synthetic low-viscosity grades are gaining share for extended service life.
- Transmission Fluid:Synthetic blends designed for automated manual transmissions in urban delivery fleets experiencing high shift frequency. Last-mile logistics providers specify these fluids to reduce gearbox wear under stop-start duty cycles, with demand concentrating in workshop-direct channels serving e-commerce vehicle pools.
- Hydraulic Oil:Anti-wear formulations for construction equipment and refuse truck lift systems operating in Singapore's high-humidity environment.
- Greases:Lithium-complex and calcium-sulfonate thickeners for chassis lubrication points and wheel bearings in bus depot maintenance programs.
Volume sits with Engine Oil; growth tilts toward Transmission Fluid.
Application:
Vehicle classification under Land Transport Authority regulations determines lubricant specification tiers and service interval mandates.
- Heavy Duty Trucks:Class 4 and 5 vehicles operating under strict emission compliance windows drive demand for high-performance diesel engine oils with extended drain capabilities. Fleet operators running regional logistics routes specify these formulations to minimize downtime at Jurong Island and Tuas Port corridors.
- Last-Mile Delivery Vehicles:Light commercial vans and small trucks serving e-commerce fulfillment networks require specialized lubricants for high-frequency stop-start operation. Logistics providers scaling electric and internal combustion hybrid fleets are expanding procurement of low-viscosity grades to optimize fuel efficiency under tight utilization schedules.
- Buses:Public transport depot contracts mandate rapid-turnaround lubricant supply with same-day blending capabilities.
- Light Commercial Vehicles:Generic service workshop segment with price-sensitive procurement patterns.
Heavy Duty Trucks dominate current volume; Last-Mile Delivery Vehicles are climbing the fastest as e-commerce logistics scales.
End User:
Procurement sophistication varies sharply between institutional fleet operators and fragmented contractor segments.
- Fleet Operators:Large logistics and transport companies with centralized maintenance programs negotiate long-term lubricant supply contracts bundled with fluid analysis subscriptions. These buyers leverage volume concentration to secure technical support and waste oil collection integration under National Environment Agency protocols.
- Logistics Providers:Third-party delivery specialists running mixed internal combustion and electric vehicle fleets require formulation flexibility across viscosity grades and electrification transition timelines.
- Construction Companies:Project-based procurement with seasonal demand spikes tied to infrastructure development cycles.
- Transportation Services:Smaller charter and private-hire operators with spot purchasing patterns and limited technical specification capability.
Procurement consolidation favors Fleet Operators; electrification uncertainty most affects Logistics Providers.
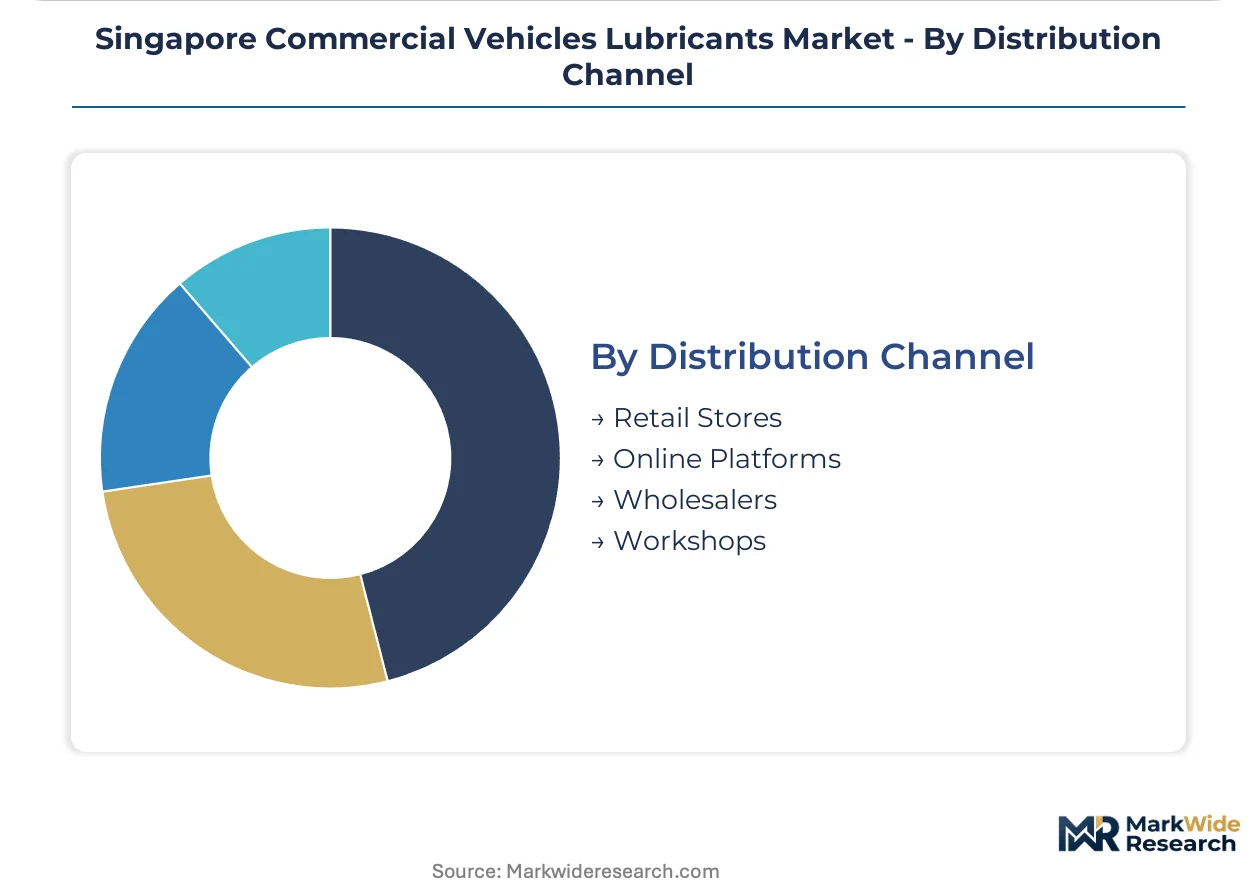
Distribution Channel:
Channel selection reflects trade-offs between technical support access, inventory velocity, and procurement administrative burden.
- Workshops:Authorized service bays with automotive trade association certification control placement for premium lubricant brands serving heavy duty truck and bus maintenance. These channels capture consolidated fleet spend through embedded technical support and compliance documentation for Land Transport Authority inspections.
- Wholesalers:Regional distributors with Jurong Island storage assets supply rapid-turnaround blending for large depot contracts and construction equipment fleets requiring bulk delivery.
- Retail Stores:Over-the-counter sales to independent operators and small fleet owners with limited technical specification requirements.
- Online Platforms:Emerging channel for standardized grades with delivery logistics challenges for bulk lubricant volumes.
Workshops hold the revenue concentration; Wholesalers gain share through depot contract specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore consumes far more commercial vehicle lubricants than it produces, importing base stocks from South Korea and the Middle East while Jurong Island blending facilities serve domestic fleet demand. This production-consumption gap shapes procurement vulnerability and supplier consolidation patterns.
Central Region
Jurong Island petrochemical cluster hosts the bulk of Singapore's lubricant blending capacity, with storage terminals supplying rapid-turnaround contracts to bus depots and heavy duty truck workshops. The National Environment Agency's waste oil tracking mandates concentrate re-refining logistics here. Fleet operators in the Tuas Port corridor source directly from these facilities to minimize delivery lead times.
Northern Region
Woodlands and Sembawang industrial zones anchor construction equipment fleet maintenance, driving hydraulic oil and grease demand from machinery serving infrastructure projects. The Land Transport Authority's emission compliance checkpoints along the Causeway route force tighter drain intervals for cross-border logistics vehicles operating here. Workshop chains with automotive trade association certification dominate lubricant placement in this corridor.
Eastern Region
Changi and Tampines logistics hubs concentrate last-mile delivery fleets serving e-commerce fulfillment networks, generating specialized demand for low-viscosity transmission fluids. The Land Transport Authority's Vehicle Emissions Scheme enforcement is strictest in this urbanized zone, rewarding high-performance lubricant formulations with preferential fleet procurement status. Fluid analysis subscription programs are penetrating fastest here due to downtime-sensitive operations.
Western Region
Tuas Port expansion and Jurong West industrial estates drive heavy duty truck lubricant throughput for container haulage and regional logistics routes. The Land Transport Authority's mandatory inspection regime for Class 4 and 5 vehicles forces workshop-direct procurement patterns. Wholesalers with Jurong Island storage assets capture depot contracts through same-day blending capabilities.
Singapore Commercial Vehicles Lubricants Market Competitive Landscape
Capital-heavy integrated oil majors compete with asset-light specialized blenders for positioning in Singapore's workshop-direct channels. The market structure tilts toward consolidation, with global suppliers commanding premium placement in certified service bays while local blenders compete on rapid turnaround and depot contract flexibility. Two strategic archetypes dominate: integrated petrochemical conglomerates with regional supply networks, and specialized lubricant formulators with tropical formulation expertise. Competitive intensity centers on fluid analysis bundling and waste oil collection integration under National Environment Agency protocols.
Among the integrated majors, Shell plc and BP Plc (Castrol) exemplify the full-service archetype, leveraging regional supply infrastructure to embed technical support into long-term fleet contracts. Fuchs Singapore and AP Oil occupy positions within the specialized tier, with the former representing technical support differentiation for construction equipment fleets and the latter exemplifying localized blending agility for rapid-turnaround depot requirements. Chevron Corporation and ExxonMobil Corporation anchor the scale-driven segment, while TotalEnergies and Idemitsu Kosan Co., Ltd. represent European and Japanese origin suppliers competing on formulation heritage. Sinopec Lubricant Singapore illustrates Chinese state-backed entry into the regional base oil and blending value chain.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Chevron Corporation |
| ExxonMobil Corporation |
| Shell plc |
| TotalEnergies |
| Fuchs Singapore |
| AP Oil |
| Sinopec Lubricant Singapore |
| Idemitsu Kosan Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Tribology formulation expertise concentrated among senior engineers in Singapore's Jurong Island petrochemical cluster widens labor-cost differentials between premium synthetic blends and economy mineral oils, compressing mid-tier pricing spreads as fleet operators consolidate procurement under technical service contracts.
Pricing Analysis
Margin tightening in workshop-direct channels reflects Land Transport Authority certification requirements that stratify lubricant placement by compliance tier. Three-tier pricing structure across premium synthetic, certified standard, and economy mineral levels separates Shell and BP's technical service bundles from AP Oil's rapid-turnaround depot contracts. Price differentiation hinges on fluid analysis subscription bundling and waste oil collection integration under National Environment Agency protocols. Small independent operators show highest price sensitivity, while fleet operators prioritize total cost of ownership over per-liter rates.
Supply Chain Analysis
Regional distribution centers on Jurong Island anchor hub-and-spoke patterns feeding workshop-direct channels across Singapore's four industrial corridors. Base oil supply draws from South Korea and Middle Eastern refiners, exposing blenders to freight volatility and currency fluctuation. Group II/III base stock dependency, additive package imports from European specialty chemical suppliers, and re-refining logistics under NEA tracking mandates constitute core input vulnerabilities. Single-source vulnerability concentrates in South Korean Group III supply for synthetic formulations. Distribution runs through automotive trade association-certified workshops controlling premium placement, with wholesalers capturing depot contracts through same-day blending agility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's commercial vehicle lubricants market functions as a cost-of-compliance arena where Land Transport Authority emission standards and National Environment Agency waste oil protocols erect regulatory moats favoring incumbents with integrated service networks and certification infrastructure.
For Market Incumbents: Deploy fluid analysis subscription bundling to lock fleet operators into multi-year technical service relationships, insulating against electric drivetrain volume erosion. Deepen backward integration into re-refining partnerships with NEA-accredited collectors, converting waste oil logistics from compliance burden into recurring revenue streams. Counter Sinopec's regional base oil expansion by accelerating tropical formulation R&D for humidity-optimized synthetics. For New Entrants and Emerging Players: Launch via construction equipment fleet specialization targeting Woodlands and Sembawang infrastructure corridors, where Fuchs Singapore's technical support model remains replicable at lower scale. Exploit bus depot rapid-turnaround requirements in Jurong Island proximity zones, where same-day blending capabilities outweigh brand heritage. Penetrate through hydraulic oil and grease segments before expanding into engine oil certification battles. For Investors and Strategic Acquirers: Re-rating potential sits with specialized formulators possessing tropical tribology expertise and NEA compliance infrastructure given electrification timeline uncertainty extending diesel fleet service lives. Acquisition targets should demonstrate Jurong Island storage assets, automotive trade association workshop relationships, and active fluid analysis program deployments. Monitor Land Transport Authority diesel phase-out announcements as the critical signal for lubricant volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fluid Analysis Subscription Bundling | Captures data-rich fleet relationships beyond commodity lubricant supply through Shell's integrated service network model. |
| Re-refining Partnership Expansion | Converts NEA waste oil mandates into closed-loop revenue streams with cradle-to-grave tracking compliance. |
| Tropical Formulation R&D Investment | Addresses humidity-specific degradation patterns in stop-start traffic conditions for synthetic low-viscosity grades. |
| Workshop Certification Acquisition | Secures preferential placement in automotive trade association-accredited service bays controlling heavy duty truck volume. |
| Jurong Island Storage Asset Expansion | Enables same-day blending capabilities for bus depot contracts and construction equipment rapid-turnaround requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet maintenance directors, workshop operations managers, lubricant procurement leads at logistics providers, and National Environment Agency compliance officers. Land Transport Authority emission standard documents, automotive trade association certification records, and Singapore Customs import statistics for base oil and additive categories provided quantitative foundations. Bottom-up volume modeling across product type, application, and distribution channel segments triangulated against top-down market sizing from petrochemical industry associations.
Granularity-level modeling distinguished synthetic versus mineral formulation tiers, workshop-direct versus wholesale channel economics, and fleet operator versus independent contractor procurement patterns across the analysis window. CAGRs derived from segment-level volume trajectories weighted by Land Transport Authority vehicle registration projections and electrification adoption curves. Forecast inputs incorporated e-commerce logistics fleet expansion rates, NEA waste oil protocol enforcement timelines, and tropical humidity degradation coefficients for drain interval modeling.
Electrification timeline revisions, base oil freight rate volatility, and automotive trade association certification rule changes are the dominant revision risks for lubricant volume assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
North America Automotive Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Angola Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
ASEAN Lubricants Market
Lubricants
Asia-Pacific Commercial Vehicles Lubricants Market