
 Global Grease Market | 2026-2036
Global Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grease Market Foresight
The EU Green Deal is broadening reformulation mandates across European grease procurement channels. ExxonMobil Corporation leverages its integrated base oil supply chain to sustain cost-competitive lithium complex output. Shell PLC anchors its position through maritime certification programs that dominate European port logistics. Fuchs Petrolub SE specializes in high-temperature polyurea grades for German automotive OEM supply chains.
Grease is a semi-solid lubricant comprising a base fluid, thickener, and additive package designed to reduce friction in rolling and sliding contacts under load. Its formulation typically uses metallic soaps or complex soaps at concentrations between 5% and 20% to create a gel-like matrix that resists leakage and extends relubrication intervals. Lithium complex greases retain the largest volume share due to their thermal stability and broad compatibility with industrial bearing systems. Polyurea greases are gaining share in electric motor applications where long life and low noise properties command premium positioning. Calcium complex formulations serve cost-sensitive construction equipment fleets across emerging industrial economies.
REACH compliance in Europe, EPA lubricant standards in the United States, and China's GB standards under SAMR oversight collectively determine thickener chemistry approvals and biodegradability thresholds for cross-border grease sales. These frameworks push manufacturers toward documented life-cycle assessments and restricted substance declarations as baseline market access requirements. Stakeholders must track evolving thickener classification rules across multiple jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
The EU F-Gas Regulation is forcing reformulation of thickener systems across European supply chains, compressing margins for legacy lithium soap producers while opening premium positioning for low-emission alternatives. Heavy machinery operators in Germany and construction fleets in India are simultaneously pulling specification-grade procurement in divergent directions.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal broadens reformulation requirements across member state procurement channels, accelerating demand for biodegradable base fluids and complex soap alternatives in industrial bearing applications.
- Electric motor expansion:Polyurea greases capture premium positioning in electric motor manufacturing where long-life and low-noise specifications command price premiums from OEM supply chains.
- Indian industrial corridor concentration:Demand clusters around Mumbai and Pune industrial zones as automotive and construction equipment manufacturers localize grease procurement to reduce import dependency.
Market Restraints
- Lithium hydroxide cost volatility:Battery sector competition for lithium hydroxide elevates input costs for lithium complex grease producers, squeezing margins on volume-grade industrial formulations.
- REACH compliance friction:ECHA substance evaluation timelines delay thickener chemistry approvals, extending reformulation cycles and freezing product line expansions for cross-border European sales.
- Mineral oil substitution pressure:Synthetic ester and vegetable oil base fluids displace conventional mineral oils in environmentally sensitive applications, requiring capital-intensive production line conversions.
Strategic Opportunities
- Maritime certification expansion:European port logistics and offshore wind installation vessels drive demand for VGP-compliant biodegradable greases with extended service intervals in saltwater environments.
- China GB standard alignment:SAMR oversight of grease quality standards under GB frameworks creates entry pathways for compliant foreign producers in high-temperature industrial segments.
- Predictive maintenance integration:IoT sensor deployment in German automotive OEM supply chains enables condition-based relubrication services, shifting revenue from product sales to performance contracts.
Industry Challenges
- Thickener chemistry expertise gap:Formulation knowledge concentrated among retiring specialists in European and Japanese laboratories constrains R&D throughput for next-generation polyurea and calcium sulfonate grades.
- Multi-jurisdiction certification complexity:Parallel EPA lubricant standards, REACH registrations, and China GB compliance requirements extend product launch timelines and inflate documentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grease Market |
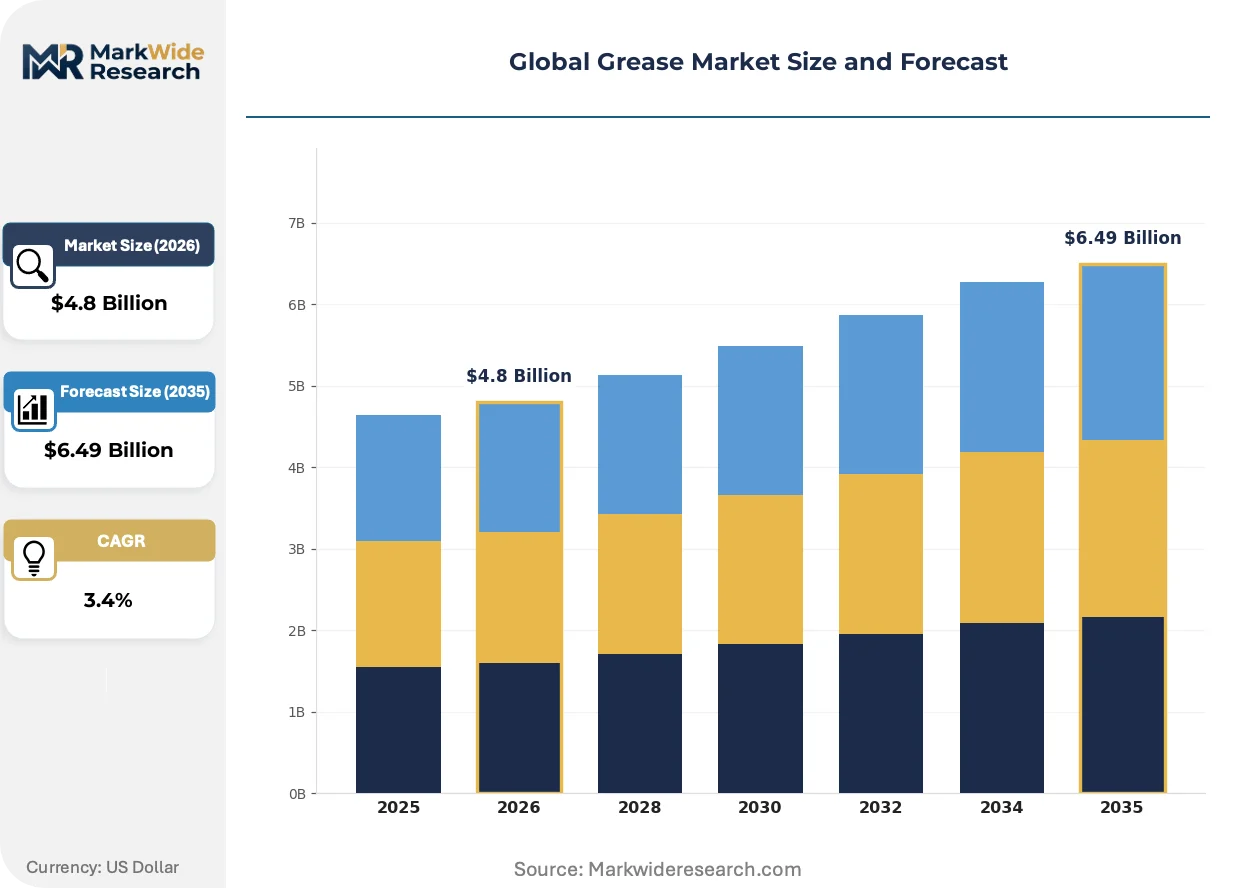
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium, Calcium Complex, Polyurea, Aluminum Complex, Bentone, Clay Application: Heavy Machinery, Bearings, Construction Equipment, Marine Engines, Agricultural Equipment, Railways End User Industry: Automotive OEMs, Aerospace Manufacturers, Mining Operations, Marine Services, Power Generation Units, Metalworking Firms Packaging Type: Tins, Cartridges, Pails, Drums, Aerosols, Bulk Containers |
| Companies Covered | ExxonMobil Corporation, Shell PLC, TotalEnergies SE, Chevron Corporation, BP PLC, Fuchs Petrolub SE, Valvoline Inc., China Petroleum & Chemical Corporation, Klüber Lubrication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grease Market Shifts & Advancements
Reformulation pressures are fragmenting competitive positioning between legacy metallic soap producers and specialty thickener innovators. Technology convergence with condition monitoring systems and regulatory alignment across Atlantic and Pacific jurisdictions are compressing product development cycles.
Polyurea thickener technology is consolidating market share in electric motor and sealed bearing applications where thermal stability and oxidative resistance extend relubrication intervals beyond lithium complex capabilities. German automotive OEMs and Japanese precision equipment manufacturers are accelerating adoption of high-purity polyurea grades. This consolidation is compressing demand for conventional lithium soaps in premium industrial segments.
REACH authorization requirements under ECHA oversight are restricting certain metallic soap precursors and pushing manufacturers toward documented life-cycle assessments as baseline market access requirements. Industrial grease producers face substance evaluation delays for novel thickener chemistries. The German automotive supply chain is responding by pre-qualifying alternative complex soap formulations ahead of regulatory deadlines.
Buyer concentration among heavy machinery fleet operators is shifting procurement toward multi-year supply agreements with embedded technical service support. Distributor networks in European port logistics and Indian construction corridors are losing volume to direct manufacturer relationships. This pattern is most visible in Germany where specification-grade procurement now routes through centralized technical purchasing functions rather than regional distributors.
Global Grease Market Segmentation
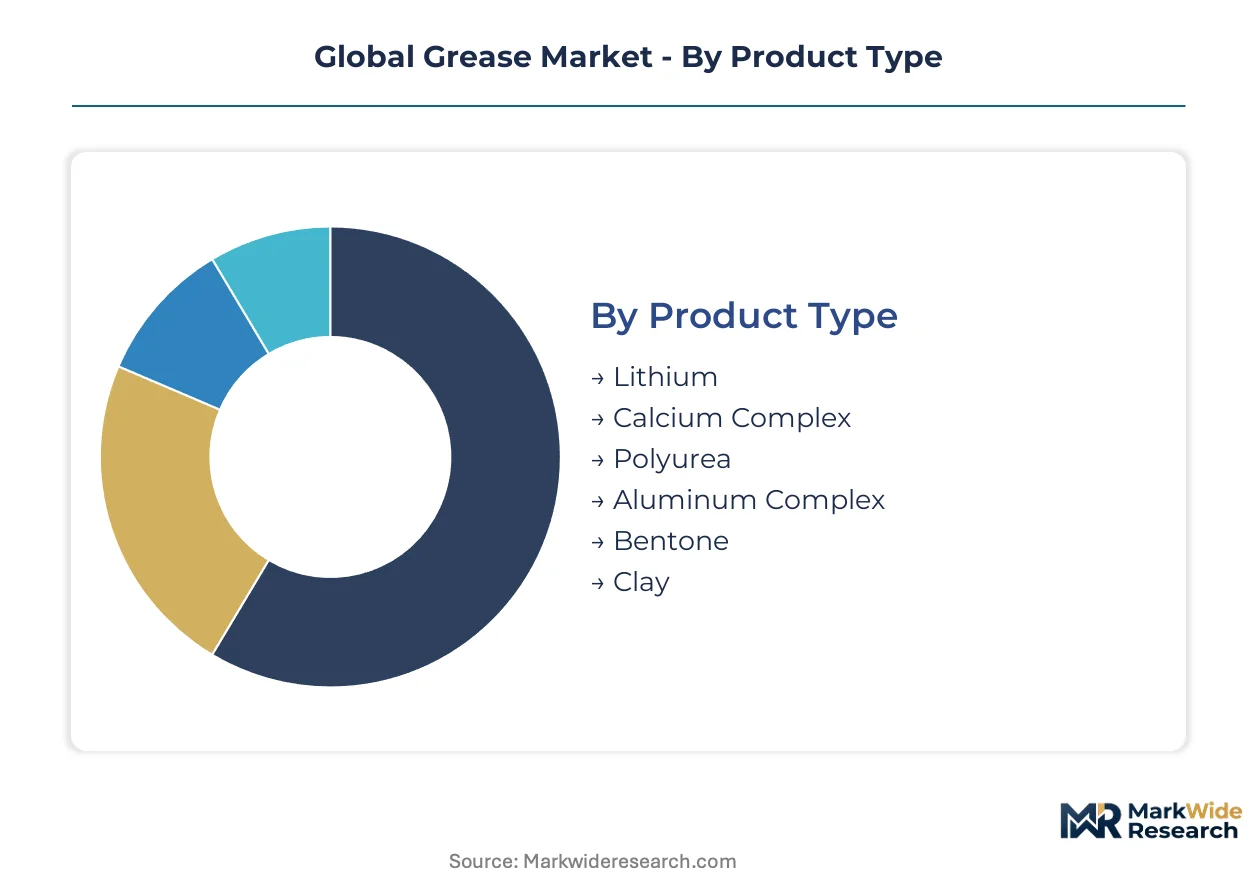
Grease formulation diversity creates distinct procurement channels where thickener chemistry, application severity, and packaging format each drive separate pricing architectures. Specification-grade buyers segment supply chains by thermal performance and regulatory compliance rather than commodity lubricant metrics.
Product Type:
Procurement decisions pivot on operating temperature range and thickener compatibility with existing inventory systems.
- Lithium:Metallic soap formulations at 5-20% concentration deliver gel-like matrices for general industrial bearings. Demand concentrates in German automotive OEM supply chains where thermal stability commands specification-grade procurement. Battery sector competition for lithium hydroxide elevates input costs and compresses margins on volume formulations.
- Polyurea:Non-soap thickeners enable oxidative resistance beyond lithium complex capabilities in sealed electric motor bearings. Japanese precision equipment manufacturers and German automotive OEMs accelerate adoption of high-purity grades where long-life specifications justify premium positioning. REACH authorization delays for novel chemistries extend reformulation cycles.
- Calcium Complex:Cost-sensitive construction equipment fleets across Indian industrial corridors favor these formulations for moderate-load applications.
- Aluminum Complex:High-temperature stability serves steel mill and foundry operations in thermally aggressive environments.
- Bentone:Clay-based thickeners provide structural stability for specialty applications requiring extreme pressure resistance.
- Clay:Inorganic thickeners suit applications where soap-based chemistry faces compatibility constraints with certain base fluids.
Volume sits with lithium; growth tilts toward polyurea.
Application:
Severity of operating environment determines specification grade and relubrication interval requirements.
- Heavy Machinery:Mining excavators and earthmoving equipment demand extreme-pressure additives and water washout resistance. German fleet operators expand specification-grade procurement through centralized technical purchasing functions. EU F-Gas Regulation pushes reformulation toward biodegradable base fluids in European procurement channels.
- Marine Engines:Saltwater exposure and extended service intervals require VGP-compliant biodegradable formulations with corrosion inhibitors. European port logistics and offshore wind installation vessels drive demand for certified products. Maritime certification programs dominate procurement specifications in Rotterdam and Hamburg.
- Bearings:Rolling and sliding contact applications prioritize leakage resistance and extended relubrication intervals.
- Construction Equipment:Indian construction corridors around Mumbai and Pune localize procurement to reduce import dependency.
- Agricultural Equipment:Seasonal operating patterns favor cost-optimized calcium complex formulations with adequate water resistance.
- Railways:Wheel flange and track lubrication systems require specialized adhesion properties and controlled dispensing compatibility.
Heavy machinery captures the largest procurement volumes; marine applications are climbing the fastest on regulatory compliance mandates.
End User Industry:
Customer technical sophistication determines service bundling and contract structure preferences.
- Automotive OEMs:German supply chains pre-qualify alternative complex soap formulations ahead of ECHA regulatory deadlines. Condition-based relubrication services shift revenue from product sales to performance contracts as IoT sensor deployment accelerates.
- Marine Services:Offshore operators and port logistics providers mandate biodegradable certifications with documented life-cycle assessments.
- Aerospace Manufacturers:Extreme temperature specifications and material compatibility constraints limit approved supplier lists.
- Mining Operations:Remote site locations prioritize bulk packaging and extended service intervals to minimize maintenance labor.
- Power Generation Units:Wind turbine and thermal plant operators balance synthetic ester costs against mineral oil substitution pressures.
- Metalworking Firms:Process fluid compatibility and chip removal efficiency influence grease selection in machining centers.
Automotive OEMs generate the most specification-grade volume; marine services are gaining share fastest on environmental compliance requirements.
Packaging Type:
Scale of consumption and dispensing automation determine format economics.
- Drums:180-200kg steel containers serve high-volume manufacturing facilities with automated dispensing systems. German automotive plants and Indian industrial zones standardize on drum supply for production line integration. Direct manufacturer relationships are displacing distributor networks in these procurement channels.
- Cartridges:400g tubes enable precise application in maintenance workshops and field service operations. Construction fleets and agricultural equipment dealers favor cartridge formats for controlled dispensing and inventory management.
- Tins:Small-format packaging serves retail aftermarket and specialty applications requiring corrosion-protected storage.
- Pails:Intermediate volumes suit mid-sized maintenance shops without drum handling infrastructure.
- Aerosols:Spray application formats target precision lubrication in inaccessible bearing locations.
- Bulk Containers:Tanker and tote deliveries minimize packaging waste for largest consumers with on-site storage.
Drum format dominates manufacturing procurement; cartridge growth accelerates with fleet maintenance outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Pune anchor industrial grease procurement in India's western manufacturing belt. German automotive OEM supply chains drive specification-grade demand through centralized technical purchasing. Chinese industrial clusters under SAMR oversight reshape thickener chemistry approvals for cross-border sales.
Germany
Automotive OEM supply chains in Stuttgart and Munich pre-qualify alternative complex soap formulations ahead of ECHA regulatory deadlines. The EU F-Gas Regulation forces thickener system reformulation across Bavarian and Baden-Württemberg industrial zones. Hamburg port logistics drive maritime certification procurement for offshore wind installation vessels.
United States
EPA lubricant standards govern thickener chemistry approvals for industrial bearing applications across Great Lakes manufacturing corridors. The Inflation Reduction Act accelerates synthetic ester base fluid adoption in power generation and electric motor manufacturing. Houston petrochemical complexes supply integrated base oil streams to regional grease compounders.
China
GB standards under SAMR oversight determine market access for high-temperature industrial grease segments in Yangtze River Delta manufacturing zones. Dual carbon goals push reformulation toward biodegradable base fluids in Shanghai and Jiangsu province chemical parks. Sinopec's integrated refineries anchor domestic lithium complex supply chains.
India
Automotive and construction equipment manufacturers localize procurement around Mumbai and Pune industrial corridors to reduce import dependency. BIS quality standards govern thickener classification for domestic manufacturing. Maharashtra state industrial policy attracts grease blending capacity to serve western India demand clusters.
Japan
Precision equipment manufacturers in Nagoya and Osaka industrial zones accelerate adoption of high-purity polyurea grades. METI industrial standards govern electric motor bearing lubricant specifications. JIS certification requirements limit approved supplier lists for long-life sealed bearing applications.
Global Grease Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive base oil supply. Three tiers define the landscape: global oil majors leveraging refinery integration, regional specialists commanding premium positioning in certified applications, and national oil companies scaling domestic volume. Capacity expansion and portfolio diversification toward biodegradable formulations represent the dominant competitive vectors.
Among integrated petrochemical majors, ExxonMobil Corporation and Shell PLC exemplify the refinery-anchored archetype with upstream control over base fluid economics. Fuchs Petrolub SE occupies a specialist position within the German automotive supply chain tier. These three entities represent distinct strategic postures: scale-driven vertical integration, maritime certification dominance, and specification-grade technical service bundling respectively.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell PLC |
| TotalEnergies SE |
| Chevron Corporation |
| BP PLC |
| Fuchs Petrolub SE |
| Valvoline Inc. |
| China Petroleum & Chemical Corporation |
| Klüber Lubrication |
| Others |
Supply & Pricing Matrix
German automotive OEM specification-grade procurement is forcing thickener chemistry reformulation across European supply chains, compressing margins on legacy lithium complex formulations while elevating price premiums for REACH-compliant polyurea alternatives. Battery sector competition for lithium hydroxide feeds directly into input cost volatility, reshaping how compounders structure long-term offtake agreements with integrated base oil suppliers.
Pricing Analysis
Extended bearing life guarantees anchor value-based pricing for polyurea grades in electric motor applications, with Japanese precision equipment manufacturers and German automotive OEMs paying premiums tied to relubrication interval performance rather than per-kilogram commodity metrics. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade polyurea from volume lithium complex and cost-optimized calcium complex tiers. Pricing pressure stems from lithium hydroxide cost volatility as battery manufacturers divert chemical feedstock supply. Construction equipment fleets in India exhibit highest price sensitivity, while marine certification programs in European ports demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore anchor hub-and-spoke patterns for maritime-certified grease delivery to offshore wind installation vessels and port logistics operators. Manufacturing concentration in Germany, China, and the United States feeds from integrated petrochemical complexes with captive base oil production. Raw material dependencies on lithium hydroxide, 12-hydroxystearic acid, and polyisocyanate precursors create single-source vulnerability for specialty thickener formulations. Distribution runs through direct manufacturer relationships displacing traditional distributor networks in high-volume automotive and heavy machinery procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
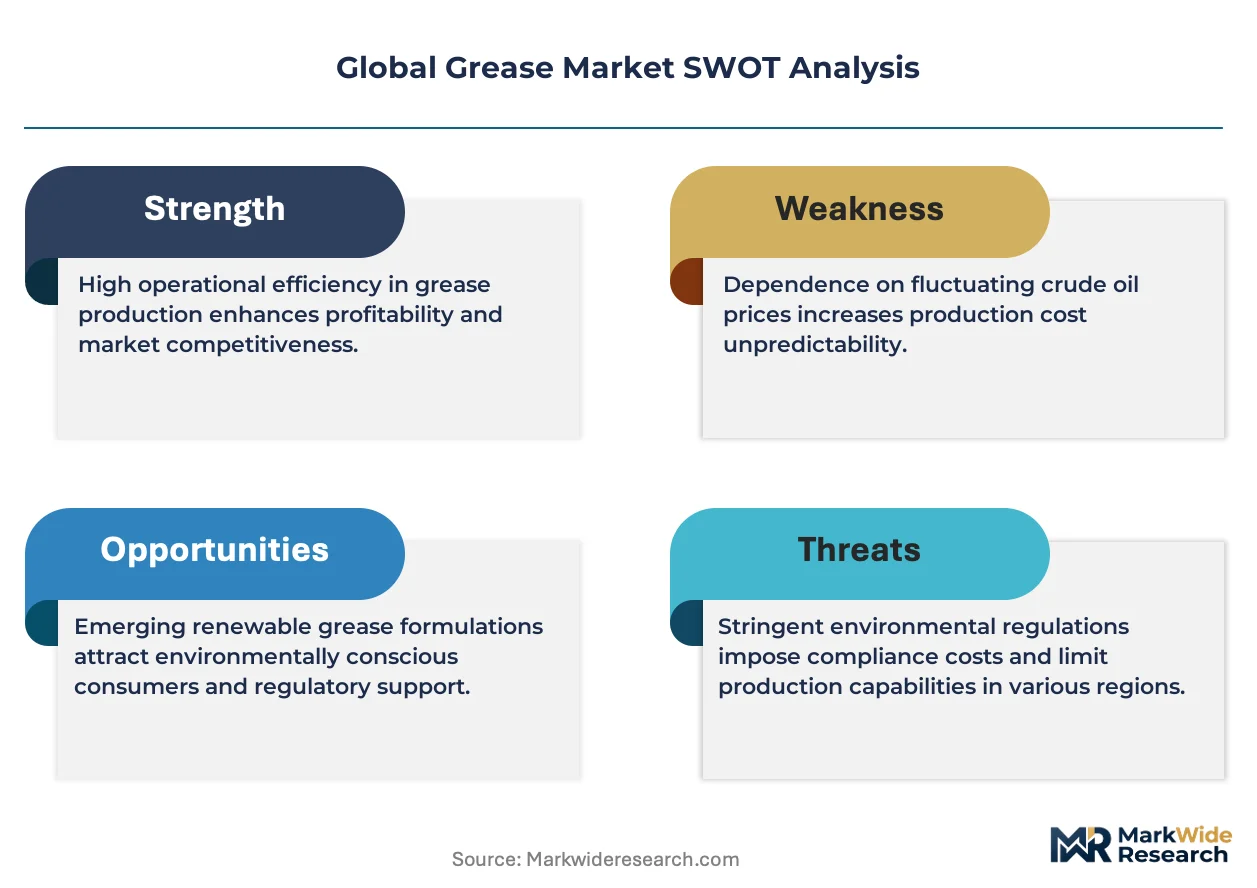
The Global Grease Market is consolidating around regulatory compliance capabilities and integrated supply chain control, with EU F-Gas Regulation and REACH authorization timelines forcing sub-scale compounders toward exit or acquisition. Reformulation cost burdens and multi-jurisdiction certification complexity favor players with captive base oil supply and established ECHA pre-qualification relationships.
For Market Incumbents: Deploy backward integration into synthetic ester base fluid production to defend margin position against mineral oil substitution pressure and lithium hydroxide cost volatility. Expand polyurea thickener capacity in German automotive corridor to capture specification-grade procurement shifting from lithium complex. Pre-qualify alternative complex soap formulations ahead of ECHA substance evaluation deadlines to freeze out reformulation-lagged competitors. For New Entrants and Emerging Players: Polyurea thickener technology for Indian electric motor manufacturing offers lowest barrier to specification-grade market entry, with Mumbai-Pune industrial corridor localization requirements creating procurement preference for domestic blending capacity. Target construction equipment fleet operators in Maharashtra state with cost-optimized calcium complex formulations bundled with technical service support. Pursue direct technical purchasing relationships rather than distributor channel penetration to bypass entrenched supply agreements. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with established REACH registrations and automotive OEM supply chain relationships over greenfield capacity builds. Long-term viability rests on regulatory compliance asset value appreciating as authorization timelines extend and reformulation costs escalate. Watch ECHA substance evaluation acceleration as inflection signal for distressed acquisition opportunities among legacy metallic soap producers facing compliance deadline pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Production | Captive base fluid supply defends margins against mineral oil substitution mandates under EU Green Deal. |
| Polyurea Thickener Capacity Expansion | German automotive OEM pre-qualification programs favor suppliers with demonstrated high-purity grade production. |
| REACH Pre-Qualification Investment | Early ECHA engagement freezes competitor product line expansions and extends certification timelines for laggards. |
| Direct Technical Purchasing Relationships | Centralized procurement functions in heavy machinery fleets displace distributor networks and capture specification-grade volume. |
| Maritime Certification Program Alignment | VGP-compliant biodegradable formulations command premium positioning in Rotterdam and Hamburg port logistics. |
Research Methodology
Trade databases, ECHA substance registration filings, and automotive OEM technical specifications formed the secondary backbone, cross-referenced with primary interviews involving grease formulators, procurement leads at German heavy machinery operators, and distribution channel partners across European port logistics. Plant managers at Indian construction equipment fleets and technical R&D directors at specialty thickener suppliers provided operational validation. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Historical trendline analysis of thickener chemistry adoption rates, base oil price indices, and regulatory compliance cost trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include thickener type, application severity grade, end-use industry technical sophistication, packaging format automation level, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating electric motor manufacturing expansion and maritime certification penetration rates.
Several conditions sit outside the modeled scope, including unannounced ECHA substance evaluation accelerations, battery sector lithium hydroxide demand shocks, and geopolitical disruptions to integrated petrochemical supply. Forecasts reflect stated assumptions on regulatory timeline adherence and raw material cost normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Biolubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Indonesia Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Jordan Lubricants Market