
 Poland Lubricants Market | 2026-2036
Poland Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Lubricants Market Analytics
Market Context
Central European refining capacity is narrowing as regional upgraders prioritize Group II and Group III base oil output over fuel production. PKN ORLEN leverages its Płock refinery complex to anchor domestic supply chains for automotive and industrial lubricants. Shell plc competes through branded service networks that extend across Polish OEM dealerships and independent workshops. FUCHS sustains technical partnerships with machinery builders in the Silesian mining and metallurgy belt.
Technical Definition and Segment Structure
Poland lubricants comprise formulated oils and greases engineered from mineral, synthetic, or bio-based base stocks blended with performance additives to reduce friction, dissipate heat, and prevent wear in mechanical systems; typical formulations specify viscosity grades from ISO VG 32 to VG 680 and operate across temperature ranges of minus forty to plus one hundred fifty degrees Celsius. Engine oil dominates product type revenue due to Poland's passenger vehicle parc and commercial fleet renewal cycles, while hydraulic oil captures industrial machinery demand tied to automation retrofits in Polish manufacturing plants. Grease trails in volume but occupies higher margin pools in aerospace and precision bearing applications where extended service intervals command premium pricing.
Regulatory Framework and Outlook
Polish lubricant marketers navigate EU REACH chemical registration requirements, the F-Gas Regulation limiting fluorinated greenhouse gas content in specialty formulations, and national waste oil recovery mandates administered under extended producer responsibility frameworks. BIS-equivalent Polish Committee for Standardization (PKN) adoption of EN and ISO lubricant specifications shapes product labeling and import compliance at Baltic port entry points. Stakeholders must monitor EU taxonomy alignment for bio-based lubricant claims and decide whether to invest in domestic re-refining capacity or rely on German and Benelux base oil supply integration.
Market Dynamics
Polish lubricant demand pivots on the collision between EU REACH chemical phase-outs and the Silesian industrial corridor's sustained appetite for heavy-duty hydraulic fluids. Refinery capacity reallocation toward Group III base oils tightens domestic supply chains.
Growth Catalysts
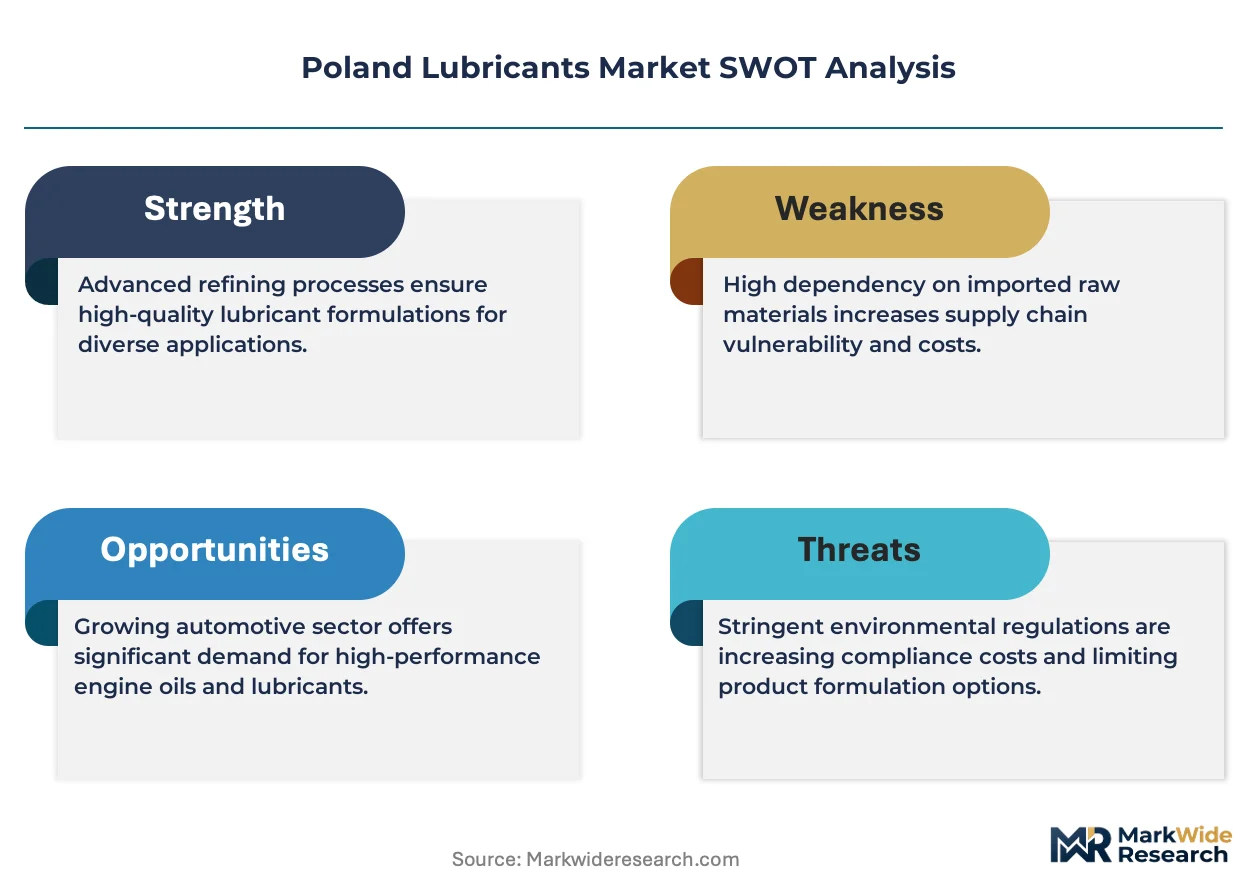
- EU F-Gas Regulation:Fluorinated greenhouse gas restrictions are accelerating reformulation investments toward biodegradable ester base stocks in specialty compressor oils.
- Automotive clusters:Bielsko-Biała and Poznań manufacturing corridors sustain OEM fill demand for high-performance engine oils through passenger vehicle and commercial fleet renewal cycles.
- Steelworks automation:Silesian metallurgy operations are retrofitting hydraulic systems, extending drain intervals and elevating synthetic hydraulic oil consumption.
Market Restraints
- Base oil import dependency:Domestic Group II and Group III supply from Płock cannot cover formulation needs, forcing reliance on German and Benelux refinery output subject to Rhine logistics disruptions.
- REACH registration costs:Small and mid-size blenders face disproportionate compliance burdens for novel additive chemistries, consolidating formulation innovation among capital-rich multinationals.
- Extended drain intervals:Synthetic lubricant durability improvements compress total addressable volume in mature automotive segments despite value-per-liter gains.
Strategic Opportunities
- Bio-based claims alignment:EU taxonomy classification for renewable content creates premium positioning potential for rapeseed-derived base stocks in agricultural and municipal fleet applications.
- Re-refining infrastructure:Extended producer responsibility mandates for waste oil recovery incentivize domestic collection-to-base-oil processing investments, closing circular supply loops.
- Wind energy expansion:Baltic Sea offshore turbine installations generate nascent demand for synthetic gear oils and greases in generator bearing applications.
Industry Challenges
- Additive chemist scarcity:Formulation expertise in sulfur-phosphorus extreme pressure chemistry is concentrating among retiring specialists, constraining indigenous product development.
- PKN standard harmonization:Polish Committee for Standardization adoption cycles for revised EN lubricant specifications lag implementation deadlines, delaying product launches.
- Legacy equipment compatibility:Mining and steelworks machinery with 1980s sealing materials requires costly backward-compatible formulations, fragmenting SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Lubricants Market |
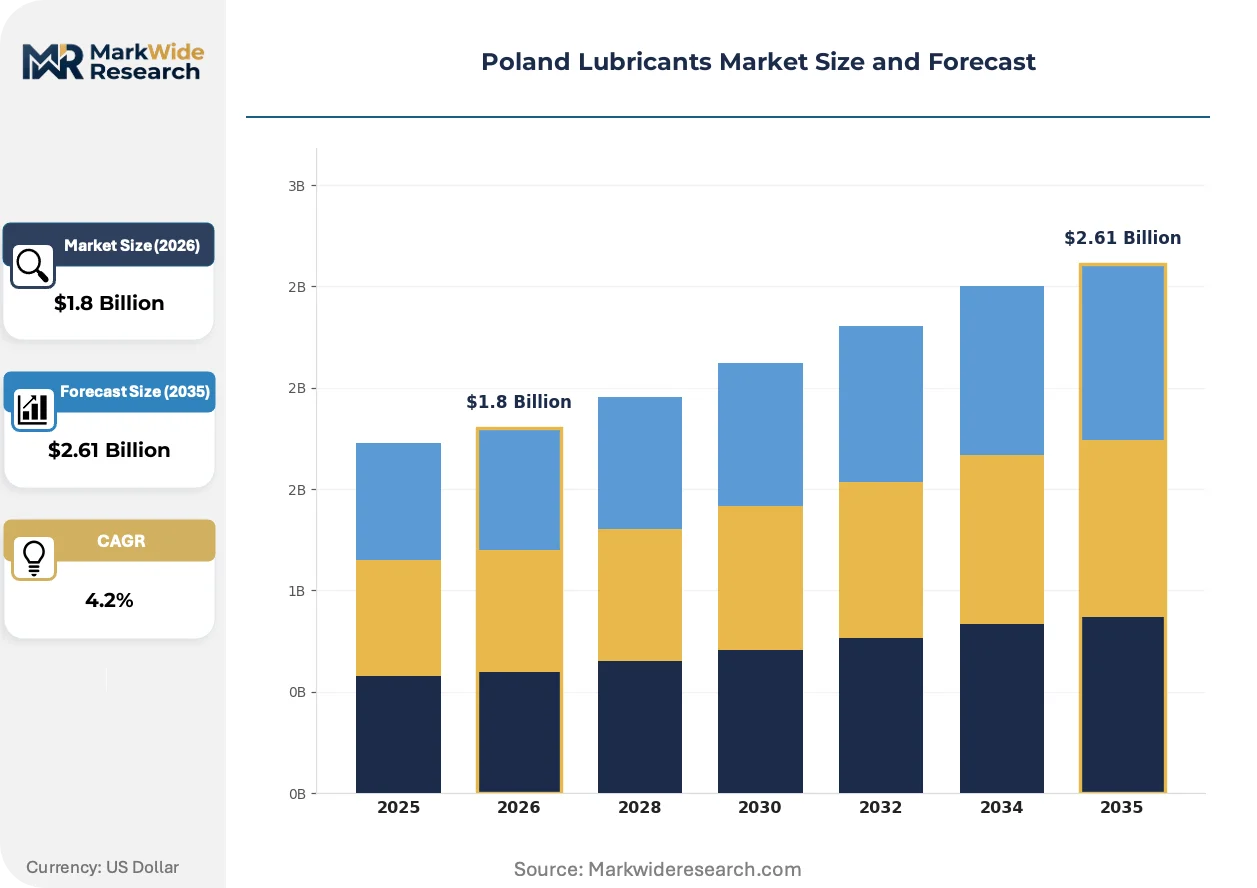
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease Application: Automotive, Industrial Machinery, Marine, Aerospace Market Segment: Commercial, Residential, Agricultural, Power Generation Distribution Channel: Retail Stores, Online Sales, Distributors, Wholesalers |
| Companies Covered | BP Plc (Castrol), FUCHS, Shell plc, Motul, Liqui Moly, TotalEnergies SE, PKN ORLEN, Eurol, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Lubricants Market Evolving Landscape
Digital lubricant monitoring systems are compressing traditional oil analysis business models while EU chemical regulations force molecular-level reformulation. Polish blenders must simultaneously navigate biodegradability mandates and industrial equipment legacy constraints.
Cloud-based oil condition sensors paired with machine learning diagnostics are virtualizing the preventive maintenance value chain. Mining operators in Upper Silesia are piloting continuous viscosity and particulate monitoring, bypassing laboratory turnaround delays. Equipment OEMs are capturing lubricant decision authority, compressing independent workshop influence.
Polish Committee for Standardization adoption of EN 16807 bio-lubricant specifications is mandating aquatic toxicity testing for hydraulic fluids used in sensitive watersheds. Formulators serving municipal water management and inland shipping must now document biodegradation rates and bioaccumulation profiles. Agricultural machinery distributors are prioritizing certified products to preempt regional environmental enforcement actions.
Fleet maintenance managers are consolidating lubricant procurement through integrated service contracts bundling fluid supply, condition monitoring, and waste oil recovery. Independent workshops in Poznań and Kraków are losing share to OEM-branded service networks offering lifecycle cost guarantees. Municipal bus operators are piloting total fluid management agreements, transferring inventory risk to suppliers.
Poland Lubricants Market Segmentation
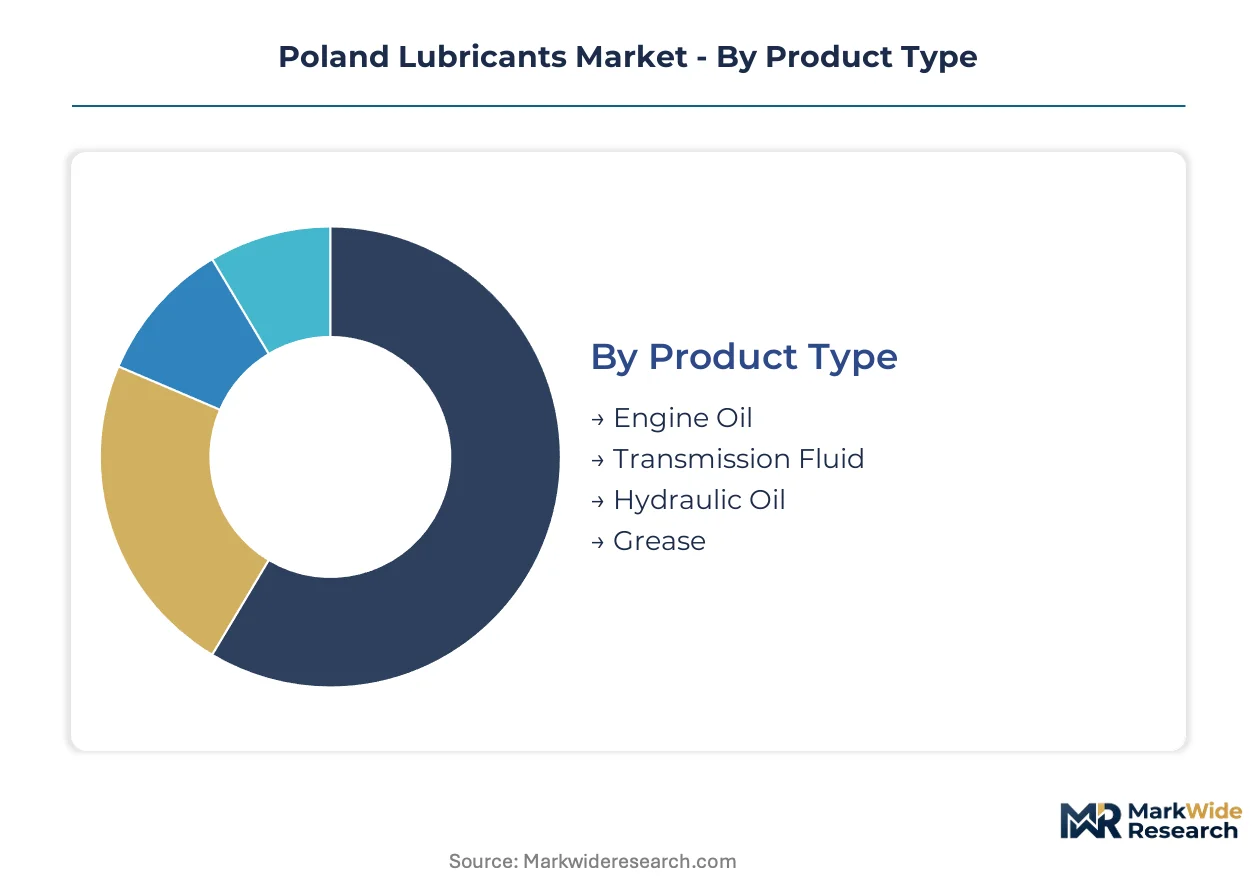
Poland lubricant procurement patterns diverge sharply between automotive OEM fill specifications and industrial maintenance purchasing. Segment boundaries are hardening as equipment manufacturers capture decision authority through integrated service contracts.
Product Type:
Cost tier differentiation separates commodity mineral formulations from premium synthetic and bio-based alternatives commanding measurable price premiums.
- Engine Oil:Formulations span SAE viscosity grades from 0W-20 to 15W-40, blending Group II/III base stocks with detergent-dispersant additive packages. Passenger vehicle parc renewal in Warsaw and Kraków metropolitan zones sustains volume, while extended drain interval specifications compress per-vehicle consumption despite value-per-liter gains.
- Hydraulic Oil:ISO VG 32 to VG 68 grades dominate, formulated with anti-wear zinc dialkyldithiophosphate chemistry for high-pressure systems. Silesian steelworks automation retrofits concentrate demand for fire-resistant and biodegradable ester variants in continuous casting and rolling mill circuits.
- Transmission Fluid:ATF and gear oil specifications service manual and automated transmission rebuild markets.
- Grease:Lithium complex and polyurea thickeners target bearing applications with extended relubrication intervals.
Engine oil commands the established base. The steepest expansion runs through hydraulic oil.
Application:
Application segmentation tracks equipment utilization intensity and lubricant specification complexity across mobility and fixed asset categories.
- Automotive:Light-duty passenger vehicles, commercial trucking fleets, and agricultural machinery each impose distinct OEM approval requirements. Poznań and Bielsko-Biała manufacturing clusters anchor OEM fill demand, while independent workshops in Łódź and Wrocław service aftermarket replacement cycles.
- Industrial Machinery:Metalworking, plastics processing, and materials handling equipment specify lubricants by operating temperature and contamination exposure. Upper Silesian mining equipment operates under severe load conditions requiring sulfur-phosphorus extreme pressure formulations.
- Marine:Inland shipping on Vistula and Oder waterways drives demand for environmentally acceptable lubricants meeting EN 16807 biodegradability thresholds.
- Aerospace:Precision bearing and actuator applications impose narrow viscosity-temperature performance windows.
Automotive absorbs the dominant volume share. Industrial machinery is gaining share fastest.
Market Segment:
Customer type segmentation distinguishes procurement scale, specification authority, and contract structure across end-use sectors.
- Commercial:Fleet operators and industrial facilities negotiate multi-year total fluid management agreements bundling supply, monitoring, and waste recovery. Municipal bus operators in Gdańsk and Szczecin are piloting outcome-based contracts transferring inventory risk to lubricant suppliers.
- Agricultural:Seasonal equipment utilization patterns favor lower-cost mineral formulations, though EU taxonomy alignment is creating pull for certified bio-based alternatives in rapeseed-growing regions.
- Residential:Do-it-yourself vehicle maintenance concentrates in retail channels with price-sensitive brand selection.
- Power Generation:Combined cycle gas turbine and wind turbine installations specify synthetic lubricants for thermal stability and extended service intervals.
Commercial segment controls the revenue base. Power generation shows the steepest upward trajectory.
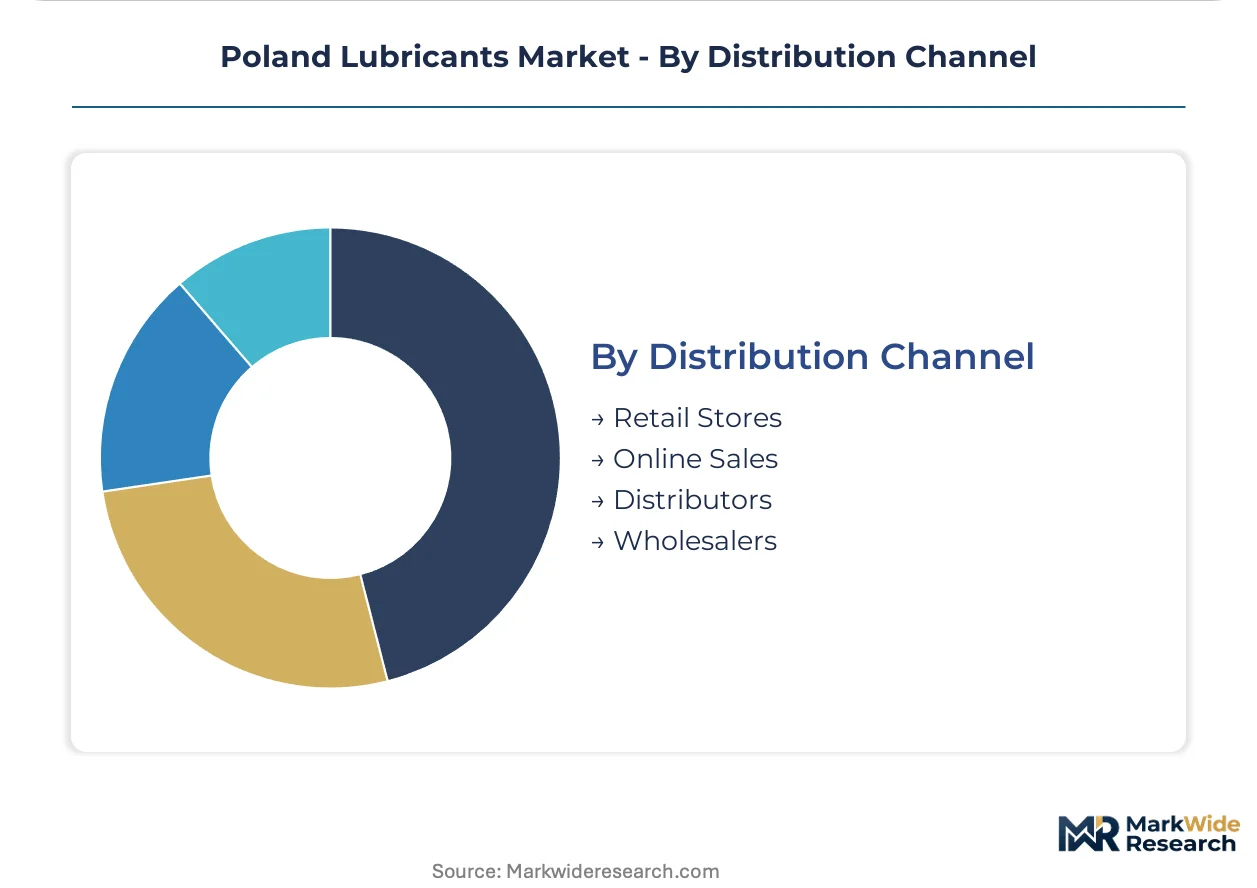
Distribution Channel:
Supply concentration patterns reflect inventory holding economics and technical service requirements across route-to-market alternatives.
- Distributors:Technical specialists maintain blending and warehousing infrastructure close to Silesian industrial demand centers, offering just-in-time delivery and on-site fluid analysis. FUCHS and regional independents compete through application engineering support.
- Retail Stores:Hypermarket chains and dedicated automotive parts outlets service DIY maintenance with branded packaged goods. Shell plc and PKN ORLEN maintain shelf presence through national retail partnerships.
- Online Sales:E-commerce platforms are capturing share in standardized product categories with transparent pricing and direct-to-workshop delivery.
- Wholesalers:Volume aggregators supply smaller independent workshops with private-label and unbranded alternatives.
Distributors retain the structural high ground. Online sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors lubricant formulation standards across Poland's industrial zones. The Polish Committee for Standardization adopts EN specifications that govern import compliance at Baltic ports. Regional demand concentrates in manufacturing clusters where automotive OEMs and heavy industry coexist.
Masovian Voivodeship
Warsaw's metropolitan vehicle parc sustains passenger car engine oil consumption through independent workshop networks. PKN ORLEN's downstream operations anchor national supply chain coordination from Płock. The region's logistics corridors channel German and Benelux base oil imports via Baltic Sea terminals.
Silesian Voivodeship
Upper Silesian steelworks and mining operations generate concentrated demand for extreme-pressure hydraulic fluids and industrial greases. EU F-Gas Regulation compliance pressures reformulation of specialty compressor lubricants used in underground machinery. Katowice-Gliwice industrial corridor hosts technical service partnerships between blenders and machinery OEMs.
Greater Poland Voivodeship
Poznań automotive manufacturing clusters drive OEM fill specifications for high-performance transmission fluids. Extended drain interval requirements from vehicle manufacturers elevate synthetic blend penetration. Regional distributors maintain just-in-time inventory for assembly plant supply contracts.
Lesser Poland Voivodeship
Kraków's commercial fleet density supports aftermarket engine oil turnover through integrated service networks. Municipal bus operators pilot total fluid management agreements transferring inventory risk to suppliers. The Vistula River corridor generates demand for EN 16807-compliant biodegradable hydraulic fluids in inland shipping applications.
Pomeranian Voivodeship
Gdańsk and Szczecin port infrastructure enables Baltic base oil import flows subject to Rhine logistics disruptions. Offshore wind turbine installations in Baltic Sea zones create nascent demand for synthetic gear oils. Ship repair yards specify marine lubricants meeting environmental acceptability standards for sensitive watershed operations.
Poland Lubricants Market Competitive Landscape
Capability concentration sits with multinational formulators possessing REACH registration portfolios; scale advantage sits with integrated refiners controlling domestic base oil supply. The market structures around three archetypes: integrated national oil companies with captive refining, international lubricant specialists with technical service networks, and regional distributors with application engineering proximity. Consolidation pressure operates through additive chemistry registration costs that disadvantage smaller blenders. Competitive moves center on strategic partnerships with machinery OEMs and circular economy investments in waste oil re-refining infrastructure.
Among integrated energy majors, PKN ORLEN anchors domestic supply chain control through Płock refinery output. Shell plc and BP Plc occupy positions as international formulators with branded service network penetration across Polish OEM dealerships. FUCHS represents the technical specialist archetype through machinery builder partnerships in Silesian mining and metallurgy applications.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| FUCHS |
| Shell plc |
| Motul |
| Liqui Moly |
| TotalEnergies SE |
| PKN ORLEN |
| Eurol |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
Tight Group III base oil capacity at PKN ORLEN's Płock complex drives parallel supplier behavior and pricing posture across Polish lubricant markets. Domestic blenders face margin compression when utilization spikes force greater reliance on German and Benelux refinery output subject to Rhine logistics volatility.
Pricing Analysis
Geographic price spreads between Baltic port imports and domestic Płock-sourced formulations widen during Rhine navigation disruptions. Three-tier pricing structure across premium synthetic, mid-grade Group III, and economy mineral levels separates OEM fill specifications from aftermarket commodity volumes. Price differentiation rests on REACH registration status and EN specification compliance rather than brand alone. Cost compression in the mineral tier is intensifying because independent workshops consolidate procurement through distributor private-label programs.
Supply Chain Analysis
Contract blending concentration sits with FUCHS and regional technical specialists maintaining compounding infrastructure near Katowice-Gliwice industrial corridors. Geographic supply concentration draws from Germany, the Netherlands, and domestic Płock output for base stocks; additive packages hinge on Belgian and French chemical manufacturing. Single-source vulnerability runs through zinc dialkyldithiophosphate anti-wear chemistry concentrated among retiring specialist formulators. Distribution runs through technical distributors holding just-in-time inventory for Silesian steelworks and Poznań automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland lubricants represent an early-cycle expansion story as EU F-Gas Regulation compliance forces reformulation investments that displace legacy mineral formulations with premium synthetic and bio-based alternatives.
For Market Incumbents: Pre-empt additive chemistry consolidation by securing backward integration into sulfur-phosphorus extreme pressure formulation expertise before specialist retirement accelerates. Anchor capacity control through Płock refinery partnership structures that lock in Group III base oil offtake. Defend against German and Benelux import dependency by investing in domestic re-refining infrastructure that closes circular supply loops under extended producer responsibility mandates. For New Entrants and Emerging Players: Pursue white-space positioning in EN 16807-certified biodegradable hydraulic fluids for Vistula and Oder inland shipping applications where environmental enforcement is tightening. Target agricultural machinery distributors in Greater Poland rapeseed-growing regions with EU taxonomy-aligned bio-based claims that command measurable price premiums. Establish go-to-market presence through technical distributor partnerships rather than direct OEM negotiation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical specialists with integrated fluid management contracts bundling supply, condition monitoring, and waste recovery. Long-term viability over the coming decade favors blenders with captive REACH registration portfolios and machinery OEM partnerships in automation retrofit cycles. Acquisition priority sits with mid-cap distributors possessing Silesian industrial corridor proximity and application engineering depth. Monitor Baltic Sea offshore wind turbine installation permits as inflection signal for synthetic gear oil demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-Refining | Captures waste oil recovery value under Polish extended producer responsibility frameworks. |
| REACH Registration Portfolio Buildout | Consolidates formulation authority among capital-rich players as small blenders exit. |
| EN 16807 Certification Investment | Unlocks municipal and inland shipping procurement requiring aquatic toxicity documentation. |
| Total Fluid Management Contracts | Transfers inventory risk to suppliers while locking in multi-year revenue streams. |
| Machinery OEM Technical Partnerships | Captures specification authority as equipment manufacturers consolidate lubricant decisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, PKN standardization filings, and EU regulatory databases. Primary interviews engaged lubricant blenders, Silesian steelworks maintenance directors, Poznań automotive procurement leads, and technical distributor operations heads. Secondary validation drew from ECHA REACH registration databases, Polish Committee for Standardization adoption schedules, and Baltic port import manifests. Bottom-up volume modeling triangulated against top-down refinery output and end-use consumption estimates.
Forecast inputs span product type segmentation by base stock chemistry, application intensity across automotive and industrial machinery, and customer contract structure from transactional spot to integrated service agreements. Modeled dimensions include viscosity grade tier, end-use equipment vintage, and regional industrial cluster concentration. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific inputs incorporate EU F-Gas Regulation phase-out schedules and extended drain interval penetration curves.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, Rhine logistics reliability, and base oil crack spreads would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and machinery replacement cycles. Quarterly review of Baltic base oil import volumes, PKN standard adoption deadlines, and offshore wind development permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
ASEAN Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Drilling Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Neat Cutting Oil Market