
 China Refrigeration Lubricants Market | 2026-2036
China Refrigeration Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
China Refrigeration Lubricants Market Outlook
Aftermarket service revenue is fragmenting across compressor rebuild networks and OEM-authorized service chains as equipment lifecycles extend. SINOPEC GROUP leverages captive petrochemical feedstocks to dominate mineral oil supply chains along the Yangtze River. Shell PLC competes through polyolester synthetic formulations calibrated for hydrofluoroolefin refrigerant transitions. FUCHS anchors premium positioning among industrial chiller operators demanding extended drain intervals.
China refrigeration lubricants are formulated base oils blended with additive packages to ensure thermal stability, seal compatibility, and refrigerant miscibility across compressor architectures operating between minus forty and one hundred fifty degrees Celsius. Mineral oil retains volume leadership in legacy ammonia and R22 systems though margin pools migrate toward synthetic ester formulations engineered for R32 and R410A compatibility. Synthetic oil commands expanding share among commercial refrigeration operators retrofitting equipment for lower-GWP refrigerant standards. Food and beverage end users concentrate procurement through HVAC contractors specifying OEM-approved lubricant grades to maintain warranty coverage.
MIIT enforces GB standards governing lubricant-refrigerant compatibility testing while MEE implements dual carbon targets that reshape compressor energy efficiency mandates and refrigerant transition timelines. SAMR monitors product quality certification requirements that filter market access for imported synthetic formulations. Stakeholders must track how provincial carbon intensity audits in Jiangsu and Shandong recalibrate lubricant procurement specifications for industrial refrigeration assets.
Market Dynamics
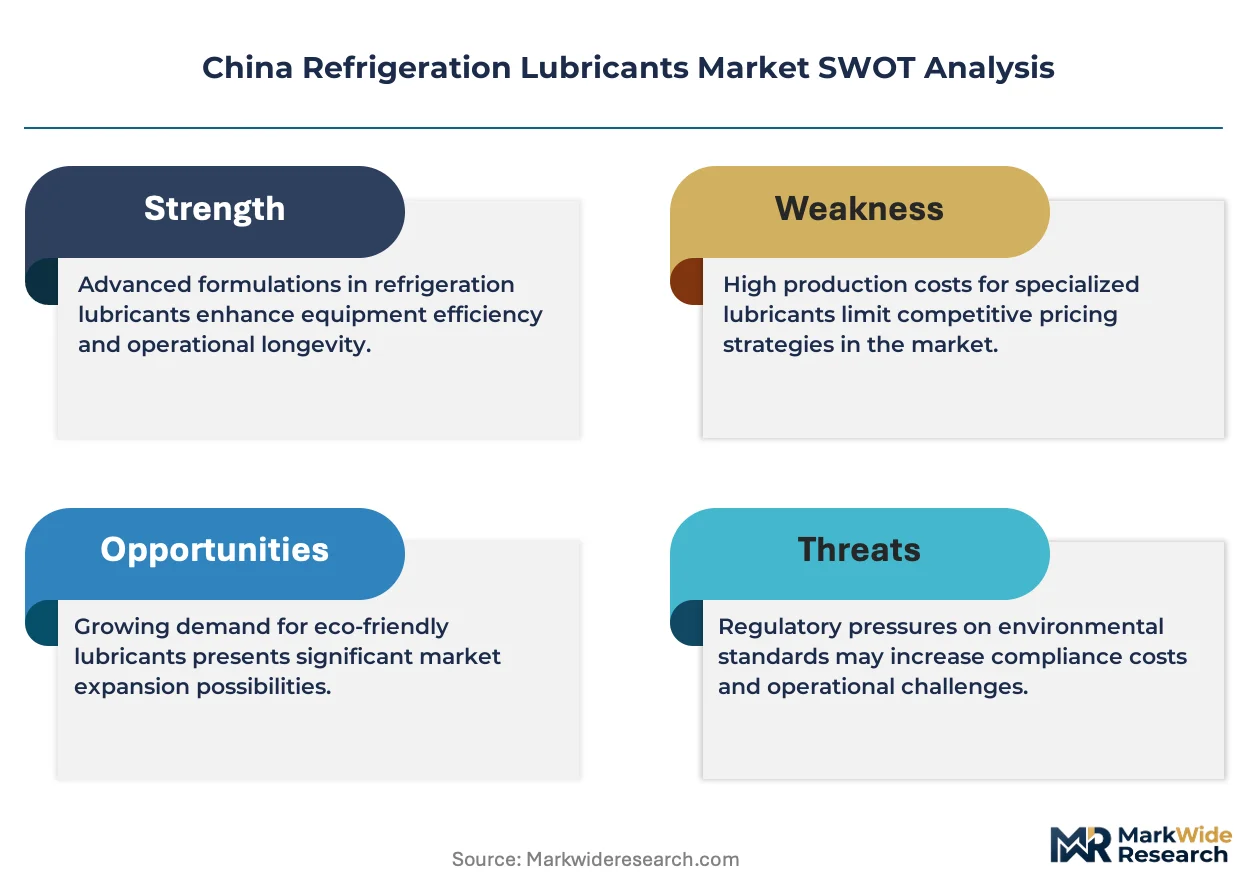
China's dual carbon mandates under MEE oversight are compressing refrigerant transition timelines, forcing compressor operators to abandon mineral oil formulations and adopt synthetic ester lubricants compatible with lower-GWP alternatives. This regulatory pressure is restructuring procurement specifications across industrial refrigeration assets.
Growth Catalysts
- Dual carbon policy enforcement:MEE carbon intensity audits in Jiangsu and Shandong provinces are mandating synthetic lubricant adoption for industrial chiller retrofits, creating specification-driven demand.
- Cold chain infrastructure expansion:Logistics operators in eastern provinces are scaling refrigerated fleet capacity, anchoring procurement volumes for compressor OEM clusters in Zhejiang manufacturing corridors.
- Lower-GWP refrigerant transition:Hydrofluoroolefin compatibility requirements are accelerating polyolester formulation deployment across commercial refrigeration systems.
Market Restraints
- Base oil supply concentration:Captive petrochemical feedstock control along the Yangtze River limits independent blender access to cost-competitive mineral oil inputs.
- Technical compatibility barriers:Seal material degradation risks with synthetic esters restrict retrofit applicability in legacy ammonia systems.
- Regulatory certification friction:SAMR quality certification requirements for imported synthetic formulations extend market access timelines for foreign suppliers.
Strategic Opportunities
- Western province penetration:Sichuan and Chongqing cold chain networks remain underdeveloped relative to eastern corridors, offering whitespace for lubricant distribution expansion.
- Extended drain interval services:Industrial chiller operators are unbundling maintenance contracts from equipment sales, creating aftermarket service revenue pools.
- GB standards harmonization:MIIT lubricant-refrigerant compatibility testing protocols are converging with international norms, reducing formulation duplication costs.
Industry Challenges
- Synthetic formulation expertise scarcity:Compound blending capabilities for polyolester and alkylbenzene chemistries concentrate among a limited supplier base.
- Legacy system integration complexity:Ammonia compressor architectures in food processing facilities resist synthetic lubricant conversion without complete refrigerant circuit replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Refrigeration Lubricants Market |
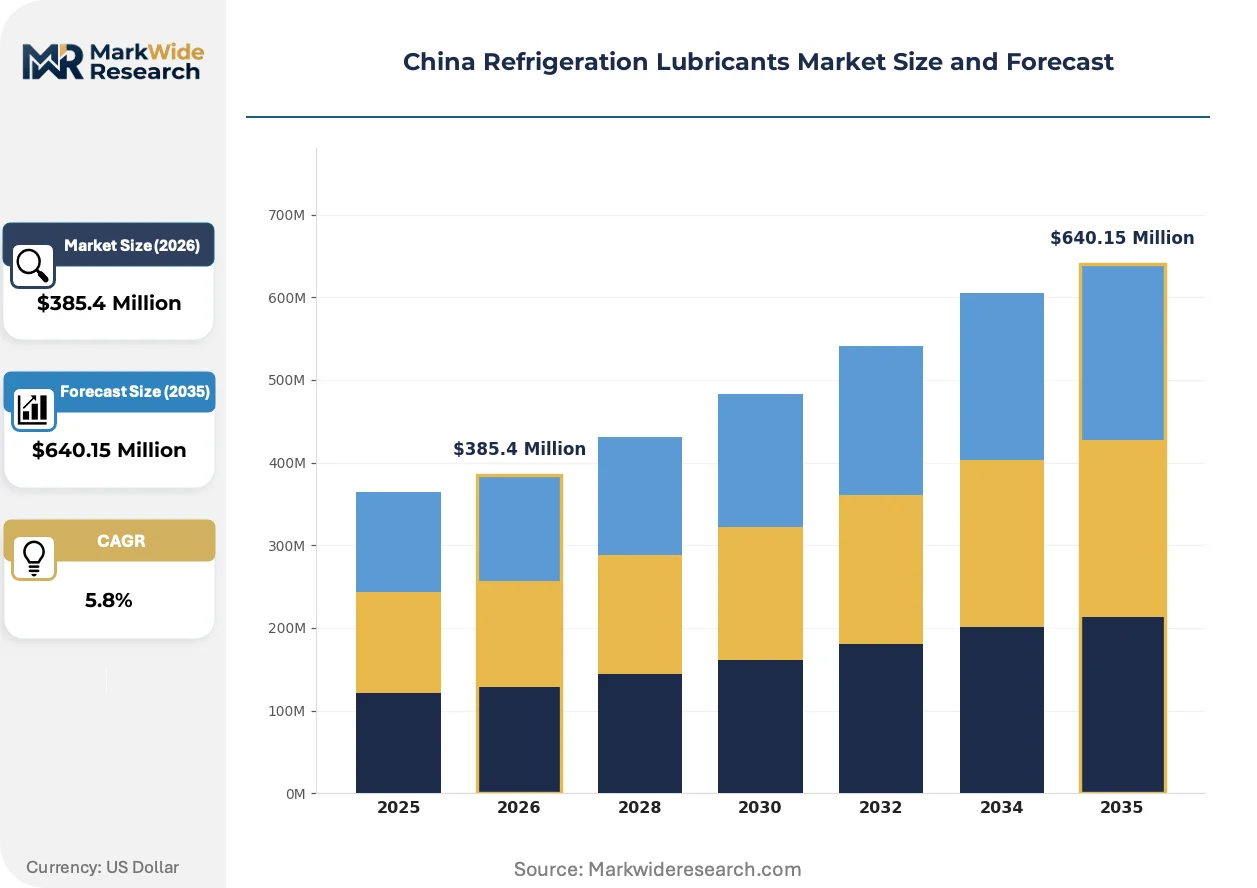
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Biodegradable Lubricants, Ester-Based Lubricants Application: Commercial Refrigeration, Residential Air Conditioning, Automotive A/C, Industrial Chillers End User: Food & Beverage Industry, Automotive Industry, HVAC Contractors, Manufacturing Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | ENEOS Corporation, Exxon Mobil Corporation, China Petroleum & Chemical Corporation (SINOPEC GROUP), Shell PLC, FUCHS, PetroChina Company Ltd, PETRONAS Lubricants International, BASF SE, Idemitsu Kosan Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Refrigeration Lubricants Market Strategic Shifts
Synthetic ester chemistry is actively displacing mineral oil dominance as refrigerant regulations tighten and compressor OEMs recalibrate thermal stability specifications. Three developments are restructuring competitive positioning.
Polyolester formulations engineered for R32 and R410A miscibility are rendering obsolete mineral oil-based service protocols in commercial refrigeration. Cold chain operators retrofitting equipment for lower-GWP compliance are specifying these synthetic grades to maintain warranty coverage. The shift is compressing margin pools toward formulation specialists with additive package customization capabilities.
MIIT enforcement of updated GB standards governing lubricant-refrigerant compatibility testing is forcing compressor OEMs to redesign seal materials and thermal management systems. Industrial refrigeration assets in Jiangsu manufacturing corridors face the most acute compliance pressure. Equipment operators are responding by consolidating procurement through HVAC contractors with certified formulation portfolios.
Aftermarket service unbundling is fragmenting lubricant demand across compressor rebuild networks and OEM-authorized service chains. Food and beverage end users are separating maintenance contracts from original equipment purchases, redirecting specification authority toward facility managers. This pattern concentrates in Zhejiang province where extended equipment lifecycles dominate operational planning.
China Refrigeration Lubricants Market Segmentation
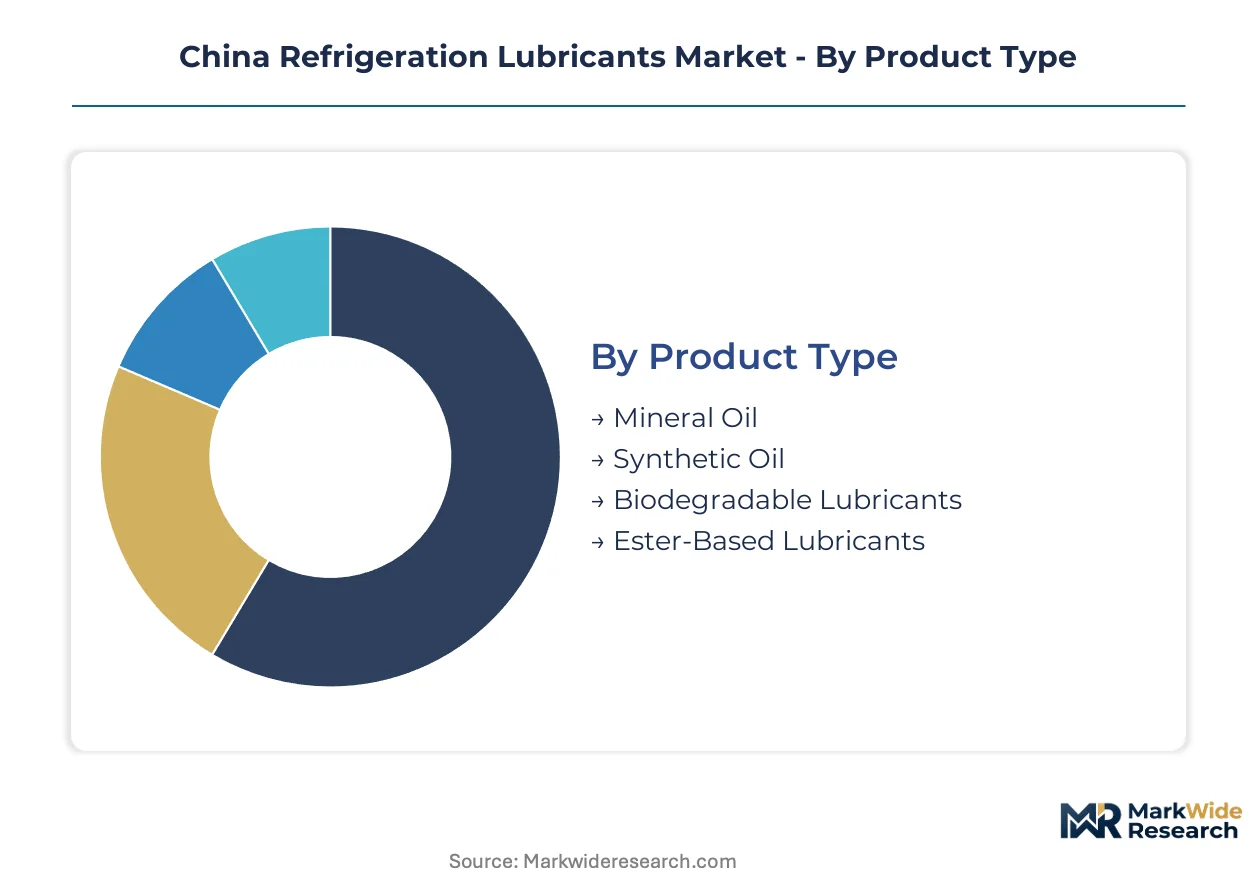
Segmentation in the China refrigeration lubricants market reveals how procurement cycles, technical specifications, and channel economics diverge across compressor architectures and end-use requirements. Understanding these fault lines exposes where margin pools concentrate and where specification authority is shifting.
Product Type:
Mineral oil formulations turn over fastest in aftermarket service protocols, while synthetic esters operate on extended drain cycles that compress replenishment frequency.
- Mineral Oil:Refined petroleum distillates formulated for legacy ammonia and R22 refrigerant systems dominate installed base maintenance. Jiangsu cold storage operators specify these grades for equipment nearing end-of-life, though dual carbon audits are accelerating replacement timelines.
- Synthetic Oil:Engineered polyolester and alkylbenzene chemistries deliver thermal stability for lower-GWP refrigerant transitions. Zhejiang compressor OEM clusters are mandating these formulations for R32 and R410A-compatible equipment to satisfy MEE efficiency mandates.
- Biodegradable Lubricants:Vegetable-derived base stocks address food processing contamination risks in Shandong poultry and seafood facilities.
- Ester-Based Lubricants:Polyol ester formulations optimize miscibility with hydrofluoroolefin refrigerants in commercial retrofit applications.
Mineral oil anchors the volume base while synthetic oil gains share at the steepest rate.
Application:
Cost tier stratification separates premium-specified industrial assets from price-sensitive residential installations.
- Commercial Refrigeration:Supermarket rack systems and cold storage warehouses specify OEM-approved lubricant grades to maintain warranty coverage. Eastern province logistics operators consolidating procurement through HVAC contractors drive specification authority here.
- Industrial Chillers:Large-tonnage centrifugal and screw compressors in Jiangsu manufacturing corridors demand extended drain interval formulations. Facility managers unbundling maintenance contracts from equipment sales redirect lubricant selection toward total cost-of-ownership metrics.
- Residential Air Conditioning:Split-system service protocols favor mineral oil replenishment in R22 legacy units during seasonal maintenance windows.
- Automotive A/C:Mobile compressor architectures require lubricant formulations compatible with variable displacement mechanisms and refrigerant charge minimization.
Industrial chillers command the premium tier while commercial refrigeration generates the highest procurement frequency.
End User:
Customer type determines whether procurement flows through consolidated enterprise contracts or fragmented spot-market purchases.
- Food & Beverage Industry:Cold chain operators from dairy processing to fresh logistics specify lubricants meeting FDA-equivalent contamination protocols. SINOPEC GROUP leverages Yangtze River feedstock access to dominate volume supply agreements with national dairy processors.
- HVAC Contractors:Installation and service networks in Zhejiang and Jiangsu provinces function as specification gatekeepers, consolidating lubricant demand from fragmented end users into bulk procurement pools.
- Automotive Industry:Vehicle OEMs and tier-one compressor suppliers enforce proprietary lubricant approvals for warranty compliance.
- Manufacturing Sector:Discrete manufacturing facilities with captive refrigeration assets source through direct mill-and-lube programs.
HVAC contractors intermediate the largest volume flows while food and beverage operators drive the fastest specification upgrades.
Distribution Channel:
Supply concentration along the Yangtze River shapes which channels control cost-competitive mineral oil access versus premium synthetic formulations.
- Distributors:Regional lubricant distributors with blending capabilities in Jiangsu and Shandong provinces aggregate demand from mid-sized cold storage operators. These intermediaries stock mineral oil volumes and synthetic ester SKUs calibrated to local refrigerant transition timelines.
- Direct Sales:Compressor OEMs and national oil companies bypass intermediaries for large industrial accounts with predictable consumption patterns. SINOPEC GROUP and Shell PLC deploy technical sales engineers to specify drain interval optimization programs.
- Specialty Stores:HVAC supply houses in Ningbo and Suzhou serve contractor trade with same-day availability for emergency service calls.
- Online Retail:E-commerce platforms capture small-volume maintenance purchases from independent service technicians.
Distributors control the broadest geographic reach while direct sales capture the highest-margin synthetic formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Chinese provinces. Eastern coastal buyers absorb synthetic lubricant premiums to satisfy MEE carbon audits, while western operators remain tethered to mineral oil economics.
Jiangsu Province
Carbon intensity audits under MEE oversight are forcing industrial chiller operators toward synthetic ester formulations. MIIT-enforced GB standards on lubricant-refrigerant compatibility are recalibrating procurement specifications. The Nanjing-Suzhou manufacturing corridor anchors compressor OEM clusters that mandate polyolester grades for R32-compatible equipment.
Zhejiang Province
Cold chain logistics operators are scaling refrigerated fleet capacity across Ningbo and Hangzhou metro areas. Extended equipment lifecycles are fragmenting aftermarket demand across rebuild networks and OEM-authorized service chains. HVAC contractors in this province function as specification gatekeepers, consolidating fragmented end-user demand into bulk procurement pools.
Shandong Province
Food processing facilities in poultry and seafood segments specify biodegradable lubricants to address contamination risks. Provincial carbon intensity audits are accelerating synthetic adoption timelines for ammonia compressor retrofits. The Qingdao-Yantai industrial belt concentrates procurement volumes among national dairy processors with captive maintenance protocols.
Sichuan-Chongqing Region
Cold chain networks remain underdeveloped relative to eastern corridors, creating whitespace for lubricant distribution expansion. Lower-GWP refrigerant transition timelines lag national benchmarks, preserving mineral oil demand in legacy R22 systems. Chengdu logistics hubs are attracting compressor OEM service depots as western infrastructure investment accelerates.
China Refrigeration Lubricants Market Competitive Environment
Capability concentration sits with formulation specialists commanding additive package customization; scale advantage sits with petrochemical majors controlling captive feedstock access. The vendor base stratifies across three tiers: national oil companies with Yangtze River integration, international lubricant blenders with synthetic ester portfolios, and regional distributors serving spot-market maintenance demand. Dominant competitive moves include backward integration into base oil refining and technical service bundling with drain interval optimization programs.
Among international blenders, Shell PLC and FUCHS exemplify the premium synthetic tier, while ENEOS Corporation anchors the Asia-Pacific supply vector. SINOPEC GROUP represents the scale-driven domestic archetype with Yangtze River feedstock control. These three entities occupy distinct competitive positions: one leverages petrochemical integration, another emphasizes polyolester formulation expertise, and the third bridges regional distribution networks with technical service capabilities.
| Leading Market Players |
|---|
| ENEOS Corporation |
| Exxon Mobil Corporation |
| China Petroleum & Chemical Corporation (SINOPEC GROUP) |
| Shell PLC |
| FUCHS |
| PetroChina Company Ltd |
| PETRONAS Lubricants International |
| BASF SE |
| Idemitsu Kosan Co Ltd |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River petrochemical corridor anchors base oil production capacity, concentrating feedstock control among integrated refiners and compressing margin pools for independent blenders downstream. Synthetic ester premiums reflect additive package customization costs and refrigerant compatibility certification burdens, while mineral oil pricing tracks naphtha feedstock volatility and SINOPEC GROUP volume leverage.
Pricing Analysis
Long-term offtake agreements dominate procurement between compressor OEM clusters and national oil companies, locking in volume commitments against spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates polyolester formulations with MIIT GB certification from mineral oil service grades and unbranded distributor blends. Cost compression in standard-tier synthetic products is intensifying because Zhejiang compressor OEMs are consolidating supplier panels. Food and beverage end users prove least price-sensitive due to warranty compliance requirements, while independent HVAC contractors absorb the highest spot-price volatility.
Supply Chain Analysis
Tariff exposure between China and key additive package suppliers concentrates formulation cost risk among polyolester blenders dependent on imported ester base stocks. Domestic supply draws from SINOPEC GROUP and PetroChina refineries along the Yangtze River, with specialty additive components sourced from Germany, Japan, and the United States. Single-source vulnerability sits with polyol ester feedstocks for hydrofluoroolefin-compatible grades, where technical specifications limit qualified suppliers. Distribution runs through Jiangsu and Shandong regional distributors with in-house blending capabilities, feeding contractor networks and direct industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China refrigeration lubricants sit in early-cycle expansion as MEE dual carbon enforcement accelerates synthetic substitution timelines and cold chain infrastructure investment deepens addressable demand. Penetration rates for polyolester formulations in legacy ammonia systems remain below structural potential, creating runway for specification upgrades.
For Market Incumbents: Entrench Yangtze River feedstock advantage through captive additive blending investments and technical service bundling. Compressor OEM consolidation threatens mineral oil volume pools; respond by locking extended drain interval contracts with Jiangsu industrial chiller operators. MIIT GB standards harmonization demands R&D allocation toward seal material compatibility testing. For New Entrants and Emerging Players: Pursue Sichuan-Chongqing distribution whitespace where cold chain networks lag eastern penetration and synthetic adoption timelines stretch. Target biodegradable lubricant demand in Shandong food processing facilities facing contamination protocol enforcement. Partner with regional HVAC contractors as specification gatekeepers rather than competing for direct OEM approvals. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because refrigerant transition mandates structurally expand synthetic addressable market regardless of macro cyclicality. Acquisition focus: mid-cap formulators with polyolester compounding capabilities and MIIT certification track records. Signal to watch: provincial carbon intensity audit enforcement velocity in Jiangsu and Shandong as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captive additive production secures polyolester formulation margins against imported component volatility. |
| Long-term Supply Agreement with Compressor OEMs | Locked volume commitments with Zhejiang OEM clusters defend market position through refrigerant transition cycles. |
| Geographic Expansion into Western Provinces | Sichuan and Chongqing cold chain buildout offers first-mover positioning in underdeveloped distribution networks. |
| Green Manufacturing Transition | Biodegradable lubricant certification addresses Shandong food processor contamination risk compliance requirements. |
| Joint Venture with Regional Distributor | Blending capacity partnerships in Jiangsu aggregate fragmented contractor demand into scalable procurement pools. |
Study Parameters
Desk research of MIIT regulatory filings, SAMR certification databases, and MEE carbon audit protocols preceded structured interviews with compressor OEM procurement directors, HVAC contractor specification managers, industrial chiller maintenance heads, and regional lubricant distributor operations leads. Secondary validation drew from SINOPEC GROUP supply disclosures, Shell PLC technical bulletins, and customs trade data on base oil and additive imports. Bottom-up demand modeling across end-use segments triangulated against top-down petrochemical capacity assessments.
Assumptions held fixed include MEE dual carbon enforcement timelines, MIIT GB standards adoption velocity, and compressor OEM R32/R410A transition schedules; variables tested included naphtha feedstock price bands and western province infrastructure investment rates. Segmentation dimensions spanned product chemistry tier, application architecture, end-user procurement consolidation level, and regional regulatory intensity cluster. CAGRs derived from equipment installation base growth, drain interval extension trends, and synthetic penetration curve analysis.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, freight logistics costs, or petrochemical feedstock availability would shift the trajectory. Forecasts reflect documented assumptions on refrigerant transition compliance and cold chain investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
US Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Lubricated Tracks Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Global Aerospace Lubricant Market