
 Thailand Automotive Engine Oils Market | 2026-2036
Thailand Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Automotive Engine Oils Market Analytics
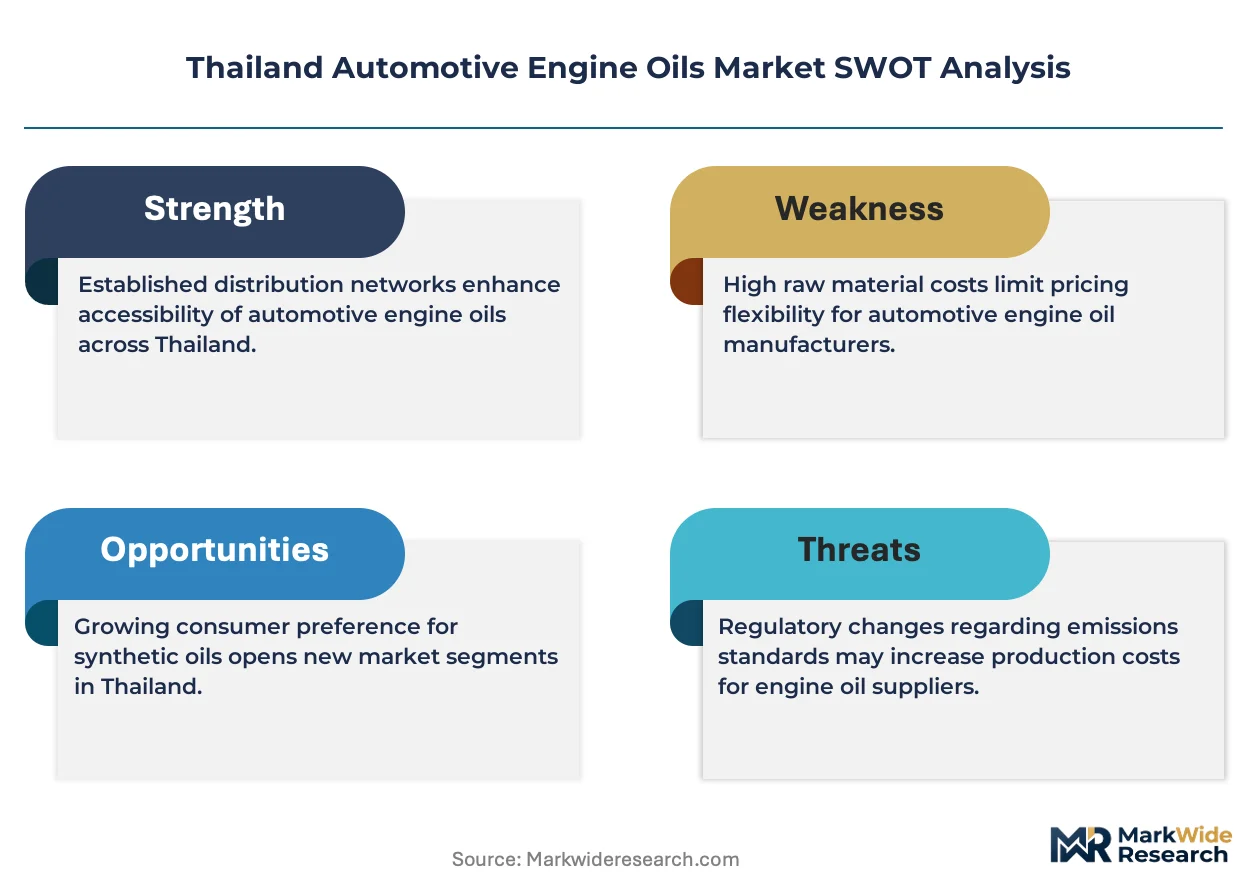
Asset-light leasing of blending and packaging facilities is fragmenting competitive barriers in Thailand's engine oils sector. PTT Lubricants leverages captive access to Group II/III base stocks from its parent refinery network. Shell plc anchors premium synthetic positioning through controlled distribution at dealership service stations. Chevron Corporation competes on commercial vehicle fleet contracts with extended drain-interval formulations.
Automotive engine oils are lubricating formulations comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with SAE viscosity grades and API service categories defining performance thresholds. Synthetic oils command margin premiums due to thermal stability requirements in turbocharged passenger vehicles operating under tropical ambient temperatures. The aftermarket channel dominates volume throughput as Thailand's vehicle parc ages beyond warranty periods, while fleet operators concentrate procurement through direct supply agreements with integrated lubricant marketers.
Thailand's Department of Industrial Works enforces hazardous substance controls under the Factory Act that govern blending plant emissions and waste oil handling protocols. The Thai Industrial Standards Institute mandates TISI certification for lubricant products sold domestically, aligning with API and JASO international benchmarks. Stakeholders must monitor evolving fuel-economy regulations and electrification timelines that will recalibrate demand for internal-combustion-specific lubricant chemistries.
Market Dynamics
Thailand's automotive engine oils sector faces a structural pivot as the Board of Investment redirects capital toward green manufacturing incentives, forcing formulators to abandon high-viscosity legacy portfolios and recalibrate additive chemistry for lower-viscosity grades demanded by next-generation powertrains.
Growth Catalysts
- Eastern Economic Corridor industrialization:Heavy vehicle utilization rates across Laem Chabang port logistics and Rayong manufacturing clusters are expanding fleet lubricant procurement volumes beyond replacement-cycle baselines.
- TISI certification alignment:Mandatory Thai Industrial Standards Institute certification for domestic lubricant sales is harmonizing quality thresholds with API and JASO international benchmarks, reducing import friction for compliant regional suppliers.
- Turbocharged powertrain penetration:Passenger vehicle thermal stability requirements under tropical ambient temperatures are accelerating synthetic oil adoption as OEM fill specifications tighten.
Market Restraints
- Group II/III base stock concentration:Captive refinery supply from integrated oil majors limits independent blender access to cost-competitive feedstock, compressing margin structures for non-integrated marketers.
- Electrification timeline uncertainty:Thailand's evolving fuel-economy regulations and battery-electric vehicle adoption curves are creating demand visibility gaps for internal-combustion-specific lubricant chemistries.
- Extended drain-interval formulations:Commercial fleet contracts specifying longer service intervals are reducing per-vehicle lubricant consumption rates despite stable vehicle parc size.
Strategic Opportunities
- Aftermarket channel consolidation:Aging vehicle parc beyond warranty periods is concentrating volume throughput in independent service networks, creating white space for direct supply agreements bypassing traditional distributor tiers.
- Lower-viscosity grade premiumization:BOI green manufacturing incentives are rewarding formulators who accelerate 0W-16 and 0W-8 grade commercialization for hybrid powertrains.
- Bangkok metropolitan corridor density:Urban congestion and stop-start driving patterns are accelerating wear-specific formulation demand for high-soot-handling passenger car motor oils.
Industry Challenges
- Additive package chemistry reconfiguration:Formulators face compressed R&D timelines to replace zinc-based anti-wear agents with ashless alternatives compatible with gasoline particulate filters.
- Blending facility emissions compliance:Factory Act hazardous substance controls mandate capital-intensive solvent recovery and waste oil handling infrastructure upgrades at legacy Bangkok-area plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Automotive Engine Oils Market |
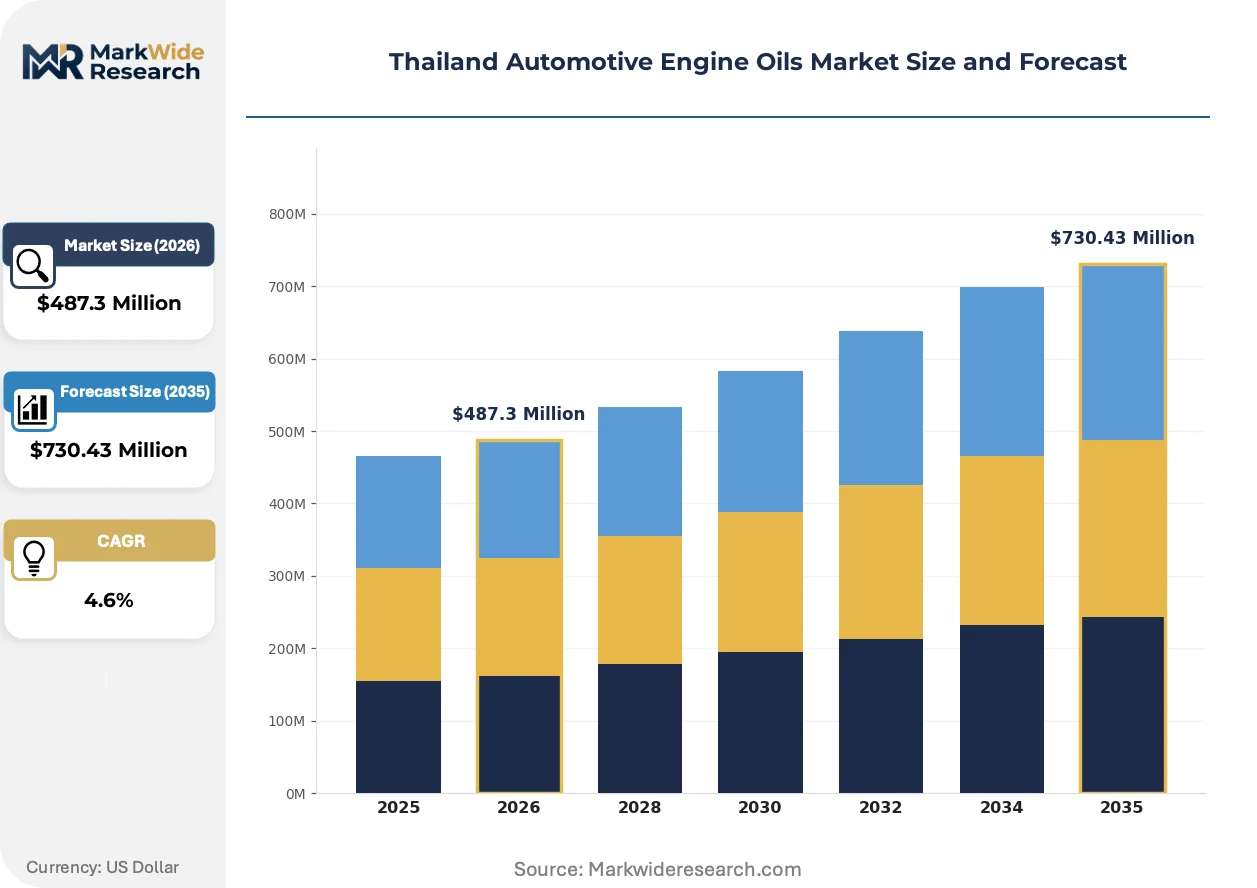
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oils, Conventional Oils, High-Mileage Oils, Bio-Based Oils End User: OEMs, Aftermarket, Fleet Operators, Retail Consumers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Machinery Distribution Channel: Online Retailers, Auto Parts Stores, Dealerships, Service Stations |
| Companies Covered | Shell plc, BP p.l.c., PTT Lubricants, LIQUI MOLY GmbH, PTG Energy Public Company Limited, Chevron Corporation, Bangchak Corporation, Siam Pan Group Public Co. Ltd, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Automotive Engine Oils Market Evolving Landscape
Digital integration is penetrating Thailand's lubricant value chain from predictive maintenance platforms to AI-driven blending optimization, compressing traditional technical service relationships and reshaping how fleet operators consume lubricant performance data.
Artificial intelligence-driven viscosity prediction algorithms are digitizing how blenders optimize base stock and additive ratios in real-time production environments. Major fleet operators in the Eastern Economic Corridor are piloting these systems to reduce batch rejection rates. The technology is digitizing quality assurance workflows that previously relied on offline laboratory verification cycles.
Thailand's Department of Industrial Works is tightening hazardous substance controls under amended Factory Act provisions, mandating closed-loop solvent systems at blending facilities. Industrial consequence includes accelerated plant consolidation as smaller operators face prohibitive retrofit costs. Bangkok metropolitan blenders are responding by pooling waste oil handling infrastructure through third-party logistics partnerships.
Direct procurement agreements between fleet operators and integrated lubricant marketers are displacing traditional distributor intermediaries in commercial vehicle segments. Fleet maintenance departments are consolidating supplier panels to capture volume rebates and technical service bundling. This pattern is most visible among Rayong-based petrochemical and automotive manufacturing fleets operating captive service workshops.
Thailand Automotive Engine Oils Market Segmentation
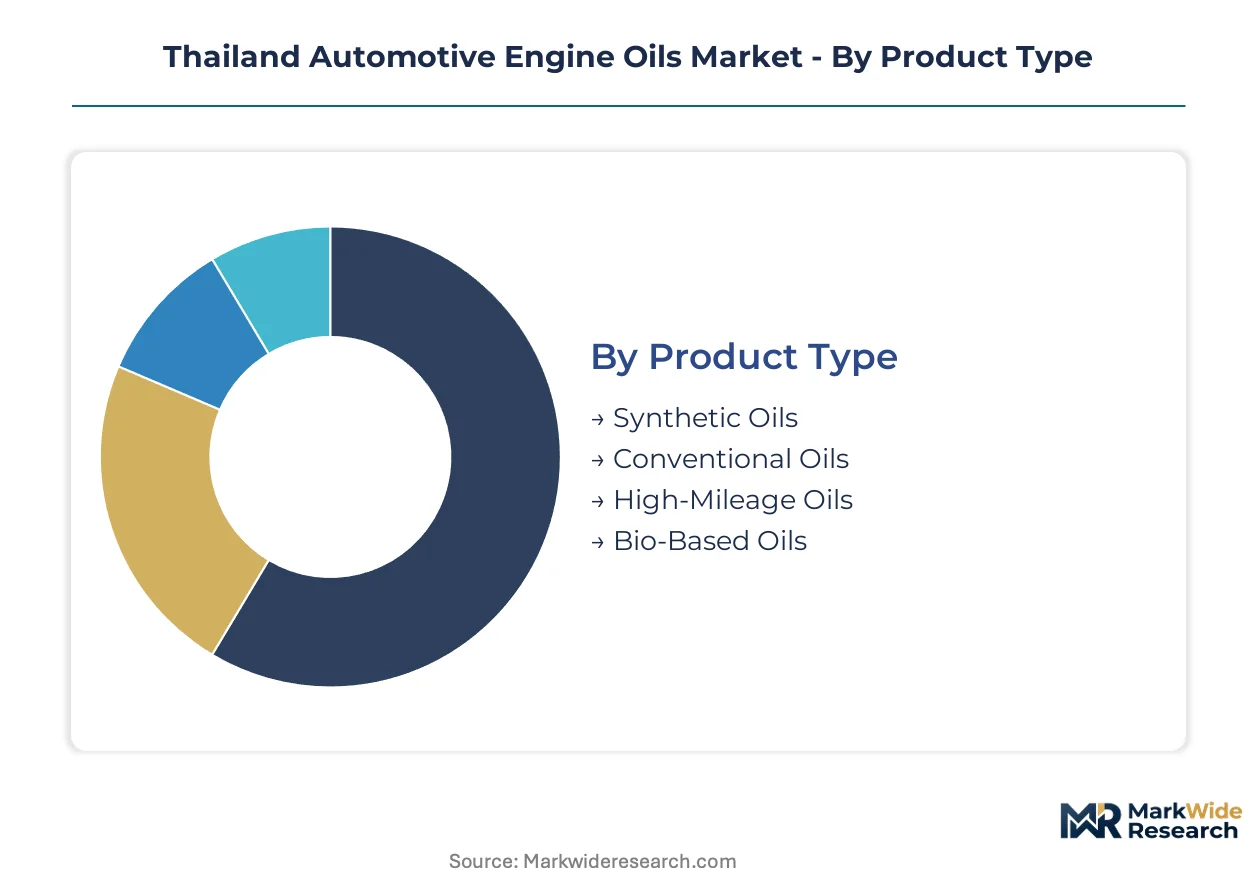
Thailand's engine oils market fragments across formulation chemistry, procurement behavior, and channel structure. Each segmentation axis reveals distinct margin profiles and competitive intensity patterns that shape how integrated marketers and independent blenders allocate capital.
Product Type:
Mature synthetic formulations dominate premium positioning while bio-based alternatives emerge at the innovation frontier.
- Synthetic Oils:Formulated from Group III/IV base stocks with tailored additive packages for thermal stability under tropical ambient temperatures. Bangkok metropolitan turbocharged passenger vehicle fleets specify 0W-16 and 0W-20 grades, compressing replacement cycles and commanding formulation premiums.
- Conventional Oils:Mineral-based formulations using Group I/II base stocks remain cost-competitive for aging vehicle parc beyond warranty periods. Eastern Economic Corridor logistics operators specify these for non-turbocharged commercial fleets with standard drain intervals.
- High-Mileage Oils:Seal conditioners and elevated viscosity indices target vehicles exceeding 120,000 kilometers. Aftermarket service networks in urban corridors stock these for retention of aging passenger car owners.
- Bio-Based Oils:Estolide and vegetable-derived base stocks align with Board of Investment green manufacturing incentives. Rayong petrochemical clusters pilot these for captive fleet trials seeking carbon footprint reduction.
Synthetic oils handle the majority of throughput; bio-based oils are expanding most quickly on share.
End User:
Procurement authority concentrates with fleet operators while retail fragmentation complicates margin capture.
- Fleet Operators:Direct supply agreements with integrated lubricant marketers consolidate volume procurement across Laem Chabang port logistics and Rayong manufacturing clusters. Extended drain-interval formulations reduce per-vehicle consumption but lock in multi-year contracts.
- Aftermarket:Independent service networks and auto repair chains source through distributor tiers or direct blender relationships. Bangkok metropolitan corridor density supports consolidated supplier panels with technical service bundling.
- OEMs:Factory fill specifications at Thai assembly plants determine initial viscosity grade penetration. Turbocharged powertrain thermal requirements tighten fill specifications toward lower-viscosity synthetics.
- Retail Consumers:Do-it-yourself purchasers select through auto parts store shelf presence and price-promotion sensitivity. Brand recognition and TISI certification visibility drive selection in fragmented purchasing occasions.
Fleet operators concentrate procurement authority; the aftermarket channel delivers volume scale.
Application:
Vehicle duty cycles determine soot-handling requirements and thermal stress profiles across formulation specifications.
- Passenger Vehicles:Stop-start urban driving patterns in Bangkok metropolitan congestion accelerate wear-specific formulation demand. Gasoline particulate filter compatibility requires ashless additive chemistry reconfiguration.
- Commercial Vehicles:Heavy-duty diesel engines operating across Eastern Economic Corridor logistics corridors specify high-total-base-number formulations for acid neutralization. Extended drain intervals reduce lubricant throughput per vehicle-kilometer.
- Two-Wheelers:Wet clutch compatibility and JASO MA2 friction specifications dominate motorcycle oil requirements. Urban commuter density supports volume concentration in metropolitan retail channels.
- Machinery:Off-highway construction and agricultural equipment operating outside standard automotive duty cycles require specialized viscosity grades and extreme-pressure additive packages.
Passenger vehicles anchor formulation innovation; commercial vehicles generate the steepest volume concentration.
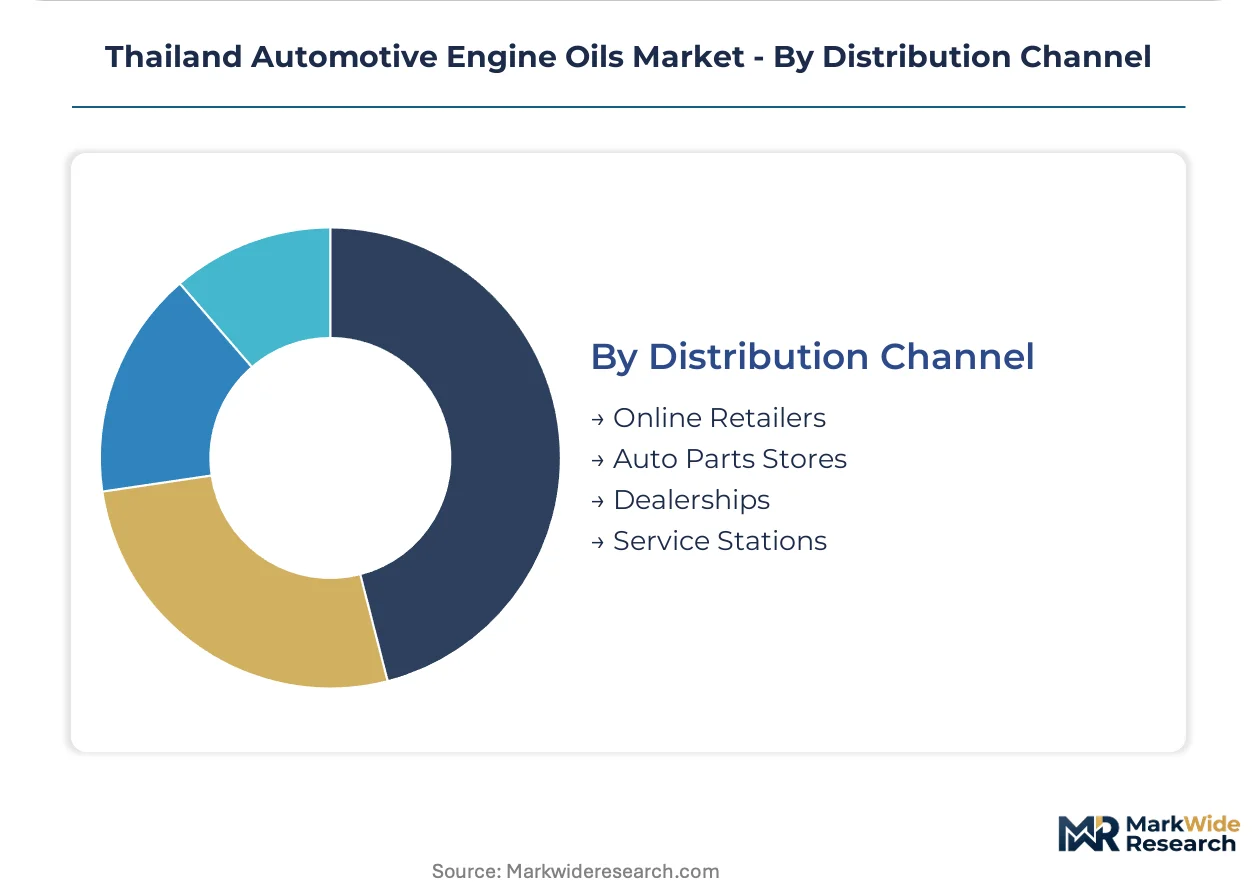
Distribution Channel:
Channel control determines margin capture and technical service relationship depth across customer segments.
- Dealerships:OEM-controlled service stations enforce proprietary fill specifications and captive lubricant procurement. Synthetic oil penetration rates exceed aftermarket channels due to warranty compliance requirements.
- Service Stations:Branded quick-lube networks and integrated oil company retail sites combine oil change services with lubricant sales. Fleet operators in industrial zones consolidate procurement through these channels for maintenance bundling.
- Auto Parts Stores:Independent retailers and chain formats stock multi-brand portfolios for do-it-yourself and walk-in trade. Price competition compresses margins on conventional oil SKUs.
- Online Retailers:E-commerce platforms penetrate metropolitan consumer segments with delivery convenience and promotional pricing. Product authenticity verification and TISI certification visibility remain purchase friction points.
Dealerships retain premium positioning; online retailers are gaining share fastest through metropolitan convenience capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment green manufacturing incentives are redirecting regional formulation priorities toward lower-viscosity grades. Demand concentrates in the Bangkok metropolitan corridor and Eastern Economic Corridor industrial zones.
Bangkok Metropolitan Corridor
Urban congestion and stop-start driving patterns accelerate wear-specific formulation demand for high-soot-handling passenger car motor oils. The Thai Industrial Standards Institute enforces TISI certification alignment with API benchmarks. Independent service networks in metropolitan Bangkok concentrate volume throughput as the vehicle parc ages beyond warranty periods.
Eastern Economic Corridor
Heavy vehicle utilization rates across Laem Chabang port logistics and Rayong manufacturing clusters expand fleet lubricant procurement volumes. Thailand's Department of Industrial Works mandates Factory Act compliance for blending plant emissions. Petrochemical and automotive manufacturing fleets in Rayong operate captive service workshops with direct supply agreements.
Central Plains Region
Agricultural machinery duty cycles create specialized demand for extreme-pressure additive packages outside standard automotive specifications. The central bank's credit facilitation programs support fleet modernization in commercial vehicle segments. Distribution networks in the Central Plains bridge urban formulation supply with rural equipment servicing requirements.
Northern Region
Mountainous terrain and temperature variation drive multi-grade viscosity requirements for commercial vehicle fleets operating cross-border logistics. Provincial industrial estates receive Board of Investment incentives for green manufacturing adoption. Chiang Mai-based logistics operators specify extended drain-interval formulations to reduce per-vehicle consumption.
Southern Region
Coastal humidity and salt exposure accelerate corrosion-protection formulation priorities for marine-adjacent vehicle operations. The Southern Seaboard Development Program channels infrastructure investment toward port-connected industrial zones. Songkhla and Surat Thani service networks stock higher-total-base-number formulations for heavy-duty diesel acid neutralization.
Thailand Automotive Engine Oils Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated oil majors with captive refinery access and independent blenders leasing third-party facilities. Domestic players leverage geographic proximity to base stock supply, while international marketers anchor premium positioning through controlled distribution. Two strategic archetypes dominate: vertically integrated refiners and asset-light formulation specialists. Competitive intensity centers on direct fleet procurement contracts and aftermarket channel consolidation.
Within the integrated refiner tier, PTT Lubricants and Bangchak Corporation exemplify supply-side concentration through captive access to Group II/III base stocks. Shell plc anchors premium synthetic positioning through dealership service station networks. Chevron Corporation occupies a position focused on commercial vehicle fleet contracts with extended drain-interval offerings.
| Leading Market Players |
|---|
| Shell plc |
| BP p.l.c. |
| PTT Lubricants |
| LIQUI MOLY GmbH |
| PTG Energy Public Company Limited |
| Chevron Corporation |
| Bangchak Corporation |
| Siam Pan Group Public Co. Ltd |
| ExxonMobil Corporation |
| Others |
Value Network & Pricing Analysis
Laem Chabang port logistics corridors anchor base stock freight economics for Thailand's engine oils sector, compressing landed costs for integrated refiners while elevating delivery premiums for independent blenders sourcing from Singapore and South Korea. This freight asymmetry concentrates pricing power with PTT Lubricants and Bangchak Corporation, forcing non-integrated marketers toward volume-rebate contracts or asset-light toll blending arrangements.
Pricing Analysis
Certification level creates the primary spread across Thailand's lubricant tiers, with TISI-certified synthetics commanding formulation premiums above uncertified imports. Three-tier pricing structure separates OEM fill specifications from aftermarket service networks and retail consumer channels, with fleet operators capturing volume scale discounts through direct procurement agreements. Pricing pressure stems from extended drain-interval formulations reducing per-vehicle consumption rates despite stable parc size. Retail consumers exhibit highest price sensitivity, while OEMs and fleet operators prioritize thermal stability specifications over unit cost.
Supply Chain Analysis
PTT Lubricants and Bangchak Corporation hold captive Group II/III base stock capacity through parent refinery networks, while independent blenders source from Singapore, South Korea, and Japan. Additive packages draw from Lubrizol, Infineum, and Afton supply hubs in Singapore and Japan, with zinc replacement chemistries for gasoline particulate filter compatibility creating formulation bottlenecks. Single-source vulnerability concentrates in Thai Industrial Standards Institute certification testing facilities, where queue delays extend product launch timelines. Distribution runs through dealership service stations, integrated oil company retail sites, and third-party logistics partnerships pooling waste oil handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's automotive engine oils market requires substitution defense against battery-electric vehicle penetration curves that threaten internal-combustion lubricant demand visibility. Incumbents must recalibrate portfolio exposure toward hybrid-compatible lower-viscosity grades while electrification timelines crystallize.
For Market Incumbents: Harden synthetic formulation capabilities for 0W-16 and 0W-8 grades ahead of Board of Investment green manufacturing incentive deadlines. Lock in multi-year fleet procurement contracts across Eastern Economic Corridor manufacturing clusters to offset retail channel margin compression. Vertical integration into additive package blending reduces exposure to Singapore supply hub congestion. For New Entrants and Emerging Players: Bio-based estolide formulations for Rayong petrochemical captive fleet trials represent the most penetrable entry point, with carbon footprint reduction mandates creating procurement openness. Bangkok metropolitan independent service networks seeking direct blender relationships bypassing distributor tiers offer channel white space. Technical service bundling with predictive maintenance platforms differentiates against established lubricant marketers. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oil majors divesting non-core lubricant assets amid energy transition portfolio rebalancing. Long-term viability hinges on hybrid powertrain lubricant demand persistence through the next decade. Watch battery-electric vehicle adoption rates in Thailand's commercial vehicle segments as inflection signal for internal-combustion lubricant demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Lower-Viscosity Grade Commercialization | Board of Investment incentives reward 0W-16 and 0W-8 synthetic formulations for hybrid powertrains. |
| Direct Fleet Procurement Agreements | Rayong manufacturing clusters consolidate supplier panels to capture volume rebates and technical service bundling. |
| Additive Package Chemistry Reconfiguration | Ashless anti-wear agents replace zinc for gasoline particulate filter compatibility in Bangkok metropolitan vehicles. |
| Blending Facility Emissions Compliance | Factory Act mandates drive capital-intensive solvent recovery upgrades and plant consolidation. |
| Aftermarket Channel Consolidation | Aging vehicle parc beyond warranty periods concentrates volume in independent service networks. |
Research Methodology
Cross-validation between primary interviews with lubricant formulators, fleet procurement managers, and aftermarket service network operators anchors the qualitative findings against secondary validation from Thai Industrial Standards Institute certification records, Department of Industrial Works Factory Act compliance filings, and Board of Investment incentive program disclosures. Bottom-up segmentation modeling triangulates with top-down macroeconomic drivers across the analysis window.
Calibration against historical base stock price volatility and additive package supply disruptions refines volume and value outputs across formulation chemistry, end-user procurement behavior, and distribution channel structure. CAGRs derive from vehicle parc aging curves, turbocharged powertrain penetration rates, and electrification timeline scenarios. Modeled inputs include Eastern Economic Corridor industrialization intensity and TISI certification alignment with API benchmark harmonization.
Stress conditions across battery-electric vehicle adoption curves, Group II/III base stock price spreads, and extended drain-interval formulation penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hybrid powertrain lubricant specification persistence and regulatory incentive continuity. Quarterly review of commercial vehicle fleet electrification announcements and Board of Investment green manufacturing incentive revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
America Lubricants Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market