
 United Arab Emirates Lubricants Market | 2026-2036
United Arab Emirates Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Lubricants Market Analytics
Multi-source procurement among fleet operators and industrial buyers is broadening across the UAE lubricants sector. ADNOC leverages its upstream refining integration to secure feedstock cost advantages for domestic blending operations. ENOC sustains retail and commercial channel dominance through service station networks and direct industrial contracts. Shell competes on synthetic and high-performance formulation portfolios aimed at OEM partnerships.
United Arab Emirates lubricants are formulated base oils blended with additive packages to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to VG 680 for industrial applications and SAE 5W-30 to 15W-40 for automotive engines. Engine oil occupies the largest volume share given the UAE's extensive vehicle fleet and commercial transport activity, while hydraulic fluids command premium pricing in construction and oilfield services. Greases represent a specialized margin pool serving high-load bearings in desert mining and marine environments.
MOHAP oversees product registration and safety standards for lubricants distributed domestically, while the Emirates Authority for Standardization and Metrology enforces UAE-specific quality benchmarks aligned with API and ACEA performance categories. The UAE's dual carbon goals and industrial decarbonization mandates are pushing formulators toward lower-viscosity and extended-drain synthetic products. Stakeholders must weigh bio-based additive investments against established mineral oil infrastructure as regulatory thresholds tighten.
Market Dynamics
Synthetic formulation mandates from MOHAP and ESMA are compressing mineral oil shelf life while elevating additive complexity requirements across UAE industrial zones.
Growth Catalysts
- Marine bunkering expansion:Jebel Ali and Ruwais port authorities are mandating high-performance cylinder oils for ultra-large container vessels, pulling demand for Group III base stocks.
- ESMA quality benchmarks:Tightened UAE-specific standards aligned with API SP and ACEA C sequences are disqualifying low-tier imports and consolidating certified domestic supply.
- Desert mining automation:Autonomous haul fleets at Ruwais and Al Dhafra mines require extended-drain synthetics with thermal stability beyond conventional formulations.
Market Restraints
- Group II/III base oil import dependency:UAE blending operations source 70% of feedstock from Singapore and South Korean refiners, exposing margins to freight rate volatility and Red Sea transit disruptions.
- Additive package concentration:Four global chemical houses control 85% of high-performance dispersant and anti-wear chemistry, limiting formulator bargaining power.
- Mineral oil infrastructure lock-in:Existing storage tanks and dispensing equipment across Dubai construction fleets require capital retrofit to handle lower-viscosity synthetics without contamination risk.
Strategic Opportunities
- Abu Dhabi industrial free zones:KIZAD and KEZAD clusters offer 15-year tax holidays for lubricant blending facilities serving petrochemical and aluminum smelter contracts.
- EV thermal management fluids:Battery electric commercial vehicles entering Dubai Metro logistics fleets require dielectric coolants with fire suppression properties absent in legacy engine oils.
- Digital fluid monitoring:IoT sensor integration with ENOC and ADNOC distribution networks enables predictive drain-interval optimization for construction contractors.
Industry Challenges
- Formulation chemist scarcity:UAE universities produce fewer than 50 tribology specialists annually, forcing blenders to recruit from Indian Institute of Petroleum and German technical institutes.
- MOHAP registration timelines:New product approvals now require 14-18 months of bench testing and field trials, delaying synthetic line extensions.
- Cross-contamination protocols:Multi-grade blending lines must undergo ISO 4406 cleanliness verification between mineral and synthetic campaigns, compressing effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Lubricants Market |
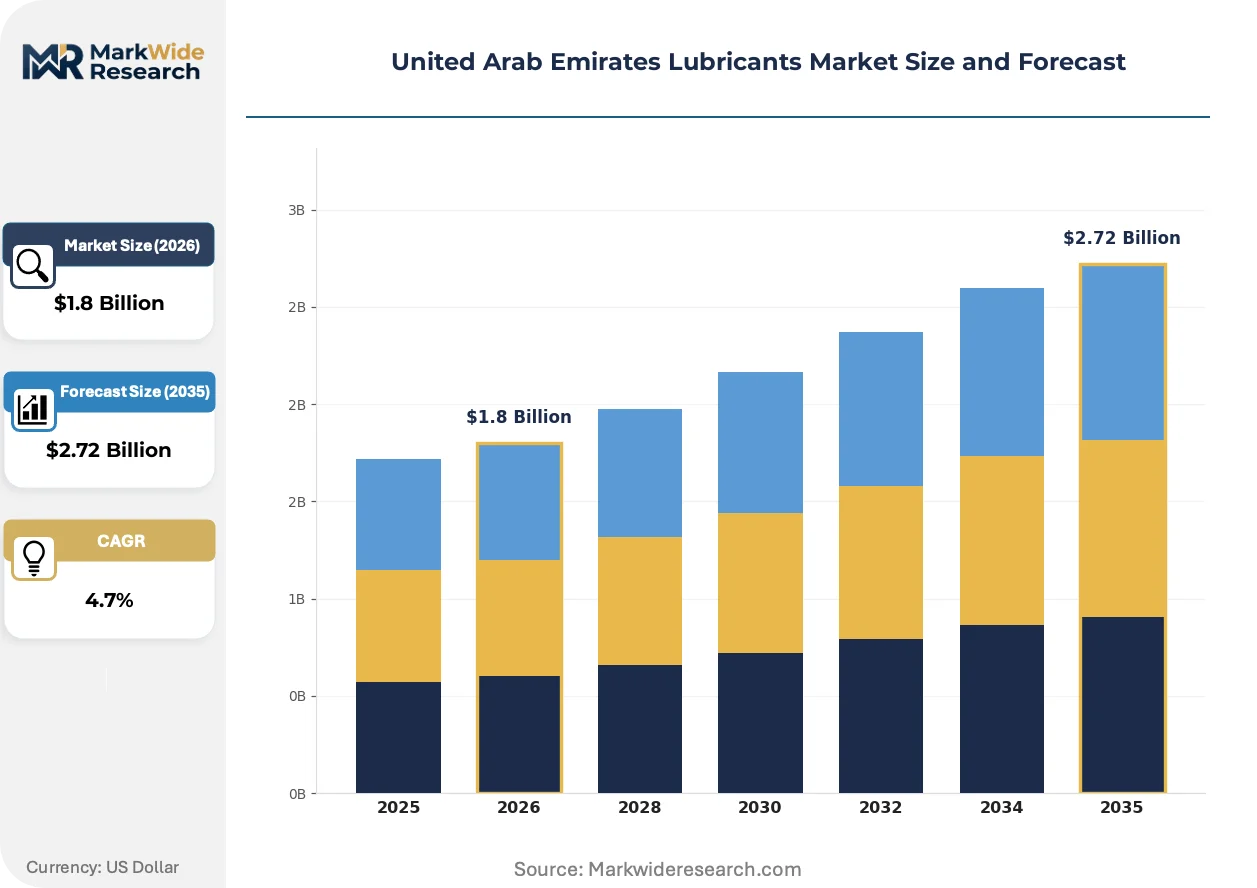
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluids, Greases End User: Automotive, Industrial, Marine, Aerospace Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Manufacturing Equipment Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Abu Dhabi National Oil Company (ADNOC), Emirates National Oil Company (ENOC), TotalEnergies, Shell, ExxonMobil, Emirates Lube Oil Company, Sharjah National Lube Oil Company (SHARLU), Petromin Corporation, BP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Lubricants Market Evolving Landscape
Refrigerant-lubricant compatibility standards and predictive maintenance integration are forcing formulators to engineer beyond traditional viscosity-grade specifications.
Synthetic polyalkylene glycol (PAG) and polyol ester (POE) chemistries are rewriting thermal stability benchmarks for UAE air conditioning and refrigeration compressors. Abu Dhabi district cooling operators are specifying these fluids for 100,000-hour service life in 50°C ambient conditions. The shift is compressing demand for naphthenic mineral oils previously dominant in HVAC applications.
MOHAP's 2024 update to lubricant product registration requirements now mandates full additive component disclosure and toxicity screening for metalworking fluids. Industrial buyers in Sharjah manufacturing zones are disqualifying suppliers lacking pre-registered formulations. The policy is accelerating consolidation among smaller trading houses unable to absorb compliance costs.
Construction fleet managers in Dubai are unbundling lubricant supply from equipment maintenance contracts, creating direct procurement relationships with blenders. Traditional distributor markups of 18-22% are compressing to 8-12% as buyers leverage ENOC and Shell direct industrial portals. The pattern is most pronounced among contractors operating above 500 unit fleet scale in Al Quoz and Jebel Ali industrial corridors.
United Arab Emirates Lubricants Market Segmentation
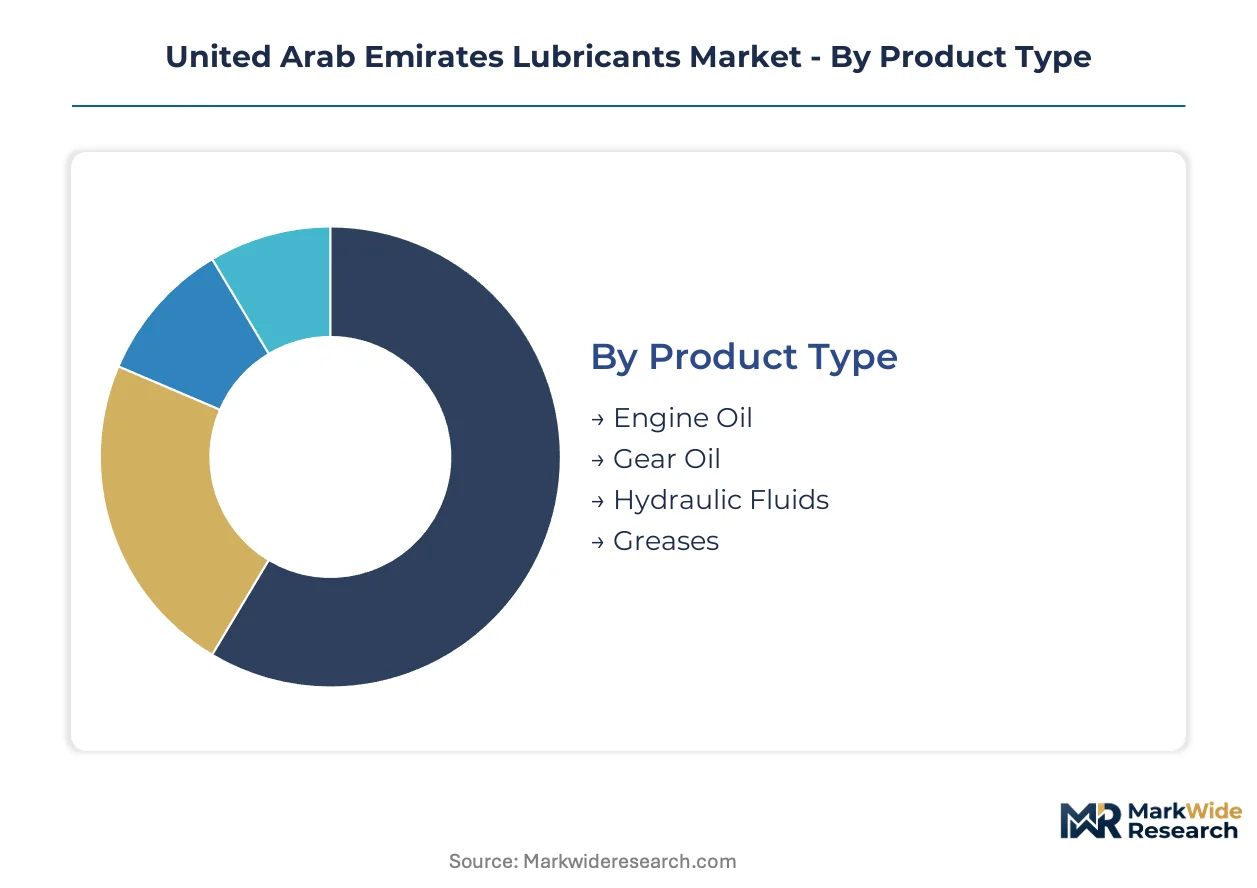
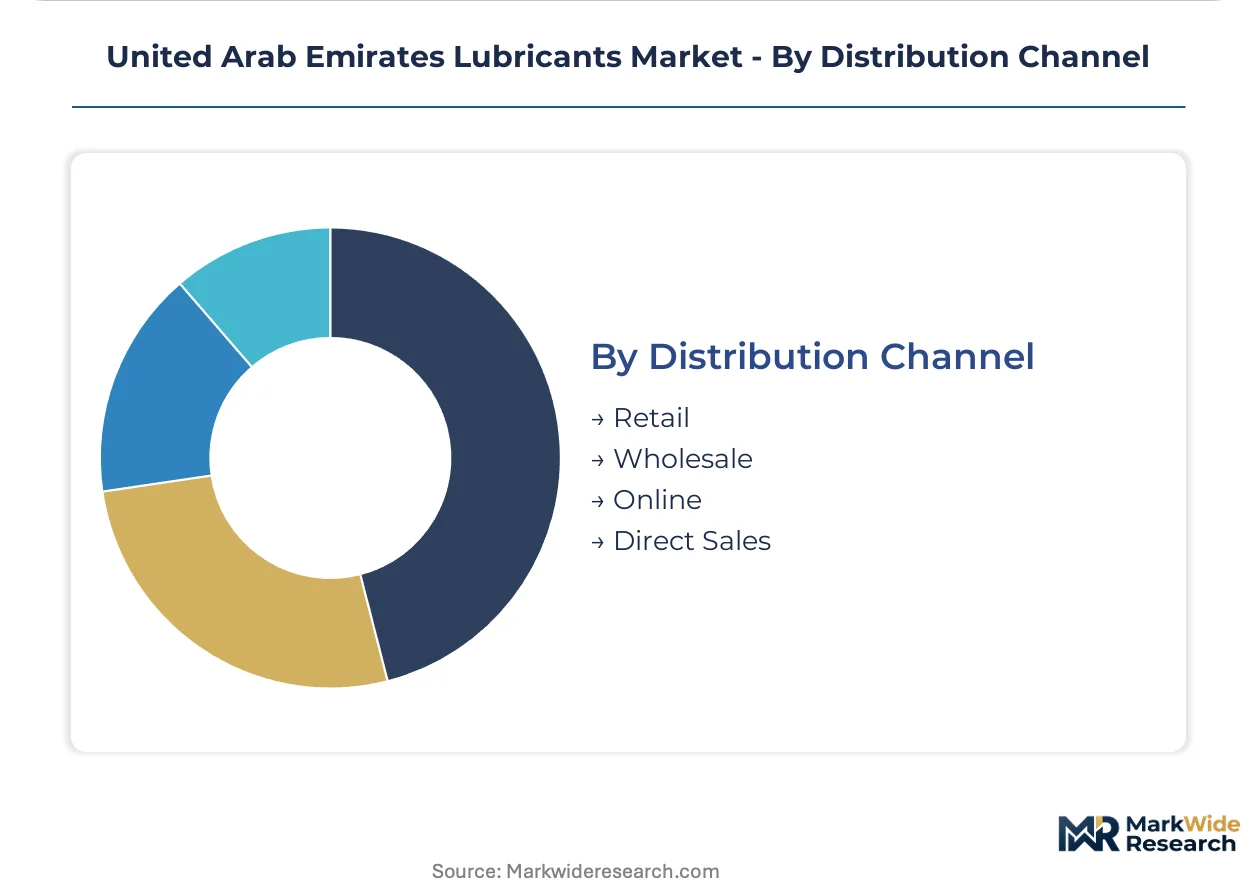
Segmentation in the UAE lubricants market reveals how procurement patterns diverge between high-volume fleet operators and specification-driven industrial buyers. Understanding these splits allows suppliers to align blending capacity, certification investments, and channel strategy with actual demand concentration across Dubai and Abu Dhabi industrial corridors.
Product Type:
Volume concentrates in commodity-grade engine oils serving Dubai's transport fleets, while premium margins pool in specialized formulations for desert mining and marine applications.
- Engine Oil:Multi-grade formulations spanning SAE 5W-30 to 15W-40 dominate procurement volumes across UAE commercial vehicle fleets. Dubai logistics contractors operating above 500 units are consolidating direct supply agreements with ENOC and Shell, bypassing traditional distributor markups.
- Hydraulic Fluids:Anti-wear formulations meeting ISO VG 32-68 specifications command pricing premiums in construction and oilfield services. Abu Dhabi contractors at Ruwais and Al Dhafra mines specify extended-drain synthetics with thermal stability beyond conventional mineral oils for autonomous haul fleets.
- Gear Oil:EP additive packages protect high-load differentials in desert mining equipment and marine reduction gears.
- Greases:Lithium complex and calcium sulfonate thickeners serve bearings in 50°C ambient conditions with contamination resistance.
Today's leader: Engine Oil. Tomorrow's challenger: Hydraulic Fluids.
End User:
Customer archetypes split between price-sensitive fleet operators and specification-bound industrial engineers with divergent procurement authority structures.
- Automotive:Service station networks and quick-lube chains in Dubai and Sharjah drive high-frequency, low-margin transactions. ENOC retail dominance and ADNOC fleet contracting capture the bulk of passenger and commercial vehicle demand.
- Industrial:Petrochemical processors at Ruwais and aluminum smelters in KIZAD specify customized additive packages with 10,000-hour service intervals. These buyers negotiate direct blender relationships with technical compliance teams overriding procurement cost targets.
- Marine:Jebel Ali and Ruwais port authorities mandate high-performance cylinder oils for ultra-large container vessels, pulling Group III base stock demand.
- Aerospace:Synthetic ester formulations meeting SAE AS5780 serve turbine engines and auxiliary power units with extreme temperature stability.
Automotive generates the highest transaction velocity. Industrial captures the steepest margin expansion trajectory.
Application:
Equipment duty cycles and operating environments determine formulation complexity and drain interval economics across UAE industrial zones.
- Passenger Vehicles:Stop-start traffic patterns in Dubai and Abu Dhabi urban corridors accelerate oil degradation, shortening drain intervals versus highway-dominated markets.
- Commercial Vehicles:Long-haul trucking between Emirates and cross-border routes into Saudi Arabia and Oman prioritize extended-drain synthetics to minimize downtime.
- Heavy Machinery:Desert mining automation at Ruwais and Al Dhafra requires thermal stability beyond conventional formulations for autonomous haul fleets.
- Manufacturing Equipment:Sharjah manufacturing zones specify metalworking fluids with full additive disclosure under MOHAP's 2024 registration requirements.
Heavy Machinery demands the most advanced formulation chemistry. Passenger Vehicles offer the largest addressable volume base.
Distribution Channel:
Channel economics are compressing as large fleet operators unbundle lubricant supply from maintenance contracts and migrate to direct procurement portals.
- Retail:ENOC service station networks and independent auto parts stores serve DIY consumers and small fleet operators with immediate availability requirements.
- Wholesale:Traditional distributors serving Dubai construction fleets face margin compression from 18-22% to 8-12% as buyers scale and demand direct relationships.
- Online:ENOC and Shell industrial portals enable procurement automation for mid-size contractors in Al Quoz and Jebel Ali corridors.
- Direct Sales:ADNOC and Shell technical teams negotiate multi-year supply agreements with petrochemical and aluminum smelter operators in KIZAD and KEZAD free zones.
Direct Sales is gaining share fastest among industrial buyers. Retail maintains defensive positioning in fragmented automotive service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali and Ruwais anchor UAE lubricant demand through marine bunkering, petrochemical processing, and autonomous mining fleets. MOHAP and ESMA regulations are compressing mineral oil shelf life while elevating synthetic formulation requirements. Procurement patterns diverge sharply between Dubai's logistics corridors and Abu Dhabi's industrial free zones.
Dubai
Construction fleet operators in Al Quoz and Jebel Ali corridors are unbundling lubricant supply from maintenance contracts. ENOC retail networks and direct industrial portals capture high-frequency transactions from contractors operating above 500 units. Service station density and logistics infrastructure position Dubai as the commercial volume leader.
Abu Dhabi
ADNOC leverages upstream refining integration to secure feedstock cost advantages for domestic blending. KIZAD and KEZAD industrial clusters offer 15-year tax holidays for facilities serving aluminum smelters and petrochemical processors. Ruwais port authorities mandate high-performance cylinder oils for ultra-large container vessels.
Sharjah
Manufacturing zones specify metalworking fluids with full additive disclosure under MOHAP's 2024 registration requirements. Industrial buyers are disqualifying suppliers lacking pre-registered formulations. Compliance cost absorption pressures are accelerating consolidation among smaller trading houses.
Northern Emirates
Ras Al Khaimah and Fujairah serve as secondary distribution nodes with lower land costs for bulk storage terminals. Marine bunkering support for East African and South Asian shipping routes pulls Group III base stock demand. Infrastructure investment lags Dubai and Abu Dhabi corridors.
United Arab Emirates Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic formulation partnerships with OEMs and industrial free zone operators. The vendor base concentrates around three strategic archetypes: integrated national oil companies with captive feedstock, multinational formulators with synthetic portfolios, and regional blenders serving construction and marine niches. Capacity expansion and direct procurement portal development represent the dominant competitive moves as distributor markups compress from 18-22% to 8-12%.
Within the integrated national oil company tier, Abu Dhabi National Oil Company and Emirates National Oil Company exemplify upstream-downstream control over base oil supply and domestic blending infrastructure. Shell occupies a position among multinational formulators competing on synthetic and high-performance portfolios. These three anchors represent distinct strategic postures: feedstock security, retail channel density, and technical specification leadership.
| Leading Market Players |
|---|
| Abu Dhabi National Oil Company (ADNOC) |
| Emirates National Oil Company (ENOC) |
| TotalEnergies |
| Shell |
| ExxonMobil |
| Emirates Lube Oil Company |
| Sharjah National Lube Oil Company (SHARLU) |
| Petromin Corporation |
| BP |
| Others |
Value Network & Pricing Analysis
MOHAP's 2024 additive disclosure mandates and ESMA synthetic formulation standards gate qualified supply and premium-tier pricing access for UAE lubricant blenders. Formulators lacking pre-registered additive packages face disqualification from industrial procurement in Sharjah manufacturing zones, compressing viable supply sources and elevating pricing power among certified domestic producers.
Pricing Analysis
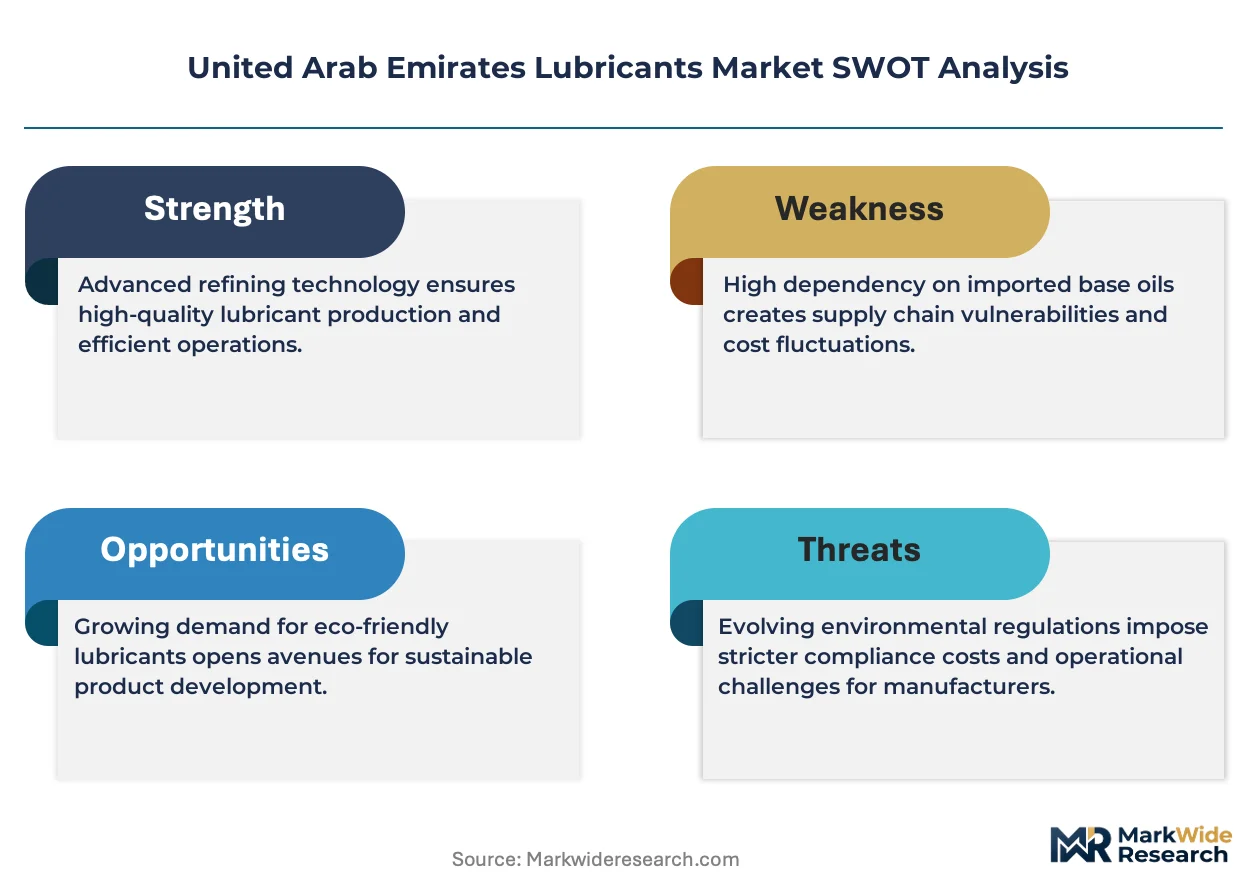
Base oil freight costs from Singapore and South Korean refiners pass through directly to UAE blending margins, with Group II/III feedstock volatility driving contract renegotiation frequency. Pricing stratifies across API SP-certified synthetics, ACEA C-sequence mid-tier formulations, and mineral-based economy grades serving legacy construction fleets. Cost compression in the economy tier intensifies because large fleet operators unbundle lubricant supply from maintenance contracts and bypass traditional distributor markups. Small Dubai construction contractors operating below 500 units exhibit highest price sensitivity, while Ruwais petrochemical processors prioritize thermal stability specifications over unit cost.
Supply Chain Analysis
Red Sea transit disruptions and Asia-Middle East freight rate volatility elevate landed costs for UAE blending operations sourcing 70% of feedstock from Singapore and South Korean refiners. Domestic production draws from Group II/III base oils, high-performance dispersant additive packages, and specialized thickener chemistries for desert mining applications. Single-source vulnerability concentrates in the four global chemical houses controlling 85% of anti-wear and dispersant chemistry. Distribution runs through ENOC retail networks, direct industrial portals for scaled contractors, and ADNOC technical sales teams serving KIZAD and KEZAD free zone operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE lubricants market offers margin expansion through synthetic formulation premiums and direct procurement channel capture. Extended-drain synthetic adoption among autonomous mining fleets and marine bunkering operators shifts value capture from distributors to certified blenders.
For Market Incumbents: Hedge feedstock cost exposure through long-term offtake agreements with Singapore and South Korean refiners, while accelerating ISO 4406 cleanliness verification protocols to compress campaign changeover downtime. Defend against direct procurement erosion by embedding IoT fluid monitoring into ENOC and ADNOC distribution networks, locking in predictive maintenance relationships with Dubai construction fleets above 500 units. For New Entrants and Emerging Players: ESMA quality benchmarks aligned with API SP and ACEA C sequences in the UAE open a window for synthetic formulation partnerships with OEMs serving desert mining automation. Target Abu Dhabi industrial free zones with 15-year tax holidays for blending facilities, leveraging KIZAD and KEZAD proximity to aluminum smelter and petrochemical processor demand. Pursue dielectric coolant development for battery electric commercial vehicles entering Dubai Metro logistics fleets as the most penetrable white-space segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders lacking MOHAP pre-registration for metalworking fluids and facing compliance cost absorption pressures. Long-term viability centers on synthetic formulation capabilities and direct industrial channel control rather than retail network density. Watch for inflection when autonomous haul fleet deployment at Ruwais and Al Dhafra mines accelerates extended-drain synthetic procurement beyond current mineral oil infrastructure lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | ADNOC upstream refining integration secures captive Group III feedstock for domestic synthetic blending. |
| Direct Industrial Portal Development | ENOC and Shell procurement automation captures margin compression from distributor bypass in Al Quoz corridors. |
| EV Thermal Management Fluid R&D | Dielectric coolant formulation addresses battery electric commercial vehicle fire suppression requirements absent in legacy oils. |
| Free Zone Blending Facility Expansion | KIZAD and KEZAD tax holidays attract capacity serving petrochemical and aluminum smelter technical specifications. |
| IoT-Enabled Predictive Maintenance Integration | Sensor-equipped distribution networks optimize drain intervals for Dubai construction contractors unbundling supply contracts. |
Research Methodology
Multiple input streams — blending plant technical directors, fleet procurement managers at Dubai logistics contractors, MOHAP regulatory affairs specialists, and marine bunkering operators at Jebel Ali — were reconciled against customs trade data, ESMA certification registries, SEC filings from multinational formulators, and petrochemical processor supply agreements. Bottom-up volume estimates from individual blender capacity and top-down demand segmentation were triangulated to produce market sizing and growth projections.
Data-stream reconciliation across product type, end user application, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and feedstock cost pass-through assumptions. Forecast inputs incorporated MOHAP registration timeline delays, Red Sea freight rate volatility scenarios, and synthetic formulation adoption curves among autonomous mining fleets.
Revisions become necessary when ESMA mandates accelerate mineral oil phase-out timelines, Red Sea transit disruptions persist beyond freight rate hedging windows, or EV thermal management fluid specifications diverge from current dielectric coolant chemistries. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Lube Skid Market
Lubricants
China Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Iraq Lubricants Market
Lubricants
Mining Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Marine Grease Market
Lubricants
Polyurea-Based Greases Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Global Grease Market
Lubricants
South America Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
ASEAN Lubricants Market