
 Russia Automotive Engine Oils Market | 2026-2036
Russia Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Engine Oils Market Analytics
Aftermarket service revenue is tilting toward higher-margin synthetic formulations as vehicle owners extend drain intervals. Gazpromneft-Lubricants Ltd. leverages its captive refinery network to anchor supply security across Russia's remote regions. Lukoil sustains broad retail penetration through integrated service station channels. Shell Plc competes on technical certification depth for European-imported passenger vehicle fleets.
Russia automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with synthetic variants typically offering viscosity stability from minus 35 degrees Celsius to over 200 degrees Celsius operating temperatures. Synthetic formulations command premium positioning due to their extended service life and cold-start performance in Siberian conditions. The 5W-30 and 10W-40 viscosity grades dominate volume flows, reflecting the legacy fleet composition and prevailing OEM fill recommendations. Passenger vehicles and commercial vehicles together absorb the majority of lubricant offtake, though heavy-duty machinery segments exhibit faster growth in mining and oilfield service applications.
Russia's national standards body BIS-equivalent GOST certification requirements, alongside Rosstandart technical regulations for lubricant quality, shape product compliance costs and import substitution incentives. The country's environmental regulator enforces waste oil handling protocols that elevate collection and re-refining infrastructure investments. Stakeholders must monitor how domestic base oil capacity expansions alter import dependency and pricing dynamics for finished lubricants.
Market Dynamics
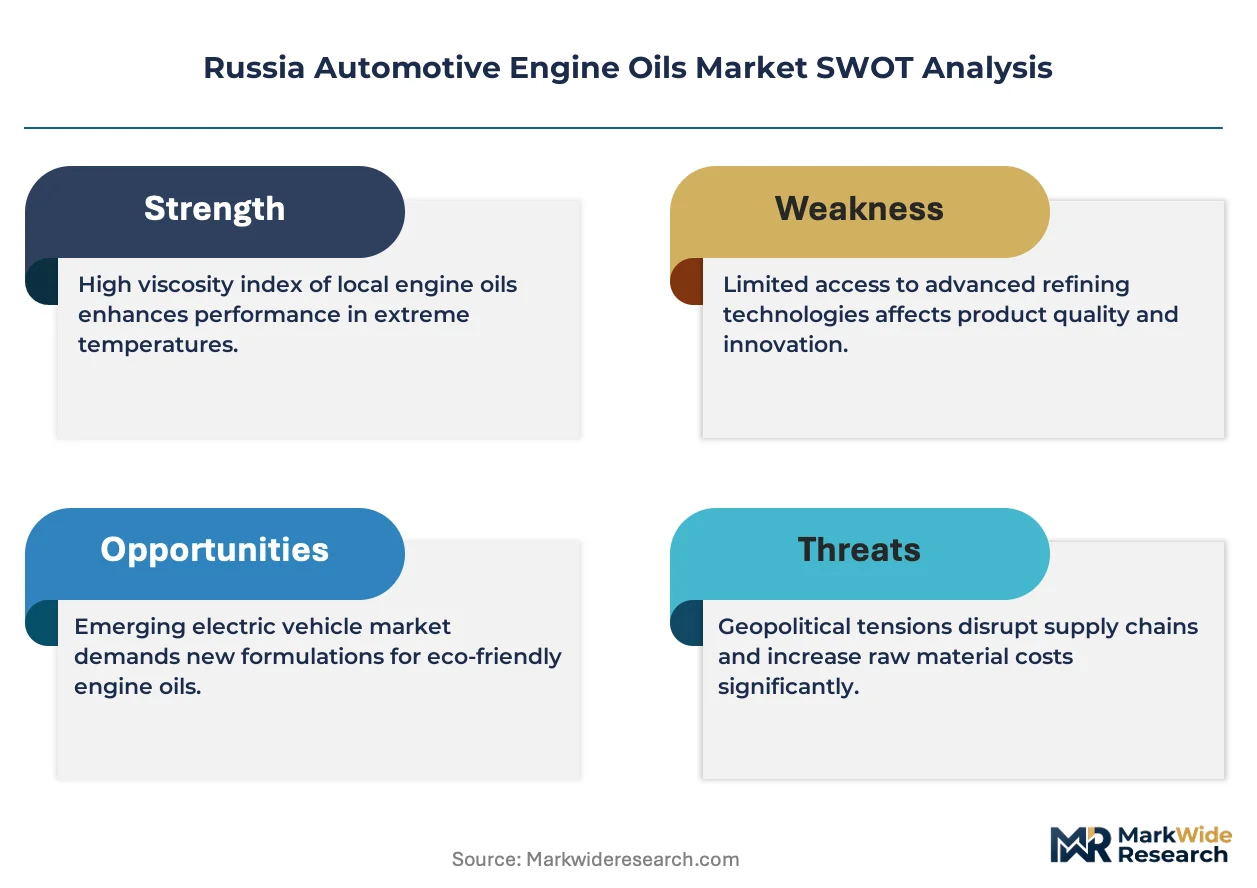
Russia's automotive engine oils sector is experiencing structural pressure from domestic base oil capacity expansions that are progressively reducing import dependency for Group II and III base stocks. This supply-side reconfiguration is altering pricing power dynamics between integrated refiners and independent blenders while Rosstandart quality mandates accelerate formulation upgrades.
Growth Catalysts
- Commercial Fleet Expansion:Long-haul logistics operators in the Central Federal District are extending vehicle replacement cycles, driving consumption of high-performance synthetic formulations with 15,000+ kilometer drain intervals.
- GOST-R Certification Alignment:Harmonization with international lubricant standards under Rosstandart technical regulations is enabling export-oriented Russian blenders to access Commonwealth of Independent States markets with reduced re-certification burden.
- Siberian Cold-Start Performance Requirements:Operating conditions in the Far Eastern Federal District and Krasnoyarsk Krai are creating pull for 0W-20 and 5W-30 low-temperature viscosity grades that minimize engine wear during sub-zero startups.
Market Restraints
- Base Oil Feedstock Concentration:Domestic Group II/III base oil production remains concentrated at three major refinery complexes, creating geographic supply vulnerability for independent lubricant blenders in the Northwestern Federal District.
- Additive Package Import Dependency:Performance chemicals including detergents, dispersants, and viscosity modifiers rely on shipments subject to payment system friction and logistics bottlenecks.
- Used Oil Collection Infrastructure Gaps:Federal environmental regulator enforcement of waste lubricant handling protocols outpaces re-refining capacity installation in the Southern and North Caucasian Federal Districts.
Strategic Opportunities
- Volga Federal District Industrial Hubs:Manufacturing clusters around Nizhny Novgorod and Samara present underpenetrated demand for specialized hydraulic-engine oil combinations serving automotive component production lines.
- Electric Vehicle Transition Preparation:Hybrid powertrain penetration is creating adjacent demand for thermal management fluids and transmission lubricants requiring reformulated additive chemistry.
- Service Station Channel Digitization:Lukoil and Gazpromneft retail networks are piloting predictive maintenance platforms that integrate oil change scheduling with telematics-driven consumption forecasting.
Industry Challenges
- Formulation Chemist Talent Scarcity:Russian technical universities produce limited graduates with specialized lubricant additive chemistry expertise, constraining R&D pipeline velocity for domestic blenders.
- Dual Certification Burden:Simultaneous compliance with GOST-R national standards and European Automobile Manufacturers Association (ACEA) specifications for imported vehicle service creates testing timeline compression.
- Legacy Fleet Viscosity Grade Mismatch:Older Russian and Soviet-era vehicle populations require mineral-based 15W-40 formulations that declining domestic production capacity struggles to supply economically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Engine Oils Market |
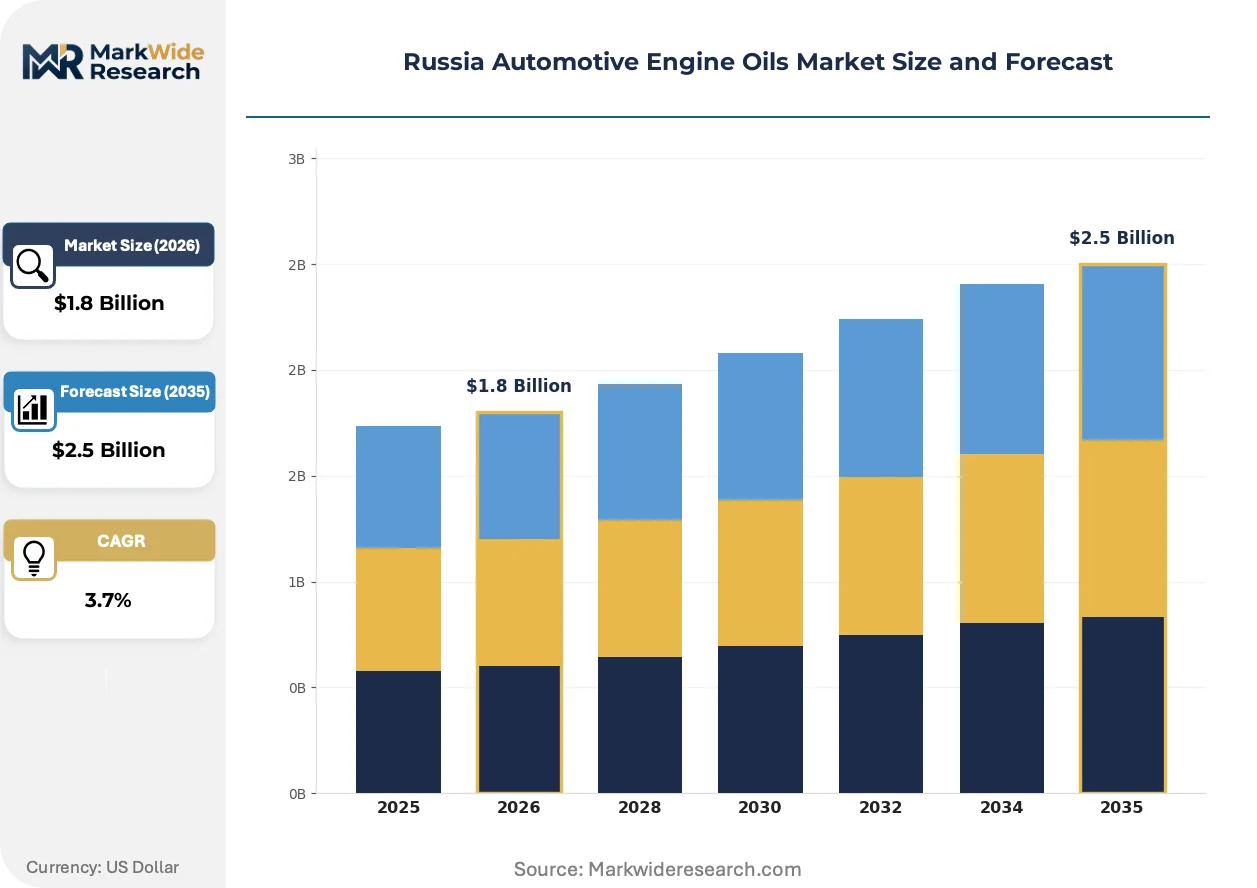
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Conventional, Mineral Viscosity Grade: 5W-30, 10W-40, 15W-40, 20W-50 Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Machinery, Motorcycles Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Service Stations |
| Companies Covered | Shell Plc, Exxon Mobil Corporation, Gazpromneft-Lubricants Ltd., LIQUI MOLY, FUCHS, Lukoil, BP plc, PJSC TATNEFT, Rosneft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as Russian lubricant stakeholders respond to tightening environmental enforcement and evolving vehicle technology requirements. These shifts are compressing traditional product lifecycles while opening new service revenue streams.
Advanced dispersant technology is migrating from conventional calcium-based chemistry to magnesium and hybrid detergent systems that maintain soot-handling capacity under extended drain intervals. Fleet operators operating Kamaz and GAZ commercial vehicles in the Ural Federal District are adopting these formulations at accelerating rates. This technology transition is compressing market share for legacy mineral oil products while elevating technical service requirements at point-of-sale channels.
Rosstandart implementation of updated technical regulations for lubricant quality marking is mandating enhanced labeling disclosure for base oil origin and additive content. The regulatory change is forcing reformulation transparency across the supply chain. Import-dependent blenders serving European passenger vehicle fleets in Moscow and Saint Petersburg are most affected, accelerating local sourcing verification systems.
Consolidated procurement by multi-site fleet operators is displacing fragmented spot purchasing through integrated supply agreements with volume-tiered pricing and technical support bundling. Independent service stations and smaller commercial vehicle operators are losing price competitiveness. This pattern is most visible in the Central Federal District where logistics company consolidation has concentrated buying power among ten major transport groups.
Russia Automotive Engine Oils Market Segmentation
Service intervals and formulation chemistry vary sharply across vehicle types and operating conditions in Russia. Segmentation reveals where margin concentration and volume expansion diverge.
Product Type:
After-sales-service intensity escalates with formulation sophistication as drain intervals extend and technical support requirements deepen.
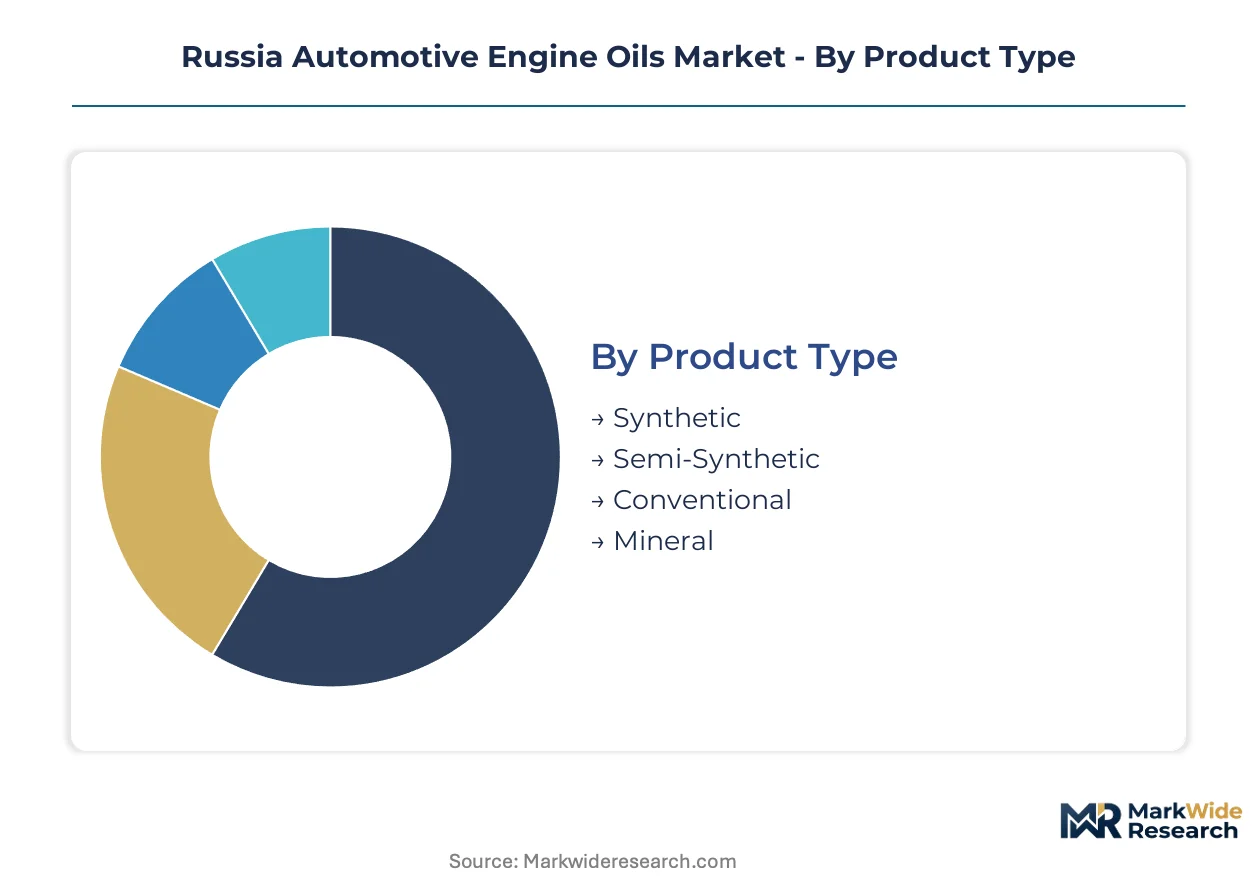
- Synthetic:Formulated from Group III and Group IV base stocks with advanced additive packages delivering viscosity stability across minus 35 to 200 degrees Celsius. Demand concentrates in long-haul commercial fleets operating in the Central Federal District where 15,000-kilometer drain intervals reduce downtime costs.
- Semi-Synthetic:Blends mineral and synthetic base stocks balancing cost performance for mid-tier vehicle owners. Adoption is accelerating in Siberian regions where cold-start protection requirements exceed conventional oil capabilities but full synthetic pricing strains fleet budgets.
- Conventional:Refined mineral base oils without synthetic content serving price-sensitive maintenance segments.
- Mineral:Unadditized or lightly additized petroleum distillates for legacy Soviet-era vehicle populations in rural districts.
Synthetic holds the largest share; momentum sits with Semi-Synthetic as price-performance trade-offs favor intermediate formulations.
Viscosity Grade:
Climate severity and OEM specifications drive grade selection across Russia's temperature extremes.
- 5W-30:Low-temperature pumpability combined with high-temperature shear stability for modern passenger vehicles. Demand concentrates in Moscow and Saint Petersburg where European-imported vehicle fleets require ACEA-compliant formulations.
- 10W-40:Versatile cold-start protection and operating temperature tolerance for mixed fleet compositions. Volume flows heaviest in the Volga Federal District where domestic vehicle production from AvtoVAZ and GAZ shapes OEM fill recommendations.
- 15W-40:Mineral-based formulations for older commercial vehicles and heavy-duty machinery in moderate climates.
- 20W-50:High-viscosity protection for worn engines and tropical operating conditions in Southern Federal District agricultural applications.
10W-40 commands volume leadership; 5W-30 is climbing the fastest on imported vehicle fleet expansion.
Application:
Operating duty cycles and equipment utilization rates determine formulation specifications and procurement patterns.
- Passenger Vehicles:Light-duty gasoline and diesel engines requiring fuel economy-optimized low-viscosity formulations. Service stations in the Central Federal District capture recurring revenue through scheduled maintenance programs tied to OEM warranty requirements.
- Commercial Vehicles:Kamaz and GAZ truck platforms operating extended duty cycles with severe soot loading. Mining and logistics operators in the Ural Federal District drive premium synthetic consumption through total cost of ownership calculations.
- Heavy-Duty Machinery:Off-highway equipment in oilfield and extractive industries requiring specialized hydraulic-engine oil combinations.
- Motorcycles:Small-displacement two-stroke and four-stroke engines with wet clutch compatibility requirements.
Passenger Vehicles anchor volume; Heavy-Duty Machinery shows steepest expansion trajectory on extractive industry capital deployment.
Distribution Channel:
Channel economics and customer acquisition costs segment procurement behavior across buyer types.
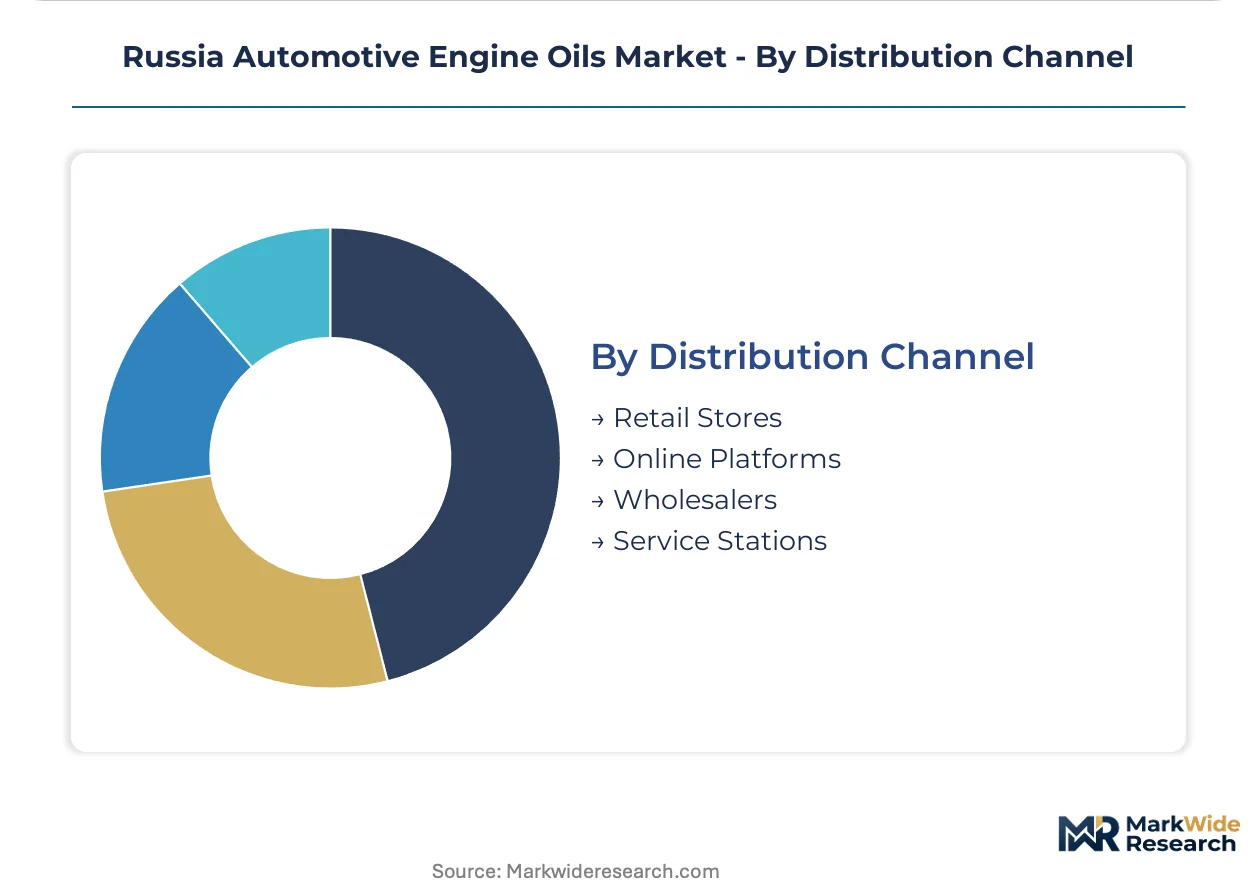
- Service Stations:Integrated retail networks offering oil change bundling with fuel and convenience services. Gazpromneft and Lukoil installations dominate the Central Federal District through loyalty program penetration and telematics-integrated scheduling.
- Retail Stores:Automotive parts chains and hypermarkets serving DIY maintenance segments with price-transparent shelf positioning.
- Online Platforms:E-commerce channels gaining traction in Moscow and Saint Petersburg for bulk purchasing by small fleet operators.
- Wholesalers:Regional distributors supplying independent service stations and industrial accounts with volume-tiered pricing.
Service Stations hold the largest share; Online Platforms are gaining share fastest on procurement digitization among younger vehicle owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Central Federal District demonstrate the lowest price elasticity, absorbing premium synthetic formulations, while operators in the Southern Federal District remain highly sensitive to per-liter costs. This demand gradient shapes regional formulation strategies and channel investments across Russia's federal districts.
Central Federal District
European-imported passenger vehicle fleets and consolidated logistics operators drive premium lubricant consumption in Moscow and the surrounding region. Rosstandart technical regulations for lubricant quality marking mandate enhanced labeling disclosure, elevating compliance costs for import-dependent blenders. The Moscow-Saint Petersburg corridor concentrates service station infrastructure where Gazpromneft and Lukoil loyalty programs capture recurring maintenance revenue.
Volga Federal District
Domestic vehicle production from AvtoVAZ and GAZ shapes OEM fill recommendations and aftermarket demand patterns around Nizhny Novgorod and Samara. The district's manufacturing clusters generate underpenetrated demand for specialized hydraulic-engine oil combinations serving automotive component production lines. Samara's industrial base is expanding procurement of thermal management fluids for hybrid powertrain applications.
Ural Federal District
Mining and long-haul logistics operators operating Kamaz truck platforms drive premium synthetic consumption through total cost of ownership calculations. Federal environmental regulator enforcement of waste lubricant handling protocols is accelerating re-refining capacity installation in Chelyabinsk and Yekaterinburg. The district's extractive industry capital deployment is pushing fastest growth in heavy-duty machinery lubricant segments.
Siberian Federal District
Sub-zero operating conditions in Krasnoyarsk Krai and the Far Eastern Federal District create structural demand for 0W-20 and 5W-30 low-temperature viscosity grades. Price-performance trade-offs favor semi-synthetic adoption where full synthetic pricing strains fleet budgets. Novosibirsk serves as the distribution hub for cold-start formulation supply chains extending into remote northern territories.
Northwestern Federal District
Saint Petersburg's European vehicle service market requires simultaneous GOST-R and ACEA specification compliance, compressing testing timelines for local blenders. Geographic supply vulnerability persists for independent lubricant blenders due to concentration of domestic Group II/III base oil production at distant refinery complexes. The district's port infrastructure facilitates additive package import flows subject to payment system friction.
Russia Automotive Engine Oils Market Competitive Landscape
Vertically integrated energy majors and specialized lubricant blenders split the market along supply security versus technical certification vectors. Three strategic archetypes dominate: captive refinery operators leveraging upstream base oil control, international technical specialists competing on OEM approval depth, and regional distributors optimizing last-mile coverage. Competitive moves center on retail network digitization for predictive maintenance integration and formulation chemistry upgrades addressing extended drain interval requirements.
Among Russia-based integrated operators, Gazpromneft-Lubricants Ltd. and Lukoil occupy positions anchored by captive refinery networks and service station channel density. Shell Plc and Exxon Mobil Corporation represent the international technical specialist archetype, competing on certification alignment with European vehicle manufacturer specifications. LIQUI MOLY and FUCHS sit within the mid-tier premium segment, balancing import-origin technical credibility with regional distribution partnerships.
| Leading Market Players |
|---|
| Shell Plc |
| Exxon Mobil Corporation |
| Gazpromneft-Lubricants Ltd. |
| LIQUI MOLY |
| FUCHS |
| Lukoil |
| BP plc |
| PJSC TATNEFT |
| Rosneft |
| Others |
Value Network & Pricing Analysis
Domestic Group II and III base oil production concentrated at three major refinery complexes in Russia's Volga and Ural regions directly determines where margin pools accumulate downstream. Independent blenders in the Northwestern Federal District face transport cost premiums that compress their pricing flexibility against integrated operators with captive supply.
Pricing Analysis
After-sales service revenue from extended drain interval programs drives lifetime value for synthetic formulation suppliers. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels segments buyers by fleet sophistication and climate exposure. Pricing pressure stems from Rosstandart labeling mandates elevating compliance costs for import-dependent blenders serving European vehicle fleets. Fleet operators in the Central Federal District show lowest price elasticity, absorbing ACEA-certified premiums, while agricultural buyers in the Southern Federal District resist per-liter cost escalation.
Supply Chain Analysis
Export-control friction on performance chemical shipments constrains additive package flows into Russian blending facilities. Base oil feedstock draws from domestic refinery complexes in Samara, Nizhny Novgorod, and Omsk, supplemented by Group III imports subject to payment system bottlenecks. Single-source vulnerability concentrates in detergent and dispersant chemistry sourced from Western suppliers facing sanctions complexity. Distribution runs through integrated service station networks for premium synthetic tiers, with wholesalers capturing price-sensitive mineral oil segments in remote districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive lubricant sector is approaching a platform-economics inflection as telematics-integrated predictive maintenance systems reshape how fleet operators procure and consume engine oils. Interoperability between oil condition monitoring sensors and service scheduling platforms is creating new ecosystem control points.
For Market Incumbents: Build data-network moats through telematics integration that locks fleet operators into predictive maintenance platforms. Gazpromneft and Lukoil retail networks should accelerate API development for third-party logistics software integration. Consolidate independent service station channels before digital procurement platforms erode geographic exclusivity. Capture formulation chemist talent pools through university partnership programs addressing Rosstandart's tightening certification timelines.
For New Entrants and Emerging Players: The Volga Federal District's automotive component manufacturing clusters present underpenetrated demand for hydraulic-engine oil combinations. Specialized thermal management fluids for hybrid powertrain assembly lines in Samara and Togliatti offer white-space entry with limited incumbent technical positioning. Partner with AvtoVAZ supplier development programs to secure OEM fill recommendations before synthetic formulation standards harden. Target mid-tier semi-synthetic positioning where price-performance trade-offs favor challengers over premium incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward blenders with verified GOST-R certification pipelines and established Commonwealth of Independent States export channels. Long-term viability hinges on domestic base oil backward integration or secured long-term offtake agreements with refinery operators. Watch for inflection in electric vehicle hybrid penetration rates as thermal management fluid demand displaces traditional engine oil volume pools. Acquisition targets should demonstrate additive chemistry R&D capabilities or exclusive distribution rights in Siberian cold-climate formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Locks fleet operators into predictive oil change scheduling through Gazpromneft and Lukoil loyalty ecosystems. |
| Domestic Base Oil Capacity Expansion | Reduces import dependency for Group III stocks while altering pricing power between integrated and independent blenders. |
| GOST-R Certification Pipeline Investment | Accelerates Commonwealth of Independent States market access with reduced re-certification burden under Rosstandart harmonization. |
| Hybrid Powertrain Fluid Development | Captures adjacent thermal management demand as AvtoVAZ and GAZ electrification programs advance. |
| Re-Refining Infrastructure Buildout | Addresses federal environmental regulator enforcement gaps in Southern and North Caucasian Federal Districts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across fleet procurement directors, lubricant blending plant managers, Rosstandart certification specialists, and aftermarket service station operators. Secondary validation incorporated customs trade data on base oil and additive package flows, GOST-R certification registry disclosures, vehicle production databases from AvtoVAZ and GAZ, and petroleum refinery capacity reports. Bottom-up triangulation across regional consumption patterns and top-down reconciliation with national lubricant demand estimates anchored volume and value outputs.
Calibration across the analysis window employed segmented growth modeling by product type, viscosity grade, vehicle application, and federal district distribution channel. CAGRs were derived from regression analysis against vehicle fleet composition shifts, OEM fill specification evolution, and environmental regulatory enforcement intensity. Industry-specific forecast inputs included drain interval extension rates among commercial logistics operators and hybrid powertrain penetration timelines from domestic automotive manufacturers.
Practitioners should monitor Rosstandart technical regulation amendments and base oil refinery capacity commissioning schedules for early signals of supply-side reconfiguration. Forecasts reflect documented assumptions on import substitution pace and additive chemistry sourcing stability. Material shifts in sanctions regime stringency or domestic Group III production economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Egypt Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Global Lubrication Systems Market
Lubricants
Norway Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Myanmar Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Sri Lanka Lubricants Market