
 United Kingdom Automotive Lubricants Market | 2026-2036
United Kingdom Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Automotive Lubricants Market Analytics
The UK's Euro 7 emission standards is repositioning lubricant specifications toward lower viscosity grades and extended drain intervals. Shell plc leverages its integrated refining and blending infrastructure to sustain cost advantages across England's Midlands distribution corridor. BP p.l.c. anchors its position through proprietary additive chemistry developed at its UK technology centers. ExxonMobil Corporation competes on global formulation platforms adapted specifically for the UK passenger car parc.
Automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with synthetic formulations typically achieving viscosity indices above 140 for stable performance across temperature extremes. The primary commercial purpose centers on extending equipment life while enabling compliance with manufacturer warranty requirements and emissions regulations. Engine oil dominates volume demand across the UK parc, though synthetic and semi-synthetic formulations capture disproportionate margin pools as OEM fill specifications tighten. Service centers remain the principal sales channel for commercial vehicle lubricants, where bulk delivery contracts and scheduled maintenance programs create sticky supplier relationships.
The Department for Transport and the Vehicle Certification Agency enforce emissions-linked lubricant standards that directly shape product registration and market access requirements. REACH compliance through ECHA governs additive chemistry composition, constraining formulation choices for suppliers serving the UK market. The Competition and Markets Authority monitors distribution channel practices, influencing how suppliers structure pricing and territorial arrangements with service centers and auto parts retailers. Stakeholders must track how the UK's evolving carbon border mechanisms and potential divergence from EU chemical regulations reshape sourcing economics for base oil and additive imports.
Market Dynamics
Fleet operators across England's industrial corridor are consolidating lubricant procurement around synthetic formulations that extend drain intervals. This shift compresses volume demand while concentrating margin pools among suppliers capable of meeting tightened OEM specifications.
Growth Catalysts
- Extended drain interval technology:Synthetic base stocks enable commercial vehicle operators to stretch service cycles from 30,000 to 100,000 miles. Fleet managers in Birmingham's logistics hub are standardizing these formulations to reduce downtime.
- REACH compliance frameworks:ECHA-mandated additive chemistry disclosures are filtering out subscale blenders. Surviving suppliers capture displaced volume as independent workshops face registration barriers.
- Net Zero Strategy alignment:The UK's CO2 emissions standards are mandating lower-viscosity lubricants in new vehicle registrations. Service centers are restocking 0W-20 and 5W-30 grades ahead of parc turnover.
Market Restraints
- Base oil supply concentration:Group III and PAO feedstocks flow predominantly from US Gulf Coast and Middle Eastern refiners. UK blenders face currency exposure and shipping cost volatility on dollar-denominated imports.
- Additive package cost structure:PAMA viscosity modifiers and boron friction reducers constitute 35-45% of finished lubricant cost. Formulators cannot pass through full input spikes to locked fleet contracts.
- Parc electrification trajectory:Battery electric vehicles eliminate engine oil demand entirely. London's ultra-low emission zone expansion is accelerating BEV penetration in the highest-mileage commercial segment.
Strategic Opportunities
- Thermal management fluids:E-axles and battery packs require dielectric coolants with tailored viscosity and conductivity profiles. Formulators with in-house ester chemistry capabilities can capture this emerging specification.
- Scotland's renewable energy corridor:Aberdeen's offshore wind maintenance fleets and Highland hydroelectric equipment operators represent underpenetrated demand for biodegradable hydraulic fluids and gear oils.
- Circular lubricant recovery:The UK's waste oil re-refining infrastructure is expanding. Suppliers offering closed-loop collection and re-refined base oil products can secure municipal and corporate sustainability procurement mandates.
Industry Challenges
- Formulation chemist scarcity:UK universities are producing fewer petroleum engineering specialists. Blenders compete with pharmaceutical and specialty chemical sectors for talent capable of balancing tribology performance with REACH compliance.
- OEM approval timeline compression:Volkswagen Group, Stellantis, and Ford are tightening certification cycles for new lubricant specifications. Smaller blenders lack capital to maintain parallel testing protocols across multiple OEM laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Automotive Lubricants Market |
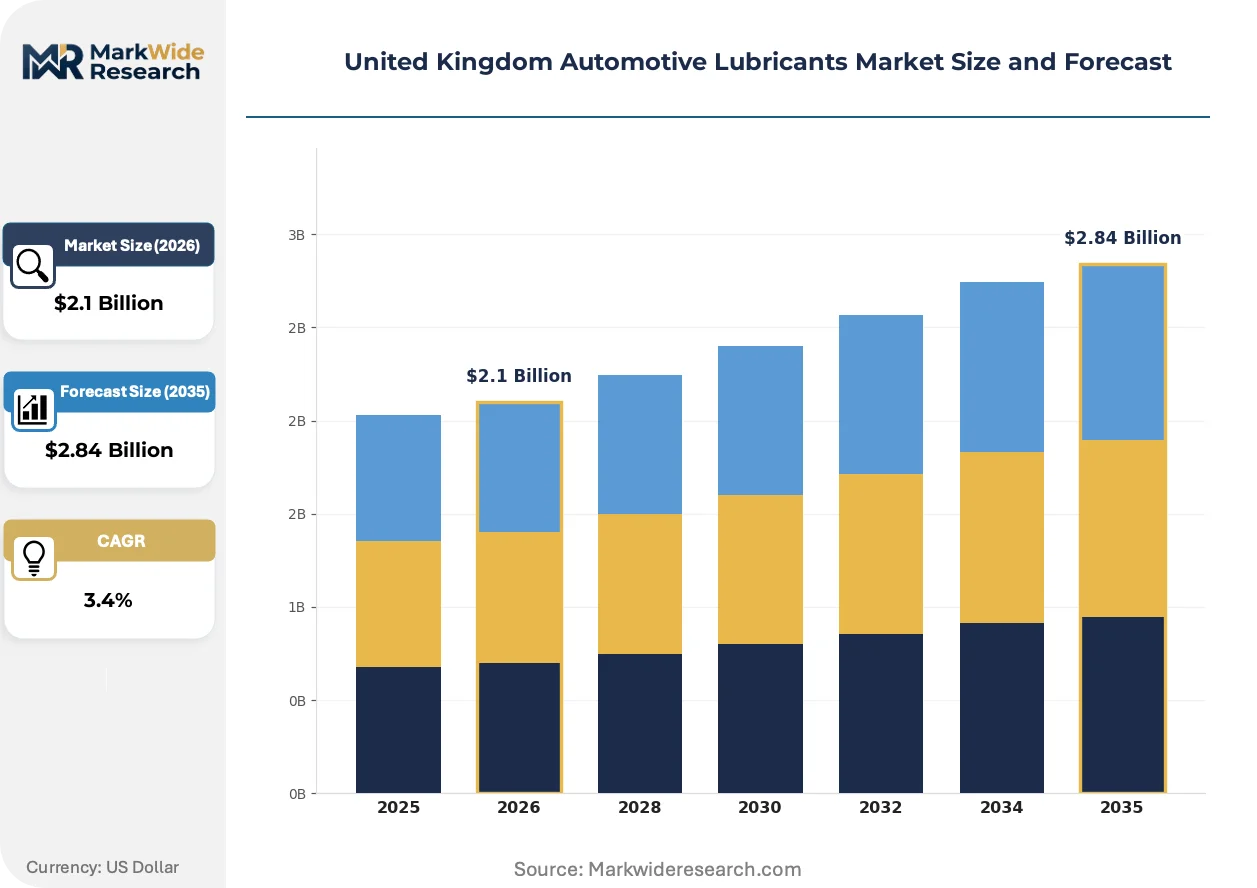
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Radiator Fluid Formulation: Synthetic, Semi-Synthetic, Mineral, Biodegradable Vehicle Type: Passenger Car, Commercial Vehicle, Motorcycle, Heavy-Duty Truck Sales Channel: Online Retail, Auto Parts Store, Dealerships, Service Centers |
| Companies Covered | TotalEnergies, Fuchs Group, BP p.l.c., Liqui Moly GmbH, Exol Lubricants Limited, Shell plc, Chevron Corporation, Motul S.A., ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Automotive Lubricants Market Evolving Landscape
Synthetic formulation chemistry is displacing mineral base stocks across commercial and passenger vehicle segments simultaneously. This transition is compressing traditional product lifecycles while opening specification gaps that specialized suppliers can exploit.
Polyalphaolefin (PAO) and gas-to-liquid (GTL) base stocks deliver viscosity stability from minus 40°C to 150°C operating temperatures. Premium fleet operators in Manchester's distribution cluster are specifying these grades for refrigerated transport and high-torque applications. The technology is electrifying competitive positioning around thermal oxidative stability rather than commodity volume.
The Department for Transport's Euro 7 implementation timeline is tightening particulate number limits for gasoline direct injection engines. Lubricant formulators must reduce sulfated ash, phosphorus, and sulfur content to protect exhaust aftertreatment systems. Low-SAPS (sulfated ash, phosphorus, sulfur) formulations are capturing disproportionate margin in London's compliance-sensitive parc.
Fleet procurement teams are consolidating suppliers through multi-year total cost of ownership contracts. Independent workshops and smaller hauliers are losing negotiating leverage as national logistics operators centralize lubricant buying. This concentration is most visible across England's M6 corridor, where Arrival, DPD, and Amazon fulfillment fleets have standardized on single-source synthetic supply agreements.
United Kingdom Automotive Lubricants Market Segmentation
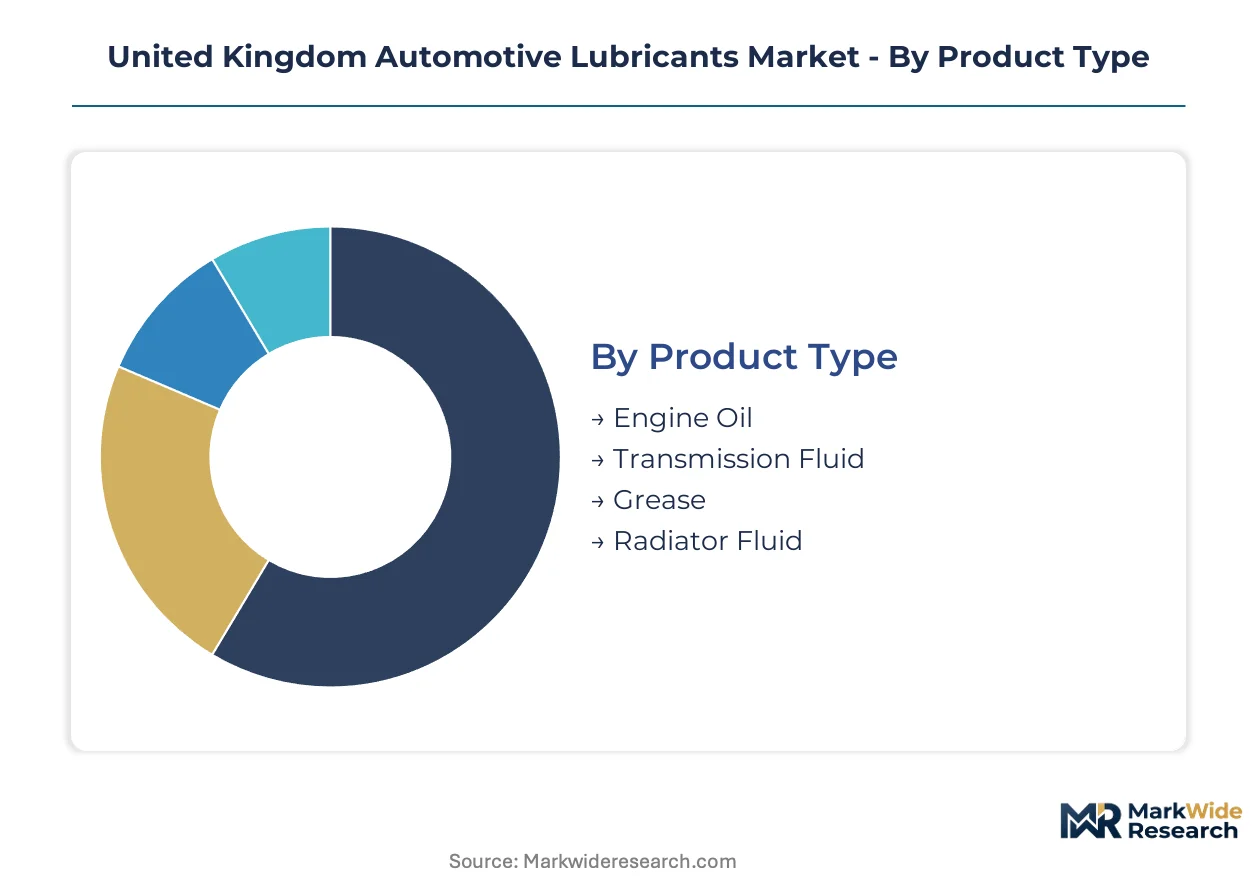
Segmentation in the UK automotive lubricants market reveals how formulation chemistry, vehicle duty cycles, and procurement channels create distinct margin pools. Suppliers must align product portfolios with the diverging technical requirements of fleet operators versus independent motorists.
Product Type:
Buyers differentiate by component protection requirements and thermal stress profiles across powertrain systems.
- Engine Oil:Formulated from Group II-III base stocks with detergent-dispersant additive packages to manage soot loading and acid neutralization. Demand concentrates in England's M6 corridor logistics hubs, where fleet operators specify low-SAPS formulations to protect exhaust aftertreatment systems under Euro 7 compliance timelines.
- Transmission Fluid:Synthetic ATF and manual transmission oils engineered for shear stability across 150,000-mile service intervals. Birmingham's commercial vehicle service centers are bulk-procuring dual-clutch compatible grades as ZF and Mercedes-Benz tighten OEM fill specifications.
- Grease:Lithium complex and calcium sulfonate thickened lubricants for chassis, wheel bearings, and fifth-wheel applications.
- Radiator Fluid:Ethylene glycol and propylene glycol-based coolants with corrosion inhibitor packages for aluminum engine block compatibility.
Engine Oil leads volumes today; Transmission Fluid is gaining share fastest.
Formulation:
Cost tiers separate buyers by drain interval targets and OEM warranty compliance requirements.
- Synthetic:PAO and GTL base stocks delivering viscosity indices above 140 for stable performance from minus 40°C to 150°C. Manchester's refrigerated transport fleets specify these grades to extend drain intervals from 30,000 to 100,000 miles.
- Semi-Synthetic:Blends of Group III base stocks with mineral components, occupying the mid-market for passenger vehicles outside manufacturer warranty periods. Scotland's independent workshops favor these formulations for cost-conscious private motorists.
- Mineral:Group I and II base stocks refined from solvent extraction and hydrocracking processes, serving legacy vehicle parc and budget maintenance segments.
- Biodegradable:Vegetable oil and synthetic ester base stocks for environmentally sensitive applications in offshore wind and hydroelectric maintenance operations.
Synthetic formulations command premium pricing; Biodegradable is expanding most quickly.
Vehicle Type:
Application severity drives specification divergence between light-duty and heavy-duty operating environments.
- Passenger Car:Low-viscosity 0W-20 and 5W-30 grades dominate as CO2 emissions standards tighten. London's ultra-low emission zone is accelerating parc turnover toward hybrid-compatible formulations.
- Heavy-Duty Truck:15W-40 and 10W-40 CK-4/FA-4 oils for high-boost diesel engines with exhaust gas recirculation and selective catalytic reduction systems. England's Midlands distribution clusters sustain bulk procurement through centralized fleet maintenance contracts.
- Commercial Vehicle:Light commercial vans and rigid trucks operating on mixed urban and motorway duty cycles.
- Motorcycle:JASO MA2 and API SN compliant oils for wet clutch compatibility and high-revving air-cooled engines.
Passenger Car lubricants generate the largest revenue pool; Heavy-Duty Truck shows the steepest margin compression from extended drain technology.
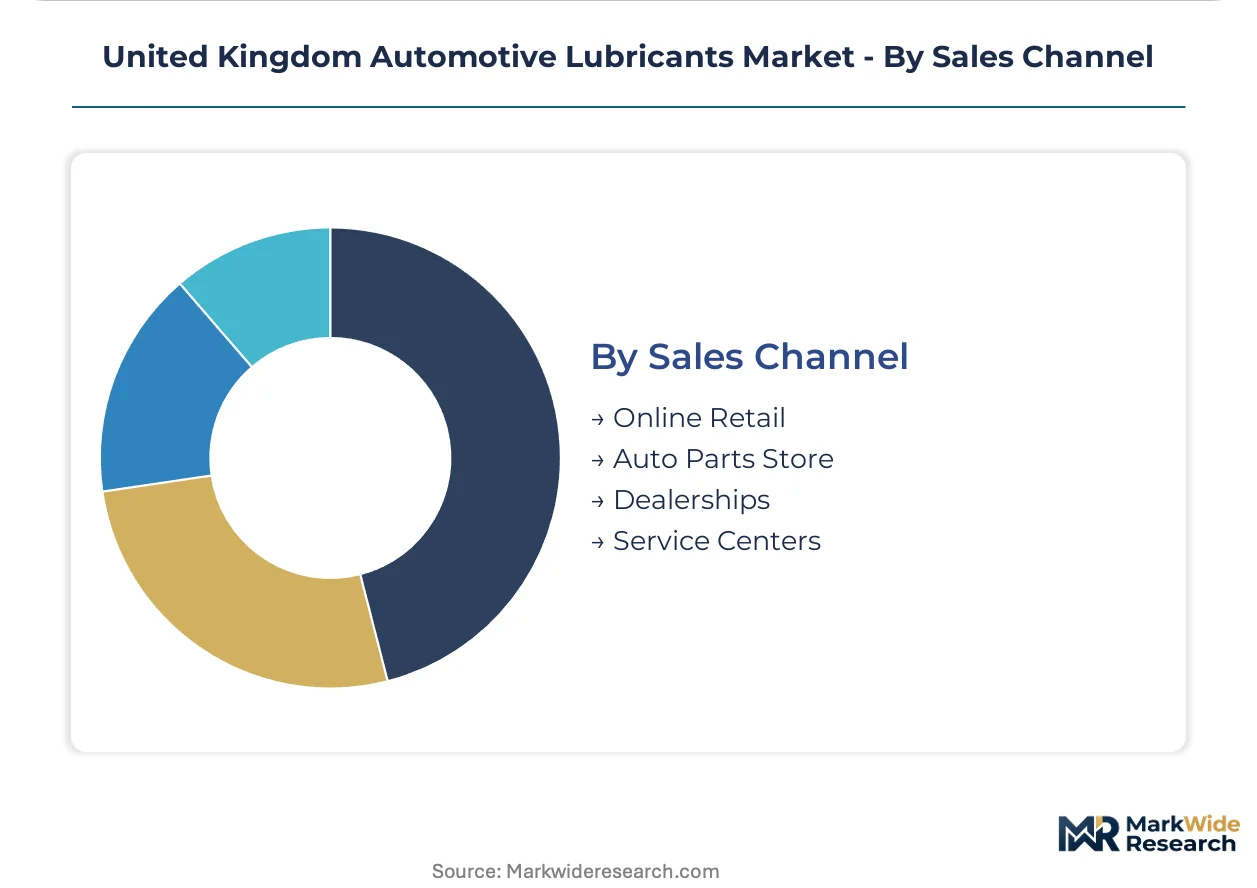
Sales Channel:
Customer procurement scale determines channel preference and supplier relationship stickiness.
- Service Centers:National chains and independent workshops performing scheduled maintenance with bulk tankage and waste oil collection infrastructure. Fleet operators in Birmingham and Manchester lock in multi-year supply agreements through these channels.
- Online Retail:Direct-to-consumer and B2B platforms capturing DIY maintenance and small workshop demand. REACH compliance documentation requirements filter out unregistered sellers, concentrating volume with established distributors.
- Auto Parts Store:Halfords and independent motor factors serving emergency top-up and consumer replacement cycles.
- Dealerships:Authorized repair networks specifying OEM-branded lubricants to maintain warranty compliance.
Service Centers anchor volume throughput; Online Retail is climbing the fastest as procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum chemists and tribology specialists cluster along England's industrial corridor, anchoring formulation expertise in the Midlands and Northwest. Scotland's offshore engineering workforce supports divergent demand for biodegradable hydraulic fluids.
London and the Southeast
Ultra-low emission zone expansion drives rapid parc electrification and hybrid-compatible lubricant restocking. The Department for Transport enforces Euro 7 particulate standards that mandate low-SAPS formulations. Service centers in Greater London concentrate procurement of 0W-20 grades ahead of compliance deadlines.
Midlands
Birmingham's logistics hub sustains bulk synthetic procurement for refrigerated transport fleets. REACH compliance through ECHA filters out unregistered blenders from the independent workshop base. Shell plc leverages integrated refining infrastructure across the distribution corridor to defend cost positions.
North England
Manchester's distribution clusters anchor multi-year fleet supply agreements with national logistics operators. The Competition and Markets Authority monitors territorial pricing arrangements between suppliers and service centers. DPD and Amazon fulfillment fleets have standardized on single-source synthetic formulations here.
Scotland
Aberdeen's offshore wind maintenance fleets generate underpenetrated demand for biodegradable hydraulic fluids and gear oils. The Scottish Government's renewable energy targets accelerate specification shifts away from mineral base stocks. Highland hydroelectric equipment operators represent emerging volume for ester-chemistry formulators.
Wales
Manufacturing clusters in South Wales sustain steady demand for industrial gear oils and metalworking fluids. The country's waste oil re-refining infrastructure expansion supports closed-loop collection mandates. Cardiff-based fleet operators are consolidating procurement around extended-drain synthetic formulations.
United Kingdom Automotive Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated majors with captive base oil supply. Three tiers separate global oil majors, mid-scale European specialists, and regional blenders serving independent workshops. Strategic moves concentrate on additive chemistry partnerships and re-refining capacity investments rather than price competition.
Among the integrated majors, Shell plc, BP p.l.c., and ExxonMobil Corporation exemplify archetypes built on refining integration and proprietary formulation platforms. TotalEnergies and Chevron Corporation occupy positions anchored in global supply networks adapted for UK specifications. European specialists including Fuchs Group, Liqui Moly GmbH, and Motul S.A. represent mid-tier players competing on OEM approval depth and workshop channel relationships. Regional blenders such as Exol Lubricants Limited sit within the independent service center segment where REACH compliance barriers are filtering competitive intensity.
| Leading Market Players |
|---|
| TotalEnergies |
| Fuchs Group |
| BP p.l.c. |
| Liqui Moly GmbH |
| Exol Lubricants Limited |
| Shell plc |
| Chevron Corporation |
| Motul S.A. |
| ExxonMobil Corporation |
| Others |
Value Network & Pricing Analysis
National logistics operators with centralized procurement functions dominate volume contracting across England's industrial corridor, locking in multi-year total cost of ownership agreements that compress spot market liquidity for independent blenders. Their consolidated buying power forces suppliers to bundle technical services, waste oil collection, and compliance documentation into headline pricing rather than competing on base product alone.
Pricing Analysis
Bundled service contracts incorporating technical support, scheduled delivery, and regulatory documentation capture premium positioning against unbundled transactional sales to independent workshops. Price differentiation rests on OEM approval depth and drain interval performance guarantees, with synthetic formulations commanding substantial premia over mineral alternatives. Pricing pressure stems from locked fleet contracts that prevent full pass-through of PAMA viscosity modifier and boron friction reducer cost spikes. Independent workshops and smaller hauliers exhibit acute price sensitivity, while national fleet operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Reverse logistics flows for waste oil collection and re-refined base oil recovery are expanding across the UK's circular economy infrastructure. Group III and PAO feedstocks draw predominantly from US Gulf Coast and Middle Eastern refiners, with additive packages resting on specialized chemical production concentrated in Germany and Belgium. Single-source vulnerability runs through dollar-denominated base oil imports exposed to currency volatility and shipping cost fluctuations. Distribution runs through England's Midlands blending facilities into service center bulk tankage and national retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK's automotive lubricants market functions as a regulatory compounder where Euro 7 emission standards and REACH compliance timelines continuously reshape product specifications and competitive barriers. The Department for Transport's particulate number limits for gasoline direct injection engines mandate low-SAPS formulations that filter out subscale suppliers.
For Market Incumbents: Anticipate accelerated parc electrification in London's ultra-low emission zone by deepening additive chemistry partnerships for thermal management fluids serving e-axle and battery pack applications. Lock in backward integration into re-refining capacity to defend margin position against circular economy mandates. Secure formulation chemist talent pools before pharmaceutical and specialty chemical sectors exhaust UK petroleum engineering graduate pipelines. For New Entrants and Emerging Players: Begin with biodegradable hydraulic fluid specifications targeting Aberdeen's offshore wind maintenance fleets and Highland hydroelectric equipment operators, where Scotland's renewable energy corridor remains underpenetrated by integrated majors. Pursue ester chemistry capabilities as the technical differentiator for dielectric coolant applications. Establish direct relationships with municipal sustainability procurement officers ahead of closed-loop collection mandate expansion. For Investors and Strategic Acquirers: Mid-scale European specialists with deep OEM approval portfolios are the most active acquirer targets in this space as certification timeline compression favors consolidated formulation platforms. The analysis window favors targets with captive re-refining infrastructure and established service center channel control. Monitor BEV penetration rates in commercial vehicle segments as the critical signal for long-term engine oil demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Capacity Expansion | Secures closed-loop supply chains against UK waste oil recovery mandates and corporate sustainability procurement. |
| Ester Chemistry Capability Buildout | Captures emerging thermal management fluid specifications for battery electric vehicle powertrains. |
| OEM Approval Portfolio Deepening | Defends market access as Volkswagen Group and Stellantis compress lubricant certification cycles. |
| Service Center Channel Consolidation | Locks in sticky relationships through bulk tankage infrastructure and scheduled maintenance program integration. |
| Low-SAPS Formulation Investment | Aligns product portfolios with Euro 7 sulfated ash, phosphorus, and sulfur limits enforced by the Vehicle Certification Agency. |
Research Methodology
Direct dialogue with lubricant blenders, fleet procurement managers, service center operators, and additive chemistry specialists grounded this analysis in operational reality across England's industrial corridor. Secondary validation drew from REACH registration databases, ECHA substance volume tracking, Vehicle Certification Agency type approval records, and customs trade data for base oil and additive imports. Bottom-up volume estimates from individual blender capacity and top-down demand models from vehicle parc analysis were triangulated to constrain forecast ranges.
Top-down macroeconomic drivers and bottom-up segment elasticity were modeled across the projection horizon. Segmentation dimensions included formulation chemistry tier, vehicle duty cycle severity, procurement channel scale, and regional regulatory compliance cluster. CAGRs were derived from trend extrapolation of synthetic penetration rates, drain interval extension trajectories, and electrification impact curves. Industry-specific inputs encompassed fleet turnover rates, OEM fill specification timelines, and re-refining capacity buildout schedules.
Several conditions sit outside the modeled scope, including potential UK divergence from EU chemical regulations, carbon border mechanism implementation timelines, and breakthrough battery thermal management technologies that could displace conventional dielectric fluids. Forecasts reflect assumptions around parc electrification pace and REACH enforcement consistency. Practitioners should monitor commercial vehicle BEV adoption curves and Scottish renewable energy procurement acceleration for early signals of specification demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Lubricants for Cement Industry Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Argentina Lubricants Market
Lubricants
Engine Oil and Lubricant Market