
 Biolubricants Market | 2026-2036
Biolubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Biolubricants Market Analytics
ISO 15380 HEES-grade specifications are bifurcating the competitive landscape into premium-certified and commodity-grade suppliers. TotalEnergies leverages its integrated biorefinery footprint to secure feedstock certainty across European distribution channels. Shell plc anchors its position through marine-sector partnerships requiring EAL compliance for vessel operations in sensitive waters. Fuchs Petrolub SE differentiates via specialized metalworking fluid formulations that meet both biodegradability and extreme-pressure performance thresholds.
Biolubricants are lubricating oils, greases, and functional fluids formulated from renewable biological feedstocks such as vegetable oils, synthetic esters, or microbial lipids, typically exhibiting greater than 60% biodegradability per OECD 301 test protocols and designed to reduce ecotoxicity in spill-prone environments. Vegetable oil-based formulations dominate volume production due to lower raw material costs and established supply chains, while synthetic esters command premium positioning in high-temperature hydraulic and aviation applications where oxidative stability determines equipment life. The automotive end-user segment remains the largest demand pool, though marine applications are expanding fastest as port authorities in Northern Europe mandate environmentally acceptable lubricants for in-water operations.
The European Chemicals Agency enforces REACH registration for bio-based feedstock derivatives, while the EPA's Vessel General Permit in the United States mandates EAL use in oil-to-sea interfaces for commercial shipping. Germany's Federal Environment Agency and the U.S. Coast Guard jointly shape technical standards that determine which formulations qualify for regulatory preference in their respective jurisdictions. Stakeholders must monitor evolving biodegradability certification thresholds and feedstock traceability requirements as these specifications increasingly determine market access rather than merely product positioning.
Market Dynamics
ISO 15380 HEES-grade certification is fragmenting supplier tiers into certified premium and uncertified commodity segments, forcing procurement departments to rewrite technical specifications and requalify vendor pools.
Growth Catalysts
- EU F-Gas Regulation:Mandates for biodegradable alternatives in refrigeration and air conditioning compressors are redirecting specification sheets toward ester-based formulations.
- Construction equipment fleets:Mining and earthmoving operators in Germany's industrial clusters are retrofitting hydraulic systems to meet site-level sustainability targets.
- OECD 301 biodegradability protocols:Standardized test methods are accelerating regulatory acceptance across multiple jurisdictions.
Market Restraints
- Vegetable oil feedstock volatility:Rapeseed and sunflower oil prices swing with agricultural harvest cycles and biofuel policy competition.
- Synthetic ester production concentration:Specialty chemical manufacturing clusters in Germany and the Netherlands control critical intermediate supply.
- REACH registration costs:ECHA compliance expenditures for novel bio-based derivatives exceed commodity lubricant economics.
Strategic Opportunities
- Aviation turbine oils:Bio-based synthetic esters meeting SAE AS5780 specifications are penetrating regional jet maintenance programs.
- Marine stern tube lubricants:Port authorities in Northern Europe are mandating EAL-compliant formulations for in-water operations.
- Metalworking fluid reformulation:Extreme-pressure biodegradable alternatives are displacing chlorinated paraffin in precision machining.
Industry Challenges
- Oxidative stability engineering:Formulation chemists with vegetable oil modification expertise remain scarce relative to demand.
- Dual certification timelines:Concurrent OECD 301 biodegradability and ISO 15380 HEES approvals extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biolubricants Market |
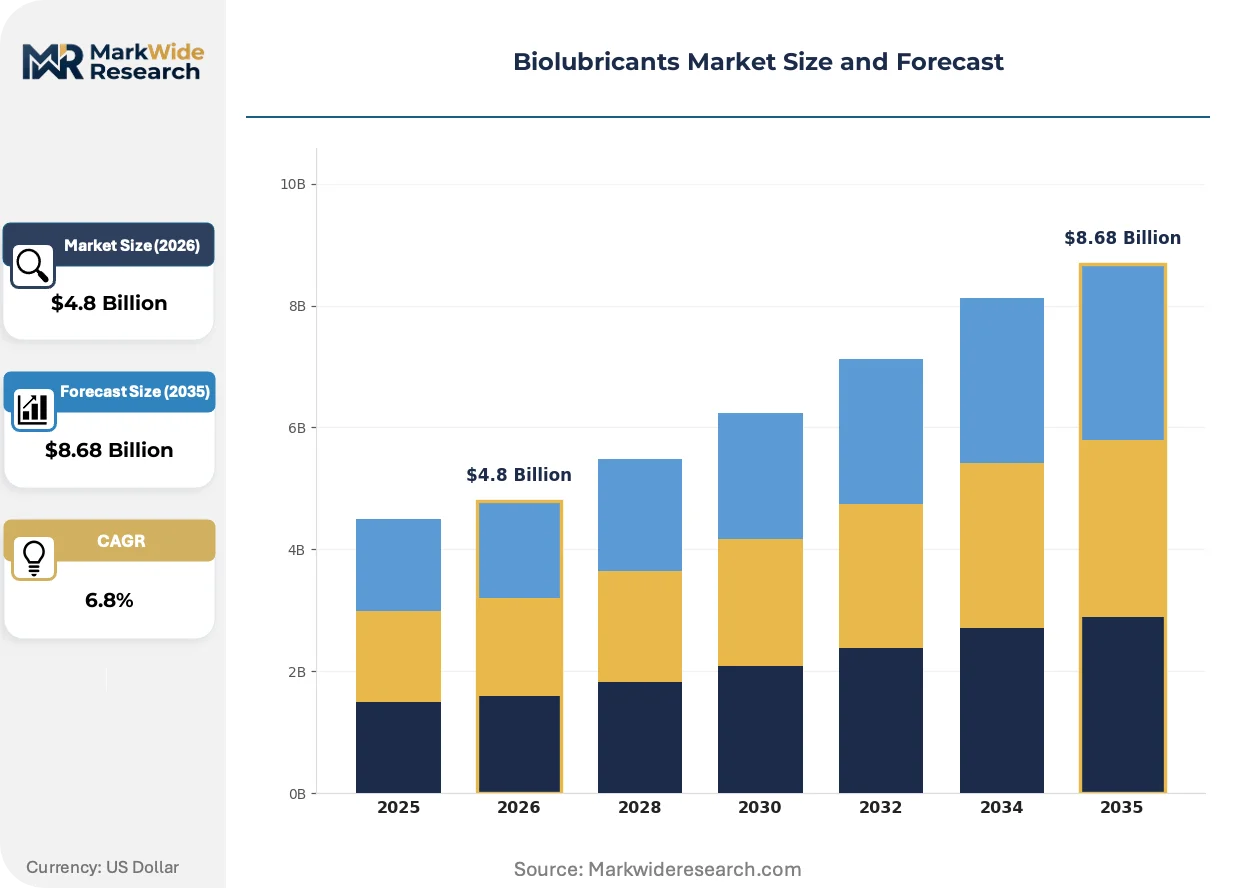
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Esters, Animal Fats, Vegetable Oils, Microbial Oils End User: Automotive, Industrial, Marine, Agriculture Application: Hydraulic Fluids, Greases, Metalworking Fluids, Gear Oils Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | TotalEnergies, Shell plc, Exxon Mobil Corporation, Fuchs Petrolub SE, Emery Oleochemicals, Chevron Corporation, BP plc, Klüber Lubrication, CASTROL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biolubricants Market Evolving Landscape
Formulation science is diverging along performance-versus-sustainability axes, with synthetic ester chemistry advancing fastest in high-stress applications where mineral oil alternatives fail.
Enzymatic transesterification is fragmenting process economics for high-oleic vegetable oil derivatives. Specialty chemical producers are licensing immobilized lipase catalysts to reduce energy inputs and improve product color stability. Marine lubricant blenders are adopting these processes fastest, as EAL compliance deadlines compress reformulation timelines.
REACH Annex XIV authorization requirements are tightening traceability obligations for bio-based feedstock derivatives. ECHA is expanding substance evaluation lists to cover modified vegetable oil oligomers used in hydraulic fluids. German metalworking fluid compounders are pre-registering supply chains to avoid authorization gaps.
Buyer technical committees are rewriting lubricant specifications to require third-party biodegradability certification. Automotive OEM procurement departments in Stuttgart and Munich are inserting OECD 301 pass/fail criteria into supplier quality agreements. This behavioral shift is most visible in German industrial clusters, where sustainability scorecards now weight lubricant environmental performance above price.
Biolubricants Market Segmentation
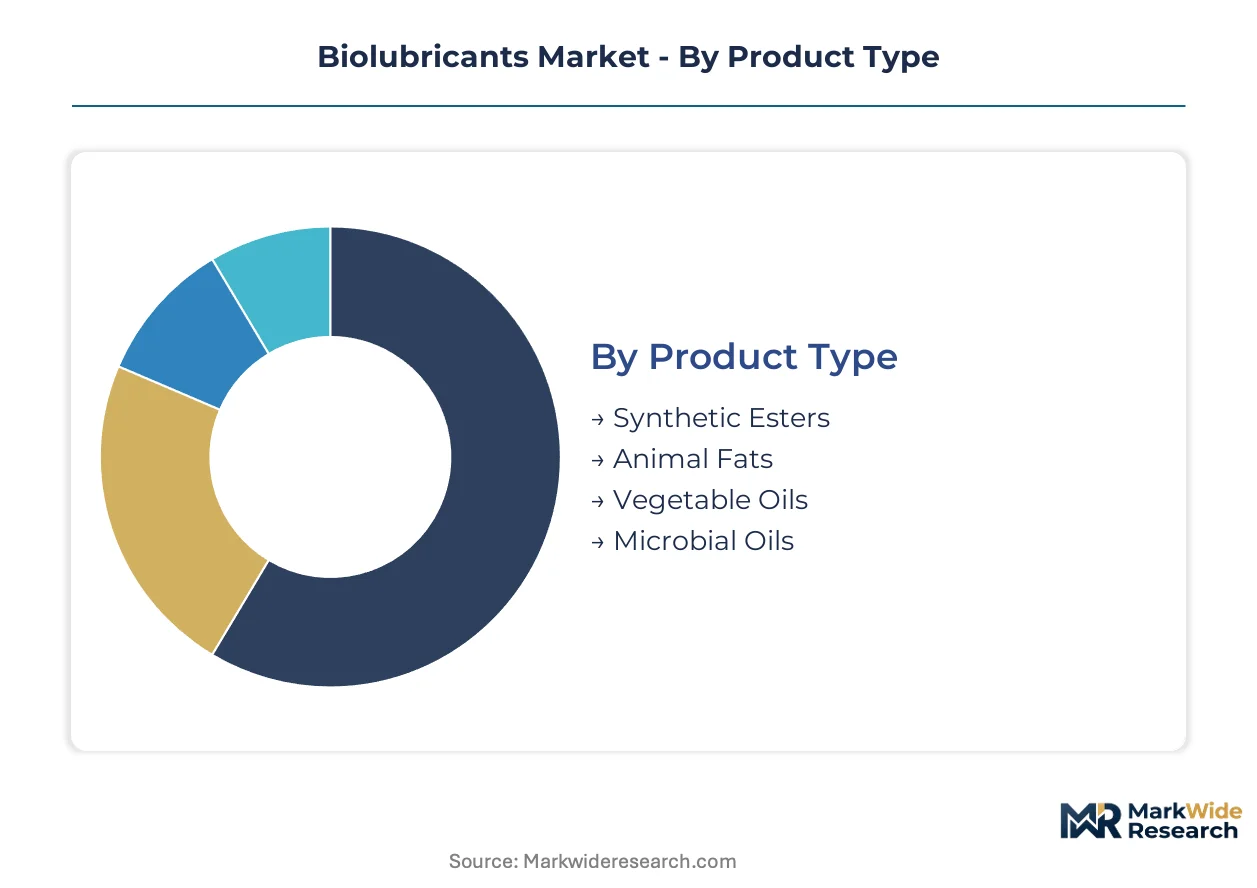
Product heterogeneity in biolubricants creates distinct competitive arenas where feedstock chemistry, performance specifications, and regulatory compliance intersect. Each segment carries unique substitution vulnerabilities—mineral oil incumbents in cost-sensitive tiers, synthetic alternatives in high-performance niches—that determine strategic positioning and investment priorities.
Product Type:
Vegetable oils face the most acute substitution pressure from low-cost mineral alternatives in commodity hydraulic applications, while synthetic esters defend premium positioning through performance gaps that mineral oils cannot bridge.
- Vegetable Oils:Formulations derived from high-oleic rapeseed and sunflower deliver baseline biodegradability at the lowest feedstock cost in the category. Demand concentrates in German construction equipment fleets where site-level sustainability mandates override price sensitivity, though harvest volatility and biofuel policy competition constrain supply security.
- Synthetic Esters:Engineered polyol esters and diesters achieve superior oxidative stability and extreme-temperature performance through controlled molecular architecture. Aviation turbine maintenance programs and marine stern tube applications in Northern European ports absorb volumes where SAE AS5780 and EAL compliance specifications exclude vegetable oil alternatives.
- Animal Fats:Tallow-derived bases offer cost positioning between vegetable oils and synthetic esters with established rendering supply chains. Industrial gear oil blenders leverage these feedstocks for applications requiring moderate biodegradability without full synthetic pricing.
- Microbial Oils:Fermentation-derived lipids from oleaginous yeasts and algae represent emerging feedstock technology with traceability advantages under REACH Annex XIV. Specialty chemical producers pilot these sources for metalworking fluids where modified vegetable oil oligomers face pending ECHA substance evaluation.
Vegetable oils retain volume leadership; microbial oils hold the steepest expansion curve.
End User:
Customer procurement sophistication varies sharply—automotive OEMs impose third-party certification requirements while agricultural buyers prioritize per-gallon economics.
- Automotive:Passenger vehicle and commercial fleet lubricant specifications increasingly embed OECD 301 pass/fail criteria into supplier quality agreements. Stuttgart and Munich industrial clusters drive specification tightening where sustainability scorecards weight environmental performance above unit cost.
- Marine:Port authorities in Hamburg, Rotterdam, and Antwerp mandate EAL-compliant formulations for in-water operations through vessel general permit analogs. Stern tube and thruster lubricant demand climbs fastest as Northern European regulatory deadlines compress reformulation timelines.
- Industrial:Metalworking, hydraulics, and compressor applications across manufacturing sectors absorb biolubricant volumes scaled to equipment life-cycle cost models. German Federal Environment Agency technical standards determine which formulations qualify for regulatory preference in procurement decisions.
- Agriculture:Tractor hydraulic systems and implement lubrication represent price-sensitive demand where vegetable oil economics compete most directly with mineral oil incumbents. Seasonal purchasing patterns and distributor credit terms shape supplier relationships more than certification premiums.
Automotive commands revenue concentration; marine gains share fastest.
Application:
Performance requirements stratify sharply—hydraulic fluids tolerate moderate specifications while metalworking demands extreme-pressure biodegradability.
- Hydraulic Fluids:Construction and mining equipment fleets absorb the largest application volumes, with German industrial clusters retrofitting machinery to meet ISO 15380 HEES-grade specifications. Mining operators balance biodegradability mandates against fire-resistance requirements in underground applications.
- Metalworking Fluids:Precision machining operations require extreme-pressure performance without chlorinated paraffin chemistries now restricted under REACH. Fuchs Petrolub SE and comparable compounders differentiate through specialized formulations that satisfy both biodegradability thresholds and tool life requirements.
- Greases:Thickened biolubricant formulations serve bearings and joints in food-processing and marine environments where incidental contact regulations apply. NLGI grade specifications and base oil viscosity selection determine suitability for centralized lubrication systems.
- Gear Oils:Industrial gearbox and transmission applications demand anti-wear additive packages compatible with biodegradable base stocks. Wind turbine maintenance programs in Northern Europe represent emerging demand as OEM service contracts specify environmental lubricants.
Hydraulic fluids dominate tonnage; metalworking fluids climb the fastest.
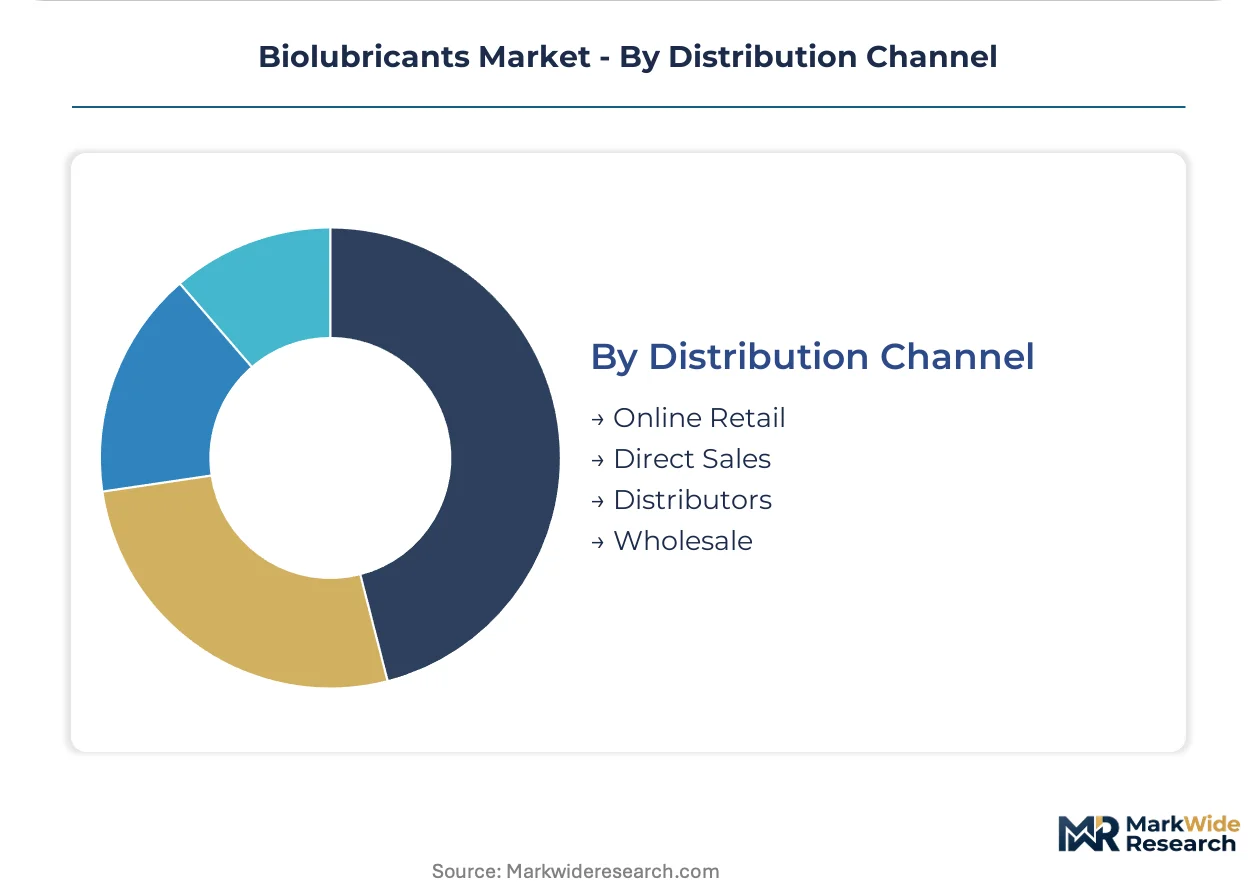
Distribution Channel:
Channel economics reflect lubricant volume scale and technical service intensity required for specification compliance.
- Distributors:Industrial lubricant distributors maintain formulation blending capabilities and technical field service teams that support ISO 15380 requalification programs. German mid-market manufacturers rely on these intermediaries for inventory management and waste oil collection services.
- Direct Sales:National account structures serve automotive OEMs and marine fleet operators with dedicated technical representatives. TotalEnergies and Shell plc anchor positions through integrated biorefinery supply security and marine-sector partnership frameworks.
- Wholesale:Volume lubricant merchants supply agricultural and small industrial accounts where price transparency and credit terms outweigh technical service requirements. Rapeseed oil feedstock cost pass-through mechanisms determine competitive positioning.
- Online Retail:E-commerce penetration remains limited to standardized packaged lubricants for consumer automotive and small equipment maintenance. Product authentication and biodegradability certification verification pose barriers to significant share expansion.
Distributors retain channel leadership; direct sales expands most quickly in marine and automotive OEM verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical manufacturing clusters in Germany and the Netherlands control critical intermediate supply for synthetic ester production, while regulatory enforcement in Northern European ports creates concentrated demand pockets for environmentally acceptable lubricants.
Germany
Industrial clusters around Stuttgart and Munich are retrofitting machinery fleets with bio-based alternatives as site-level sustainability targets override price sensitivity. The Federal Environment Agency shapes technical standards that determine which formulations qualify for regulatory preference in procurement decisions. Baden-Württemberg's automotive OEM procurement departments embed OECD 301 pass/fail criteria into supplier quality agreements.
Netherlands
Rotterdam port authorities mandate EAL-compliant formulations for in-water operations through vessel general permit analogs, compressing reformulation timelines for marine lubricant blenders. REACH registration requirements for bio-based feedstock derivatives concentrate compliance expertise in specialty chemical manufacturing clusters. Amsterdam-based distributors maintain formulation blending capabilities that support ISO 15380 requalification programs.
United States
The EPA's Vessel General Permit mandates EAL use in oil-to-sea interfaces for commercial shipping, creating regulatory pull in coastal states. Construction equipment operators in Texas and California balance biodegradability mandates against fire-resistance requirements in underground mining applications. Midwest agricultural machinery fleets represent price-sensitive demand where vegetable oil economics compete directly with mineral oil incumbents.
France
Île-de-France industrial procurement departments weight lubricant environmental performance above unit cost in sustainability scorecards. ANSM traceability obligations for bio-based feedstock derivatives tighten supply chain documentation requirements. Lyon-based metalworking fluid compounders pre-register supply chains to avoid REACH Annex XIV authorization gaps.
United Kingdom
London marine insurers are inserting EAL compliance clauses into hull coverage terms for vessels operating in sensitive waters. The Environment Agency enforces biodegradability certification thresholds that determine market access rather than merely product positioning. Midlands manufacturing sectors absorb biolubricant volumes scaled to equipment life-cycle cost models.
Biolubricants Market Competitive Landscape
Concentration sits with integrated energy majors and specialty chemical producers that control biorefinery feedstock security and formulation expertise. The supplier base fragments across certified premium and uncertified commodity tiers as ISO 15380 HEES-grade specifications force procurement departments to rewrite technical specifications. Three archetypes dominate: integrated majors with captive biorefinery supply, specialty compounders with extreme-pressure formulation expertise, and regional distributors with technical field service capabilities. Competitive moves center on strategic partnerships for marine-sector compliance and enzymatic transesterification licensing for process economics.
Within the integrated majors tier, TotalEnergies and Shell plc exemplify players leveraging biorefinery footprint to secure feedstock certainty across European distribution channels. Fuchs Petrolub SE occupies a position among specialty compounders that differentiate through metalworking fluid formulations meeting both biodegradability and extreme-pressure performance thresholds. These three anchors represent how competitive positioning stratifies between supply security, formulation specialization, and technical service intensity.
| Leading Market Players |
|---|
| TotalEnergies |
| Shell plc |
| Exxon Mobil Corporation |
| Fuchs Petrolub SE |
| Emery Oleochemicals |
| Chevron Corporation |
| BP plc |
| Klüber Lubrication |
| CASTROL Limited |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German biorefineries determines feedstock cost floors for synthetic ester producers, concentrating pricing power among integrated majors while forcing vegetable oil compounders into commodity margin compression. This scale asymmetry bifurcates the supplier landscape into ISO 15380-certified premium tiers and uncertified economy alternatives.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating biodegradable alternatives in compressor applications, elevating ester-based formulations above vegetable oil substitutes. Pricing stratifies across ISO 15380 HEES-certified premium, REACH-registered standard, and uncertified economy tiers. Cost compression in vegetable oil segments intensifies because agricultural harvest volatility and biofuel policy competition squeeze rapeseed feedstock economics. Agricultural machinery buyers exhibit the highest price sensitivity, while marine fleet operators absorbing EAL compliance mandates show the least.
Supply Chain Analysis
Rotterdam port congestion on North Sea trade lanes elevates inbound logistics costs for specialty chemical intermediates, compressing blender margins across Northern European distribution networks. Manufacturing gravity centers on Germany, the Netherlands, and Belgium, where synthetic ester production clusters control critical polyol supply. Feedstock security hinges on high-oleic rapeseed, sunflower oil, and palm-derived fatty acids. Single-source vulnerability concentrates in enzymatic catalyst licensing from immobilized lipase technology holders. Distribution runs through industrial lubricant distributors with ISO 15380 requalification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral oil incumbents with established cost structures pose the central substitution threat as bio-based premiums erode, forcing biolubricant producers to defend positioning through certification moats rather than price competition alone.
For Market Incumbents: Fortify feedstock certainty through captive biorefinery capacity or long-term offtake agreements with high-oleic oilseed processors. Deepen ISO 15380 HEES-grade certification coverage to create procurement stickiness against mineral oil price undercutting. Prioritize enzymatic transesterification licensing to reduce energy inputs and defend margin structure against vegetable oil volatility. For New Entrants and Emerging Players: Anchor in microbial oil fermentation technology to bypass agricultural commodity cycles and satisfy REACH Annex XIV traceability requirements ahead of ECHA substance evaluation timelines. Target aviation turbine maintenance programs where SAE AS5780 specifications exclude incumbent vegetable oil alternatives. Pursue direct technical sales to regional jet operators rather than distributor channel buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty compounders with extreme-pressure formulation expertise over integrated majors exposed to biorefinery capex cycles. Five-to-ten-year viability rests on regulatory ratcheting rather than voluntary sustainability adoption. Acquisition screening should prioritize metalworking fluid compounders with concurrent OECD 301 and ISO 15380 approvals. The signal to monitor is ECHA expansion of authorization lists to modified vegetable oil oligomers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Captive high-oleic rapeseed supply secures margin stability against biofuel policy competition. |
| Enzymatic Transesterification Licensing | Immobilized lipase catalyst adoption reduces energy intensity for marine lubricant blenders facing EAL deadlines. |
| ISO 15380 HEES Certification Investment | Third-party biodegradability verification unlocks automotive OEM procurement in Stuttgart industrial clusters. |
| Marine Sector Partnership Framework | EAL-compliant stern tube formulations satisfy Rotterdam port authority mandates for in-water operations. |
| REACH Annex XIV Pre-Registration | Supply chain documentation readiness avoids authorization gaps for modified vegetable oil oligomers. |
Research Methodology
Desk research of customs trade data, ECHA substance registration databases, and SEC chemical sector filings preceded structured interviews with lubricant formulation chemists, automotive OEM procurement directors, marine fleet technical superintendents, and industrial distributor account managers. Primary fieldwork captured specification rewriting behaviors and requalification timelines. Secondary validation drew from OECD test protocol documentation, ISO standards repositories, and port authority regulatory notices. Bottom-up volume builds across product grades triangulated against top-down market sizing from feedstock consumption patterns.
Variance decomposition across feedstock cost trajectories, regulatory enforcement intensity, and substitution elasticity shaped the analytical framework over the projection horizon. Segmentation modeling captured product type heterogeneity, end-user procurement sophistication tiers, application performance requirements, and channel service intensity levels. CAGRs derived from segment-level volume forecasts weighted by value-per-ton differentials. Industry-specific inputs included enzymatic process adoption curves and EAL mandate implementation schedules across Northern European ports.
Material uncertainties — agricultural commodity price spikes, REACH authorization timeline delays, and mineral oil price collapse scenarios — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory ratcheting consistency and biofuel policy stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Kenya Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Marine Grease Market