
 Printing Ink Additives Market | 2026-2036
Printing Ink Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Ink Additives Market Analytics
Flexible packaging demand is hardening as the dominant pull force for printing ink additives, displacing slower-growth publication segments. BASF SE leverages its pigment dispersant portfolio to anchor supply relationships with multinational flexible packaging converters across Europe and Asia. Evonik Industries AG competes through specialized defoamer and substrate wetting technologies tailored for high-speed flexographic lines. Dow Inc. differentiates via silicone-free surfactant platforms that address both foam control and regulatory compliance in food-contact applications.
Printing ink additives comprise functional chemical modifiers—typically surfactants, dispersants, rheology modifiers, and stabilizers—blended at 0.5-5.0 wt% to control viscosity, pigment distribution, drying speed, and substrate adhesion during ink manufacturing and application. These additives determine print fidelity, production efficiency, and compliance with substrate-specific performance requirements across packaging, commercial, and industrial printing operations. Liquid dispersant formulations lead volume consumption due to compatibility with dominant water-based and UV-curable ink systems, while powder thickeners occupy a narrower but higher-margin niche in specialty screen and gravure applications. Packaging applications sustain the fastest growth trajectory as e-commerce fulfillment and shelf-ready branding requirements intensify substrate versatility demands.
REACH restrictions on volatile organic compound emissions and FDA food-contact notification requirements directly shape additive selection criteria, disqualifying legacy chemistries and creating qualification barriers for new entrants. ECHA substance evaluations and state-level US EPA air quality mandates are forcing reformulation investments across solvent-borne segments. Stakeholders must monitor evolving PFAS restrictions in both European and North American jurisdictions, as fluorinated surfactants face phasedown timelines that will disrupt existing ink performance specifications and supplier certifications.
Market Dynamics
Water-based ink reformulation is forcing additive suppliers to rebuild dispersant architectures from the ground up as converters abandon solvent-borne systems under tightening VOC mandates.
Growth Catalysts
- EU REACH Annex XVII restrictions:VOC emission limits in Germany and France are accelerating solvent-to-aqueous ink transitions, creating demand for compatible surfactant and rheology modifier chemistries.
- Flexible packaging converters:E-commerce fulfillment requirements in India and China are driving substrate versatility needs that only advanced wetting agents and adhesion promoters can satisfy.
- UV-LED curing technology:Photoinitiator-stabilizer packages are integrating into high-speed flexographic lines to enable instant curing on heat-sensitive films.
Market Restraints
- Petrochemical feedstock volatility:Acrylate monomer and silicone intermediate price swings compress additive margins and destabilize long-term supply contracts.
- Specialty chemical supply concentration:Fluorinated surfactant production clusters in Belgium and Japan create geographic vulnerability as PFAS phasedowns approach.
- Performance ceiling in aqueous systems:Water-based dispersants still fail to match solvent-grade pigment loading efficiency in high-density metallic inks.
Strategic Opportunities
- Brazil and Mexico:Underpenetrated flexographic packaging markets lack qualified local additive blending capacity, opening technical partnership models.
- US FDA food-contact notification pathways:Streamlined additive approval processes for indirect food contact are incentivizing early-mover qualification investments.
- Bio-based dispersant platforms:Convergence of enzymatic synthesis and agricultural waste feedstocks is enabling renewable-content claims for premium brand owners.
Industry Challenges
- Formulation chemist scarcity:Expertise in pigment surface chemistry and colloidal stability is retiring faster than universities replenish trained talent.
- Multi-jurisdiction certification lag:Simultaneous EU REACH, US FDA, and China GB standard compliance extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Ink Additives Market |
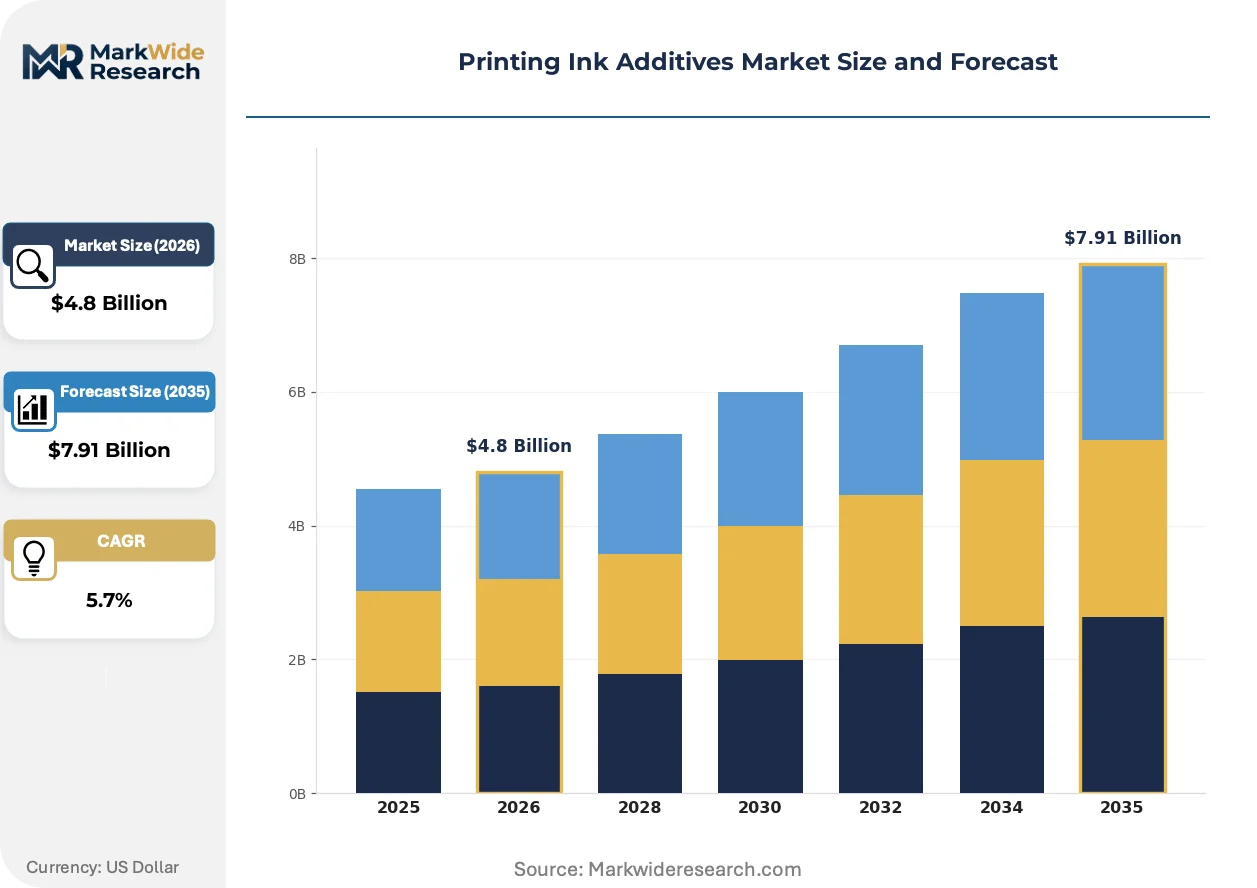
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersants, Stabilizers, Thickeners, Surfactants Application: Packaging, Commercial Printing, Publication, Coatings Form: Liquid, Powder, Paste, Granular End User: Packaging Manufacturers, Printing Houses, Publishing Firms, Label Producers |
| Companies Covered | BASF SE, Evonik Industries AG, Clariant AG, Lubrizol Corporation, Eastman Chemical Company, ALTANA AG, Elementis Plc, Münzing Corporation, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Ink Additives Market Evolving Landscape
Hybrid additive architectures are displacing single-function chemistries as converters demand simultaneous foam control, substrate wetting, and regulatory compliance from single-product platforms.
Silicone-polyether block copolymer defoamers are integrating into water-based flexographic ink systems to eliminate surface defects without compromising substrate adhesion. High-volume corrugated packaging operations in the US and Germany are adopting these multifunctional additives to reduce SKU complexity and inventory carrying costs. This integration is compressing demand for standalone mineral oil defoamers and legacy polydimethylsiloxane products.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing reformulation of surfactants used in UV-curable overprint varnishes. The industrial consequence is a qualification race for hydrocarbon-based and organo-modified siloxane alternatives that can match surface tension reduction performance. Food-contact flexible packaging applications in Italy and Spain are most affected, with converters pressuring suppliers for drop-in replacements ahead of phasedown deadlines.
Specification consolidation among multinational brand owners is compressing approved additive lists to pre-qualified global platforms. Tier-1 flexible packaging converters in the Netherlands and Japan are replacing regional formulation variations with standardized ink additive packages that satisfy multiple end-customer sustainability scorecards. This behavioral shift is most visible in the premium snack and personal care segments, where dual-brand supply contracts now mandate identical chemistries across production sites.
Printing Ink Additives Market Segmentation
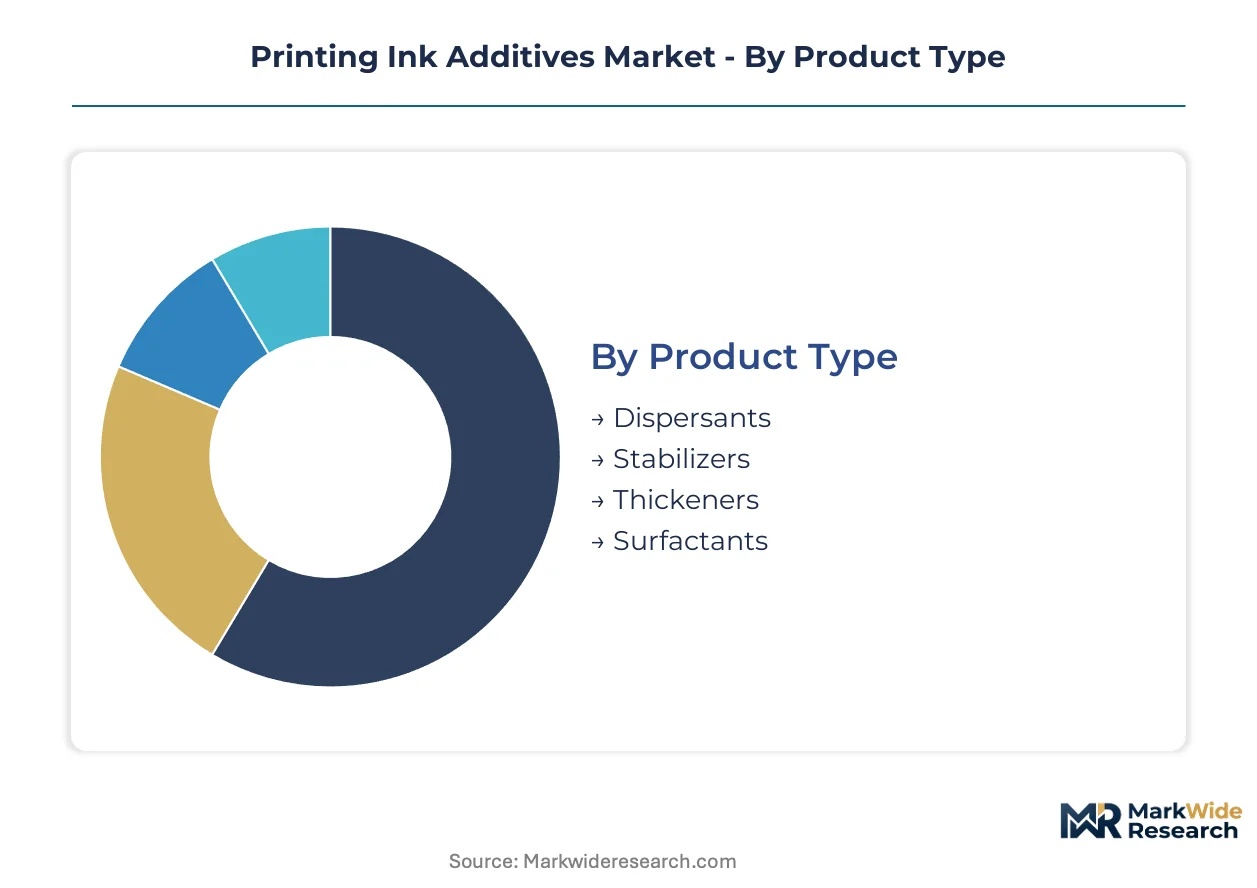
Segmentation in printing ink additives reveals how regulatory burden and formulation complexity concentrate value in specific product architectures. Understanding these divisions exposes where qualification investments yield sustainable margin protection.
Product Type:
Dispersants carry the heaviest certification load under EU REACH and US FDA food-contact frameworks, while surfactants face escalating PFAS scrutiny across multiple jurisdictions.
- Dispersants:Pigment-stabilizing chemistries—typically polymeric or surfactant-based—govern color consistency and loading efficiency in water-based and UV-curable systems. Demand hardens in Germany and India where flexible packaging converters abandon solvent-borne inks under tightening VOC mandates. REACH Annex XVII compliance costs favor suppliers with pre-qualified polymer architectures.
- Surfactants:Surface-active agents control wetting, foam, and substrate adhesion across flexographic and gravure lines. Food-contact applications in Italy and Spain are forcing urgent reformulation as EU F-Gas Regulation phases down fluorinated surfactants. Hydrocarbon and organo-modified siloxane alternatives command qualification premiums.
- Stabilizers:Photoinitiator stabilizers and antioxidant packages protect ink integrity during UV-LED curing and shelf storage.
- Thickeners:Rheology modifiers in powder and liquid forms adjust viscosity for screen printing and high-build coating applications.
Leading the category by volume: Dispersants. Expanding most quickly: Surfactants as fluorinated replacements gain share.
Application:
Packaging applications absorb the majority of technical service resources as converters navigate multi-jurisdiction food-contact approvals simultaneously.
- Packaging:Flexible and corrugated substrates demand additives that satisfy FDA notification, EU REACH, and China GB standards in parallel. E-commerce fulfillment requirements in India and China intensify substrate versatility needs. UV-LED curing integration on high-speed flexographic lines drives photoinitiator-stabilizer demand.
- Commercial Printing:Point-of-sale and promotional materials require rapid-drying formulations with lower regulatory burden than food-contact segments.
- Publication:Magazine and catalog printing represents a contracting segment as digital displacement accelerates in North American and European markets.
- Coatings:Overprint varnishes and specialty finishes occupy a narrower volume position with higher margin concentration.
Packaging dominates absolute consumption. Coatings delivers the steepest expansion trajectory as brand owners specify premium protective finishes.
Form:
Liquid formulations concentrate supply relationships with multinational ink manufacturers, while powder forms serve fragmented specialty screen printing operations.
- Liquid:Pre-dispersed additive concentrates compatible with continuous manufacturing processes at large-scale ink plants. Water-based liquid dispersants lead volume in Germany, China, and India where environmental compliance accelerates solvent-to-aqueous transitions.
- Powder:Dry thickeners and stabilizers for small-batch screen and gravure applications where shipping economics favor solid forms.
- Paste:High-viscosity concentrates for specific gravure and specialty coating segments.
- Granular:Free-flowing solid additives for automated dosing in continuous production environments.
Liquid forms anchor the category by volume. Powder forms are climbing the fastest as regional specialty printers upgrade from manual to semi-automated batching.
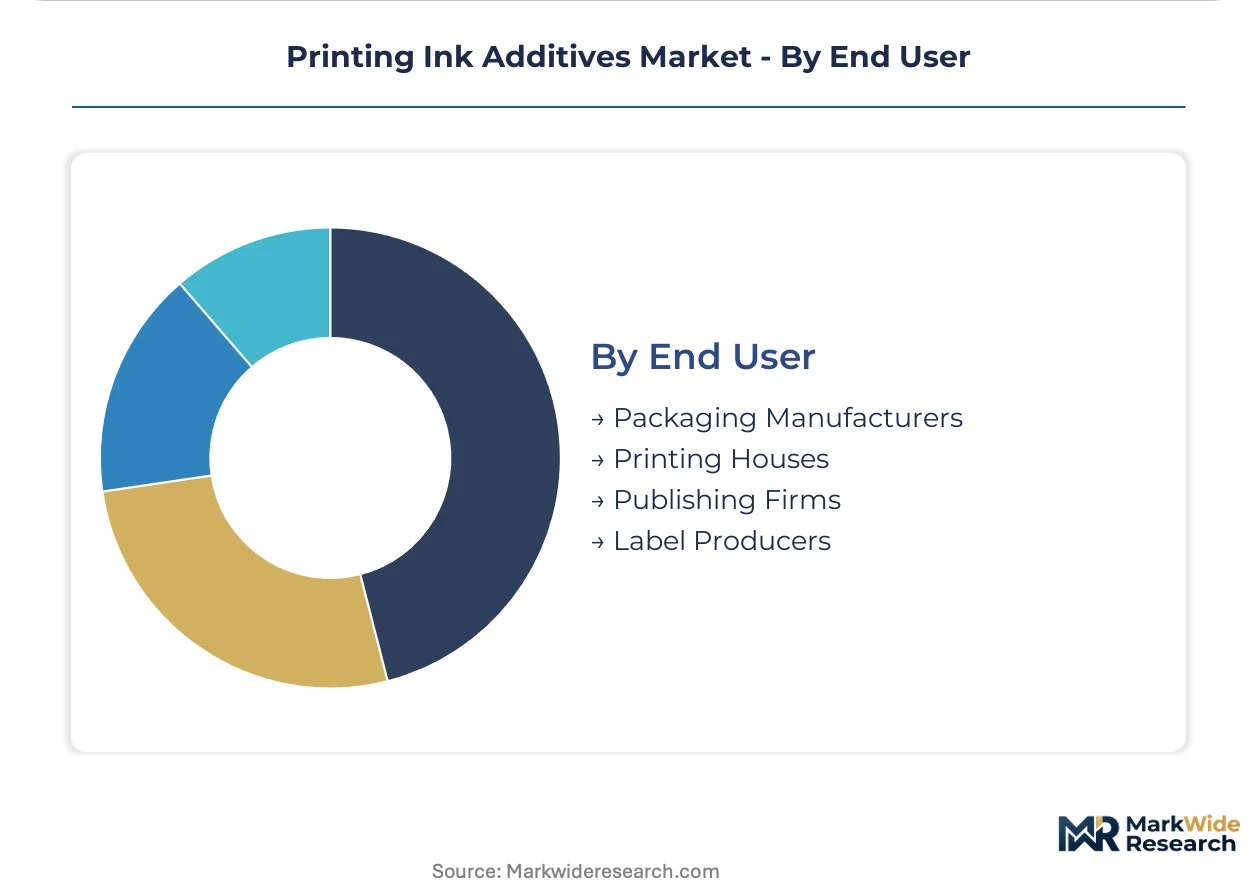
End User:
Packaging manufacturers consolidate purchasing power through global specification standards, while printing houses retain fragmented procurement patterns.
- Packaging Manufacturers:Multinational flexible packaging converters in the Netherlands and Japan are replacing regional formulation variations with standardized additive packages. Dual-brand supply contracts in premium snack and personal care segments now mandate identical chemistries across production sites.
- Printing Houses:Commercial and publication printers operate on thinner margins with less technical staff to manage additive qualification.
- Publishing Firms:Declining segment with contracting additive demand as print runs shorten and digital alternatives expand.
- Label Producers:Pressure-sensitive and shrink-sleeve label operations require precise adhesive and release control additives.
Packaging manufacturers lead the category by volume. Label producers are gaining share fastest as beverage and pharmaceutical labeling requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate additive blending capacity for India's flexible packaging export corridor. These zones attract multinational ink manufacturers seeking duty-advantaged supply positions for Middle Eastern and African markets.
Germany
Flexible packaging converters in Baden-Württemberg and Bavaria drive dispersant demand as solvent-to-aqueous transitions accelerate under REACH Annex XVII VOC limits. The country's central bank monitors industrial chemical export credit exposure amid feedstock price volatility. Stuttgart and Munich host technical service clusters supporting multinational brand owner qualification programs.
China
E-commerce fulfillment requirements in the Yangtze River Delta and Pearl River Delta intensify substrate versatility needs for water-based ink systems. GB standards for food-contact materials tighten additive selection criteria for domestic and export packaging. Shanghai and Shenzhen concentrate UV-LED curing technology integration on high-speed flexographic lines.
United States
Corrugated packaging operations in the Midwest and Southeast adopt multifunctional silicone-polyether defoamers to reduce SKU complexity. FDA food-contact notification pathways incentivize early-mover qualification investments for indirect food contact applications. Chicago and Atlanta anchor technical service networks serving multinational flexible packaging converters.
India
Flexible packaging demand hardens in Maharashtra and Gujarat as domestic e-commerce fulfillment requirements expand substrate versatility specifications. BIS standards alignment with EU REACH creates dual-certification burdens for additive suppliers. Mumbai and Ahmedabad concentrate regional blending capacity serving South Asian export markets.
Japan
Specification consolidation among multinational brand owners drives standardized additive package adoption in Kanto and Kansai regions. METI industrial chemical regulations enforce substance evaluation timelines that compress product launch windows. Tokyo and Osaka host qualification laboratories supporting dual-brand supply contract requirements.
Printing Ink Additives Market Competitive Landscape
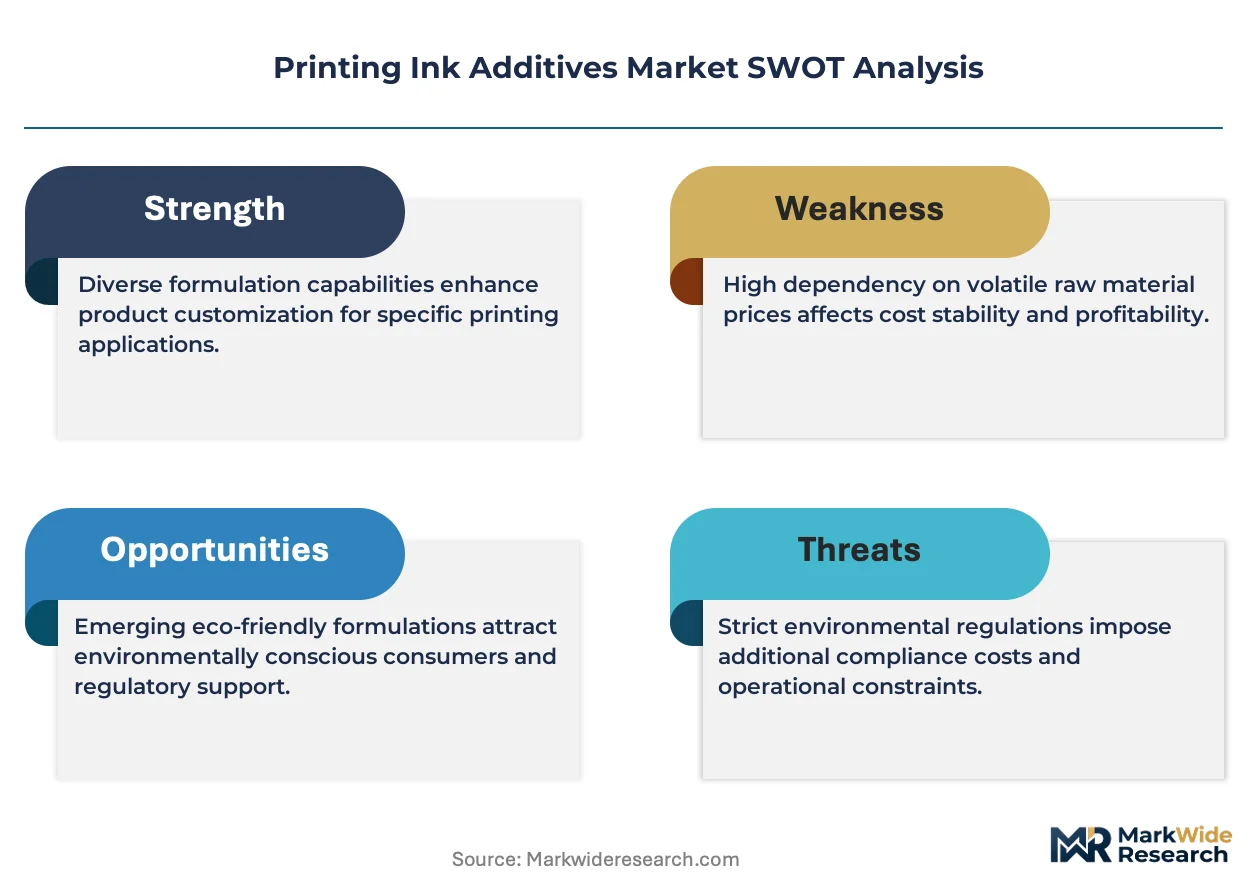
Top-tier vendors anchor multinational supply relationships, while mid-cap specialists occupy regional blending niches. The market exhibits tiered concentration with three to five global suppliers commanding pre-qualified additive portfolios under REACH and FDA frameworks. Strategic archetypes include integrated petrochemical conglomerates with captive dispersant synthesis, specialized surfactant houses with fluorinated replacement expertise, and regional formulators with local certification agility. Dominant competitive moves encompass backward integration into bio-based feedstocks and technology licensing partnerships for UV-LED stabilizer platforms.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify scale-driven positions with pre-qualified polymer architectures spanning multiple jurisdictions. Evonik Industries AG occupies a specialist position in defoamer and substrate wetting technologies. These three anchors represent distinct competitive vectors: BASF SE leverages pigment dispersant breadth, Dow Inc. emphasizes silicone-free surfactant compliance positioning, and Evonik Industries AG concentrates on high-speed flexographic line performance specifications.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Clariant AG |
| Lubrizol Corporation |
| Eastman Chemical Company |
| ALTANA AG |
| Elementis Plc |
| Münzing Corporation |
| Dow Inc. |
| Others |
Value Network & Pricing Analysis
Flexible packaging converter consolidation into global specification standards is forcing additive suppliers to maintain redundant qualification inventories across multiple jurisdictions, compressing margin structures for non-pre-qualified chemistries. This procurement centralization rewards suppliers with REACH and FDA pre-certifications while marginalizing regional formulators lacking multi-market dossiers.
Pricing Analysis
Short lead-time premiums for REACH-compliant dispersant concentrates command 15-25% markups over standard delivery windows in Germany and India. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified food-contact grades from industrial packaging chemistries and commodity mineral oil defoamers. Pricing pressure stems from petrochemical feedstock volatility in acrylate monomer and silicone intermediate markets. Small regional formulators exhibit highest price sensitivity, while multinational flexible packaging converters absorb premiums for qualification security.
Supply Chain Analysis
REACH and FDA qualification gating concentrates supply relationships with additive suppliers possessing pre-filed polymer architectures, excluding new entrants without multi-year certification investments. Manufacturing clusters in Germany, China, and India anchor global dispersant production, with raw material dependencies on acrylic acid, silicone intermediates, and specialty surfactant feedstocks. Single-source vulnerability concentrates in fluorinated surfactant production facilities in Belgium and Japan ahead of PFAS phasedown deadlines. Distribution runs through multinational ink manufacturer direct procurement channels and regional chemical distributor networks serving specialty printers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-qualified additive capacity under REACH and FDA frameworks operates at effective utilization ceilings, propping pricing premiums for certified chemistries as converter consolidation intensifies specification standardization.
For Market Incumbents: Cement supply relationships with multinational flexible packaging converters through dedicated technical service clusters in Stuttgart and Shanghai. Expand backward integration into bio-based dispersant feedstocks to defend margin position against petrochemical volatility. Prioritize UV-LED stabilizer platform licensing partnerships ahead of high-speed flexographic line upgrades in China and the United States. For New Entrants and Emerging Players: The premium-to-economy price gap in food-contact surfactants offers entry points for hydrocarbon-based fluorinated replacements in Italy and Spain. Target underqualified local additive blending capacity in Brazil and Mexico through technical partnership models rather than greenfield investment. Lead with streamlined FDA notification pathway expertise for indirect food contact applications to bypass incumbent qualification timelines. For Investors and Strategic Acquirers: The window for entry favors specialized surfactant houses with organo-modified siloxane expertise and existing EU F-Gas Regulation compliance positioning. Long-term viability hinges on defluorination transition execution across the packaging value chain. Monitor PFAS restriction timeline acceleration in European and North American jurisdictions as the primary inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Agricultural waste enzymatic synthesis enables renewable-content claims for premium brand owner specifications. |
| UV-LED Stabilizer Platform Licensing | Photoinitiator-stabilizer packages capture high-speed flexographic line upgrades in Shanghai and Shenzhen manufacturing clusters. |
| Multi-jurisdiction Qualification Investment | Simultaneous EU REACH, US FDA, and China GB compliance compresses product launch timelines for early movers. |
| Regional Blending Partnership in Latin America | Technical collaboration models address underpenetrated Brazilian and Mexican flexographic packaging markets lacking qualified local capacity. |
| Fluorinated Surfactant Replacement R&D | Hydrocarbon and organo-modified siloxane alternatives command qualification premiums ahead of EU F-Gas Regulation phasedown deadlines. |
Research Methodology
Multi-period observation of formulation chemist retirement rates, REACH Annex XVII compliance cost trajectories, and flexible packaging converter specification consolidation anchored the trend analysis, supplemented by interviews with additive R&D directors, procurement leads at multinational ink manufacturers, technical service managers, and regulatory affairs specialists. Secondary validation drew from ECHA substance evaluation databases, FDA food-contact notification filings, SEC 10-K chemical segment disclosures, and Cefic industrial chemical trade statistics. Bottom-up segment sizing triangulated against top-down petrochemical feedstock consumption models.
Input-output matrices mapped dispersant, surfactant, and stabilizer demand to water-based, UV-curable, and solvent-borne ink production volumes across packaging, commercial, and publication end-uses. Segmentation dimensions spanned product chemistry architecture, ink system compatibility, food-contact certification tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted consumption models incorporating VOC mandate enforcement timelines and substrate versatility requirements. Forecast inputs included e-commerce fulfillment growth corridors and UV-LED curing technology adoption curves.
Underlying measurement precision varies by segment; REACH-compliant food-contact dispersants carry tighter precision than commodity mineral oil defoamers due to certification documentation density. Forecasts embed assumptions regarding PFAS restriction implementation pace and petrochemical feedstock price stabilization. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or FDA food-contact notification pathway streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Asia Pacific Silage Additives Market
Additives
Global Feed Acidulants Market
Additives
Impact Modifier Market
Additives
Sorbitan Tristearate Market
Additives
Defoaming Coating Additives Market
Additives
Calcium Acetate Market
Additives
Citrate Ester Market
Additives
Cold Flow Improvers Market
Additives
Epoxy Type Stabilizers Market
Additives
Saudi Arabia Feed Additives Market
Additives
Dipotassium Guanylate Market
Additives
Sorbitan Oleate Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Biofuel Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Ethoxyquin Market