
 Marine Lubricants Market | 2026-2036
Marine Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Lubricants Market Analysis
Singapore is narrowing its position as the premier marine lubricant blending and distribution hub for Asia-Pacific vessel traffic. ExxonMobil Corporation leverages integrated supply chains from refinery to port to sustain cost advantages in high-volume ports. Shell plc anchors its position through specialized cylinder oil formulations designed for dual-fuel engines. BP p.l.c. competes on technical service density, embedding engineers directly with operator fleets.
Marine lubricants are formulated base oil and additive packages engineered to withstand high-salinity environments, extreme pressure loads, and extended drain intervals in propulsion and auxiliary systems. They typically incorporate detergents, dispersants, anti-wear agents, and corrosion inhibitors balanced for residual fuel combustion byproducts. Engine Oils command the largest volume share given crankcase and cylinder lubrication demands across commercial fleets, while Hydraulic Fluids generate premium pricing in offshore operations where equipment reliability carries operational risk. Greases represent a concentrated margin pool in stern tube and deck machinery applications where re-lubrication access is limited.
The International Maritime Organization enforces sulfur content limits through MARPOL Annex VI, directly dictating base oil selection and additive chemistry for compliant lubricants. The EPA regulates vessel emissions in United States waters, creating segmented product registration requirements for operators on trans-Pacific routes. Classification societies including DNV and Lloyd's Register certify lubricant performance against machinery warranty conditions, effectively gatekeeping market access. Stakeholders must monitor bio-based lubricant standard development and carbon intensity accounting rules to anticipate product line transitions.
Market Dynamics
IMO 2020 sulfur regulations have forced a complete reformulation of marine lubricant chemistry, compressing margins for blenders while creating specialized product tiers for dual-fuel engine compatibility across container and bulk carrier fleets.
Growth Catalysts
- IMO 2020 Sulfur Cap:Mandates for 0.5% sulfur fuel have created dedicated demand for low-BN cylinder oils and system oils compatible with exhaust gas cleaning systems. Fleet operators in Singapore and Rotterdam now specify these formulations as standard.
- Container Fleet Expansion:Megamax vessel deliveries with two-stroke dual-fuel engines require specialized lubricant protocols for gas-mode operation. This engine category now dominates newbuild contracts at Korean and Chinese shipyards.
- Scrubber Retrofit Cycles:Open-loop and hybrid exhaust gas cleaning installations concentrate in Chinese and Singaporean drydocks, sustaining aftermarket lubricant demand for high-sulfur fuel compatibility during transitional operations.
Market Restraints
- Group II/III Base Oil Concentration:Asian refiners in South Korea and Singapore control the majority of high-viscosity index feedstock supply, exposing blenders to input cost volatility when crude differentials widen.
- Additive Package Oligopoly:Four chemical specialists dominate marine-dispersant and detergent chemistry, limiting formulation flexibility and compressing blender margins on premium cylinder oil grades.
- Residual Fuel Quality Variability:Inconsistent cat-fine content and sulfur levels in bunkered fuels accelerate lubricant degradation, forcing shorter drain intervals and technical service costs that operators resist.
Strategic Opportunities
- Bio-Based Formulation Standards:EU Green Deal carbon intensity accounting and draft ISO/TC 28 bio-lubricant specifications create first-mover positioning for hydrotreated vegetable oil-derived marine products in European coastal traffic.
- Offshore Wind Service Vessels:Crew transfer and installation vessels operating in North Sea and Taiwan Strait zones require synthetic hydraulic fluids and biodegradable greases for subsea equipment access.
- Digital Bunkering Integration:Blockchain-verified lubricant delivery documentation and automated viscosity monitoring at Singapore and Antwerp terminals enable outcome-based service pricing tied to engine performance metrics.
Industry Challenges
- Lubricant Engineer Scarcity:Specialized tribology expertise for two-stroke crosshead engine analysis remains concentrated among retired marine superintendents, limiting technical service scaling for mid-size blender networks.
- Classification Society Certification Lag:DNV and Lloyd's Register testing protocols for new gas-engine lubricant grades extend approval timelines by 18-24 months, delaying product launches past vessel commissioning schedules.
- Legacy System Compatibility:Older auxiliary engines and stern tube seals in the existing fleet require mineral-oil formulations that conflict with shipowner sustainability reporting targets and insurer risk assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Lubricants Market |
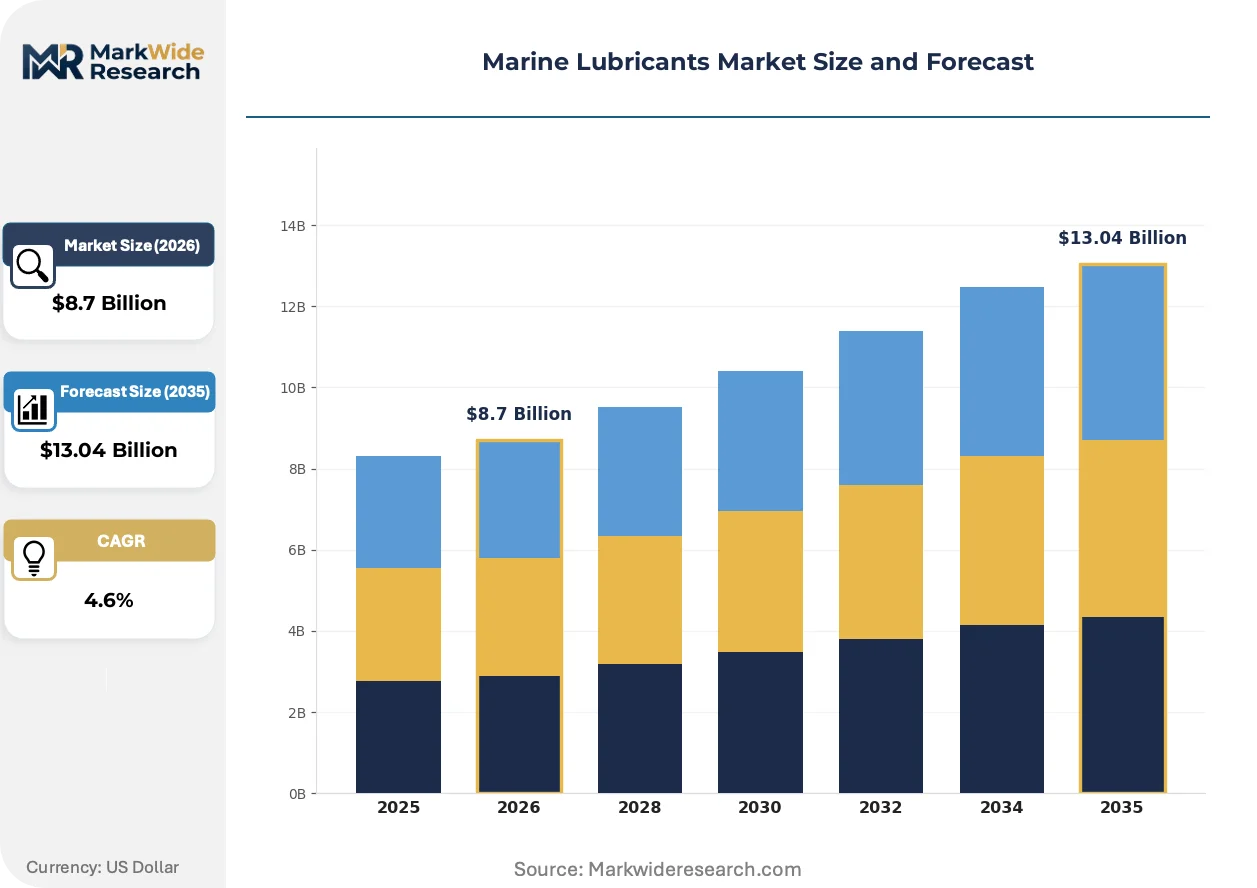
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Hydraulic Fluids, Greases, Gear Oils Application: Commercial Shipping, Fishing, Yachting, Offshore Operations Delivery Mode: Bulk Supply, Packaged, On-site Blending, Drum Supply End User: Shipowners, Operators, Shipbuilders, Maintenance Providers |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, BP p.l.c., TotalEnergies SE, LUKOIL, China Petroleum & Chemical Corporation, Petronas, ENEOS Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Lubricants Market Emerging Trajectories
Synthetic and bio-derived base stocks are displacing conventional mineral formulations as vessel operators face dual pressures from emission accounting rules and extended drain interval guarantees in service contracts.
Polyalphaolefin-based system oils with enhanced thermal stability are rendering obsolete traditional mineral formulations in high-load medium-speed engines. Cruise operators and offshore supply vessel fleets have adopted these synthetics for 12,000-hour drain intervals, compressing the addressable market for conventional products in premium segments.
EU Green Deal carbon border adjustment mechanisms and FuelEU Maritime regulations are forcing lubricant suppliers to document full lifecycle emissions. Blenders serving Rotterdam and Hamburg traffic now source hydrotreated base stocks with certified carbon intensity scores, while product lines without such documentation face exclusion from major charterer procurement lists.
Shipowner technical departments now unbundle lubricant supply from technical service contracts, issuing separate tenders for product volume and condition monitoring. Greek and Danish container operators pioneered this split-procurement model, which independent testing laboratories and sensor-technology providers are capturing in major bunkering hubs.
Marine Lubricants Market Segmentation
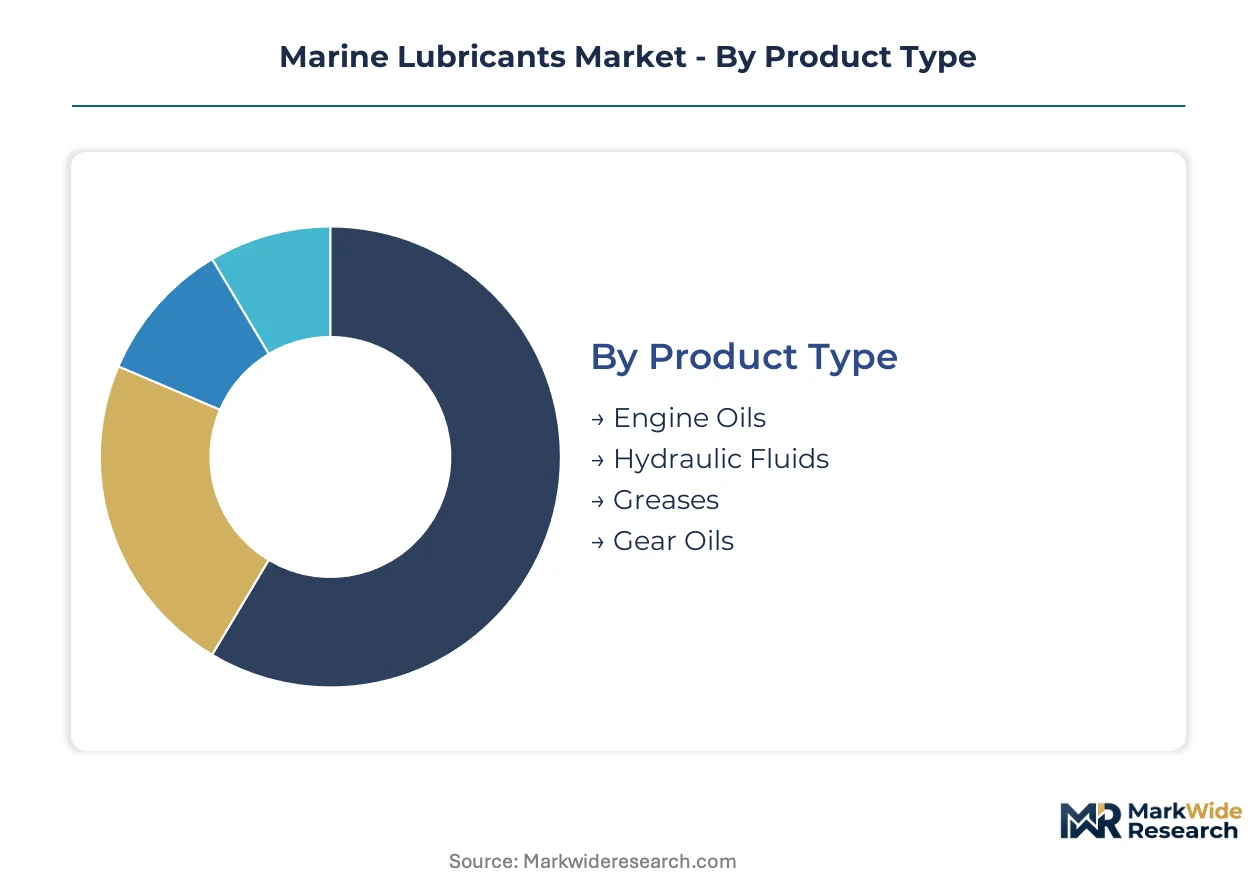
Segmentation in marine lubricants reveals how consumption cycles, procurement authority, and delivery logistics fragment what appears as a commodity market. Understanding these splits exposes where volume concentrates versus where margin accumulates.
Product Type:
Engine oils turn over fastest with every voyage cycle, while greases and gear oils stretch across years of service interval extension.
- Engine Oils:Cylinder and system oils formulated with detergent-dispersant packages manage combustion byproducts in two-stroke crosshead and four-stroke trunk engines. Demand clusters in Singapore and Rotterdam where container fleets bunker low-sulfur formulations for IMO 2020 compliance, with drain intervals now stretching to 1,000 hours for premium grades.
- Hydraulic Fluids:Synthetic and mineral-based fluids transmit power in steering gear, deck machinery, and subsea equipment with anti-wear and oxidation stability additives. Offshore operations in the North Sea and Gulf of Mexico specify fire-resistant synthetics, driven by insurer mandates for blowout preventer reliability.
- Greases:Lithium complex and calcium sulfonate thickeners with extreme pressure additives for stern tube seals and rudder bearings.
- Gear Oils:High-viscosity formulations for thruster and propulsion reduction gearboxes in cruise and offshore vessels.
Engine oils dominate installed base. Hydraulic fluids in offshore applications are where expansion concentrates.
Application:
Commercial shipping generates volume through scheduled bunkering, while offshore operations command premium pricing through unscheduled demand and technical service bundling.
- Commercial Shipping:Container, bulk, and tanker fleets consume 80% of marine lubricant volume through high-frequency cylinder oil replenishment and system oil top-offs. Greek and Danish operators now split procurement between product supply and condition monitoring services, compressing blender margins in major hubs.
- Offshore Operations:Drillships, production platforms, and support vessels require synthetic hydraulic fluids and biodegradable greases for subsea equipment access. Crew transfer vessels in Taiwan Strait and North Sea zones specify fire-resistant formulations under EU Green Deal carbon accounting rules.
- Fishing:Trawler and longline fleets in Peru and Norway using mineral-based engine oils with shorter drain intervals.
- Yachting:Recreational craft in Mediterranean and Caribbean ports demanding mid-tier formulations with brand recognition.
Commercial shipping anchors procurement volume. Offshore operations is climbing the fastest on synthetic fluid conversion.
Delivery Mode:
Bulk supply minimizes unit costs for fleet operators, while packaged and drum formats capture margin in remote ports and emergency replenishment.
- Bulk Supply:Direct barge-to-vessel transfer at Singapore, Rotterdam, and Fujairah terminals enables just-in-time cylinder oil delivery synchronized with bunkering operations. Blockchain documentation pilots at Antwerp terminals now verify viscosity and base stock certification automatically.
- Drum Supply:205-liter steel drums for auxiliary machinery top-offs and remote port calls where bulk infrastructure is absent.
- Packaged:Retail formats for yachting and fishing segments in Caribbean and Mediterranean marinas.
- On-site Blending:Port-based facilities in Houston and Singapore mixing base oils with additive packages for custom BN grades.
Bulk supply dominates fleet procurement. Drum supply captures margin in port infrastructure gaps.
End User:
Shipowners control specification authority, while operators manage consumption rates and maintenance providers influence switching decisions.
- Shipowners:Greek, Danish, and Singapore-based container and tanker owners set fleet-wide lubricant standards through technical management agreements, increasingly unbundling supply from service contracts. Procurement committees now require carbon intensity documentation for EU Green Deal compliance.
- Operators:Third-party technical managers in Hamburg and London optimizing drain intervals and consumption rates through sensor-based condition monitoring.
- Shipbuilders:Korean and Chinese yards specifying initial fill volumes for newbuild dual-fuel engines.
- Maintenance Providers:Drydock contractors in Singapore and Chinese facilities influencing reformulation during engine overhauls.
Shipowners dominate specification authority. Operators are gaining fastest on outcome-based service pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blending capacity clusters along major bunkering corridors where vessel traffic density justifies port-side infrastructure investment. Singapore, Rotterdam, and Houston anchor the three dominant supply nodes, each serving distinct trade lane configurations and regulatory environments.
Singapore
Container transshipment volumes and scrubber retrofit activity at Sembcorp Marine and Keppel yards sustain cylinder oil demand for dual-fuel engine protocols. The Maritime and Port Authority of Singapore enforces strict bunker quality standards that cascade into lubricant certification requirements. Jurong Island blending facilities supply low-BN formulations for megamax vessels bunkering at the world's largest refueling port.
China
Shipyard output at Dalian, Shanghai, and Guangzhou drives initial fill volumes for newbuild dual-fuel engines entering container and bulk carrier fleets. The Ministry of Ecology and Environment implements emission control area rules that align lubricant specifications with coastal sulfur restrictions. Yangtze River Delta ports concentrate demand for high-viscosity system oils serving inland waterway vessels.
United States
Gulf Coast offshore operations and Mississippi River barge traffic generate hydraulic fluid consumption for subsea equipment and steering systems. The EPA regulates vessel emissions under the Clean Air Act, creating segmented product registration for operators on trans-Pacific routes. Houston blending terminals serve both domestic inland fleets and international deep-sea vessels calling at the port.
Germany
Container feeder services and North Sea offshore wind support vessels require synthetic formulations under EU Green Deal carbon accounting rules. The Federal Maritime and Hydrographic Agency enforces MARPOL Annex VI compliance inspections at Hamburg and Bremerhaven. Port of Hamburg lubricant terminals now stock hydrotreated vegetable oil-derived products for coastal traffic.
South Korea
DSME and Hyundai Heavy Industries newbuild contracts for LNG-fueled vessels establish specification authority for gas-mode lubricant protocols. The Ministry of Trade, Industry and Energy supports domestic blending capacity expansion to reduce import dependence. Busan port infrastructure handles growing volumes of specialized cylinder oils for dual-fuel engine commissioning.
Marine Lubricants Market Vendor Landscape
Integrated energy majors and national oil companies split the market between global formulation expertise and captive feedstock access. The vendor base concentrates around five vertically integrated players controlling additive chemistry and high-viscosity base oil supply. Strategic archetypes include refinery-integrated blenders leveraging backward integration into Group II/III feedstocks, and technical service specialists embedding engineers directly with operator fleets. Competitive moves center on unbundling supply from condition monitoring contracts, and securing classification society pre-approvals for gas-engine lubricant grades.
Within the integrated-major tier, ExxonMobil Corporation and Shell plc occupy positions defined by refinery-to-port supply chain control and specialized cylinder oil formulation heritage. BP p.l.c. exemplifies the technical-service-density archetype through embedded engineering support. Among Asian national oil companies, China Petroleum & Chemical Corporation and Petronas represent state-backed blending capacity expansion aligned with domestic shipyard output.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP p.l.c. |
| TotalEnergies SE |
| LUKOIL |
| China Petroleum & Chemical Corporation |
| Petronas |
| ENEOS Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in South Korean Group II/III base oil refining tightens feedstock availability, forcing blenders to absorb cost volatility while passing selective increases to container fleet operators with locked annual contracts.
Pricing Analysis
MARPOL Annex VI dictates the pricing tier structure across marine lubricants, separating low-BN cylinder oils for IMO 2020 compliance from premium synthetic formulations for dual-fuel engines. Three-tier pricing structure across premium synthetics, standard mineral grades, and economy bulk supplies anchors the market, with certification by DNV and Lloyd's Register commanding material premiums. Cost compression in standard mineral grades is intensifying because Greek and Danish operators now unbundle supply from technical service contracts. Small fishing fleets and inland waterway vessels exhibit highest price sensitivity, while offshore drillship operators accept premiums for fire-resistant hydraulic fluids under insurer mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement between Singapore blenders and Greek shipowners, with supply-chain finance facilities from commodity traders bridging working capital gaps. Production gravity centers on Singapore, South Korea, and the United States Gulf Coast, where Jurong Island and Houston terminals control high-viscosity base oil blending. Formulation draws from Group II/III base stocks, detergent-dispersant additive packages, and corrosion inhibitor chemistries. Single-source vulnerability concentrates in the four chemical specialists controlling marine additive technology. Distribution runs through bulk barge-to-vessel transfer at major bunkering hubs, supplemented by drum supply for remote port calls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic and bio-derived base stocks threaten incumbent mineral-oil formulations as EU Green Deal carbon accounting forces lifecycle emissions documentation, compelling blenders to defend existing product lines against substitution.
For Market Incumbents: Pre-empt bio-lubricant standard adoption by securing hydrotreated vegetable oil feedstock contracts with certified carbon intensity scores before EU FuelEU Maritime enforcement tightens. Deepen backward integration into Group II/III base oil production in South Korea to offset additive package oligopoly pricing power. Anchor position through exclusive technical service contracts with Korean and Chinese shipyards specifying initial fill protocols for newbuild dual-fuel engines.
For New Entrants and Emerging Players: Build out biodegradable grease and synthetic hydraulic fluid capacity targeting North Sea and Taiwan Strait offshore wind service vessels, where EU Green Deal regulations create first-mover advantages. Crew transfer vessels represent the most penetrable segment given unscheduled demand patterns and limited incumbent technical service density. Pursue digital bunkering integration partnerships with Singapore and Antwerp terminal operators to automate viscosity verification and outcome-based pricing.
For Investors and Strategic Acquirers: Capital is best deployed toward technical-service-specialist blenders with embedded engineering teams and classification society pre-approvals for gas-engine lubricant grades. Long-term viability hinges on positioning ahead of bio-based formulation standard finalization and carbon border adjustment mechanism expansion. Watch for ISO/TC 28 bio-lubricant specification publication as the inflection signal triggering accelerated product line transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply of Group II/III feedstocks insulates blenders from Asian refinery margin volatility. |
| Classification Society Pre-Approval Investment | DNV and Lloyd's Register certification for gas-engine grades accelerates vessel commissioning timelines. |
| Bio-Based Formulation Development | Hydrotreated vegetable oil-derived products secure EU Green Deal compliance for Rotterdam and Hamburg traffic. |
| Digital Bunkering Platform Integration | Blockchain-verified delivery documentation enables outcome-based service pricing at Singapore terminals. |
| Technical Service Density Expansion | Embedded lubricant engineers with operator fleets lock in switching costs against unbundled procurement. |
Methodological Framework
A standing panel of marine superintendents, blending plant managers, shipowner procurement directors, and classification society technical reviewers provided ongoing calibration across primary fieldwork. Secondary validation drew from MARPOL Annex VI regulatory filings, Lloyd's Register and DNV certification databases, Singapore Maritime and Port Authority bunker quality statistics, and customs trade records for base oil and additive imports. Bottom-up volume modeling by vessel type and engine category triangulated against top-down lubricant consumption estimates from major bunkering hubs.
Scenario bracketing around sulfur regulation compliance pathways, dual-fuel engine adoption curves, and bio-lubricant standard timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, delivery mode, and end-user procurement authority, with vessel age distribution and scrubber retrofit status as marine-specific inputs. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory inflection points.
The forecast holds incumbent behavior within observed patterns; aggressive moves by national oil companies or independent bio-lubricant specialists would shift outcomes beyond projected ranges. Macroeconomic shipping demand collapse, accelerated IMO decarbonization targets, or breakthrough synthetic base stock cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
America Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Chile Lubricants Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Myanmar Lubricants Market
Lubricants
Norway Lubricants Market