
 Gun Lubricant Market | 2026-2036
Gun Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Gun Lubricant Market Insights
The gun lubricant market is consolidating around a sharp split between military-specification products and mass-market retail formulations. Lucas Oil Products leverages its motorsports-derived synthetic chemistry expertise to dominate premium firearm maintenance channels. WD-40 Company competes through mass retail distribution density and brand recognition among general consumers. Breakthrough Clean Technologies specializes in non-toxic, odorless formulations that anchor its position in indoor range and competitive shooting segments.
Gun lubricants are formulated substances—typically petroleum-based oils, synthetic esters, or PTFE-infused greases—engineered to reduce friction between moving metal parts in firearms while displacing moisture and preventing corrosion under extreme temperature ranges from -65°F to 500°F. Their primary commercial purpose centers on extending firearm service life, ensuring operational reliability, and meeting military maintenance protocols. Oil-based formulations lead the product type landscape due to their versatility across handguns, rifles, and shotguns, while aerosol delivery is growing fastest among casual owners seeking convenient application. Military end users command the deepest margin pools through multi-year supply contracts, though general consumers generate the highest unit volume.
EPA oversight of volatile organic compound emissions shapes aerosol formulation requirements, while REACH compliance in Europe restricts certain chlorinated solvent chemistries. The U.S. Department of Defense maintains MIL-PRF specifications that function as de facto market access barriers for non-certified suppliers. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as PTFE-containing greases face intensifying regulatory scrutiny across multiple jurisdictions.
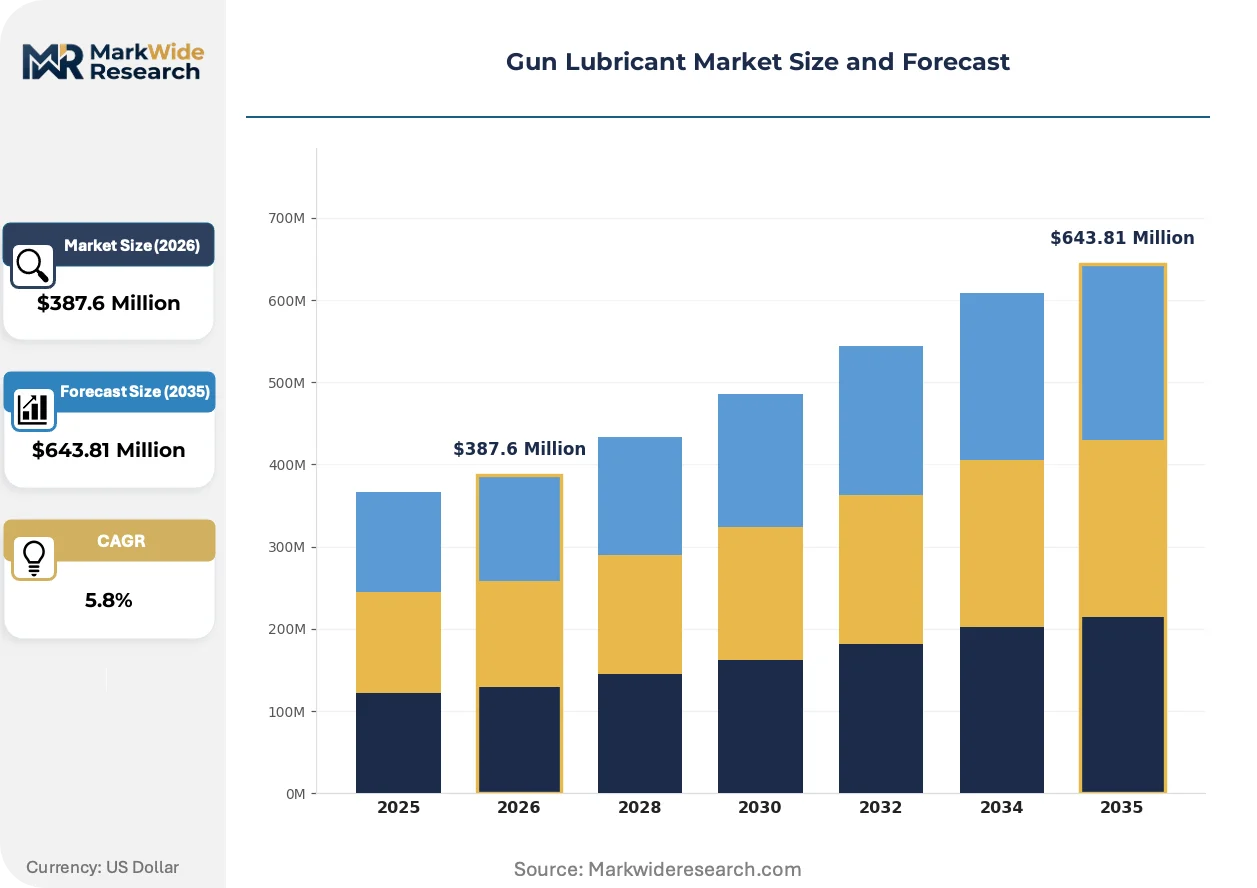
Market Dynamics
Biodegradable synthetic chemistry is compressing formulation cycles as military procurement specifications tighten under REACH and EPA volatile organic compound limits, forcing suppliers to recertify entire product lines.
Growth Catalysts
- MIL-PRF specification alignment:NATO member states are expanding multi-year small arms maintenance contracts that require certified lubricant compliance, locking in supplier relationships for the duration of fleet modernization programs.
- REACH chemical registration:European biodegradable lubricant mandates are accelerating synthetic ester adoption as chlorinated solvents face progressive phase-out across defense and civilian channels.
- Indoor range proliferation:Competitive shooting facilities in the United States are mandating low-odor, non-toxic formulations to comply with occupational exposure limits and improve shooter comfort during extended training sessions.
Market Restraints
- Base oil price volatility:Synthetic polyalphaolefin feedstock costs fluctuate with natural gas liquid markets, compressing margins for formulators lacking backward integration into petrochemical supply.
- PTFE regulatory scrutiny:Per- and polyfluoroalkyl substance restrictions across multiple U.S. state jurisdictions threaten greases containing polytetrafluoroethylene thickeners, forcing reformulation investments.
- Certification timeline friction:MIL-PRF qualification protocols require 18-24 month validation cycles that freeze product innovation and create barriers for new market entrants.
Strategic Opportunities
- Electroless nickel boron coatings:Convergence of dry-film lubricant technology with advanced firearm surface treatments is creating integrated maintenance solutions that reduce liquid lubricant dependency.
- Direct-to-consumer subscription:E-commerce replenishment models for high-volume recreational shooters bypass traditional retail markup structures and capture lifetime value through automated resupply.
- Canadian civilian market expansion:Relaxed transport regulations for non-restricted firearms are expanding the addressable base of precision rifle owners requiring premium maintenance products.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with expertise in extreme-temperature friction reduction are concentrated among legacy defense contractors, constraining R&D velocity at mid-tier suppliers.
- Cross-jurisdictional labeling complexity:Divergent state-level chemical disclosure requirements force SKU proliferation and inventory fragmentation for national distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gun Lubricant Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based, Grease, Aerosol, Liquid End User: Military, Law Enforcement, General Consumers, Armories Distribution Channel: Online Retail, Specialty Stores, Military Supply, Sporting Goods Application: Firearms Maintenance, Competitive Shooting, Hunting, Collecting |
| Companies Covered | Lucas Oil Products, ITW Rocol, Amsoil Inc, L&R Ultrasonics, G96 Products Inc., Ballistol, WD-40 Company, Mil-Comm Products, Breakthrough Clean Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gun Lubricant Market Trends and Innovations
Formulation science is pivoting toward environmental compliance as the primary innovation axis, with performance claims now requiring regulatory certification as a prerequisite for market access rather than a secondary selling point.
Ceramic-infused dry lubricants are rewriting application protocols for precision rifle bolts and AR-15 carrier groups. Competitive long-range shooters are adopting these formulations to eliminate carbon fouling adhesion and extend cleaning intervals. The technology is compressing the addressable market for traditional wet oils in high-performance segments.
EPA volatile organic compound emission limits are reshaping aerosol packaging requirements for gun lubricant sprays. Manufacturers are migrating to bag-on-valve systems and compressed air propellants to maintain retail shelf presence. The reformulation burden falls heaviest on mass-market brands dependent on convenience-oriented delivery formats.
Recreational shooters are consolidating purchases through specialty retailers that bundle lubricants with cleaning kits and diagnostic tools. This pattern is displacing standalone lubricant sales at big-box sporting goods channels. The United States exhibits the most pronounced shift, where online firearm community influence drives brand preference formation.
Gun Lubricant Market Segmentation
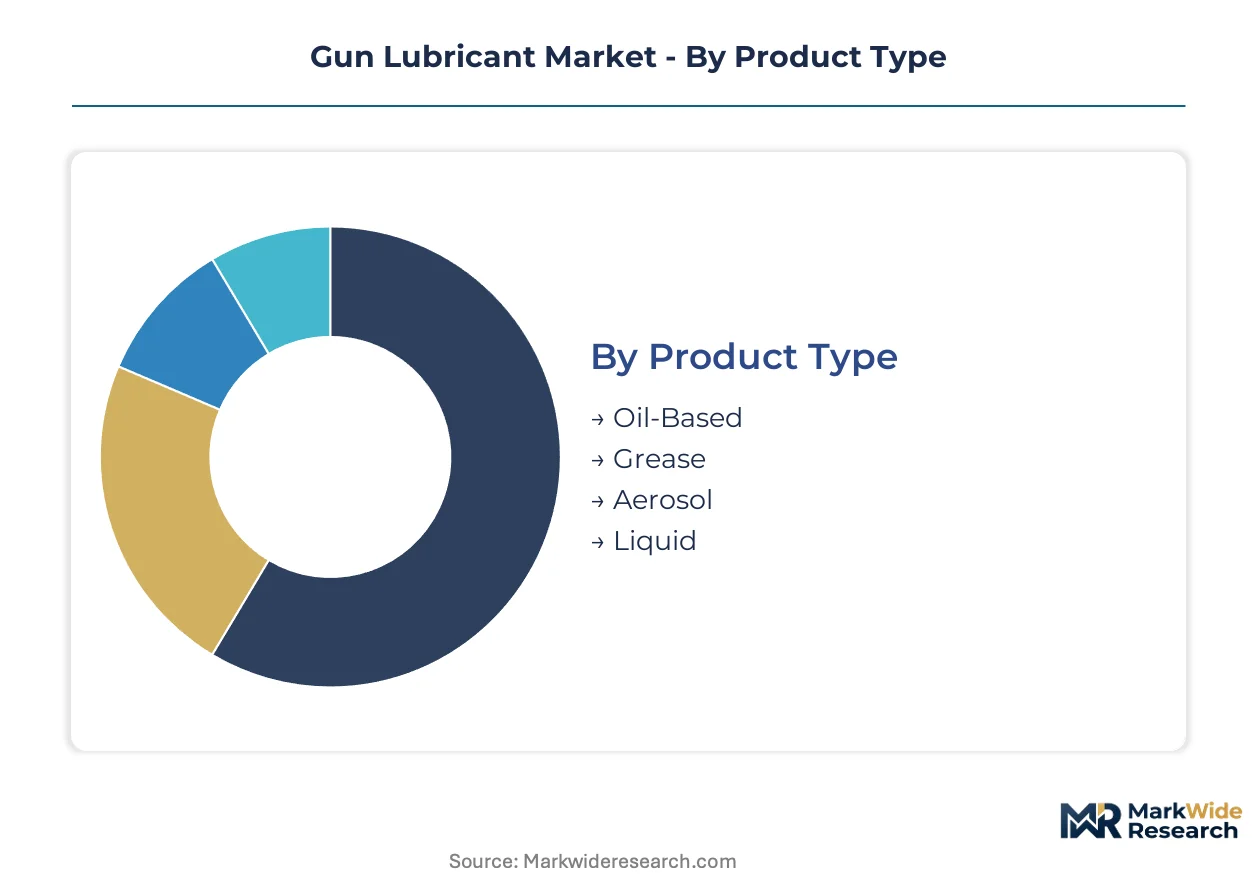
Gun lubricant segmentation reflects divergent performance requirements across defense procurement protocols and civilian usage patterns. Formulation chemistry, delivery mechanism, and certification tier determine supplier access to margin pools.
Product Type:
Oil-based formulations function as standalone maintenance solutions for field-deployed weapons, while greases embed within armorer bench protocols for long-term storage applications.
- Oil-Based:Petroleum and synthetic ester formulations dominate multi-weapon maintenance kits due to pour-point versatility spanning arctic to desert conditions. United States civilian owners and NATO armorer units concentrate demand here, driven by compatibility across handgun, rifle, and shotgun platforms without inventory multiplication.
- Grease:PTFE-thickened and ceramic-infused greases serve precision bolt assemblies and sear mechanisms where boundary lubrication prevents galling under high-load cycling. Military supply channels in Germany and the United States specify these for crew-served weapons and sniper systems, though REACH per- and polyfluoroalkyl substance scrutiny is forcing synthetic thickener substitutions.
- Aerosol:Compressed-gas delivery systems target casual owners seeking rapid application without disassembly depth. EPA volatile organic compound limits are compressing propellant options, accelerating bag-on-valve migration.
- Liquid:Bench-top dispensing formats concentrate in armorer workshops and competitive shooting facilities where precise volume control matters.
Oil-based leads volumes today; aerosol is gaining share fastest among first-time firearm owners.
End User:
Cost tier stratification separates specification-grade procurement from mass-market retail, with certification burden and volume scale defining supplier economics.
- Military:MIL-PRF qualification mandates function as de facto market access barriers, locking suppliers into multi-year NATO maintenance contracts with 18-24 month recertification cycles. Formulation stability under extreme temperature ranges and chemical weapons decontamination protocols drive specification tightness.
- Law Enforcement:Agency-level procurement concentrates in the United States, where municipal police departments and federal agencies balance duty-weapon reliability against budget constraints. Synthetic formulations with extended service intervals command premium positioning.
- General Consumers:Recreational shooters and hunters generate highest unit volume through retail and e-commerce channels, with brand preference shaped by online community endorsement and convenience-oriented packaging.
- Armories:Commercial maintenance facilities and gunsmith operations require bulk-format lubricants compatible with ultrasonic cleaning workflows and corrosion-inhibiting storage protocols.
Military commands deepest margins; general consumers drive absolute volume expansion.
Distribution Channel:
Customer type concentration determines channel economics, with specification buyers routing through dedicated supply chains while casual purchasers fragment across retail formats.
- Online Retail:E-commerce platforms capture subscription-based replenishment from high-volume recreational shooters, bypassing traditional retail markups through automated resupply algorithms.
- Specialty Stores:Firearm-focused retailers bundle lubricants with cleaning kits and diagnostic tools, displacing standalone sales at general sporting goods channels.
- Military Supply:Defense Logistics Agency and NATO equivalent procurement systems require certified supplier status, creating multi-year contract lock-in with limited vendor rotation.
- Sporting Goods:Big-box retailers serve entry-level firearm owners through convenience-oriented aerosol and wipe formats, though shelf space is compressing under specialty store competition.
Specialty stores lead value capture today; online retail is climbing the fastest.
Application:
Maturity gradients separate established maintenance routines from emerging usage contexts, with performance tier and frequency of use determining formulation selection.
- Firearms Maintenance:Routine cleaning and preservation protocols constitute the foundational use case, spanning military field stripping, law enforcement qualification cycles, and civilian storage preparation.
- Competitive Shooting:Precision rifle and action-pistol competitors demand low-odor, non-toxic formulations for extended indoor range sessions, with ceramic dry lubricants displacing wet oils in high-round-count segments.
- Hunting:Seasonal firearm preparation emphasizes corrosion resistance under variable field conditions, with all-weather synthetic oils commanding preference among backcountry hunters.
- Collecting:Curators and historical firearm enthusiasts prioritize non-reactive, museum-grade preservation chemistries with archival stability documentation.
Firearms maintenance anchors volume today; competitive shooting shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tribology chemists and firearms maintenance specialists concentrate in defense corridor clusters across NATO member states, with formulation expertise clustering near military research facilities and precision manufacturing zones.
United States
Civilian firearm ownership and Department of Defense maintenance contracts generate sustained lubricant volume across handgun, rifle, and shotgun platforms. EPA volatile organic compound limits reshape aerosol propellant formulations, forcing bag-on-valve system adoption. Texas and Arizona host precision rifle manufacturing clusters where ceramic dry lubricant adoption accelerates among competitive long-range shooters.
Germany
Bundeswehr small arms modernization programs and civilian precision shooting culture drive specification-grade demand. REACH chemical registration restricts chlorinated solvent chemistries, accelerating synthetic ester formulation transitions. Bavaria's firearms industry concentration around Oberndorf am Neckar anchors lubricant R&D partnerships between defense contractors and specialty chemical suppliers.
Canada
Relaxed transport regulations for non-restricted firearms expand the precision rifle owner base requiring premium maintenance products. Health Canada environmental assessment protocols influence biodegradable lubricant acceptance in hunting and competitive shooting segments. Alberta and British Columbia backcountry hunting communities prioritize all-weather synthetic oils for seasonal firearm preparation.
United Kingdom
Historic armory maintenance expertise and competitive target shooting traditions sustain specialized lubricant demand. ECHA REACH compliance mandates shape import specifications for European distribution networks. Birmingham's historic gun quarter retains concentration of museum-grade preservation chemistries serving historical firearm curators and collectors.
Australia
Strict firearm licensing frameworks concentrate ownership among dedicated sporting shooters and professional pest controllers with high maintenance discipline. TGA chemical oversight and state-level environmental regulations constrain formulation options for imported products. New South Wales and Victoria host the densest concentrations of competitive pistol and rifle facilities mandating low-odor indoor formulations.
Gun Lubricant Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and distribution architecture. The market structure concentrates around three tiers: military-certified suppliers locked into multi-year NATO contracts, specialty retailers bundling maintenance solutions, and mass-market brands dependent on retail shelf density. Strategic archetypes include synthetic chemistry specialists leveraging motorsport-derived expertise, non-toxic formulation pioneers targeting indoor range mandates, and diversified maintenance conglomerates exploiting brand recognition. Competitive moves center on MIL-PRF certification acquisition and direct-to-consumer subscription model deployment.
Within the synthetic chemistry tier, Lucas Oil Products exemplifies motorsport-derived formulation expertise applied to premium firearm maintenance channels. WD-40 Company occupies a position as the mass-market recognition anchor among general consumers seeking convenience-oriented aerosol delivery. Breakthrough Clean Technologies represents the non-toxic specialization vector, anchoring indoor range and competitive shooting segments with odorless formulation positioning.
| Leading Market Players |
|---|
| Lucas Oil Products |
| ITW Rocol |
| Amsoil Inc |
| L&R Ultrasonics |
| G96 Products Inc. |
| Ballistol |
| WD-40 Company |
| Mil-Comm Products |
| Breakthrough Clean Technologies |
| Others |
Pricing and Supply Chain Analysis
Military procurement officers at NATO defense ministries concentrate purchasing power through multi-year MIL-PRF specification contracts, anchoring pricing power with certified suppliers and compressing margin flexibility for non-compliant competitors.
Pricing Analysis
Bundled maintenance service contracts versus unbundled product-only transactions split pricing architectures across the gun lubricant market. Three-tier pricing structure across premium, standard, and economy levels separates military-specification synthetics from mass-market retail formulations and private-label alternatives. Price differentiation rests on MIL-PRF certification grade and volume procurement scale. Cost compression in economy-tier aerosol segments is intensifying because EPA volatile organic compound reformulation requirements force packaging investments. General consumers exhibit highest price sensitivity, while military end users prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with synthetic polyalphaolefin feedstock suppliers concentrated in the United States, Germany, and Japan. Formulation chemistry draws from petroleum distillates, synthetic esters, and ceramic nanoparticle inputs. Supply chain risk centers on regulatory restriction as REACH and EPA frameworks progressively ban chlorinated solvent and PTFE thickener chemistries. Distribution runs through defense logistics agencies for military tiers, specialty firearm retailers for premium civilian segments, and mass-market sporting goods channels for convenience-oriented purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable synthetic formulations where regulatory compliance premiums offset base oil cost volatility and certification investments.
For Market Incumbents: Lock in MIL-PRF specification renewals ahead of NATO fleet modernization waves to freeze out emerging competitors facing 18-24 month qualification barriers. Deepen backward integration into synthetic ester feedstock production to insulate margin structures from natural gas liquid price swings. Ceramic dry lubricant substitutes threaten traditional wet oil volumes in precision rifle segments. For New Entrants and Emerging Players: The price-point gap between premium military-certified synthetics and economy retail oils offers entry space for mid-tier biodegradable formulations targeting indoor range mandates. Canadian precision rifle owners and competitive shooting facilities present the most penetrable geography-application combination. Direct-to-consumer subscription models bypass entrenched retail markups and capture lifetime value through automated replenishment. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing defense sector relationships are the most active acquirer in this space. Long-term viability favors suppliers with integrated formulation-certification capabilities rather than pure-play distributors. Acquisition target archetypes include biodegradable lubricant specialists with REACH-compliant product lines and established e-commerce subscription infrastructure. Watch for state-level per- and polyfluoroalkyl substance bans as inflection indicators forcing accelerated PTFE grease reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Certification | REACH and EPA compliance opens NATO procurement channels previously closed to non-certified suppliers. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures lifetime value from high-volume recreational shooters bypassing retail markup. |
| Ceramic Dry Lubricant Product Line | Precision rifle competitors adopt carbon-fouling-resistant formulations extending cleaning intervals. |
| Bag-on-Valve Packaging Migration | EPA volatile organic compound limits force aerosol propellant reformulation for retail shelf retention. |
| Canadian Market Distribution Expansion | Relaxed transport regulations for non-restricted firearms expand addressable precision rifle owner base. |
Research Methodology
Direct dialogue with formulation chemists at defense contractors, procurement officers at NATO military supply agencies, specialty firearms retailers, and competitive shooting facility operators grounded qualitative assessment. Secondary validation drew from EPA regulatory filings, ECHA REACH registration databases, Department of Defense MIL-PRF specification documents, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Bottom-up demand aggregation across military, law enforcement, and civilian end-user segments converged with top-down macroeconomic drivers. Segmentation dimensions modeled include formulation chemistry, delivery mechanism, certification tier, and geographic procurement cluster. CAGRs were derived from trend extrapolation adjusted for regulatory phase-out timelines and fleet modernization cycles. Synthetic base oil feedstock cost trajectories and indoor range proliferation rates served as industry-specific forecast inputs across the analysis window.
Caveats apply where accelerated per- and polyfluoroalkyl substance regulatory bans or NATO procurement budget reallocations could materially shift the outlook. Forecasts reflect documented assumptions about specification stability and reformulation cost pass-through elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Polyurea Greases Market
Lubricants
Japan Lubricants Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Industrial Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Global Grease Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Myanmar Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Russia Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market