
 Emission Control Catalyst for Marine Market | 2026-2036
Emission Control Catalyst for Marine Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Control Catalyst for Marine Market Foresight
IMO 2020 is consolidating the competitive landscape around technical compliance capabilities. Johnson Matthey leverages its precious metals chemistry expertise to dominate high-performance SCR systems for large two-stroke engines. BASF SE anchors its position through backward integration into zeolite substrates, controlling critical raw material pathways. Haldor Topsoe A/S differentiates via proprietary titanium-vanadium catalyst formulations optimized for marine exhaust temperatures.
Emission control catalyst for marine denotes heterogeneous catalytic systems—typically comprising platinum-group metals on ceramic or metallic honeycomb substrates, with cell densities of 200-400 cpsi—that accelerate reduction or oxidation reactions in diesel engine exhaust streams. These systems convert nitrogen oxides to nitrogen and water, oxidize carbon monoxide and unburned hydrocarbons, and enable particulate matter capture when paired with filters. Selective catalytic reduction occupies the dominant value position due to its efficacy against IMO Tier III NOx limits, while diesel oxidation catalyst maintains volume leadership in retrofit applications where space constraints preclude full SCR installations. Fixed-bed reactor configurations retain manufacturing scale advantages, though hybrid systems integrating continuous flow elements are capturing interest for variable-load operations in fishing vessels and pleasure boats.
The European Maritime Safety Agency enforces MARPOL compliance through port state control inspections, directly shaping product certification requirements for catalyst suppliers seeking EU market access. The US Coast Guard implements EPA marine engine standards, creating a dual-certification burden for equipment sold into North American waters. China's Ministry of Ecology and Environment applies domestic emission standards for inland and coastal vessels, accelerating local production partnerships. Stakeholders must monitor regulatory divergence between flag-state requirements and port-state enforcement mechanisms when allocating R&D and manufacturing capacity.
Market Dynamics
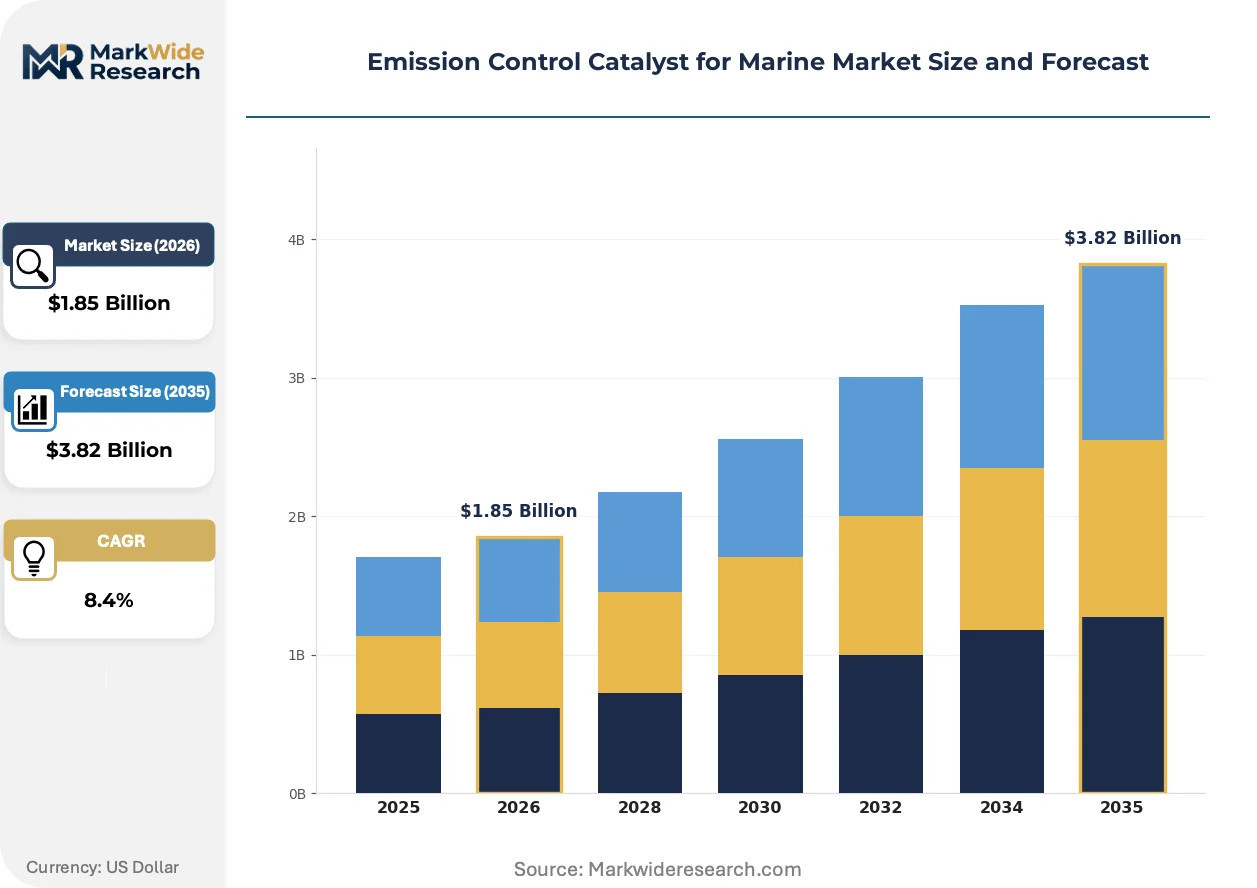
The marine emission control catalyst sector is restructuring around IMO Tier III compliance deadlines, with shipowners accelerating retrofit investments ahead of enforcement milestones in emission control areas.
Growth Catalysts
- MARPOL Annex VI amendments:The International Maritime Organization's nitrogen oxide limits for newbuild engines mandate selective catalytic reduction installations across oceangoing fleets.
- Cargo transport fleet renewal:Container shipping operators are retrofitting existing vessels with diesel oxidation catalysts to extend asset life under tightened port state control inspections.
- Zeolite substrate advances:Improved copper-zeolite formulations enable lower-temperature NOx conversion, expanding catalyst applicability to variable-load marine operations.
Market Restraints
- Platinum-group metal price volatility:Palladium and rhodium cost swings compress catalyst manufacturer margins and destabilize long-term shipowner procurement budgeting.
- Substrate supply concentration:Ceramic honeycomb production clusters in East Asian manufacturing hubs create single-source vulnerability for European and North American catalyst finishers.
- Space constraints in engine rooms:Retrofit SCR systems require volumetric footprints that conflict with existing auxiliary equipment layouts on vessels built before 2010.
Strategic Opportunities
- Inland waterway regulatory expansion:China's Ministry of Ecology and Environment is extending coastal emission standards to Yangtze River cargo fleets, creating retrofit demand beyond oceangoing vessels.
- Hybrid propulsion convergence:Battery-diesel hybrid systems require catalyst architectures optimized for intermittent combustion cycles and cold-start emissions profiles.
- Digital catalyst monitoring:IoT-enabled performance diagnostics allow suppliers to unbundle hardware sales from predictive maintenance subscriptions, capturing recurring revenue streams.
Industry Challenges
- Marine exhaust systems engineering talent:The intersection of naval architecture, catalytic chemistry, and control systems engineering generates acute hiring competition among suppliers.
- Type approval certification timelines:European Maritime Safety Agency and US Coast Guard parallel review processes extend product qualification cycles by twelve to eighteen months.
- Legacy engine integration complexity:Pre-Tier II engine control architectures lack sensor networks required for closed-loop SCR dosing, demanding costly auxiliary instrumentation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Control Catalyst for Marine Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Catalytic Reduction, Diesel Oxidation Catalyst, Three-Way Catalyst, Exhaust Gas Recirculation Catalyst Application: Commercial Shipping, Fishing Vessels, Pleasure Boats, Cargo Transport Technology: Continuous Flow, Fixed-Bed, Fluidized Bed, Hybrid Systems End User: Shipbuilders, Shipping Companies, Regulatory Bodies, Vessel Operators |
| Companies Covered | Johnson Matthey, BASF SE, Haldor Topsoe A/S, Clariant AG, Umicore N.V., Cormetech, Cataler Corporation, Tenneco, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Control Catalyst for Marine Market Shifts & Advancements
Marine catalyst technology is pivoting toward configurable architectures that accommodate fragmented regulatory timelines and vessel-specific operational profiles without complete system redesigns.
Compact SCR reactor designs are modularizing around standardized cartridge dimensions that permit field replacement of catalyst cores without dry-docking. Fishing vessel operators in Norway and Denmark are piloting these swappable units to minimize downtime during peak seasons. The approach is compressing total cost of ownership calculations for mid-size fleet owners previously priced out of full SCR installations.
EPA marine engine standards are tightening particulate matter limits for Category 3 engines, forcing catalyst suppliers to integrate diesel particulate filter elements with existing SCR substrates. Engine manufacturers in Germany and Japan are redesigning exhaust gas routing to accommodate the combined pressure drop. The regulatory sequence is accelerating R&D coordination between catalyst formulators and turbocharger specialists.
Ship charterers are embedding emission performance clauses in vessel lease agreements, redirecting owner procurement criteria from upfront capital cost to verified nitrogen oxide reduction rates. Greek and Singapore-based tanker operators now require third-party catalyst efficiency certification before fixture confirmation. The contractual shift is elevating supplier technical service capabilities alongside product specifications in competitive evaluations.
Emission Control Catalyst for Marine Market Segmentation
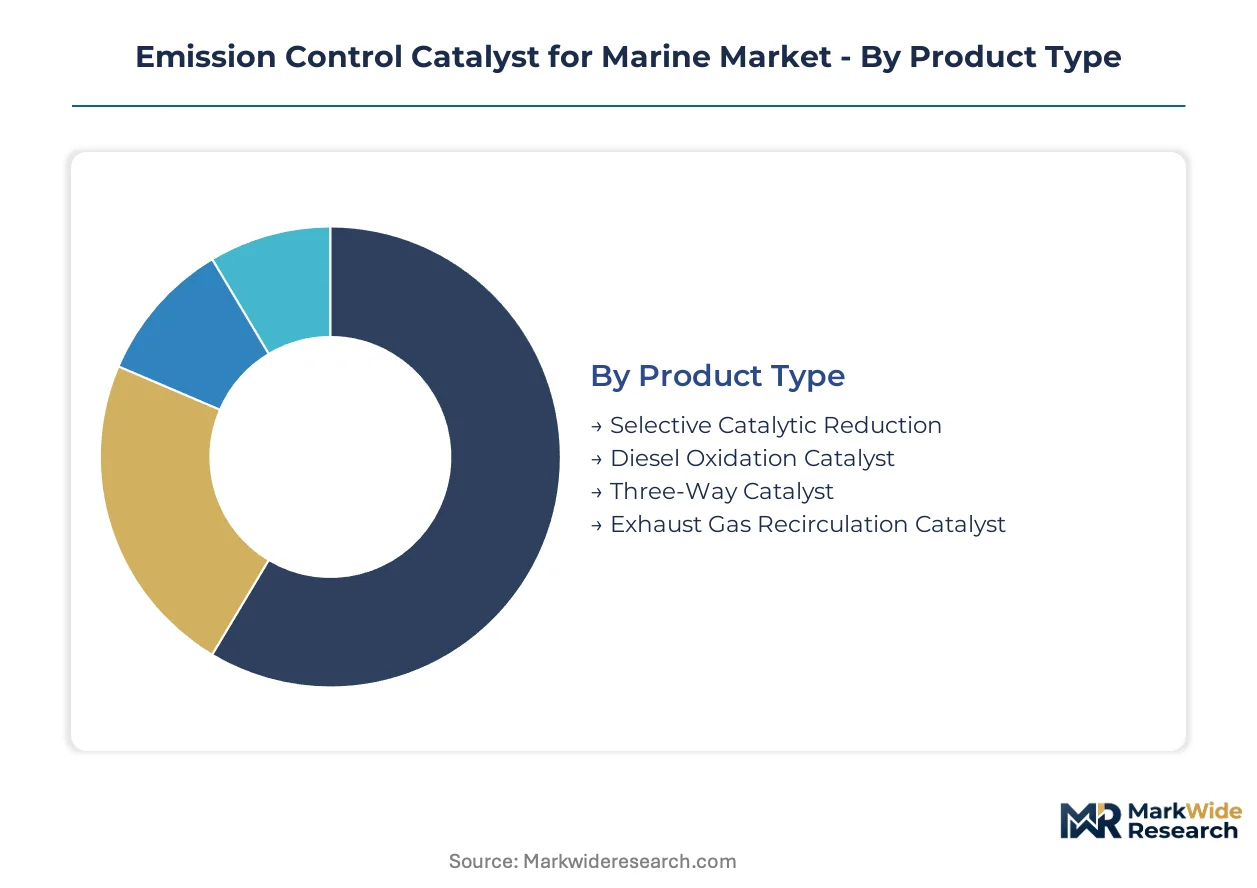
Marine emission control catalyst procurement splits sharply between compliance-driven retrofit decisions and newbuild system integration, with each segment category carrying distinct technical certification requirements and lifecycle cost profiles that reshape supplier engagement models.
Product Type:
Shipowners weigh capital outlay against NOx reduction efficacy when selecting catalytic systems for IMO Tier III compliance.
- Selective Catalytic Reduction:Platinum-group metals on ceramic honeycomb substrates enable 90%+ NOx conversion at exhaust temperatures above 280°C. Container shipping operators in Hamburg and Singapore mandate SCR installations for long-haul routes subject to emission control area enforcement.
- Diesel Oxidation Catalyst:Palladium-rhodium formulations oxidize carbon monoxide and unburned hydrocarbons without urea infrastructure. Greek tanker owners deploy these for retrofit programs where engine room volumetrics preclude full SCR reactor footprints.
- Three-Way Catalyst:Combined oxidation-reduction chemistry serves dual-fuel LNG-diesel engines with variable exhaust compositions.
- Exhaust Gas Recirculation Catalyst:Compact designs integrate with EGR cooler systems on medium-speed four-stroke engines.
Selective Catalytic Reduction leads on scale; Diesel Oxidation Catalyst leads on momentum.
Application:
Vessel operating patterns dictate catalyst durability specifications and regeneration frequency requirements.
- Cargo Transport:Container ships and bulk carriers run catalyst systems at continuous high-load conditions that accelerate thermal degradation. Chinese state-owned yards specify copper-zeolite formulations for 16,000+ hour service intervals on transpacific routes.
- Commercial Shipping:Cruise liners and ferries face stop-start port cycles demanding rapid catalyst light-off performance. Mediterranean operators prioritize low-temperature activity to meet port state control inspection protocols.
- Fishing Vessels:Intermittent engine loading and salt-laden exhaust challenge conventional substrate durability.
- Pleasure Boats:Space constraints and owner-operator maintenance limitations favor compact, cartridge-replaceable units.
Cargo Transport dominates procurement volumes; Commercial Shipping shows steepest expansion trajectory.
Technology:
Reactor configuration selection hinges on vessel stability requirements and available auxiliary power for system control.
- Fixed-Bed:Honeycomb monoliths in steel reactor housings deliver manufacturing scale economies and established type approval pathways. Japanese engine licensees specify these for two-stroke engine integrations with minimal control system complexity.
- Hybrid Systems:Combined fixed-bed and continuous flow elements adapt to variable-load fishing and offshore supply operations. Norwegian vessel owners pilot these architectures for battery-diesel hybrid propulsion cycles with frequent cold starts.
- Continuous Flow:Rotating or moving catalyst beds enable in-situ regeneration without dry-docking.
- Fluidized Bed:Powder catalyst suspensions suit high-sulfur residual fuel exhaust treatment with continuous ash removal.
Fixed-Bed retains volume leadership; Hybrid Systems are gaining share fastest.
End User:
Procurement authority fragmentation between asset owners and charterers reshapes supplier contract structures and technical service obligations.
- Shipping Companies:Fleet operators with in-house technical departments negotiate performance-based contracts linking catalyst replacement intervals to verified NOx reduction rates. Danish and German container lines bundle catalyst supply with remote monitoring subscriptions.
- Shipbuilders:Korean and Chinese newbuild yards source catalyst systems as engine package subcomponents, compressing supplier margins through volume aggregation but securing long-term aftermarket positions.
- Vessel Operators:Third-party technical managers oversee retrofit installations on behalf of dispersed ownership structures.
- Regulatory Bodies:Classification societies and flag state administrations define type approval testing protocols that gate market access.
Shipping Companies control specification authority; Shipbuilders concentrate manufacturing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine catalyst engineering talent clusters in port cities with dense shipyard ecosystems, concentrating procurement influence among technical managers in Hamburg, Singapore, and Shanghai who specify systems for fleet retrofits.
China
State-owned shipyards in Dalian and Shanghai are scaling domestic copper-zeolite catalyst production for Yangtze River retrofit programs. The Ministry of Ecology and Environment extends coastal emission standards to inland waterways, compelling fleet operators to install SCR systems. Jiangsu province hosts substrate manufacturing clusters supplying honeycomb ceramics to regional finishers.
Germany
Engine manufacturers in Augsburg and Hamburg integrate catalyst systems with two-stroke propulsion packages for container shipping operators. The KBA enforces MARPOL type approval timelines that compress supplier qualification cycles. North Rhine-Westphalia hosts precious metals trading desks hedging palladium exposure for catalyst formulators.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor catalyst procurement for newbuild LNG carriers at Ulsan and Geoje shipyards. The Korean Register of Shipping accelerates certification reviews for copper-zeolite formulations. Busan port state control inspections verify SCR urea dosing compliance for transpacific routes.
Singapore
Bunkering operators and technical managers at Tuas Marine Park specify catalyst performance clauses in vessel charter agreements. The Maritime and Port Authority enforces NOx monitoring protocols for ships calling at Southeast Asian emission control areas. Jurong ship repair clusters retrofit diesel oxidation catalysts for Greek and Danish tanker owners.
United States
EPA marine engine standards for Category 3 propulsion systems drive catalyst integration at Caterpillar and Wärtsilä engine packaging facilities in Illinois and Texas. The US Coast Guard implements parallel type approval reviews with EMSA, extending qualification timelines. Houston ship channel operators face port state control inspections verifying Tier III compliance for petrochemical tankers.
Emission Control Catalyst for Marine Market Competitive Landscape
The competitive structure tilts toward precious metals specialists with backward integration into substrate chemistry. Three tiers separate integrated chemical conglomerates with captive zeolite production, independent catalyst formulators sourcing honeycomb ceramics from East Asian suppliers, and marine exhaust system integrators bundling hardware with installation services. Consolidation pressure intensifies as shipowners demand performance guarantees spanning catalyst replacement intervals. Strategic moves concentrate on securing substrate supply agreements and acquiring IoT monitoring capabilities for predictive maintenance revenue streams.
Within the integrated chemical tier, Johnson Matthey and BASF SE occupy positions anchored by precious metals trading expertise and substrate manufacturing control. Haldor Topsoe A/S exemplifies the specialized formulator archetype, competing through proprietary titanium-vanadium formulations optimized for marine thermal profiles. These three companies represent distinct strategic postures: metals chemistry dominance, raw material pathway control, and application-specific formulation specialization.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Haldor Topsoe A/S |
| Clariant AG |
| Umicore N.V. |
| Cormetech |
| Cataler Corporation |
| Tenneco |
| Mitsubishi Heavy Industries |
| Others |
Supply & Pricing Matrix
Catalytic chemists and exhaust systems engineers cluster in Hamburg, Augsburg, and Shanghai, with labor-cost differentials between German and Chinese technical centers driving three-tier pricing spreads across IMO-certified, national-standard, and non-certified equipment tiers.
Pricing Analysis
The bundled hardware-plus-monitoring service split separates premium suppliers from commodity finishers. Three-tier pricing structure across premium, standard, and economy levels reflects precious metals loading, EMSA/USCG dual-certification status, and urea infrastructure inclusion. Cost compression in the economy tier is intensifying because Chinese state-owned yards are scaling domestic copper-zeolite production. Greek and Danish tanker operators show highest price sensitivity on retrofit programs, while Singapore-based container lines prioritize verified NOx reduction rates over capital outlay.
Supply Chain Analysis
Workforce availability for ceramic honeycomb manufacturing concentrates in Jiangsu province, South Korea's industrial corridors, and Japan's Nagoya region. Raw material pathways draw from South African platinum-group metal refiners, Chilean copper cathode producers, and synthetic zeolite synthesis operations in Germany and China. Single-source vulnerability pervades ceramic substrate supply, with East Asian manufacturing hubs feeding European and North American catalyst finishers. Distribution runs through engine manufacturer package suppliers and shipyard procurement offices, with aftermarket service contracts increasingly unbundled from initial hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European regulatory enforcement costs and Chinese manufacturing scale, with MARPOL Annex VI compliance timelines creating demand pull ahead of Tier III deadlines in North Sea and North American emission control areas.
For Market Incumbents: Acquire IoT-enabled performance monitoring platforms to capture recurring revenue streams and defend against emerging digital-native entrants. BASF SE and Johnson Matthey should deepen backward integration into synthetic zeolite production to secure substrate supply against East Asian concentration risk. Invest in copper-zeolite formulation R&D for low-temperature NOx conversion to extend service interval guarantees.
For New Entrants and Emerging Players: Proprietary titanium-vanadium catalyst formulations optimized for marine thermal profiles offer entry wedge against precious-metals-dependent incumbents. Target Yangtze River inland waterway retrofit programs where Chinese Ministry of Ecology and Environment standards are tightening ahead of full enforcement capacity. Partner with Norwegian fishing vessel operators piloting swappable cartridge SCR systems to establish reference installations without dry-docking infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent catalyst formulators lacking captive substrate production but holding EMSA type approval pathways. Five-to-ten year viability hinges on regulatory divergence between flag-state requirements and port-state enforcement mechanisms. Watch for European Maritime Safety Agency acceleration of certification reviews as signal of supply-demand imbalance favoring approved suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Substrates | BASF SE controls critical raw material pathways against East Asian supply concentration. |
| IoT-Enabled Predictive Maintenance Launch | Remote NOx monitoring subscriptions unbundle hardware sales from recurring revenue streams. |
| Copper-Zeolite Formulation Advancement | Lower-temperature activity expands applicability to variable-load fishing and offshore supply operations. |
| Modular Cartridge Reactor Design | Swappable units minimize downtime for Norwegian and Danish fishing vessel operators during peak seasons. |
| Dual-Certification Investment | Parallel EMSA and US Coast Guard approval extends addressable market to transpacific container routes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with marine exhaust systems engineers, catalyst procurement managers at German and Greek shipping companies, shipyard technical directors in Dalian and Ulsan, and classification society surveyors with secondary validation from IMO MARPOL amendment filings, European Maritime Safety Agency type approval registers, US Coast Guard marine engine standard documentation, and customs trade data on platinum-group metal flows. Bottom-up vessel fleet analysis and top-down chemical industry capacity estimates were triangulated against regional regulatory enforcement timelines.
Segment-weighting approaches distributed value across product type, application, technology, and end-user dimensions, with selective catalytic reduction, diesel oxidation catalyst, and three-way catalyst categories modeled separately for cargo transport, commercial shipping, fishing vessel, and pleasure boat applications. CAGRs were derived from regression analysis against fleet renewal schedules and retrofit investment cycles, incorporating platinum and palladium price volatility indices, shipyard orderbook pipelines, and port state control inspection frequency data as industry-specific forecast inputs across the projection horizon.
The model holds under stable MARPOL Annex VI enforcement intensity and continued precious metals market liquidity; deviation in IMO regulatory delay, East Asian substrate supply disruption, or platinum-group metal price spike would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Catalyst Handling Services Market
Catalysts
Catalase Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Global FCC Catalyst Market
Catalysts
Hydrogenation Catalyst Market