
 Polyurea-Based Greases Market | 2026-2036
Polyurea-Based Greases Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurea-Based Greases Market Analytics
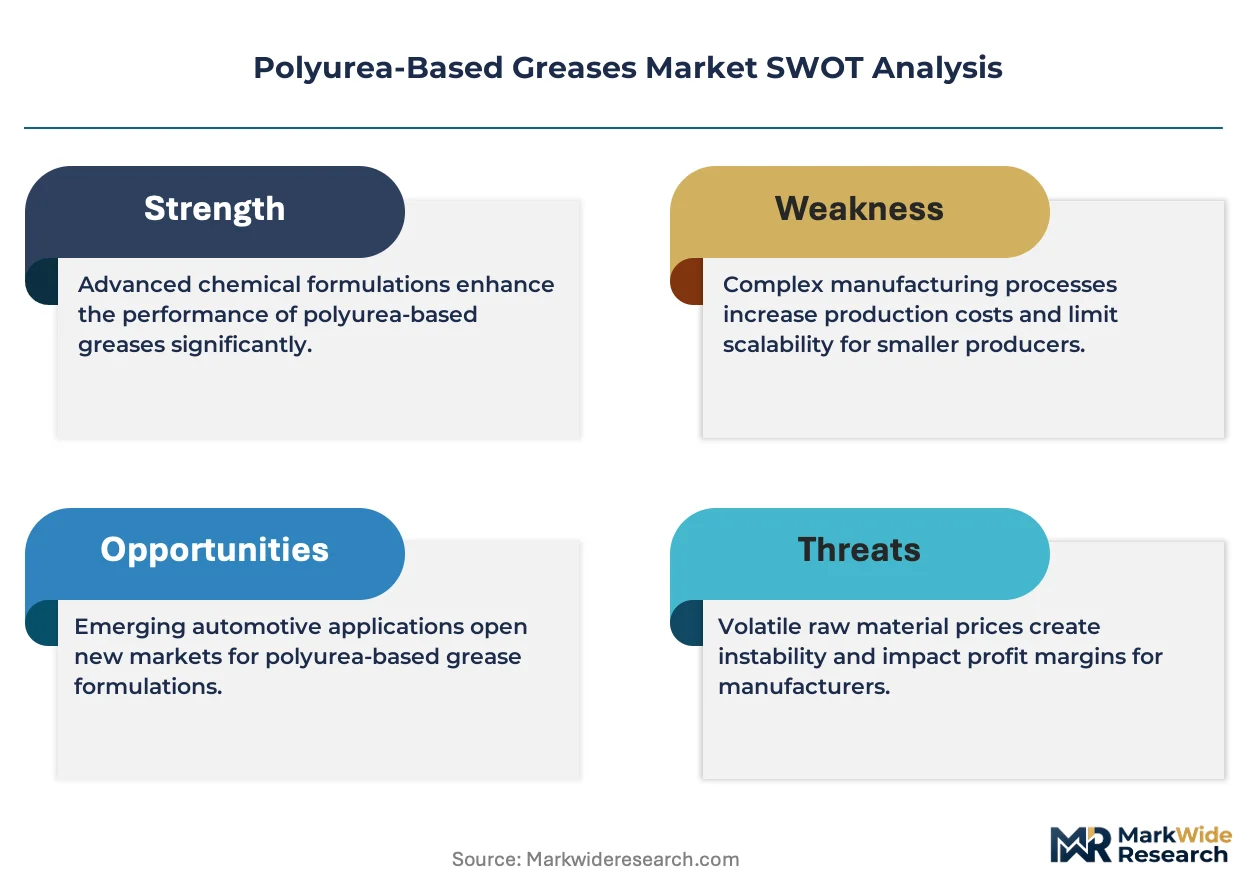
Aftermarket service revenue is fragmenting as equipment owners extend maintenance intervals and shift toward predictive lubrication programs. ExxonMobil Corporation leverages its integrated base-oil supply network to secure cost positions in high-volume industrial contracts. Shell PLC anchors its polyurea grease portfolio through direct OEM partnerships in aerospace and power generation. Fuchs Petrolub differentiates via application engineering labs that formulate custom polyurea thickeners for extreme-temperature mining equipment.
Polyurea-based greases combine a diisocyanate-reacted thickener system with mineral or synthetic base oils to yield drop points above 240°C and superior shear stability for high-speed bearing applications. Automotive greases lead volume consumption due to concentrated OEM specification power, while industrial greases capture expanding margin pools as maintenance providers shift from calendar-based to condition-based lubrication regimes. Marine greases represent a specialized growth pocket where salt-water corrosion resistance and biodegradability requirements drive formulation complexity.
The EPA governs lubricant environmental toxicity through Vessel General Permit discharge rules and used-oil management standards, while REACH in Europe mandates full substance registration for polyurea thickener intermediates. OEMs now demand grease formulations that satisfy both FDA incidental food-contact guidelines and NLGI GC-LB performance specifications. Stakeholders must monitor how tightening per- and polyfluoroalkyl substance restrictions in North America and Europe reshape thickener chemistry roadmaps and qualification timelines.
Market Dynamics
Electric vehicle powertrain redesigns are eliminating traditional bearing configurations, forcing polyurea grease formulators to engineer drop-point stability for ceramic hybrid bearings and integrated motor-generator units.
Growth Catalysts
- REACH Substance Registration:Full disclosure mandates for diisocyanate intermediates in Europe are accelerating qualification of cleaner thickener chemistries among compliant suppliers.
- EV Bearing Assemblies:Automotive OEM procurement teams in Germany and Japan are specifying polyurea greases for high-speed electric motor bearings above 15,000 RPM.
- Shanghai-Osaka Industrial Corridors:Concentrated demand from precision machinery and robotics manufacturing clusters is pulling specialized formulation capacity toward East Asian ports.
Market Restraints
- Diisocyanate Feedstock Volatility:TDI and MDI pricing swings tied to Asian petrochemical capacity constrain margin predictability for independent blenders.
- Thickener Supply Concentration:Four specialty chemical producers control over 80% of polyurea thickener precursor supply, creating single-source vulnerability for mid-tier grease manufacturers.
- PFAS Substitution Pressure:Pending restrictions on per- and polyfluoroalkyl substances in North America and Europe threaten existing PTFE-thickened grease formulations that polyurea alternatives cannot yet fully replace.
Strategic Opportunities
- India Industrial Corridor Expansion:BIS certification pathways for high-temperature greases remain underpenetrated, offering first-mover positioning in Ahmedabad and Pune manufacturing zones.
- Condition-Based Lubrication Convergence:Integration of IoT sensor networks with polyurea grease life prediction algorithms enables predictive maintenance contracts in wind turbine and steel mill applications.
- EU Green Deal Biodegradability Mandates:Marine and agriculture equipment OEMs must phase out mineral oil base stocks by 2030, creating formulation partnerships for ester-based polyurea systems.
Industry Challenges
- Tribology Talent Scarcity:Grease formulators with expertise in high-speed bearing rheology and thickener-synthetic base oil compatibility command premium compensation, constraining R&D team scaling.
- OEM Qualification Timelines:NLGI GC-LB and ASTM D4950 certification cycles for new polyurea formulations extend 18-24 months, delaying revenue recognition on development investments.
- Legacy Equipment Compatibility:Polyurea greases exhibit incompatibility with lithium-complex and calcium-sulfonate thickened residues, forcing costly flushing protocols during maintenance transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurea-Based Greases Market |
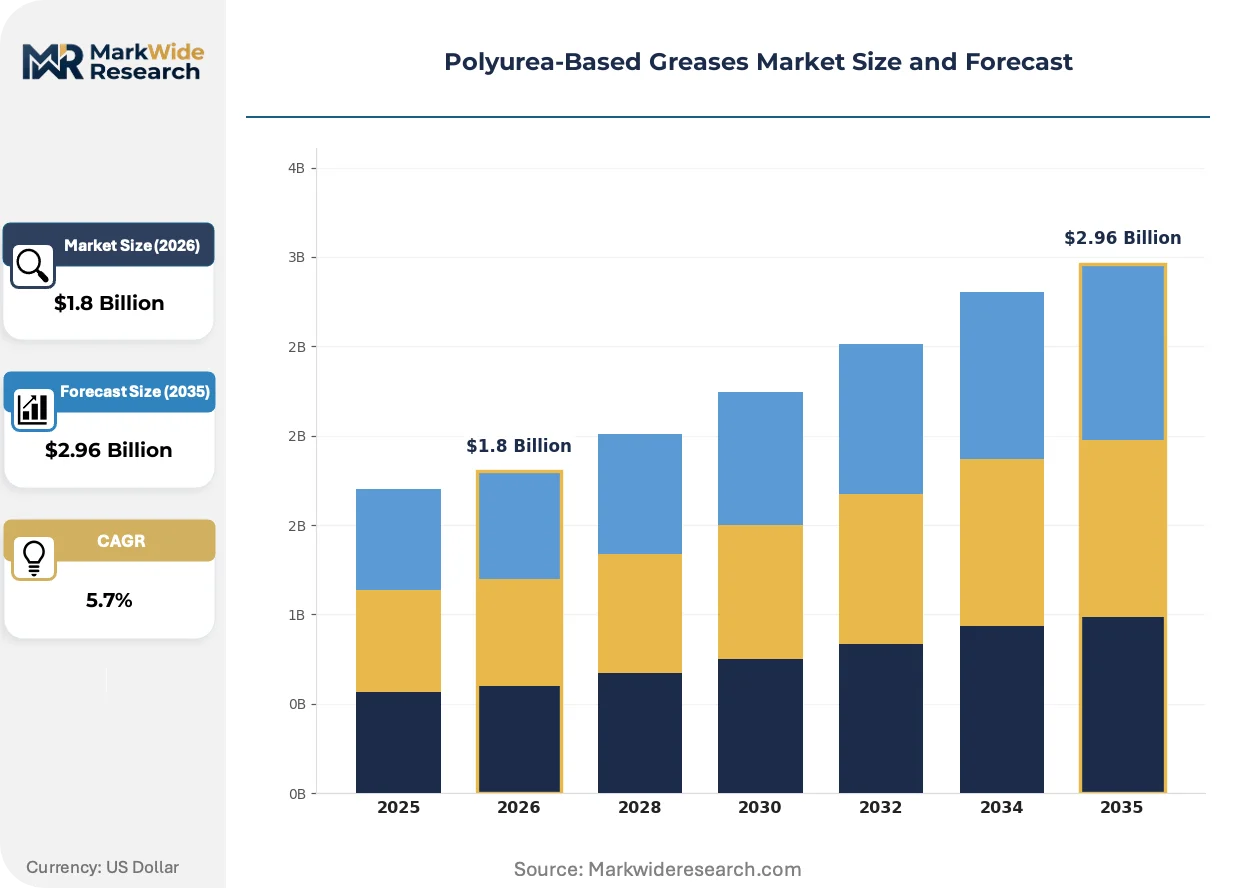
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Greases, Industrial Greases, Marine Greases, Electrical Greases Application: Aerospace, Construction, Manufacturing, Mining End User: OEMs, Maintenance Service Providers, Distributors, Retailers Packaging Type: Tubs, Cartridges, Drums, Sachets |
| Companies Covered | Chevron Corporation, ExxonMobil Corporation, Shell PLC, TotalEnergies, Castrol, Fuchs Petrolub, Klüber Lubrication, SKF, Martin Lubricants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurea-Based Greases Market Evolving Landscape
Formulation science is converging with digital monitoring systems, compressing the traditional boundaries between lubricant supply and equipment maintenance services.
Advanced polyurea thickener architectures incorporating hindered phenol antioxidants and boron nitride extreme-pressure additives are collapsing the performance gap between mineral-oil and PAO-based greases in automotive wheel bearing applications. Tier-1 suppliers in Stuttgart and Toyota City are qualifying these formulations for 150,000-kilometer fill-for-life specifications. The technology is collapsing aftermarket service revenue models that depended on 30,000-kilometer relubrication intervals.
EPA Vessel General Permit discharge rules now mandate aquatic toxicity testing for all lubricants used in commercial marine equipment operating in US waters. The regulation forces reformulation of legacy polyurea greases containing zinc dialkyldithiophosphate antiwear additives. Alaska and Gulf Coast fishing fleets are switching to EAL-labeled polyurea products ahead of 2026 enforcement deadlines.
Equipment owners in German automotive stamping plants and Japanese semiconductor fabrication facilities are unbundling lubricant procurement from maintenance service contracts. Buyers now source polyurea greases through industrial distributors while negotiating predictive analytics subscriptions separately. This pattern is most pronounced in Baden-Württemberg and Kyushu manufacturing clusters where maintenance departments operate as profit centers.
Polyurea-Based Greases Market Segmentation
Polyurea grease procurement patterns diverge sharply across end-use verticals, with formulation specifications, packaging formats, and channel economics varying by application intensity and regulatory exposure. Understanding these segment boundaries enables suppliers to align R&D investments with qualification timelines and margin structures.
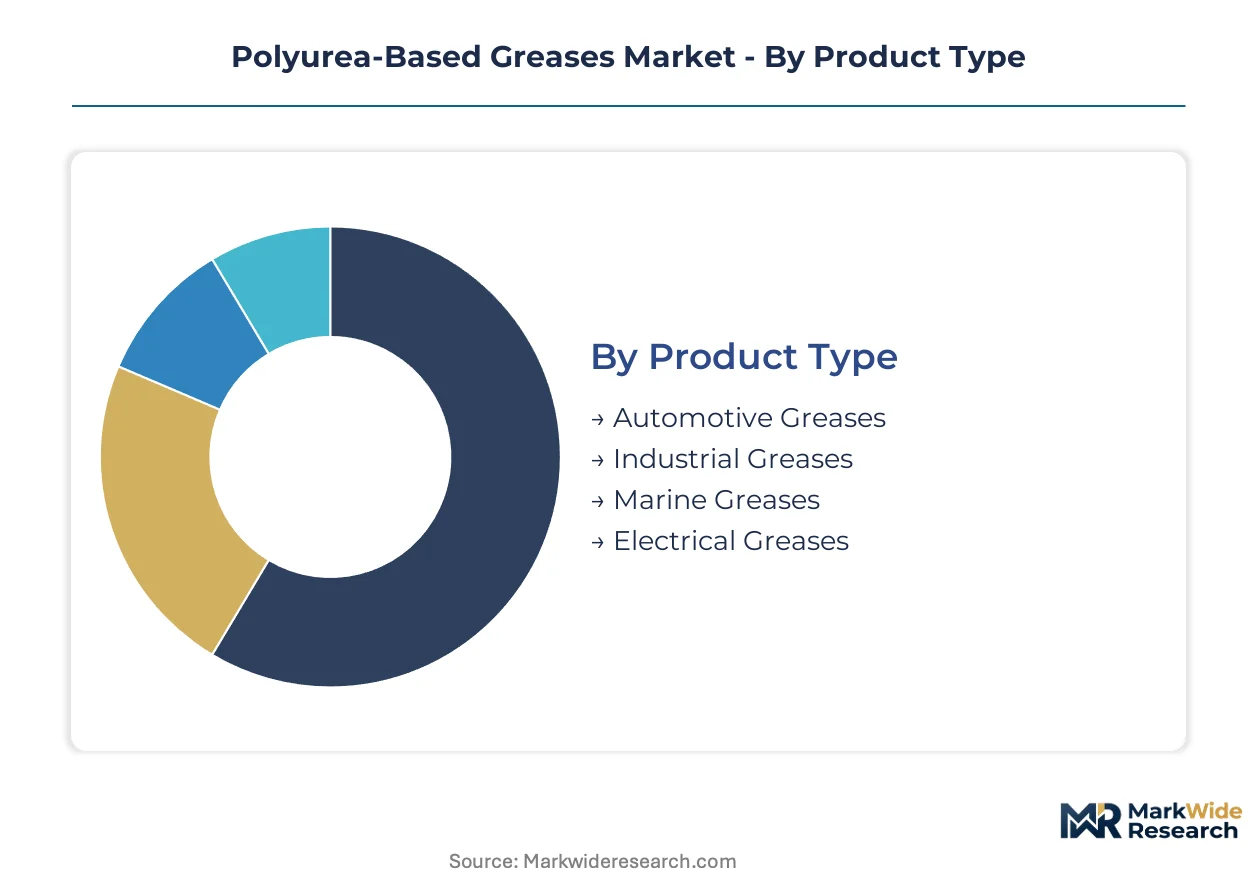
Product Type:
Mature automotive specifications dominate procurement volumes while emerging marine and electrical segments reshape formulation roadmaps.
- Automotive Greases:These formulations combine diisocyanate-thickened systems with PAO or Group III base oils to achieve NLGI GC-LB certification and 150,000-kilometer fill-for-life intervals. German and Japanese OEM procurement teams specify these grades for electric vehicle bearing assemblies above 15,000 RPM, driven by powertrain redesigns eliminating traditional lubrication access points.
- Industrial Greases:Mining equipment and steel mill applications demand extreme-pressure additives and drop-point stability above 240°C for continuous-duty bearings. Condition-based lubrication programs in German automotive stamping plants and Japanese semiconductor fabs are compressing relubrication intervals and shifting procurement toward predictive maintenance bundles.
- Marine Greases:EAL-labeled formulations with ester base stocks address EPA Vessel General Permit discharge rules for Alaska and Gulf Coast fishing fleets ahead of enforcement deadlines.
- Electrical Greases:Ceramic hybrid bearing compatibility and low-noise properties serve integrated motor-generator units in EV powertrains.
Automotive greases handle the majority of throughput; marine greases are climbing the fastest on share.
Application:
Cost tier differentiation separates specification-intensive aerospace grades from volume-driven construction and mining segments.
- Aerospace:AS9100-certified formulations with boron nitride extreme-pressure additives meet FAA airworthiness standards for turbine engine accessory bearings. Direct OEM partnerships anchor Shell PLC's positioning in this segment, where qualification cycles extend 24-36 months and pricing stratifies across military, commercial, and space-grade tiers.
- Manufacturing:Precision machinery and robotics clusters around Shanghai and Osaka pull specialized formulation capacity toward East Asian ports. REACH substance registration for diisocyanate intermediates is accelerating cleaner thickener chemistry qualification among compliant European suppliers serving this segment.
- Construction:High-volume concrete pump and crane applications favor mineral-oil-based polyurea greases in 180-kg drum packaging through industrial distributor networks.
- Mining:Fuchs Petrolub's application engineering labs formulate custom polyurea thickeners for extreme-temperature haul truck wheel bearings in Australian and Chilean open-pit operations.
Manufacturing captures the widest margin dispersion; aerospace shows the steepest expansion trajectory as commercial aviation recovery accelerates specification activity.
End User:
Customer type determines contract structure, with OEMs demanding multi-year qualification commitments and service providers seeking flexible distributor terms.
- OEMs:Automotive and aerospace original equipment manufacturers specify polyurea greases through approved vendor lists with 18-24 month NLGI GC-LB and ASTM D4950 certification requirements. Procurement teams in Stuttgart and Toyota City unbundle lubricant supply from maintenance contracts, sourcing through industrial distributors while negotiating predictive analytics separately.
- Maintenance Service Providers:German automotive stamping plants and Japanese semiconductor fabrication facilities operate maintenance departments as profit centers, driving demand for IoT-integrated condition monitoring systems.
- Distributors:Industrial supply houses in Baden-Württemberg and Kyushu manufacturing clusters intermediate between formulators and end-users, managing inventory for extended maintenance interval programs.
- Retailers:Automotive aftermarket channels serve DIY and small fleet segments with cartridge-packaged polyurea greases for wheel bearing and chassis applications.
OEMs anchor long-term formulation development; maintenance service providers are gaining share fastest as predictive lubrication programs displace calendar-based contracts.
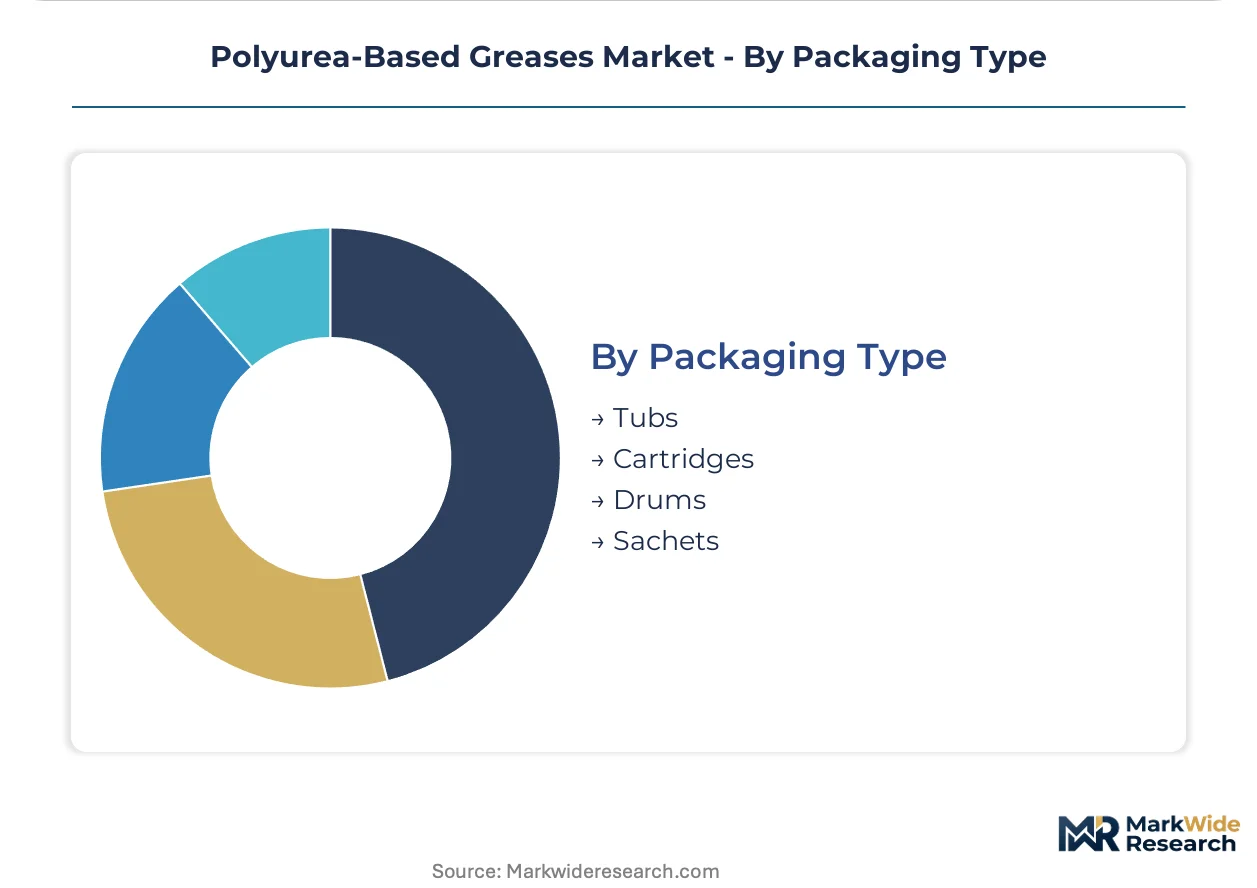
Packaging Type:
Volume scale and handling economics dictate format selection across application environments.
- Drums:180-kg steel drums dominate mining and steel mill procurement, with ExxonMobil Corporation leveraging integrated base-oil supply networks to secure cost positions in these high-volume industrial contracts.
- Cartridges:400-g grease gun cartridges serve automotive wheel bearing and chassis lubrication in aftermarket service bays, where compatibility flushing protocols complicate transitions from lithium-complex residues.
- Tubs:1-5 kg plastic tubs address maintenance shop and small fleet applications requiring manual application methods.
- Sachets:Single-use foil pouches serve aerospace line maintenance and marine equipment where contamination control and biodegradability certification outweigh unit cost premiums.
Drums handle the majority of throughput; sachets are expanding most quickly as contamination-sensitive applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German and Japanese buyers absorb premium formulations for EV bearing specifications, while Indian and Brazilian procurement teams prioritize cost positions in high-volume industrial contracts. This elasticity divide shapes where suppliers anchor formulation capacity versus where they push standardized grades.
Germany
Automotive OEM procurement teams in Stuttgart and Wolfsburg specify polyurea greases for 15,000 RPM electric motor bearings in integrated powertrain assemblies. REACH mandates full substance registration for diisocyanate intermediates, accelerating cleaner thickener qualification among compliant suppliers. The Baden-Württemberg manufacturing cluster hosts precision machinery and robotics operations that pull specialized formulation capacity toward southwestern industrial zones.
Japan
Toyota City and Nagoya-based OEMs unbundle lubricant procurement from maintenance contracts, sourcing through industrial distributors while negotiating predictive analytics separately. METI guidelines on high-performance industrial lubricants shape qualification timelines for domestic suppliers. The Osaka-Kyushu corridor concentrates demand from semiconductor fabrication facilities operating maintenance departments as profit centers.
United States
EPA Vessel General Permit discharge rules mandate aquatic toxicity testing for marine lubricants, forcing reformulation of legacy polyurea greases containing zinc dialkyldithiophosphate additives. Alaska and Gulf Coast fishing fleets switch to EAL-labeled products ahead of 2026 enforcement deadlines. Houston and Detroit industrial zones anchor high-volume drum procurement for mining and automotive applications.
China
Shanghai precision machinery and robotics manufacturing clusters pull specialized formulation capacity toward East Asian ports. GB standards on industrial lubricant performance create domestic qualification barriers that favor local blenders with captive thickener supply. The Yangtze River Delta hosts concentrated demand from wind turbine and steel mill operations adopting condition-based lubrication programs.
India
BIS certification pathways for high-temperature greases remain underpenetrated, offering first-mover positioning in Ahmedabad and Pune manufacturing zones. The country's national standards body is tightening disclosure requirements for base-oil and thickener compositions. Maharashtra and Gujarat industrial corridors concentrate construction equipment and textile machinery demand that favors mineral-oil-based polyurea grades in bulk packaging.
Polyurea-Based Greases Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Four specialty chemical producers control over 80% of polyurea thickener precursor supply, creating single-source vulnerability for mid-tier grease manufacturers. The market structures around three archetypes: integrated petrochemical majors with captive base-oil networks, independent lubricant specialists with application engineering depth, and regional blenders serving cost-sensitive industrial segments. Competitive moves center on backward integration into thickener chemistry and geographic expansion through distributor partnerships in underpenetrated manufacturing corridors.
Among integrated majors, ExxonMobil Corporation and Shell PLC exemplify contrasting scale strategies. ExxonMobil leverages its captive base-oil supply network to secure cost positions in high-volume industrial contracts, while Shell anchors its portfolio through direct OEM partnerships in specification-intensive segments. Fuchs Petrolub occupies a position among independent specialists, differentiating via application engineering capabilities that formulate custom thickeners for extreme-temperature equipment. These three represent how competitive positioning splits between upstream integration and downstream formulation expertise.
| Leading Market Players |
|---|
| Chevron Corporation |
| ExxonMobil Corporation |
| Shell PLC |
| TotalEnergies |
| Castrol |
| Fuchs Petrolub |
| Klüber Lubrication |
| SKF |
| Martin Lubricants |
| Others |
Value Network & Pricing Analysis
Diisocyanate feedstock volatility tied to Asian petrochemical capacity swings determines both pricing tier spreads and supply chain shape, compressing margins for independent blenders while concentrating thickener precursor procurement among integrated majors with captive supply networks.
Pricing Analysis
Aftermarket service revenue drives lifetime value, with three-tier pricing structure across premium, standard, and economy levels separating aerospace AS9100-certified formulations from mineral-oil automotive grades and bulk industrial drums. Price differentiation rests on NLGI certification tier and base-oil quality grade, with PAO-based EV bearing specifications commanding premiums over Group III mineral alternatives. Pricing pressure stems from extended maintenance intervals collapsing 30,000-kilometer relubrication schedules to fill-for-life contracts. Construction equipment buyers in India and Brazil exhibit highest price sensitivity, while German and Japanese automotive OEMs absorb premiums for REACH-compliant formulations.
Supply Chain Analysis
Supplier-financing facilities from specialty chemical producers extend 90-120 day payment terms to mid-tier blenders, easing working capital strain amid TDI and MDI price swings. Geographic supply concentration centers on Germany, Japan, and China, with thickener precursor production anchored in Ludwigshafen chemical corridors and Osaka Bay industrial zones. Raw material dependencies draw from aromatic diisocyanates, polyether polyols, and synthetic base oil feedstocks. Single-source vulnerability pervades the four-producer thickener precursor market. Distribution runs through industrial lubricant distributors in Baden-Württemberg and Kyushu manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as unbundling of lubricant procurement from maintenance contracts creates specialized formulation niches for application-engineering specialists.
For Market Incumbents: Harden thickener supply security through backward integration into diisocyanate precursor chemistry or long-term offtake agreements with the four dominant specialty chemical producers. Deepen application engineering capabilities in ceramic hybrid bearing compatibility to defend against emerging entrants targeting EV powertrain specifications. Prioritize REACH-compliant formulation pipelines ahead of tightening European disclosure mandates. For New Entrants and Emerging Players: India's BIS certification pathways for high-temperature greases offer first-mover positioning in Ahmedabad and Pune manufacturing corridors where mineral-oil-based polyurea grades remain underpenetrated. Target condition-based lubrication convergence in wind turbine and steel mill applications, bundling IoT sensor integration with predictive grease life algorithms. Pursue distributor partnerships with industrial supply houses serving profit-center maintenance departments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors independent specialists with captive formulation expertise over commodity blenders exposed to feedstock volatility. Acquisition targets should demonstrate application engineering depth in extreme-temperature or EAL-labeled marine segments. Watch for diisocyanate price inflection signals and REACH enforcement acceleration as revision triggers. Long-term viability hinges on synthetic base-oil compatibility capabilities across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thickener Chemistry | Captive diisocyanate supply secures margin predictability against TDI and MDI price swings. |
| EAL-Labeled Marine Formulation Partnerships | Ester-based polyurea systems address EPA Vessel General Permit discharge rules ahead of enforcement. |
| Condition-Based Lubrication Platform Integration | IoT sensor networks with grease life algorithms enable predictive maintenance contracts in steel mills. |
| REACH-Compliant Thickener Qualification | Full substance registration for diisocyanate intermediates accelerates cleaner chemistry adoption in Europe. |
| EV Bearing Assembly Specification Capture | Ceramic hybrid bearing compatibility opens 15,000 RPM electric motor procurement in Stuttgart and Toyota City. |
Research Methodology
The analysis maps automotive, industrial, marine, and electrical grease sub-sectors, each validated through grease formulators, OEM procurement teams, maintenance service directors, and industrial distributor channel managers. Primary interviews triangulate with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH substance registration databases. Bottom-up volume modeling across packaging formats and applications converges with top-down value triangulation.
Assumptions held fixed include regulatory enforcement timelines and base-oil technology roadmaps, while diisocyanate feedstock pricing and EV penetration rates varied across sensitivity scenarios. The analytical framework segments by product type, application intensity, end-user contract structure, and packaging format, with CAGRs derived from historical volume trajectories and qualification pipeline visibility. Forecast inputs incorporate NLGI GC-LB certification cycle durations and condition-based lubrication adoption curves.
Practitioners should monitor REACH substance registration acceleration and PFAS restriction finalization for early signals of thickener chemistry disruption. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Anti-Static Oil Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Lube Skid Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Lubrication Equipment Market