
 Solid/Dry Lubricants Market | 2026-2036
Solid/Dry Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Solid/Dry Lubricants Market Analytics
Fragmentation across maintenance providers and Tier-1 suppliers is repositioning procurement leverage toward smaller industrial buyers with specialized coating needs. DuPont leverages its fluoropolymer heritage to dominate PTFE-based solid lubricant supply for extreme-temperature applications. Henkel AG & Co. KGaA anchors European demand through industrial adhesives and coatings distribution networks that bundle dry lubricants with surface preparation systems. Klüber Lubrication specializes in application-engineered pastes and sticks for precision assembly lines where liquid lubricants risk contamination.
Solid and dry lubricants comprise bonded films, powder coatings, and composite materials—typically molybdenum disulfide, graphite, or PTFE particles suspended in resin matrices—that reduce friction between moving parts without liquid oil transfer, functioning across temperature ranges from cryogenic to above 300°C where conventional oils degrade. PTFE formulations lead product-type revenue due to chemical inertness and low coefficient of friction in food processing and pharmaceutical equipment. Powder and coating forms capture the fastest expansion as manufacturers retrofit existing components rather than redesigning assemblies, while paste formulations retain margin concentration in aerospace OEM specifications where manual application control remains mandatory.
EPA toxicity evaluations and REACH substance restrictions are reshaping permissible binder chemistries and accelerating substitution of legacy additives with boron nitride and certified food-grade graphite. FDA compliance for incidental food contact and EU MDR requirements for medical device lubrication create dual certification burdens that filter market access toward formulation houses with regulatory testing infrastructure. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that threaten PTFE availability while tracking boron nitride scale-up as the primary technical hedge.
Market Dynamics
REACH substance restrictions and EPA toxicity evaluations are compressing permissible binder chemistries while aerospace maintenance divisions accelerate procurement of solid lubricant coatings for turbine assemblies. This regulatory squeeze is electrifying substitution toward boron nitride and certified food-grade graphite across European and North American supply chains.
Growth Catalysts
- Aerospace turbine maintenance:Maintenance divisions are expanding bonded film procurement for high-temperature assemblies where liquid oils degrade. Manual application control remains mandatory in OEM specifications.
- REACH compliance deadlines:European substance restrictions are forcing legacy additive substitution. Formulation houses with regulatory testing infrastructure capture filtered market access.
- German precision manufacturing:Automotive OEM supply chains anchor consumption of molybdenum disulfide and PTFE-based formulations. Clusters concentrate demand in Baden-Württemberg and Bavaria.
Market Restraints
- PTFE supply vulnerability:Evolving per- and polyfluoroalkyl substance restrictions threaten fluoropolymer availability. ECHA evaluations are compressing feedstock security for extreme-temperature formulations.
- Boron nitride scale-up lag:Technical hedge materials face production bottlenecks. Primary suppliers concentrate in Japan and China, creating geographic concentration risk.
- Dual certification burden:FDA incidental food contact rules combined with EU MDR medical device requirements extend validation timelines. Smaller industrial buyers lack testing infrastructure.
Strategic Opportunities
- Retrofit coating services:Powder and coating forms capture expansion as manufacturers retrofit existing components. Application service providers bypass OEM redesign cycles.
- Medical device lubrication:EU MDR requirements create certified formulation demand. Lubrication for surgical instruments and implantable devices offers premium margin capture.
- Industrial adhesives bundling:Surface preparation systems combined with dry lubricants reduce procurement friction. Distribution networks that integrate both capture maintenance provider loyalty.
Industry Challenges
- Application engineering talent:Precision assembly lines require specialists who can specify paste versus powder forms. Klüber Lubrication and similar houses compete for limited formulation chemists.
- Legacy equipment compatibility:Bonded films on existing turbine components require surface preparation protocols. Maintenance providers face integration complexity with established overhaul procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid/Dry Lubricants Market |
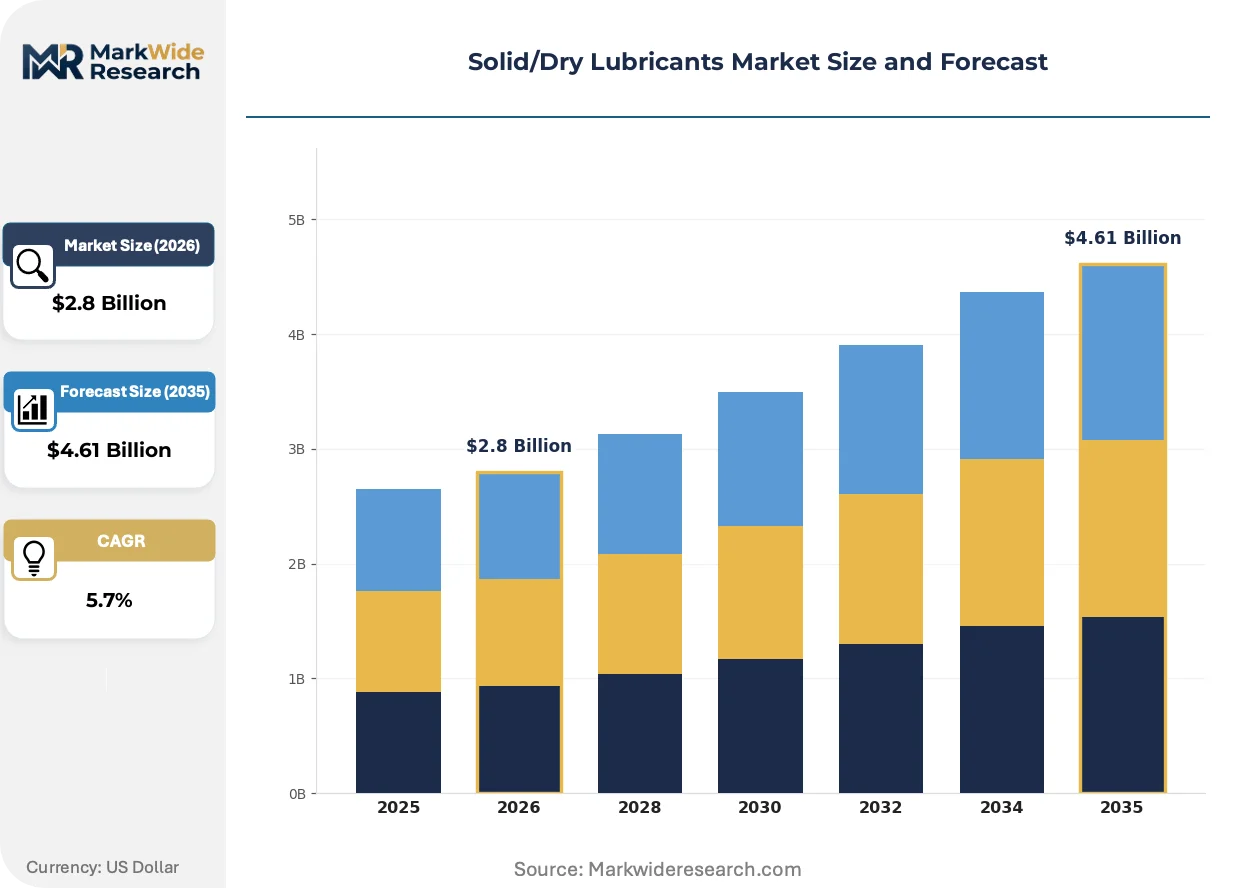
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite, Molybdenum Disulfide, PTFE, Boron Nitride Application: Automotive, Aerospace, Manufacturing, Food Processing End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Industrial Users Form: Powder, Stick, Paste, Coating |
| Companies Covered | DuPont, Henkel AG & Co. KGaA, Illinois Tool Works Inc., CASTROL LIMITED, Klüber Lubrication, Sun Coating Company, Slickote Coatings, Everlube, Lubrication Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid/Dry Lubricants Market Evolving Landscape
Boron nitride formulations are electrifying competitive positioning as the primary technical hedge against fluoropolymer restrictions. Three distinct movements are compressing traditional supply relationships while opening white space for certified specialists.
Laser-deposited solid lubricant coatings are electrifying retrofit economics for existing turbine blades and bearing races. MRO providers at Lufthansa Technik and Delta TechOps are adopting these processes to extend component life without OEM redesign. The technology is electrifying margin capture in aftermarket services while compressing demand for original equipment specification changes.
EPA toxicity evaluations under the Toxic Substances Control Act are narrowing permissible resin matrices for bonded films. Industrial consequence includes accelerated validation of ceramic-based alternatives and compressed timelines for legacy formulation phase-outs. Aerospace OEM specifications in the United States are most affected, with Pratt & Whitney and GE Aviation pressing suppliers for pre-certified alternative binders.
Maintenance procurement teams are consolidating vendor relationships around bundled surface preparation and lubrication systems. Industrial buyers with specialized coating needs are gaining leverage through multi-year service contracts that unbundle material supply from application labor. This pattern concentrates in Germany and the United States where precision manufacturing clusters maintain captive maintenance divisions.
Solid/Dry Lubricants Market Segmentation
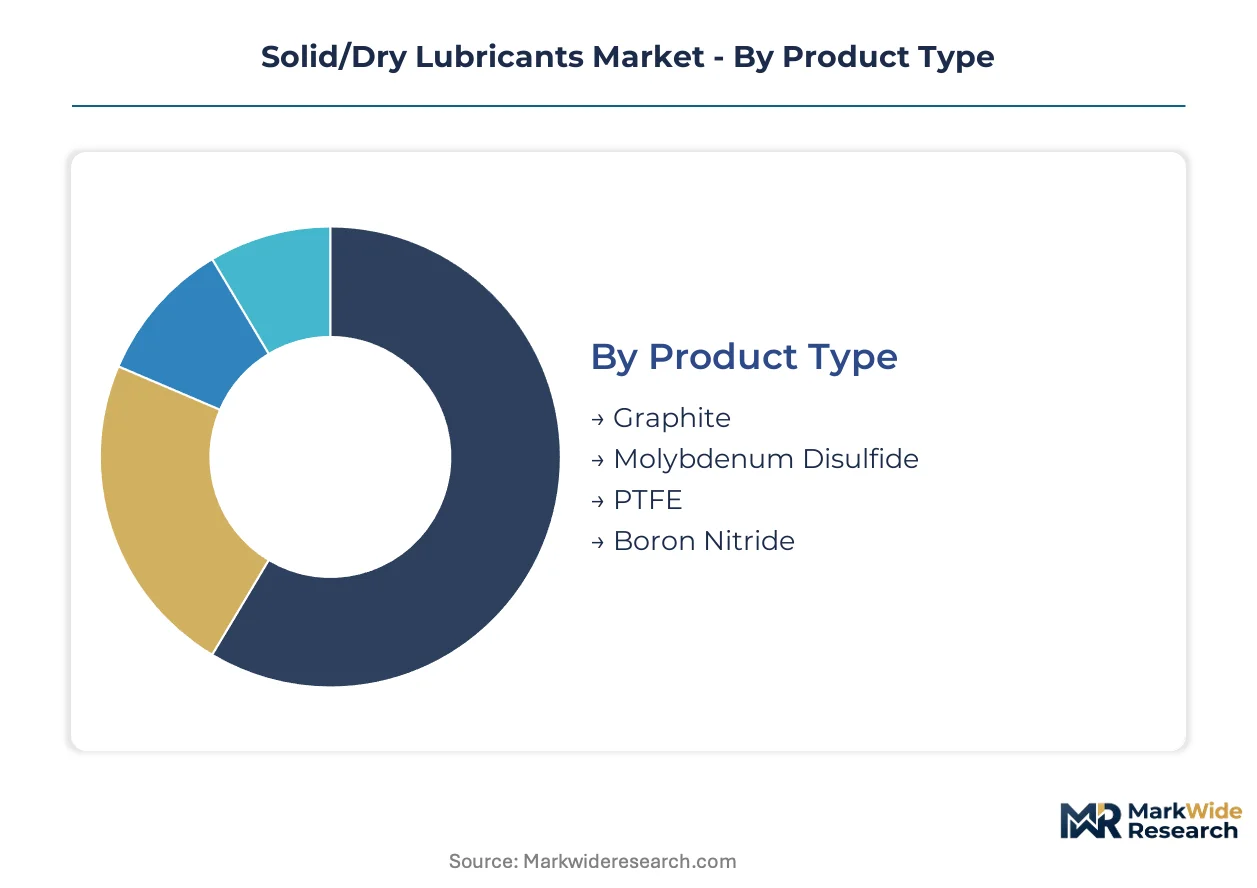
Solid and dry lubricants fragment across material chemistry, physical form, and procurement channel. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Integration depth varies sharply—PTFE and molybdenum disulfide dominate bonded film applications for extreme-temperature assemblies, while graphite and boron nitride serve more commoditized, standalone powder uses.
- Graphite:Lamellar carbon structure provides electrical conductivity alongside friction reduction. Foundry operations in Germany's precision manufacturing clusters anchor procurement volumes for die-casting release agents.
- Molybdenum Disulfide:Hexagonal crystal lattice shears under load to form protective tribofilms. Aerospace turbine maintenance divisions in the United States specify MoS2-bonded coatings for bearing races above 300°C where petroleum oils thermally degrade.
- PTFE:Fluoropolymer backbone delivers the lowest coefficient of friction among commercial solid lubricants. FDA incidental food contact certification and EU MDR medical device compliance create dual regulatory burdens that filter formulation access.
- Boron Nitride:Ceramic hexagonal structure mimics graphite's lubricity while resisting oxidation to 900°C. Japanese and Chinese suppliers concentrate primary production, creating geographic feedstock vulnerability as REACH and EPA restrictions accelerate substitution from PTFE.
PTFE leads volumes today; boron nitride is gaining share fastest.
Application:
Cost tier stratification separates specification-driven aerospace and medical segments from price-sensitive automotive and general manufacturing.
- Automotive:OEM supply chains in Baden-Württemberg and Bavaria specify MoS2 and PTFE formulations for transmission synchronizers and seat track mechanisms. Tier-1 suppliers bundle dry lubricants with surface preparation systems to reduce procurement friction.
- Aerospace:Maintenance divisions at Lufthansa Technik and Delta TechOps drive bonded film demand for turbine blade overhaul. Manual application control remains mandatory in Pratt & Whitney and GE Aviation specifications, preserving paste formulation margins.
- Manufacturing:General industrial users retrofit existing components with powder coatings rather than redesigning assemblies. Application service providers bypass OEM specification cycles to capture aftermarket revenue.
- Food Processing:FDA-compliant PTFE and certified food-grade graphite serve conveyor bearings and packaging machinery. EU EFSA evaluations and US FDA toxicity assessments compress permissible binder chemistries, extending validation timelines.
Aerospace commands premium pricing; food processing shows steepest expansion trajectory.
End User:
Customer type determines specification authority and contract structure—OEMs and Tier-1 suppliers control design-phase decisions while maintenance providers and industrial users dominate retrofit economics.
- OEMs:Original equipment manufacturers embed solid lubricants into component designs during development. Pratt & Whitney and GE Aviation press suppliers for pre-certified alternative binders as EPA TSCA evaluations narrow permissible resin matrices.
- Tier-1 Suppliers:Intermediate manufacturers bundle dry lubricants with adhesives and coatings distribution. Henkel AG's European network exemplifies integrated surface preparation and lubrication procurement.
- Maintenance Providers:MRO operations adopt laser-deposited coating processes to extend component life without OEM redesign. Lufthansa Technik and Delta TechOps consolidate vendor relationships around multi-year service contracts.
- Industrial Users:Smaller manufacturers with specialized coating needs gain procurement leverage through retrofit services. Fragmentation across maintenance providers concentrates demand in German and US precision manufacturing clusters.
Maintenance providers represent the fastest-climbing customer category; OEMs retain specification control.
Form:
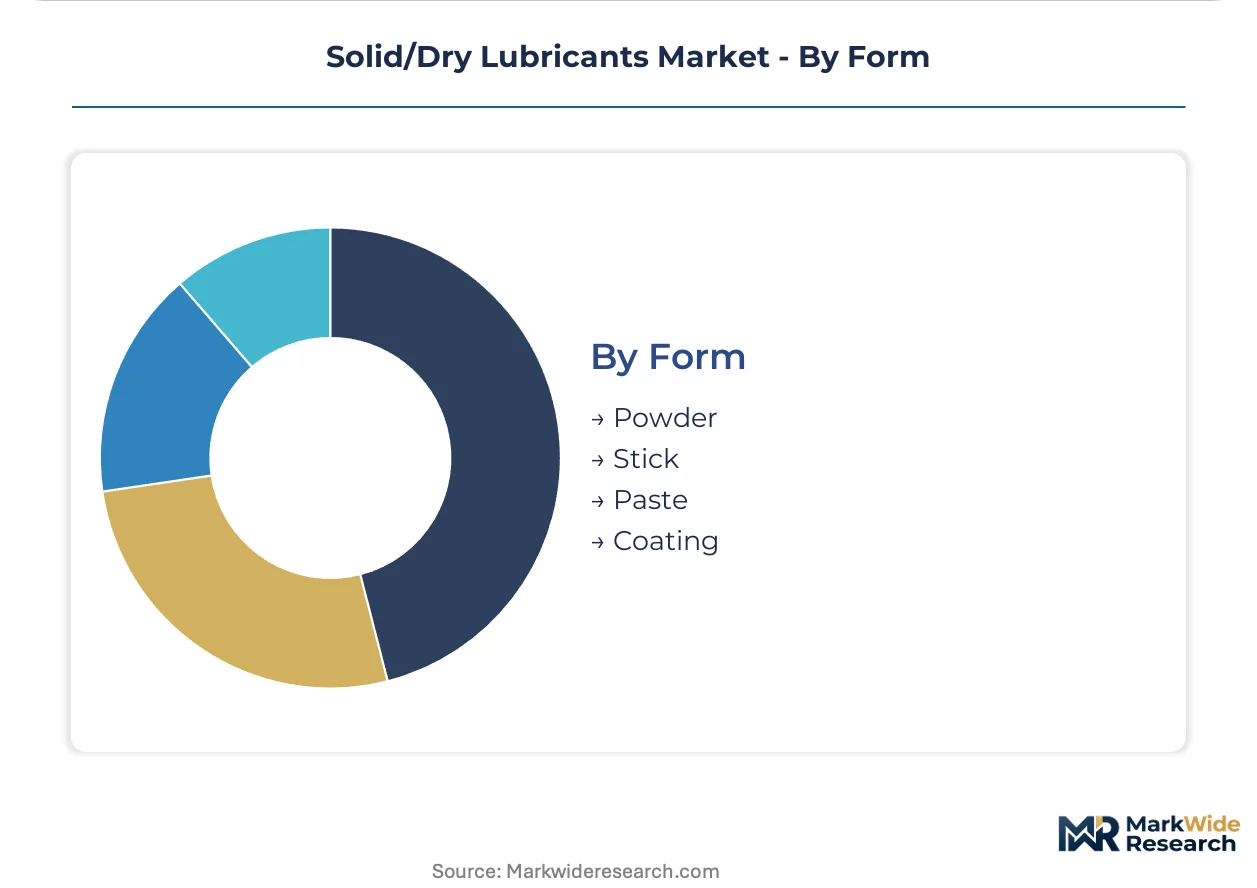
Physical format dictates application method and margin capture—powders and coatings scale through retrofit services while pastes and sticks preserve manual-application premiums.
- Powder:Dry particulate for bulk application or resin matrix suspension. Manufacturers retrofit existing turbine components and bearing races without redesign cycles, compressing demand for original equipment specification changes.
- Stick:Compressed solid for direct rubbing application. Maintenance technicians apply to inaccessible assemblies where spray or dip methods fail.
- Paste:Thixotropic dispersion of lubricant particles in carrier fluid. Aerospace OEM specifications mandate manual application control for precision assembly lines where liquid lubricants risk contamination.
- Coating:Bonded films and laser-deposited layers for component surface modification. EPA toxicity evaluations and REACH substance restrictions reshape permissible binder chemistries, accelerating ceramic-based alternative validation.
Coating forms expand most quickly; paste formulations retain margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and application engineers concentrate in German precision manufacturing clusters, United States aerospace hubs, and Japanese materials science centers. These talent pools anchor regional competitive positioning and determine regulatory response speed. Geographic distribution of solid lubricant demand tracks automotive OEM supply chains, MRO infrastructure density, and chemical processing capabilities.
United States
Aerospace turbine maintenance divisions at Delta TechOps and Pratt & Whitney specifications drive bonded film procurement. EPA toxicity evaluations under the Toxic Substances Control Act compress permissible resin matrices for extreme-temperature formulations. Connecticut and Ohio manufacturing corridors concentrate application service providers serving commercial aviation MRO networks.
Germany
Automotive OEM supply chains in Baden-Württemberg and Bavaria anchor molybdenum disulfide consumption for transmission synchronizers. REACH substance restrictions force legacy additive substitution toward boron nitride and certified food-grade graphite. Stuttgart precision manufacturing clusters bundle dry lubricants with Henkel AG surface preparation distribution networks.
China
Domestic boron nitride production capacity expansion responds to fluoropolymer substitution demand from export-oriented manufacturers. GB standards and MEE environmental guidelines tighten permissible binder chemistries for bonded film applications. Yangtze River Delta industrial zones concentrate powder coating retrofit service providers serving automotive Tier-1 suppliers.
Japan
METI industrial policy supports ceramic-based solid lubricant R&D as technical hedge against PTFE supply vulnerability. Primary boron nitride feedstock suppliers concentrate production in Nagoya and Osaka manufacturing basins. Precision assembly equipment OEMs specify application-engineered pastes where liquid lubricants risk contamination.
United Kingdom
Medical device lubrication demand escalates under EU MDR compliance timelines for surgical instruments and implantable devices. ECHA evaluations of per- and polyfluoroalkyl substances compress PTFE availability for pharmaceutical equipment manufacturers. Midlands aerospace maintenance providers adopt laser-deposited coating processes for turbine blade overhaul.
Solid/Dry Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, application engineering, and distribution channels. The vendor base segments into three strategic archetypes: fluoropolymer heritage houses leveraging polymer science depth, industrial adhesives bundlers integrating surface preparation systems, and application-engineered specialists serving precision assembly specifications. Dominant competitive moves include regulatory pre-certification of alternative binders and geographic expansion of retrofit coating service networks.
Within the diversified conglomerate tier, DuPont and Henkel AG occupy positions defined by materials science heritage and European distribution infrastructure respectively. Klüber Lubrication exemplifies the pure-play specialist archetype, anchoring application-engineered paste and stick formulations for precision manufacturing segments. These three entities represent distinct strategic postures: polymer backbone control, integrated surface preparation bundling, and specification-grade application expertise.
| Leading Market Players |
|---|
| DuPont |
| Henkel AG & Co. KGaA |
| Illinois Tool Works Inc. |
| CASTROL LIMITED |
| Klüber Lubrication |
| Sun Coating Company |
| Slickote Coatings |
| Everlube |
| Lubrication Engineers |
| Others |
Value Network & Pricing Analysis
Aerospace maintenance divisions consolidating vendor relationships around multi-year service contracts are forcing suppliers to unbundle material supply from application labor, compressing margins on commodity formulations while preserving premiums on specification-grade pastes.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for powder coating retrofit services. Three-tier pricing structure across aerospace specification-grade, industrial certified-grade, and general manufacturing commodity-grade levels separates margin capture. Cost compression in food-grade graphite formulations is intensifying because REACH substance restrictions accelerate substitution from legacy additives. Tier-1 automotive suppliers in Germany exhibit lowest price sensitivity due to bundled surface preparation procurement, while smaller industrial buyers in general manufacturing show highest sensitivity to per-kilogram powder costs.
Supply Chain Analysis
Dual-sourcing mandates from Pratt & Whitney and GE Aviation specifications require qualified suppliers to maintain redundant boron nitride feedstock relationships. Primary production concentrates in Japan, China, and Germany. Formulation draws from hexagonal boron nitride powder, fluoropolymer resin matrices, and ceramic-based binder chemistries. Single-source vulnerability threatens extreme-temperature formulations as ECHA evaluations compress PTFE availability. Distribution runs through Henkel AG's European industrial adhesives networks and direct technical sales forces serving aerospace MRO providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA toxicity evaluations in the United States and REACH compliance timelines in Europe creates geographic cost differentials for formulation houses with dual-certification infrastructure.
For Market Incumbents: Hedge PTFE supply vulnerability by accelerating boron nitride formulation R&D and securing Japanese feedstock offtake agreements before competitor qualification. Defend specification-grade paste margins through captive application engineering talent pools in Stuttgart and Connecticut manufacturing corridors. Prioritize pre-certification of ceramic-based alternative binders under EPA TSCA evaluations to maintain aerospace OEM approval status. For New Entrants and Emerging Players: Begin with laser-deposited coating services for turbine blade retrofit, bypassing OEM specification cycles that incumbents control. Medical device lubrication under EU MDR compliance offers the most penetrable white space due to extended validation timelines filtering established competitors. Partner with Lufthansa Technik or Delta TechOps maintenance divisions for reference credibility in aerospace aftermarket entry. For Investors and Strategic Acquirers: Asymmetric upside sits with application-engineered specialists possessing regulatory testing infrastructure and precision assembly line relationships. Five-to-ten year viability favors targets with backward integration into boron nitride sourcing or captive surface preparation bundling capabilities. Watch ECHA final determinations on per- and polyfluoroalkyl substance restrictions as inflection indicator for fluoropolymer-dependent formulation houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Nitride Sourcing | Secures feedstock independence from Japanese and Chinese suppliers as REACH restrictions accelerate. |
| Regulatory Pre-Certification Investment | Captures filtered market access under EPA TSCA and EU MDR compliance timelines. |
| Laser-Deposited Coating Service Expansion | Bypasses OEM redesign cycles at Lufthansa Technik and Delta TechOps maintenance divisions. |
| Surface Preparation System Bundling | Locks in maintenance provider loyalty through Henkel AG-style integrated procurement. |
| Application Engineering Talent Acquisition | Secures scarce formulation chemists competing for precision assembly line specifications. |
Research Methodology
Bottom-up aerospace and automotive end-use modeling reconciled against top-down boron nitride and PTFE supply tracking forms the analytical core. Primary interviews with maintenance directors at Lufthansa Technik and Delta TechOps, formulation chemists at Klüber Lubrication, procurement leads at Henkel AG distribution networks, and plant engineers in Baden-Württemberg precision manufacturing clusters combined with secondary validation from EPA TSCA filings, ECHA substance restriction databases, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data for fluoropolymer and ceramic powder imports.
Input-output matrices connect raw material availability constraints to finished formulation demand across chemistry type, physical form, and procurement channel dimensions. Modeled segmentation spans PTFE, molybdenum disulfide, graphite, and boron nitride chemistries; powder, paste, stick, and coating forms; and OEM, Tier-1 supplier, maintenance provider, and industrial user channels. CAGRs derive from regression analysis against aerospace turbine maintenance cycle frequencies and automotive OEM production schedules. Forecast inputs include REACH substance restriction implementation timelines and EPA toxicity evaluation completion trajectories.
Several conditions sit outside the modeled scope, including unannounced mergers among boron nitride primary suppliers, breakthrough ceramic lubricant technologies displacing hexagonal formulations, and geopolitical trade restrictions on Japanese or Chinese feedstock exports. Deviation in ECHA final determinations on per- and polyfluoroalkyl substance restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Polyurea Greases Market
Lubricants
Food Grade Lubricant Market
Lubricants
Offshore Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Europe Metalworking Fluids Market