
 Battery Pack Balancer Market | 2026-2036
Battery Pack Balancer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Pack Balancer Market Insights
Multi-source procurement for battery management ICs is hardening as automakers reduce dependency on single semiconductor vendors. Texas Instruments leverages its analog portfolio depth to sustain design wins across Tier 1 battery suppliers. Analog Devices anchors high-precision voltage sensing architectures in premium EV platforms. NXP Semiconductors competes on automotive-grade functional safety integration.
A battery pack balancer is an electronic subsystem that redistributes charge among series-connected cells to prevent overvoltage, undervoltage, and thermal runaway, typically operating with millivolt-level accuracy and switching frequencies above 100 kHz. Its commercial purpose is to maximize usable pack capacity, extend cycle life, and satisfy safety mandates in high-voltage energy storage. Passive balancers still occupy the volume tier in cost-sensitive consumer electronics, while active balancers are extending into EV and grid-scale storage where efficiency losses carry larger economic weight. Smart balancers with integrated state-of-estimation algorithms are capturing margin pools in renewable energy systems requiring predictive maintenance.
The EU Battery Regulation and CE marking requirements are forcing cell-level traceability and balanced state-of-health reporting across imported packs. China's NMPA and GB standards mandate thermal propagation containment that elevates balancer response speed specifications. India's BIS and automotive PLI scheme are localizing testing infrastructure for imported battery management subsystems. Stakeholders must decide whether to develop captive balancer firmware or license adaptive algorithms from semiconductor partners as cell chemistries diversify.
Market Dynamics
Active balancing architectures are displacing passive resistor networks as electric vehicle platforms prioritize energy recovery and thermal management precision across heterogeneous cell chemistries.
Growth Catalysts
- EU Battery Regulation:Mandatory cell-level state-of-health documentation and balanced charge reporting is forcing OEMs to upgrade from basic passive systems to intelligent active balancers with integrated monitoring.
- Lithium iron phosphate (LFP) chemistry proliferation:Wider voltage plateaus in LFP cells demand tighter millivolt-level balancing accuracy than traditional nickel-manganese-cobalt packs, accelerating precision hardware procurement.
- Grid-scale storage deployment:Utility-scale battery installations in Germany and California require predictive maintenance capabilities that only smart balancers with embedded state-estimation algorithms can deliver.
Market Restraints
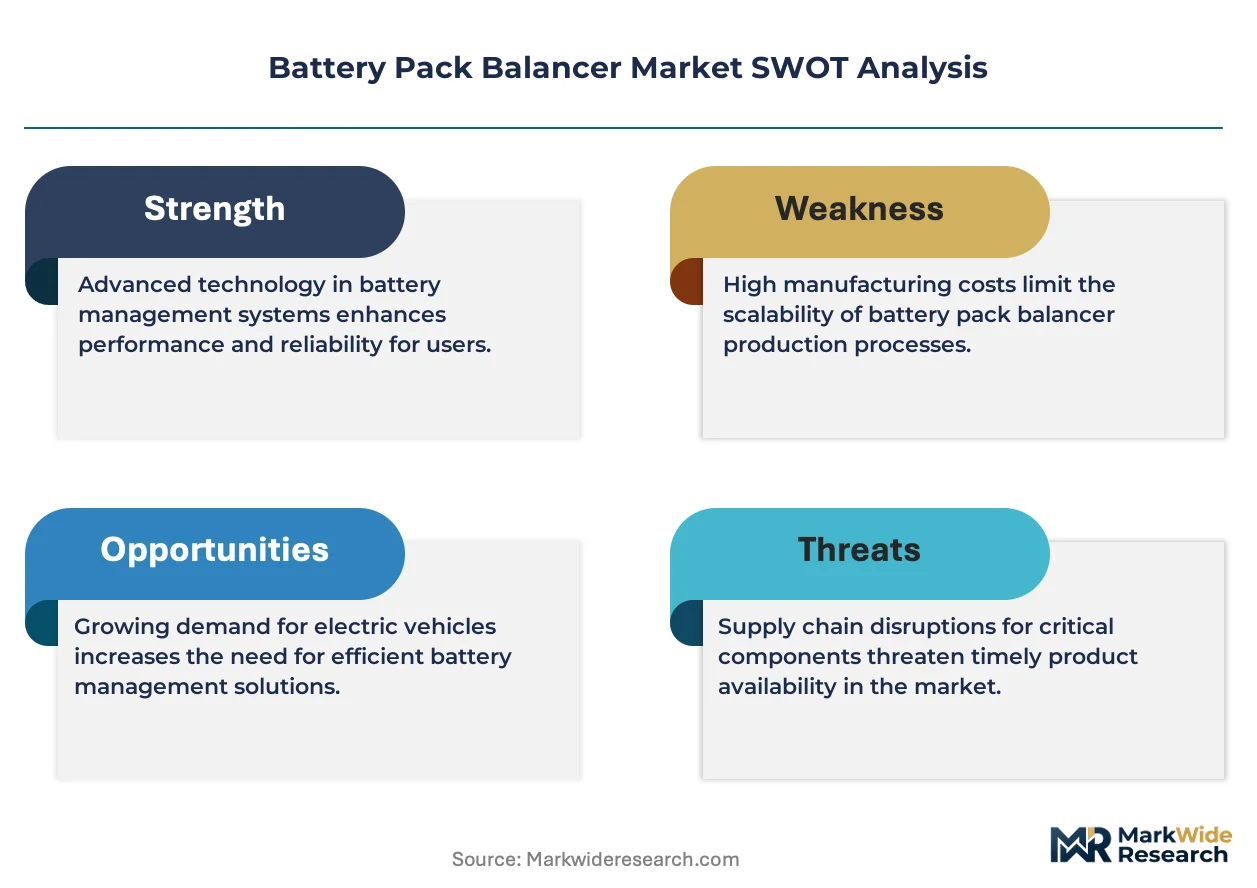
- Inductor and transformer cost volatility:Active balancing subsystems rely on magnetics whose raw material exposure to rare earth pricing swings compresses gross margins for system integrators.
- Semiconductor foundry concentration:Automotive-grade battery management ICs face allocation constraints from Taiwan-based fabrication capacity, extending lead times for Tier 1 suppliers.
- Passive balancer substitution persistence:Consumer electronics and low-cost mobility applications continue specifying resistor-based bleeding circuits that undercut active system pricing by 60-80 percent.
Strategic Opportunities
- India automotive PLI scheme:Localized testing infrastructure mandates for imported battery management subsystems create entry points for foreign balancer firmware licensors partnering with domestic pack assemblers.
- Solid-state battery convergence:Next-generation ceramic electrolyte cells with silicon-anode architectures will require entirely new balancing voltage thresholds, opening design-win windows for adaptive algorithm providers.
- Second-life stationary storage:Repurposed EV packs with degraded cells need granular cell-level bypass capability that smart balancers with dynamic reconfiguration can monetize through hardware-as-a-service models.
Industry Challenges
- Embedded firmware talent scarcity:State-estimation algorithm development requires electrochemistry-aware control engineers whose cross-disciplinary training pipelines remain underdeveloped in automotive hubs.
- ISO 26262 functional safety certification timelines:ASIL-D qualification for active balancing hardware stretches 18-24 months, delaying platform launches for EV programs with compressed development cycles.
- Legacy pack architecture integration:Retrofitting intelligent balancers into existing 400V and 800V platforms without redesigning junction box layouts forces costly mechanical re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Pack Balancer Market |
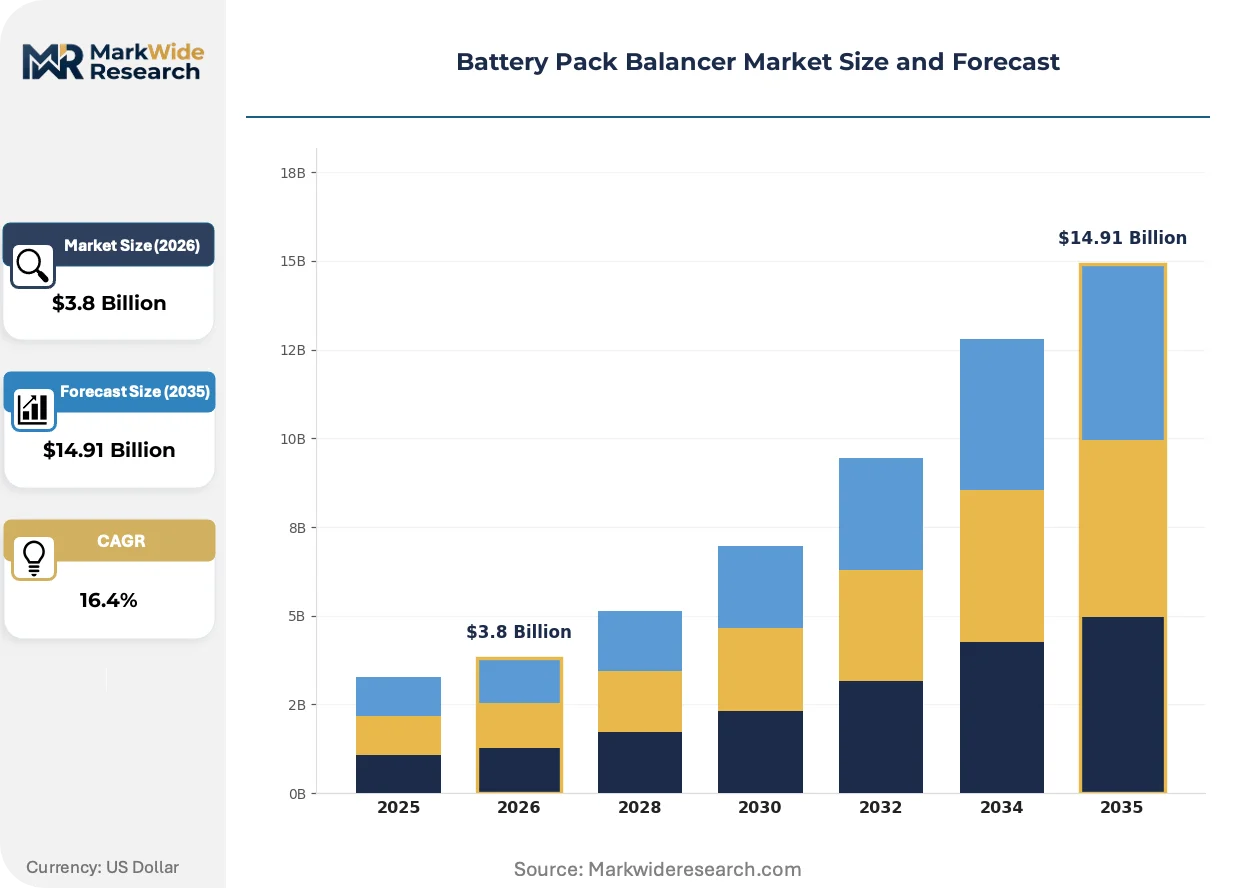
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Balancers, Active Balancers, Hybrid Balancers, Smart Balancers Technology: Voltage Regulation, Current Equalization, Temperature Control, Monitoring Systems End User: Electric Vehicles, Renewable Energy Systems, Consumer Electronics, Industrial Equipment Application: Energy Storage, Power Management, Battery Optimization, Load Balancing |
| Companies Covered | Texas Instruments, Analog Devices, NXP Semiconductors, LG Energy Solution, Panasonic Holdings Corporation, Eberspächer, Sensata Technologies, STMicroelectronics, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Pack Balancer Market Trends and Innovations
Transformer-coupled active balancing is rewriting how energy moves between cells, while regulatory traceability mandates and procurement centralization are compressing vendor selection cycles across automotive supply chains.
Transformer-coupled resonant converters is rewriting charge redistribution economics by enabling 90-plus percent energy recovery between series-connected cells rather than dissipating excess as heat. Premium EV platforms from Stuttgart to Shanghai are adopting these architectures for 800V systems. The technology is rewriting supplier margin structures by shifting value capture from discrete power components toward integrated magnetics and control firmware.
China's GB standards for thermal propagation containment are mandating sub-100-millisecond balancer response times that passive systems cannot achieve. The industrial consequence is a technical barrier to entry for cost-optimized suppliers lacking active switching expertise. Pack manufacturers serving the NMPA-certified market are responding by captive-sourcing high-speed gate drivers and isolated communication links.
Automotive OEMs are consolidating battery management procurement under centralized commodity councils rather than delegating to individual platform teams. Tier 1 suppliers face compressed negotiation windows and mandatory second-source requirements that favor semiconductor partners with broad analog portfolios. The shift is most visible in Germany's automotive supply corridor, where Stuttgart-based OEMs now mandate cross-platform balancer standardization across their entire EV lineup.
Battery Pack Balancer Market Segmentation
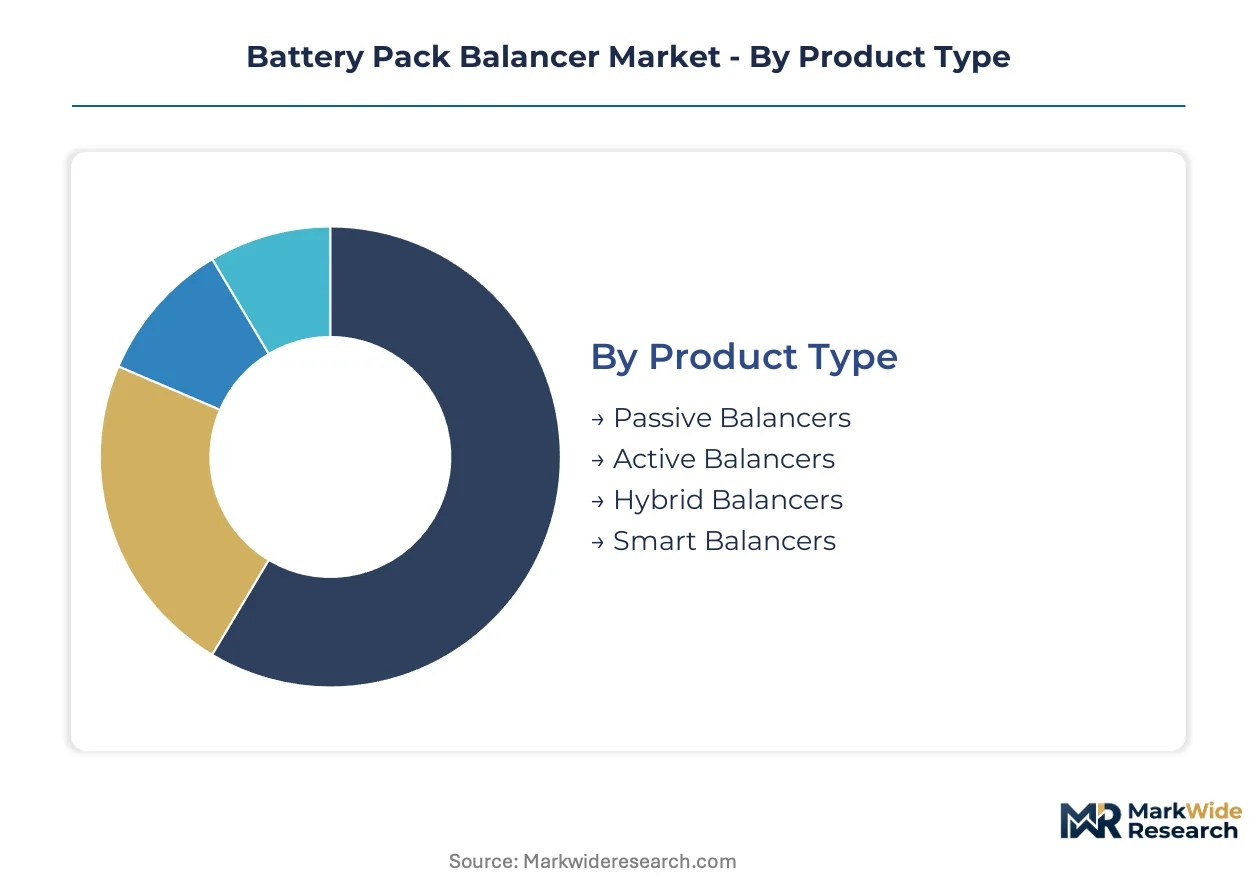
Battery pack balancer procurement decisions hinge on energy efficiency targets, cell chemistry requirements, and regulatory compliance burdens that vary sharply across end-use applications. Segmentation reveals how passive architectures retain cost-driven niches while active and smart systems capture premium platforms demanding predictive capabilities.
Product Type:
Cost tier determines architecture selection, with passive systems dominating price-sensitive volume and active configurations penetrating efficiency-critical premium applications.
- Passive Balancers:Resistor-based bleeding circuits dissipate excess cell charge as heat through simple resistive networks. Consumer electronics manufacturers in Shenzhen and low-cost mobility producers across India specify these systems where unit economics override energy recovery priorities.
- Active Balancers:Inductor, capacitor, or transformer-coupled architectures redistribute charge between cells with 85-95% energy recovery. Electric vehicle platforms in Germany's Stuttgart-Munich corridor and grid-scale installations in California mandate these systems to satisfy thermal management and cycle-life extension requirements.
- Hybrid Balancers:Combined passive-active architectures switch between modes based on state-of-charge differentials. Industrial equipment OEMs favor these for mixed-duty cycles where cost and efficiency tradeoffs vary by operating condition.
- Smart Balancers:Embedded state-estimation algorithms enable predictive maintenance and dynamic reconfiguration. Renewable energy developers in Germany deploy these for second-life stationary storage requiring granular cell-level bypass capability.
Volume sits with Passive Balancers; growth tilts toward Smart Balancers.
Technology:
Functional specialization tracks the precision demands of heterogeneous cell chemistries and widening voltage plateau differentials.
- Voltage Regulation:Millivolt-level sensing and switching circuits maintain cell voltage within narrow tolerance bands. Lithium iron phosphate proliferation in Chinese EV platforms demands tighter accuracy thresholds than legacy nickel-manganese-cobalt packs required.
- Current Equalization:Charge redistribution mechanisms balance amp-hour capacity across series strings. Active architectures employing this technology are displacing passive networks as NMPA thermal propagation mandates tighten response speed specifications.
- Temperature Control:Thermal sensing integration prevents localized heating that accelerates cell degradation. High-voltage 800V platforms incorporate these subsystems to manage heterogeneous thermal profiles across large-format pouch and prismatic cells.
- Monitoring Systems:Isolated communication links and diagnostic telemetry enable cell-level traceability. EU Battery Regulation compliance now requires these capabilities for state-of-health documentation across imported battery packs.
Deployment concentrates in Voltage Regulation; capability expansion centers on Monitoring Systems.
End User:
Application maturity and procurement scale separate established automotive demand from emerging stationary storage opportunities.
- Electric Vehicles:High-voltage traction battery packs with 400V and 800V architectures require ASIL-D qualified balancing subsystems. OEMs in Germany and China consolidate procurement under centralized commodity councils, compressing vendor selection cycles.
- Renewable Energy Systems:Utility-scale and residential solar-plus-storage installations demand predictive maintenance algorithms. Grid operators in California and Germany specify smart balancers for predictive state-of-health estimation.
- Consumer Electronics:Portable power banks and personal electronics specify passive resistor networks. Cost optimization in Shenzhen manufacturing clusters sustains demand for bleeding-circuit architectures.
- Industrial Equipment:Forklifts, material handling systems, and backup power units balance duty-cycle variability with capital constraints. Hybrid balancer architectures address this segment's mixed efficiency requirements.
Revenue concentrates in Electric Vehicles; capability requirements are steepest in Renewable Energy Systems.
Application:
System-level integration depth separates standalone balancing functions from embedded optimization platforms.
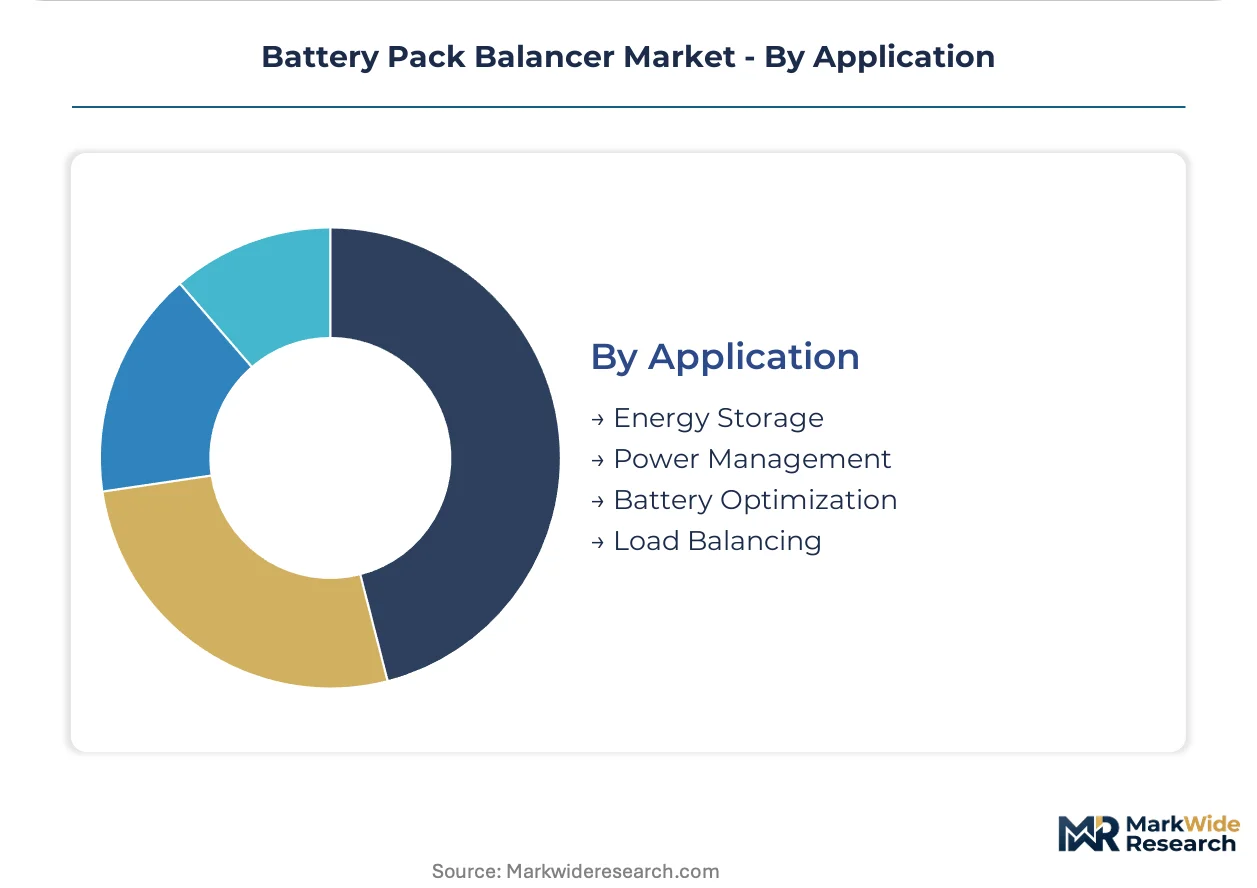
- Energy Storage:Grid-scale and residential battery installations prioritize round-trip efficiency and cycle-life extension. Active balancing penetration is highest here as economic weight of energy losses compounds across decade-long operational horizons.
- Power Management:Real-time load matching and discharge rate control protect cell integrity. Industrial and commercial applications employ these capabilities to manage peak shaving and demand response participation.
- Battery Optimization:Capacity maximization algorithms extract usable energy from degraded or mismatched cells. Second-life EV pack repurposing relies on smart balancer dynamic reconfiguration to monetize heterogeneous cell states.
- Load Balancing:Distributed charge distribution across parallel strings prevents localized stress. Multi-megawatt grid installations deploy these architectures to manage cell-to-cell variation across thousands of series-connected units.
System value pools in Energy Storage; technical complexity peaks in Battery Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnetics processing in Jiangxi Province supplies the inductive cores that active balancing architectures require. Cell chemistry diversity and regulatory tightening are redistributing procurement patterns across three continents.
China
Domestic EV manufacturers are scaling 800V platform deployments that demand sub-100-millisecond balancer response speeds. NMPA thermal propagation mandates and GB standards enforce cell-level monitoring that passive systems cannot satisfy. Pack assemblers in Shenzhen and Ningbo are captive-sourcing high-speed gate drivers to meet certification timelines.
Germany
Stuttgart-based OEMs have centralized battery management procurement under commodity councils mandating cross-platform balancer standardization. EU Battery Regulation requires state-of-health documentation that elevates smart balancer specifications. The Munich-Stuttgart supply corridor concentrates Tier 1 system integration for premium EV platforms.
United States
Grid-scale storage developers in California specify predictive maintenance algorithms for decade-long operational horizons. NHTSA safety guidelines and FERC interconnection standards shape high-voltage pack design requirements. Texas and Arizona utility installations are driving procurement of transformer-coupled resonant architectures.
India
Automotive PLI scheme incentives are localizing testing infrastructure for imported battery management subsystems. BIS certification mandates and DGFT import regulations create entry barriers for foreign firmware providers. Tamil Nadu and Maharashtra pack assemblers are partnering with semiconductor licensors to satisfy domestic content thresholds.
Japan
Precision voltage sensing requirements from silicon-anode solid-state development programs are reshaping balancer specifications. METI battery safety guidelines and JIS standards govern high-voltage energy storage integration. Automotive suppliers in Nagoya and Tokyo are qualifying ASIL-D hardware for next-generation ceramic electrolyte platforms.
Battery Pack Balancer Market Competitive Landscape
Strategic partnerships dominate the current landscape as semiconductor vendors align with Tier 1 battery system integrators. The vendor base clusters around three archetypes: analog specialists with automotive-grade functional safety portfolios, diversified electronics conglomerates with captive cell manufacturing, and power management specialists with magnetics integration expertise. Competitive positioning hardens through M&A activity targeting embedded firmware capabilities and geographic expansion into localized testing markets.
Within the analog-centric tier, Texas Instruments and Analog Devices occupy positions defined by precision sensing architectures and millivolt-level accuracy specifications. NXP Semiconductors exemplifies the functional safety-integrated archetype through automotive-grade ASIL-D qualification pathways. STMicroelectronics and Renesas Electronics represent diversified semiconductor houses with power management portfolios extending into battery management subsystems. These five anchors collectively illustrate how competitive differentiation concentrates in firmware integration depth and automotive certification velocity rather than discrete component manufacturing scale.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Eberspächer |
| Sensata Technologies |
| STMicroelectronics |
| Renesas Electronics |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM commodity councils in Germany's Stuttgart-Munich corridor dictate contract structures that bundle ASIL-D certification costs into multi-year supply agreements, compressing spot-market pricing flexibility for Tier 1 battery system integrators.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium smart balancer offerings from unbundled hardware-only transactions in the active balancing segment. Three-tier pricing structure across premium, standard, and economy levels tracks ASIL-D certification grade, with OEM-direct contracts commanding 40-60% premiums over aftermarket channels. Cost compression in passive resistor networks is intensifying because Shenzhen-based consumer electronics manufacturers are consolidating purchase volumes. Low-cost mobility producers across India exhibit the highest price sensitivity, while German premium EV platforms prioritize millivolt accuracy over unit cost.
Supply Chain Analysis
ISO 26262 ASIL-D qualification timelines of 18-24 months gate entry for automotive-grade battery management ICs, concentrating qualified supply among Taiwan, South Korea, and USA fabrication facilities. Active balancing architectures draw from rare earth magnetics processed in Jiangxi Province, automotive-grade silicon from Taiwan-based foundries, and precision voltage sensing components from Japanese analog specialists. Single-source vulnerability in Taiwan semiconductor fabrication exposes lead time volatility for high-speed gate drivers. Distribution runs through Tier 1 battery system integrators with captive firmware development capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery pack balancer market functions as a vertical-integration race where semiconductor vendors are pursuing backward integration into embedded state-estimation firmware to capture margin pools shifting from discrete components toward algorithmic control.
For Market Incumbents: Hedge against passive balancer substitution persistence in cost-sensitive segments by accelerating ASIL-D certification velocity for next-generation transformer-coupled architectures. Captive magnetics sourcing from Jiangxi Province suppliers insulates gross margins from rare earth pricing swings. Reinforce design-win stickiness through cross-platform standardization mandates across OEM commodity councils. For New Entrants and Emerging Players: Direct-to-OEM firmware licensing platforms offer the most penetrable route into India's automotive PLI scheme, where domestic pack assemblers require adaptive algorithm partnerships to satisfy BIS certification thresholds. Target second-life stationary storage applications requiring dynamic cell-level bypass capability that incumbent hardware vendors underserve. White-label smart balancer modules for renewable energy developers in California and Germany seeking predictive maintenance capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor electrochemistry-aware firmware specialists in Japan and Germany as solid-state battery development programs reshape voltage threshold specifications. Long-term viability over the next decade rests on adaptive algorithm portfolios that transcend specific cell chemistries. Watch NMPA thermal propagation mandate enforcement velocity as the inflection signal for active balancing hardware procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses 18-24 month qualification timelines to match compressed EV platform development cycles in Germany. |
| Backward Integration into Firmware | Captures margin pools shifting from discrete power components toward state-estimation algorithms in premium EV platforms. |
| Localized Testing Infrastructure Partnerships | Satisfies India's BIS and PLI scheme domestic content thresholds for foreign semiconductor licensors. |
| Transformer-Coupled Resonant Architecture Deployment | Enables 90-plus percent energy recovery for 800V systems in China's NMPA-certified market. |
| Second-Life Storage Hardware-as-a-Service | Monetizes granular cell-level bypass capability for repurposed EV packs with degraded heterogeneous cells. |
Research Methodology
Independent corroboration across primary interviews with Tier 1 battery system integrators, OEM platform engineers, and semiconductor vendor application teams, combined with secondary validation through NMPA filings, EU Battery Regulation implementation documents, and automotive production databases, underwrites the qualitative findings. Bottom-up triangulation across product-type segmentation and top-down cross-checks against regional EV deployment data anchor the market sizing.
Comparable-period anchoring to historical EV platform launch cycles and grid-scale storage procurement waves structures the projection horizon. The analytical framework models active, passive, hybrid, and smart balancer architectures across voltage regulation, current equalization, temperature control, and monitoring system technologies, with electric vehicle, renewable energy, consumer electronics, and industrial equipment end-use segments. CAGRs derive from cell chemistry proliferation rates and regulatory mandate enforcement timelines, with LFP chemistry adoption and thermal propagation response speed specifications as key forecast inputs.
The model holds under stable NMPA and EU Battery Regulation enforcement trajectories; deviation in semiconductor foundry allocation constraints or rare earth magnetics pricing volatility would shift procurement patterns toward hybrid architectures. A model refresh is warranted upon material change in solid-state battery commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Iron-Chromium Flow Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
US Solar Battery Market
Batteries
China Battery Market
Batteries
Wood-Based Batteries Market
Batteries
India Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Japan Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Italy SLI Battery Market
Batteries
Battery Cell Market
Batteries
Seawater Battery Market
Batteries
South America Primary Battery Market
Batteries
High Temperature NiMH Battery Market