
 Asia Pacific Electric Generators Market | 2026-2036
Asia Pacific Electric Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Generators Market Outlook
Chinese generator manufacturing is consolidating around tier-one coastal provinces with integrated engine foundries and alternator winding facilities. Cummins Inc leverages its joint-venture engine platforms to dominate mid-range diesel sets across ASEAN infrastructure projects. Mitsubishi Heavy Industries Ltd anchors the heavy-duty gas turbine generator segment through localized production and regional service networks.
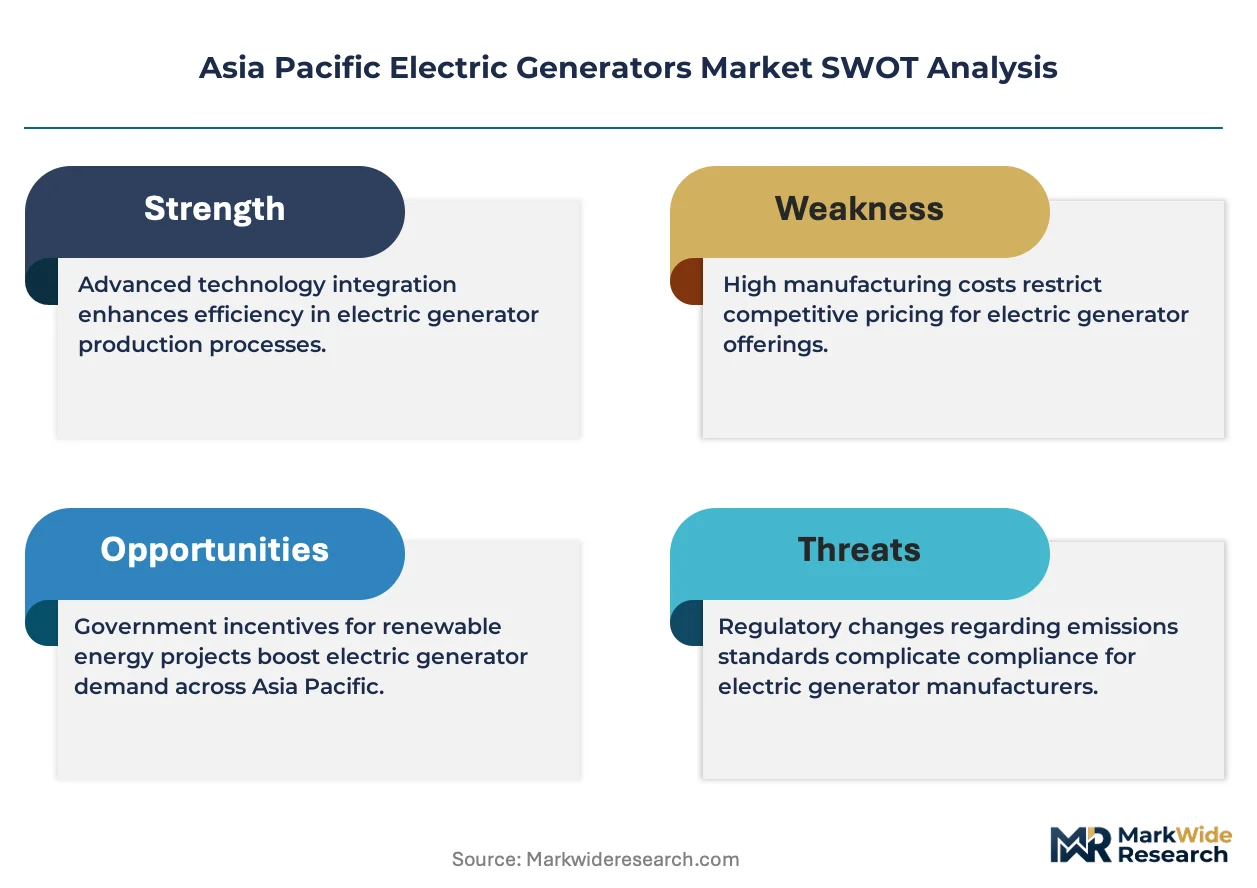
Asia Pacific electric generators are electromechanical devices converting mechanical energy into electrical output, typically rated between 1 kW and multi-megawatt scales, using electromagnetic induction via rotating armatures within stator windings to serve prime, standby, or emergency power functions. Diesel generators retain the largest installed base across industrial and construction end users due to fuel accessibility and load-following reliability, while inverter generators are gaining share among residential buyers seeking quieter operation and cleaner waveform output for sensitive electronics. Standby generators command premium pricing in commercial segments where automatic transfer switches and NFPA 110 compliance create specification barriers.
India's Central Pollution Control Board enforces emission standards for diesel generators under the Environment Protection Act, compelling manufacturers to adopt common-rail fuel injection and exhaust after-treatment. China's Ministry of Ecology and Environment implements GB standards for non-road mobile machinery that restrict particulate matter from generator engines in urban construction zones. Australia's Clean Energy Regulator tracks backup generator fuel use under emission reporting frameworks for large facilities. Stakeholders must weigh dual-fuel capability investments against the pace of grid reliability improvements and renewable-plus-storage alternatives across the region's diverging power infrastructure trajectories.
Market Dynamics
India's Bureau of Indian Standards emission tightening for diesel generator sets is compressing product lifecycles and forcing engine architecture redesigns across the region's manufacturing base.
Growth Catalysts
- Data center captive power:Southeast Asian hyperscale facilities are installing dedicated generation assets to bypass grid instability. Singapore and Jakarta clusters drive specification intensity for low-NOx diesel configurations.
- GB standards enforcement:China's Ministry of Ecology and Environment restrictions on particulate matter from construction-zone generators are accelerating common-rail and SCR adoption in urban equipment fleets.
- Western industrial corridor concentration:Gujarat and Maharashtra manufacturing hubs are consolidating standby power procurement, creating volume pull for 500 kW–2 MW class sets with automatic transfer switch integration.
Market Restraints
- Copper and silicon steel volatility:Alternator core material costs swing with commodity cycles, compressing margin visibility for mid-range set assemblers without captive winding facilities.
- Engine supply concentration:Tier-one diesel engine production clusters in China's coastal provinces create geographic dependency risk for ASEAN generator packagers.
- Grid-plus-storage substitution:Lithium-ion battery systems paired with solar PV are displacing backup diesel in commercial buildings with <4-hour runtime requirements.
Strategic Opportunities
- Vietnam manufacturing expansion:Northern industrial zones around Hai Phong show underpenetrated standby power density as electronics contract manufacturers localize production.
- Dual-fuel retrofit kits:Natural gas blending capability for existing diesel engines opens compliance pathways where China's urban emission zones tighten fastest.
- Remote monitoring integration:IoT-enabled predictive maintenance contracts are penetrating ASEAN rental fleet operators, shifting revenue from equipment sale to uptime guarantee.
Industry Challenges
- Emission calibration expertise:Common-rail fuel mapping and SCR dosing optimization require scarce combustion engineering talent, extending new product validation timelines.
- NFPA 110 certification complexity:Level 1 emergency power system compliance for hospitals and data centers demands witnessed factory testing and third-party witness protocols that strain smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Generators Market |
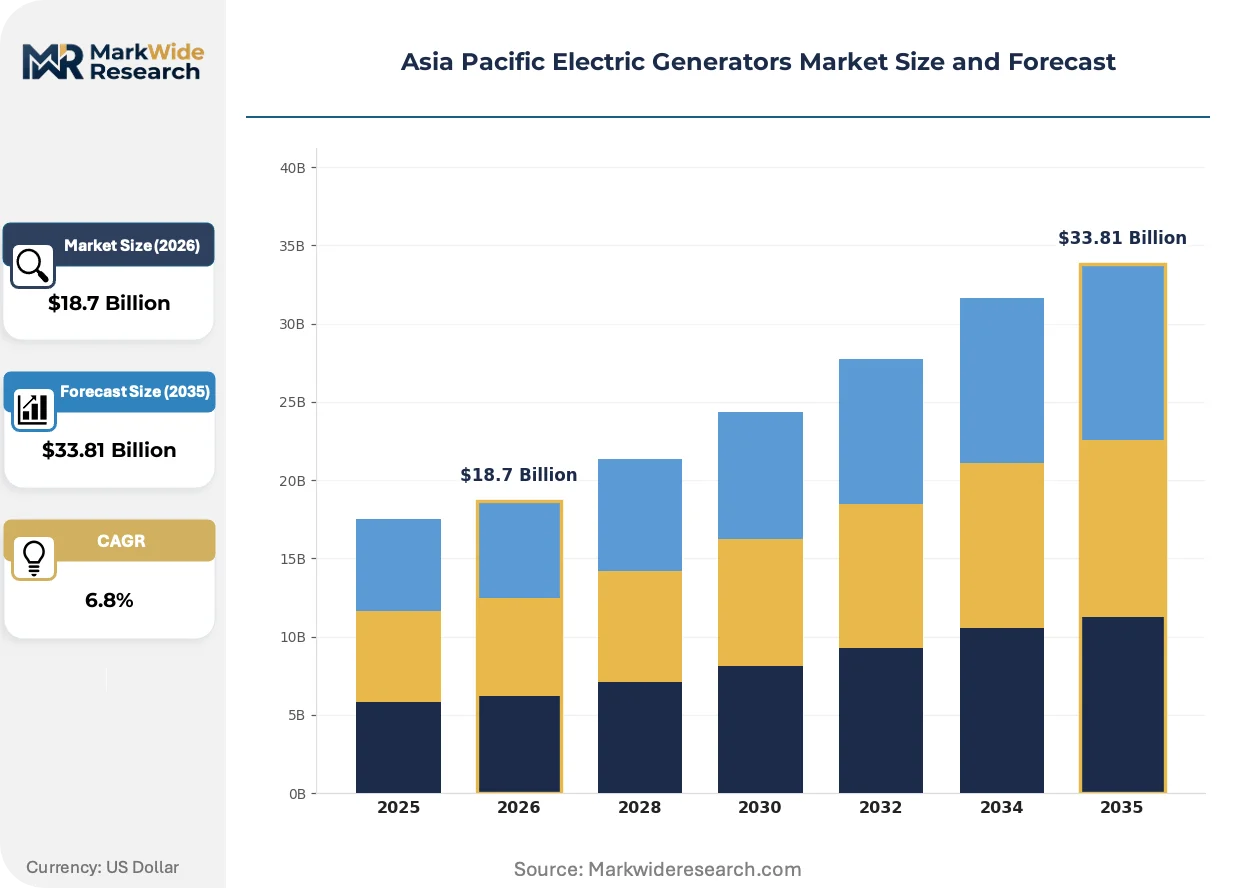
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Diesel Generators Power Rating: 1-5 kW, 6-10 kW, 11-20 kW, Above 20 kW End User: Residential, Commercial, Industrial, Construction Fuel Type: Diesel, Gasoline, Natural Gas, Propane |
| Companies Covered | Cummins Inc, Kohler Co, ABB Ltd, Generac Power Systems, Honda Power Equipment, Siemens AG, Mitsubishi Heavy Industries Ltd, Kirloskar Electric Co. Ltd, Caterpillar Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Generators Market Strategic Shifts
Electrification of off-grid industrial processes and tightening urban emission boundaries are forcing convergence between conventional generator hardware and digital control layers.
Integrated power electronics is unifying variable-speed engine control with inverter output stages in mid-range diesel sets. Australian mining camp operators are specifying these hybrid architectures for 20-40% fuel efficiency gains over fixed-speed alternatives. The technology is compressing the traditional separation between engine governor systems and voltage regulation hardware.
India's Central Pollution Control Board enforcement under the Environment Protection Act is mandating real-time emission monitoring for diesel generators above 800 kW. Industrial users in Delhi-NCR and Mumbai must install PM and NOx sensors with data transmission to state pollution boards. Heavy-duty set manufacturers are responding with factory-integrated telematics that automate compliance reporting.
Equipment-as-service contracting is displacing outright purchase in ASEAN construction rental markets. Singapore-based fleet operators now specify availability-based pricing with maintenance bundled, transferring operational risk to OEM service networks. This model concentrates most visibly in Indonesia's infrastructure project pipeline where contractor balance sheet constraints limit capex deployment.
Asia Pacific Electric Generators Market Segmentation
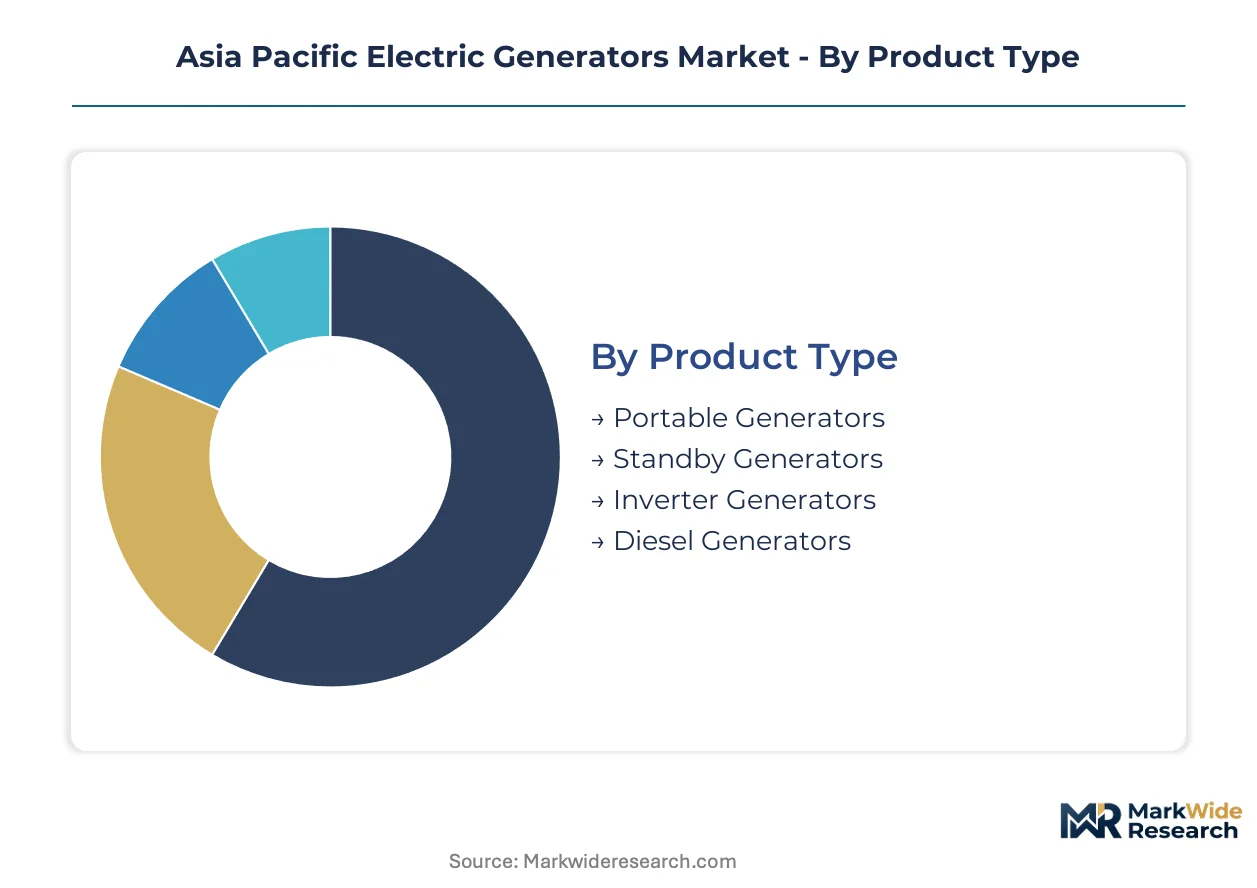
Segmentation in Asia Pacific electric generators reveals distinct procurement patterns across power classes and fuel technologies. Standby installations in Indian manufacturing corridors operate on different economic logic than portable units serving Indonesian construction sites.
Product Type:
Integration depth varies sharply: standby systems demand permanent electrical infrastructure coupling, while portable units function as standalone mobile assets.
- Portable Generators:Compact, wheeled units typically rated below 10 kW with recoil or electric start mechanisms. Demand clusters at Indonesian construction camps and Philippine rural electrification programs where grid extension remains uneconomical. Rental fleet operators in Vietnam specify these for short-duration infrastructure projects.
- Standby Generators:Fixed-installation systems with automatic transfer switch integration for seamless grid failover. Indian data centers in Mumbai and Chennai drive specification intensity for NFPA 110 Level 1 compliance and sub-10-second transfer times. These units command premium pricing through witnessed factory testing protocols.
- Inverter Generators:Microprocessor-controlled units producing clean sine wave output for sensitive electronics. Japanese residential buyers and Australian recreational vehicle owners favor these for noise suppression and fuel efficiency.
- Diesel Generators:Compression-ignition engines dominating industrial prime power and emergency standby applications. China's GB standards enforcement is accelerating common-rail fuel injection adoption across this segment.
Volume placements concentrate in Diesel Generators; the faster expansion belongs to Inverter Generators.
Power Rating:
Cost tier stratification aligns with customer balance sheet capacity and runtime criticality.
- 1-5 kW:Single-phase residential units for household backup during monsoon grid failures. Indian urban middle-class households in Bengaluru and Hyderabad represent concentrated demand for inverter-equipped models.
- 6-10 kW:Small commercial installations for retail stores and medical clinics requiring uninterrupted refrigeration and diagnostic equipment power. Thai hospitality operators specify these for island resorts with unreliable grid connections.
- 11-20 kW:Three-phase systems serving light industrial loads and mid-sized construction sites. Australian mining exploration camps deploy these for drilling rig auxiliary power.
- Above 20 kW:Heavy-duty industrial sets with paralleling capability for manufacturing plants and hyperscale data centers. Gujarat's chemical processing corridor generates sustained procurement for 500 kW–2 MW class units with SCR after-treatment.
Procurement volume clusters in Above 20 kW for industrial applications; the steepest expansion trajectory appears in 6-10 kW commercial installations.
End User:
Application-specific duty cycles and emission compliance requirements create divergent specification pathways.
- Residential:Intermittent-use backup power for urban households and rural homesteads. Indian inverter generator adoption is climbing fastest among apartment dwellers seeking low-noise operation.
- Commercial:Retail, hospitality, and healthcare facilities requiring automatic failover for revenue protection. Singapore's hospital construction pipeline mandates Level 1 emergency power under Ministry of Health regulations.
- Industrial:Continuous prime power and standby for manufacturing processes where downtime costs exceed generator capital expense. Maharashtra's automotive component suppliers specify dual-fuel capability for emission zone compliance.
- Construction:Mobile prime power for equipment operation and site electrification. Indonesia's Trans-Java toll road project consumes substantial rental fleet capacity for batching plants and crane operations.
Industrial buyers generate the largest revenue pool; Construction end users are expanding most quickly across ASEAN infrastructure buildouts.
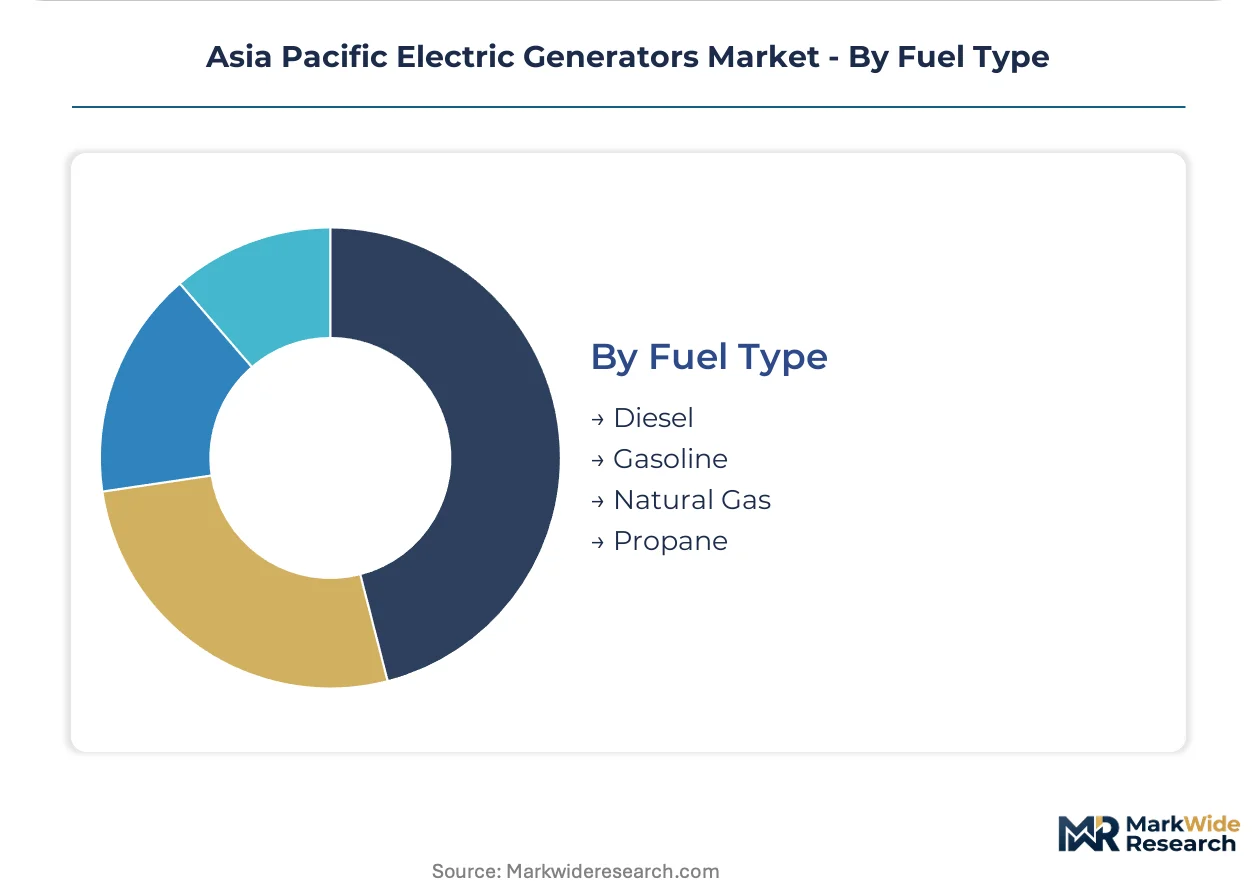
Fuel Type:
Supply concentration and infrastructure maturity dictate regional fuel preferences and technology lock-in.
- Diesel:Energy-dense liquid fuel with established distribution networks across archipelagic Southeast Asia. India's CPCB emission tightening is forcing common-rail architecture redesigns and SCR system integration.
- Gasoline:Spark-ignition engines dominating portable generator applications for ease of starting and lower first cost. Australian bushfire-prone regions restrict gasoline storage quantities, dampening demand.
- Natural Gas:Pipeline or CNG-supplied fuel gaining traction in Chinese urban zones where MEE particulate restrictions apply. Dual-fuel retrofit kits enable diesel engine conversion for compliance.
- Propane:LPG-fueled systems serving remote sites lacking liquid fuel logistics. Philippine island resorts specify these for reduced emissions and simplified fuel handling.
Diesel retains dominant installed base; Natural Gas is gaining share fastest where pipeline infrastructure penetrates Chinese and Australian urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and silicon steel supply chains from China's coastal provinces anchor generator manufacturing across the Asia Pacific. Raw material proximity shapes assembly location decisions for alternator windings and engine castings. India's western industrial corridor and Southeast Asian data center clusters represent the fastest-growing demand poles.
China
GB standards enforcement by the Ministry of Ecology and Environment is accelerating common-rail fuel injection adoption in construction-zone generator fleets. Yangtze River Delta foundries supply alternator laminations to ASEAN packagers. Shanghai and Jiangsu province house integrated engine-alternator manufacturing complexes serving domestic and export markets.
India
The Bureau of Indian Standards emission tightening is compressing diesel generator product lifecycles and forcing engine architecture redesigns. Central Pollution Control Board mandates under the Environment Protection Act require real-time emission monitoring for sets above 800 kW. Gujarat and Maharashtra manufacturing hubs are consolidating standby power procurement for chemical processing and automotive component suppliers.
Japan
METI efficiency regulations and JIS standards certification create specification barriers for emergency power systems in commercial buildings. Kanto region data center operators specify low-NOx diesel configurations with sub-10-second transfer times. Tokyo-Osaka industrial corridor demand concentrates in inverter generators for residential and precision electronics applications.
Australia
The Clean Energy Regulator tracks backup generator fuel use under emission reporting frameworks for large mining and healthcare facilities. Western Australia mining camps specify variable-speed hybrid architectures for fuel efficiency gains. Queensland and New South Wales bushfire-prone regions restrict gasoline storage quantities, dampening portable generator demand.
Vietnam
Northern industrial zones around Hai Phong show underpenetrated standby power density as electronics contract manufacturers localize production. Hai Phong and Bac Ninh provinces attract generator rental fleet operators serving infrastructure buildouts. Electronics manufacturing facility construction is driving specification intensity for 500 kW–2 MW class sets with automatic transfer switch integration.
Asia Pacific Electric Generators Market Competitive Environment
Global majors compete with regional champions across technology licensing and service network density in the Asia Pacific electric generators market. The vendor base stratifies into three tiers: integrated engine-generator manufacturers, alternator-focused assemblers sourcing power units from third parties, and rental fleet operators bundling maintenance contracts. Two strategic archetypes dominate: coastal Chinese fabricators with captive foundry capacity, and ASEAN-based packagers leveraging import duty differentials. Capacity expansion and dual-fuel retrofit kit development represent the primary competitive moves.
Among engine-integrated manufacturers, Cummins Inc exemplifies the joint-venture platform strategy across ASEAN infrastructure projects. Mitsubishi Heavy Industries Ltd occupies a position in heavy-duty gas turbine generators through localized production. Kirloskar Electric Co. Ltd represents the India-focused specialist archetype serving western industrial corridor demand.
| Leading Market Players |
|---|
| Cummins Inc |
| Kohler Co |
| ABB Ltd |
| Generac Power Systems |
| Honda Power Equipment |
| Siemens AG |
| Mitsubishi Heavy Industries Ltd |
| Kirloskar Electric Co. Ltd |
| Caterpillar Inc |
| Others |
Value Chain & Pricing Dynamics
China's Ministry of Ecology and Environment GB standards enforcement gates qualified supply access and premium-tier pricing power by mandating common-rail fuel injection and SCR after-treatment for urban construction-zone generators. Manufacturers lacking emission-certified engine architectures face exclusion from municipal procurement pools, while compliant OEMs capture pricing premiums through witnessed factory testing and NFPA 110 Level 1 certification bundles.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier suppliers from unbundled economy competitors across ASEAN rental markets. Three-tier pricing structure across premium, standard, and economy levels reflects NFPA certification grade, automatic transfer switch integration depth, and telematics inclusion. Cost compression in mid-range diesel sets is intensifying because copper and silicon steel commodity swings erode margin visibility for assemblers without captive alternator winding facilities. Construction rental fleet operators in Indonesia exhibit highest price sensitivity, while Indian data center operators prioritize sub-10-second transfer reliability over unit economics.
Supply Chain Analysis
Freight cost volatility from China's coastal provinces to ASEAN packagers shapes alternator lamination sourcing economics for generator assemblers. Yangtze River Delta foundries, Jiangsu engine casting facilities, and Shanghai integrated manufacturing complexes anchor regional supply. Copper winding wire, silicon steel laminations, and common-rail fuel systems constitute critical input dependencies. Single-source vulnerability concentrates in tier-one diesel engine production clusters, creating geographic dependency risk for ASEAN generator packagers. Distribution runs through OEM-direct project contracting for large industrial installations and rental fleet operators for construction mobility applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over alternator winding facilities and engine foundry capacity determines margin capture and emission compliance velocity.
For Market Incumbents: Extend service network density across Vietnam's northern industrial zones to preempt electronics manufacturing facility demand. Secure captive supply of silicon steel laminations from Yangtze River Delta foundries to defend against commodity cost compression. Battery-plus-solar substitution in sub-4-hour runtime commercial buildings threatens standby diesel volumes; counter with hybrid variable-speed architectures that deliver 20-40% fuel efficiency gains over fixed-speed alternatives. For New Entrants and Emerging Players: The 500 kW–2 MW price-point gap between premium certified sets and economy diesel units offers entry traction in India's western industrial corridor. Target Gujarat chemical processing and Maharashtra automotive component suppliers seeking dual-fuel retrofit capability for emission zone compliance. Penetrate through IoT-enabled predictive maintenance contracts that shift revenue from equipment sale to uptime guarantees, mirroring Singapore-based fleet operator specifications. For Investors and Strategic Acquirers: India's Central Pollution Control Board real-time emission monitoring mandate for sets above 800 kW is the leading indicator that factory-integrated telematics and compliance automation capabilities will concentrate market value. Long-term viability over the next decade hinges on exposure to data center captive power buildouts and dual-fuel technology platforms. Acquisition target archetype: mid-range diesel set assemblers with established SCR calibration expertise and pending NFPA 110 Level 1 certification pathways. Monitor BIS emission standard revision timelines as inflection signals for product lifecycle compression intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternator Winding | Captive lamination capacity insulates margin from copper and silicon steel commodity cycles. |
| Dual-Fuel Retrofit Kit Development | Natural gas blending capability opens compliance pathways in China's tightening urban emission zones. |
| IoT-Enabled Predictive Maintenance Contracts | Revenue model shift from equipment sale to uptime guarantees penetrates ASEAN rental fleet markets. |
| NFPA 110 Level 1 Certification Investment | Witnessed factory testing protocols create specification barriers for hospital and data center procurement. |
| Vietnam Manufacturing Footprint Expansion | Hai Phong and Bac Ninh electronics manufacturing localization drives standby power density growth. |
Study Parameters
Independent corroboration across plant engineers at Indian manufacturing facilities, procurement leads at Southeast Asian data center operators, and aftermarket service heads at ASEAN rental fleet operators underwrites the qualitative findings. Primary interviews with generator set assemblers, engine foundry managers, and emission compliance consultants combined with secondary validation from China's Ministry of Ecology and Environment GB standard filings, India's Central Pollution Control Board enforcement circulars, and Australian Clean Energy Regulator emission reporting frameworks. Bottom-up unit economics modeling and top-down sectoral demand aggregation triangulate volume and value estimates.
Rate-of-change decomposition across diesel generator product lifecycles, inverter generator adoption curves, and hybrid architecture penetration trajectories structures the analytical framework. Segmentation dimensions include power rating tier, fuel technology type, end-use application duty cycle, and regional regulatory cluster severity. CAGRs derive from installed base replacement dynamics, captive power buildout pipelines, and grid reliability improvement trajectories. Forecast inputs incorporate alternator core material cost indices, emission calibration talent availability, and lithium-ion battery cost displacement thresholds.
Inputs from Indian Bureau of Indian Standards draft notifications and China MEE enforcement calendars were available through the study window; gaps in real-time Vietnamese industrial zone power reliability data introduce uncertainty bands around northern electronics manufacturing demand projections. Forecasts reflect documented assumptions regarding grid infrastructure investment pacing and renewable-plus-storage substitution economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Tanzania Diesel Generator Market
Generators
East Africa Diesel Generator Market
Generators
Europe Gas Generator Market
Generators
Europe Portable Generator Market
Generators
Middle East Portable Generator Market
Generators
China Diesel Generator Market
Generators
Middle East and Africa Gas Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Commercial Generator Market
Generators
Europe Gas Turbine Market
Generators
Multi Fuel Generators Market
Generators
Construction Portable Generators Market
Generators
Generator Sets Market
Generators
Southeast Asia Portable Generator Market
Generators
Kuwait Diesel Gensets Market
Generators
Saudi Arabia Diesel Generator Market