
 North America Portable Generators Market | 2026-2036
North America Portable Generators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Portable Generators Market Analysis
Buyer concentration across the North America Portable Generators Market is shifting from dispersed residential purchases toward bulk procurement by national contractors and event management firms. Generac Holdings Inc. leverages its dealer network density across the southeastern United States to capture recurring storm-season demand. Cummins Inc. anchors its position through commercial-grade diesel platforms targeting construction site uptime requirements. Honda Motor Co. Ltd differentiates via inverter technology leadership that serves recreational and residential noise-sensitive applications.
Portable generators are self-contained combustion or solar-electric units that convert mechanical or photovoltaic energy into alternating current, typically delivering outputs from 500W to above 5000W for off-grid or backup power scenarios. Gasoline generators retain the largest installed base due to lower first-cost barriers and fuel accessibility across rural North America. Solar generators represent the fastest-expanding product category as lithium-ion battery costs decline and CARB-compliant zero-emission mandates intensify in California and adjacent states. The 3000W-5000W power rating band captures the dominant margin pool by balancing contractor runtime requirements with transportability constraints.
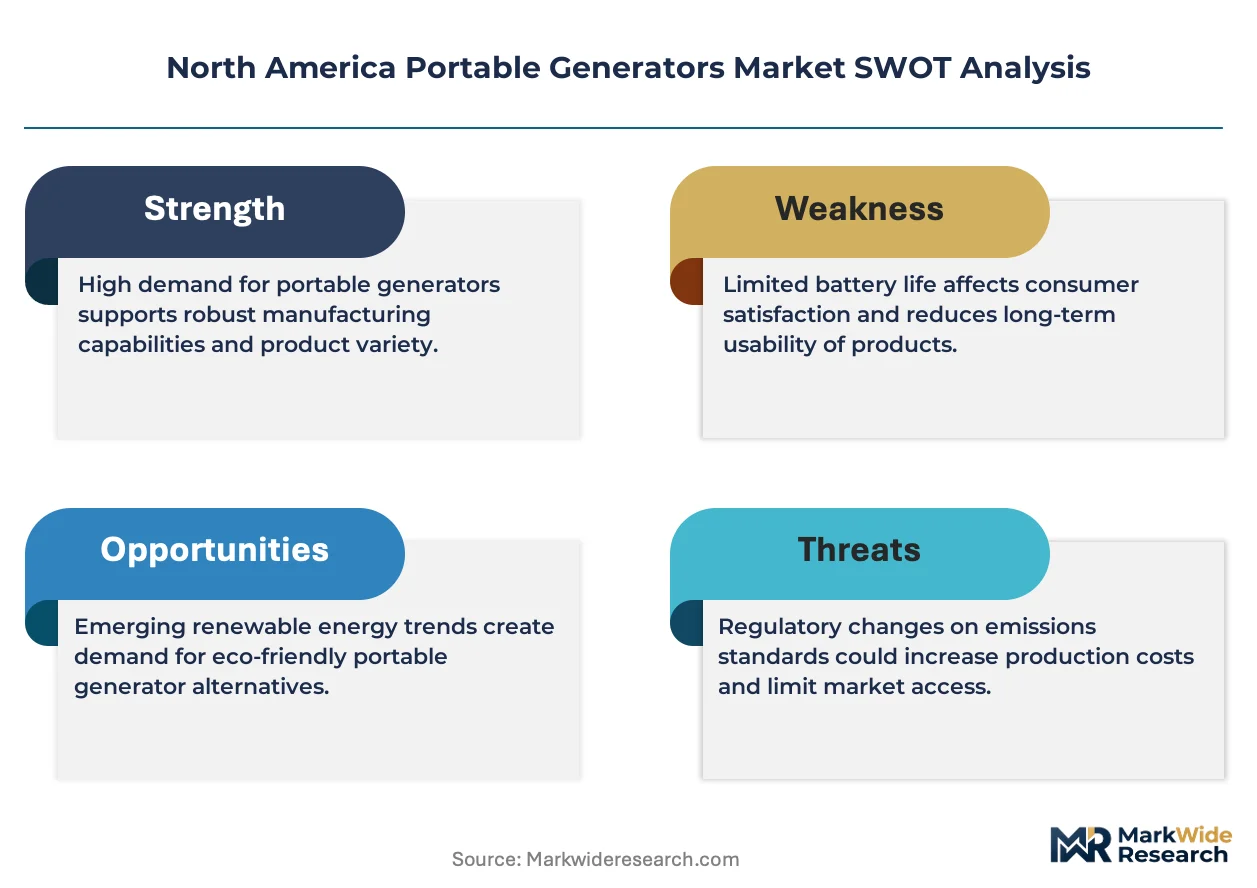
The Environmental Protection Agency (EPA) enforces emissions certification under Tier 4 standards that constrain small-engine designs and elevate compliance costs for gasoline and diesel architectures. California Air Resources Board (CARB) regulations extend beyond federal baselines, effectively creating a bifurcated product landscape where manufacturers must maintain separate SKUs for California-bound distribution. OSHA workplace safety standards govern construction site deployment, mandating ground-fault protection and ventilation protocols that shape feature prioritization. Stakeholders must monitor state-level zero-emission equipment mandates and utility-sponsored resilience programs that could redirect demand toward battery-based alternatives or subsidize standby system upgrades.
Market Dynamics
CARB zero-emission mandates and EPA Tier 4 compliance costs are bifurcating the North America Portable Generators Market into dual-SKU supply chains, forcing manufacturers to maintain separate California-certified and federal-compliant product lines.
Growth Catalysts
- Hurricane-season grid instability:Texas, Florida, and Louisiana residential buyers and contractors are accelerating repeat purchase cycles for backup power systems ahead of peak storm months.
- OSHA workplace safety standards:Ground-fault protection and ventilation protocol mandates on construction sites are elevating specification requirements for contractor-grade units.
- Lithium-ion battery cost decline:Solar-electric generator architectures are achieving price parity with gasoline units in California's zero-emission zones.
Market Restraints
- Small-engine supply concentration:Carburetor and ignition system sourcing from concentrated Southeast Asian suppliers creates input vulnerability.
- CARB certification friction:California's emissions standards extend 18-24 month product development timelines versus federal-only SKUs.
- Diesel particulate filter costs:Tier 4 compliance adds material cost burden to commercial diesel platforms above 25 horsepower.
Strategic Opportunities
- Utility-sponsored resilience programs:Subsidized standby system upgrades in hurricane-prone coastal counties are redirecting portable demand toward battery-based alternatives.
- Event management firm procurement:Festival and outdoor entertainment verticals are consolidating fleet purchases for noise-sensitive inverter units.
- RV and camping channel expansion:Recreational vehicle dealers represent underpenetrated distribution for sub-3000W solar generator SKUs.
Industry Challenges
- Emissions calibration technician scarcity:EPA and CARB certification testing requires specialized small-engine expertise concentrated at limited third-party labs.
- Dual-SKU inventory complexity:Manufacturers face working capital strain maintaining separate California and federal distribution pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Portable Generators Market |
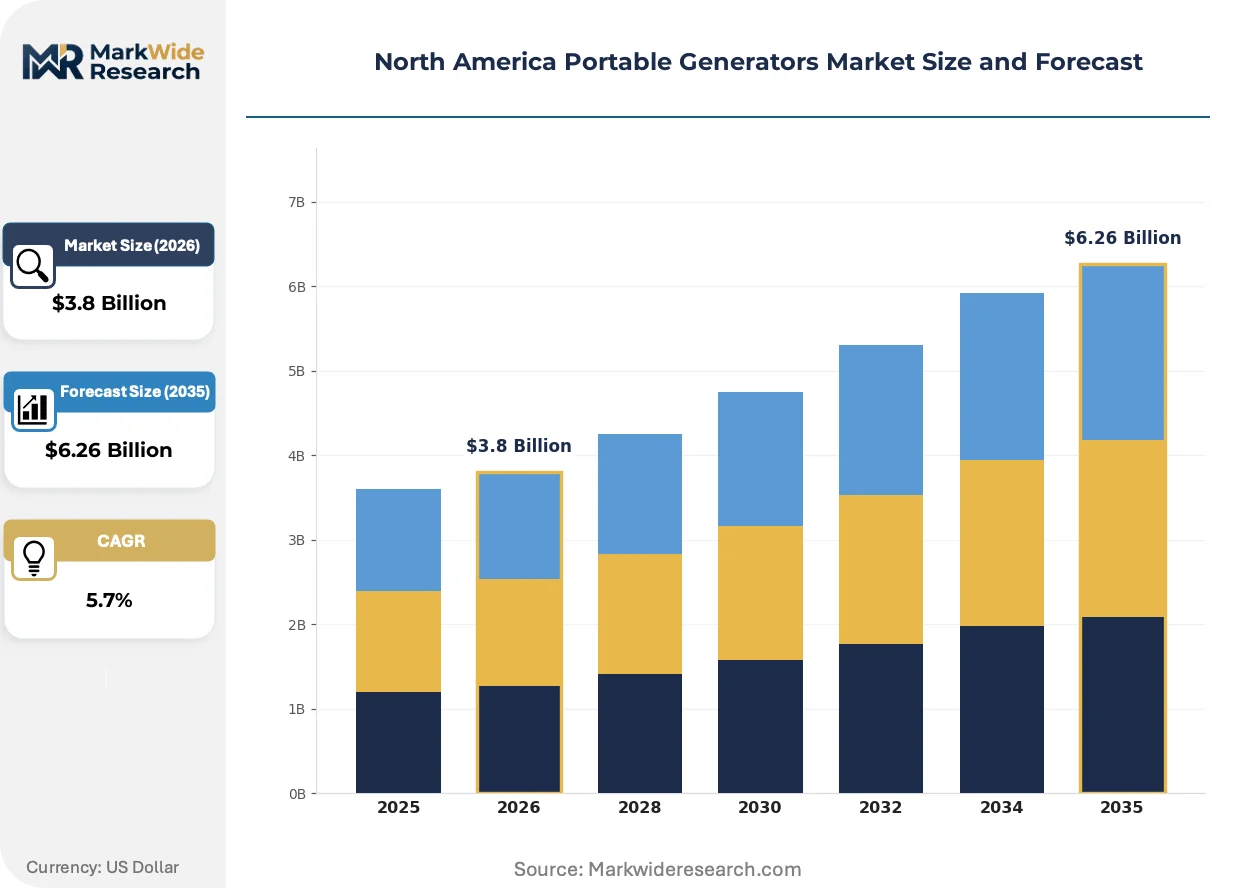
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Generators, Diesel Generators, Solar Generators, Dual Fuel Generators Application: Event Power, Emergency Backup, Recreational Use, Construction Sites End User: Residential Users, Contractors, Event Organizers, Campsites Power Rating: 500W-1000W, 1000W-3000W, 3000W-5000W, Above 5000W |
| Companies Covered | Generac Holdings Inc., Caterpillar Inc., Cummins Inc., Briggs & Stratton Corporation, Honda Motor Co. Ltd, Kohler Co., Yamaha Motor Co. Ltd, Champion Power Equipment Inc, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Portable Generators Market Emerging Trajectories
Smart load management and bidirectional charging capabilities are redefining portable generator value propositions beyond raw wattage output toward integrated home energy ecosystem participation.
Inverter generator technology is automating voltage stabilization and harmonic distortion reduction through microprocessor-controlled power conditioning. Residential buyers in noise-restricted subdivisions are specifying these units for recreational and backup applications at accelerating rates. The technology is automating the displacement of conventional alternator architectures in sub-5000W residential segments.
California Air Resources Board zero-emission equipment mandates are prohibiting gasoline generator sales in state-procured contracts and select air quality management districts. Manufacturers are reallocating R&D capacity toward lithium-iron-phosphate battery platforms and solar charging integration. Construction contractors operating in Los Angeles and San Diego metro areas are pre-positioning solar generator fleets to maintain bid eligibility on public works.
Fleet procurement by national rental houses is compressing replacement cycles and unbundling maintenance from equipment ownership. Independent rental operators in Texas and Florida are losing share to branded national chains with standardized spec sheets and volume purchasing leverage. This concentration is most visible in the 3000W-5000W contractor segment where runtime reliability drives repeat rental contracts.
North America Portable Generators Market Segmentation
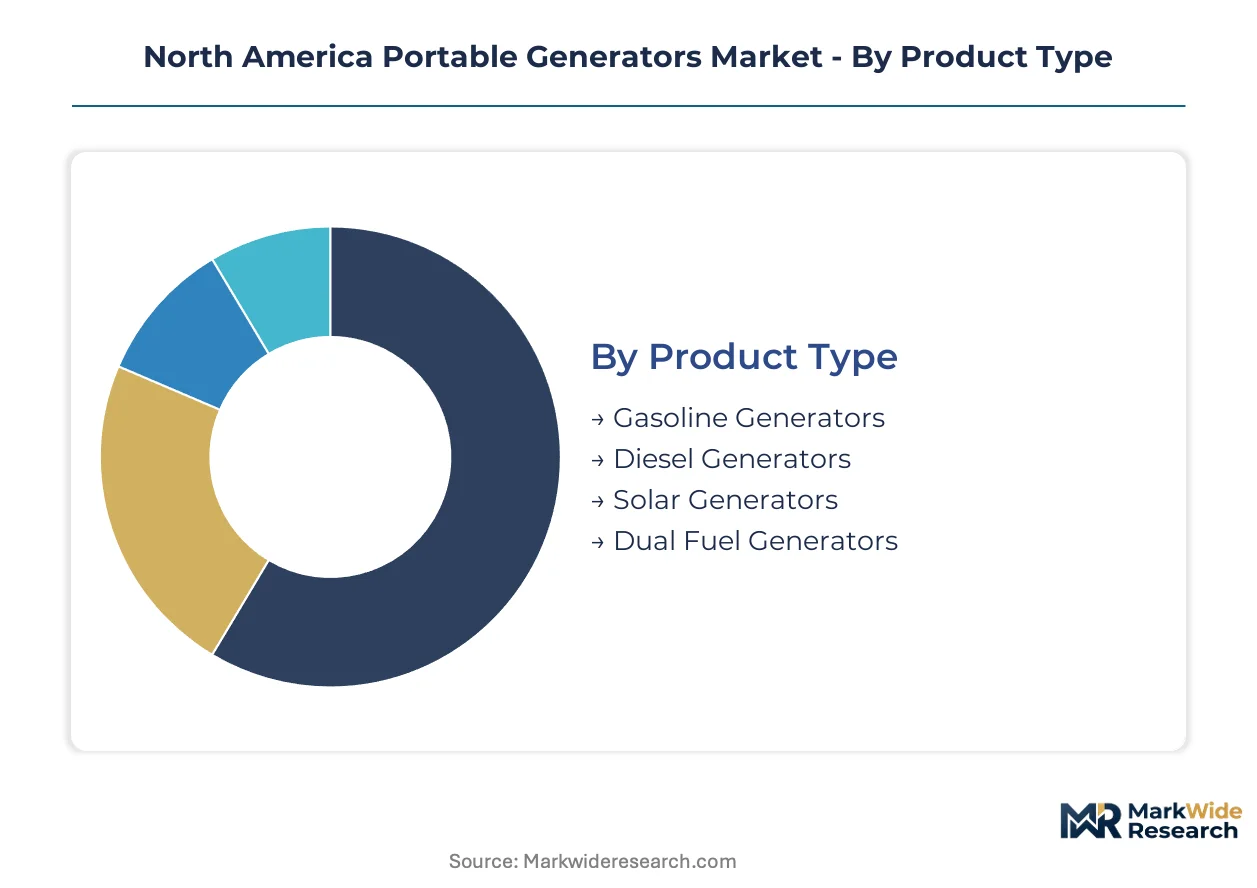
Portable generator purchasing decisions pivot on runtime requirements, noise restrictions, and fuel accessibility across distinct use environments. Segmentation reveals how EPA Tier 4 compliance costs and CARB zero-emission mandates are fragmenting product architectures into parallel supply chains. Understanding these divides enables manufacturers to align R&D allocation with margin concentration zones.
Product Type:
Buyers prioritize fuel availability and first-cost thresholds when selecting combustion versus electric architectures.
- Gasoline Generators:Carbureted small engines deliver 500W to above 5000W outputs using widely available fuel. Residential buyers across Texas, Florida, and Louisiana hurricane corridors favor these units for emergency backup due to lower upfront investment and established dealer service networks.
- Solar Generators:Lithium-ion battery platforms with photovoltaic charging integration provide silent, zero-emission operation. California contractors pre-position these fleets to maintain bid eligibility on Los Angeles and San Diego public works projects under CARB zero-emipment mandates.
- Diesel Generators:Compression-ignition architectures excel in commercial-grade construction applications requiring extended runtime durability.
- Dual Fuel Generators:Propane-gasoline flexibility hedges fuel supply disruptions during extended grid outages.
Gasoline generators lead on installed base scale; solar generators lead on regulatory momentum.
Application:
Runtime continuity requirements and noise sensitivity thresholds differentiate specification priorities across deployment contexts.
- Emergency Backup:Automatic transfer switch compatibility and cold-start reliability dominate residential procurement in hurricane-prone coastal counties. Texas and Florida buyers accelerate replacement cycles ahead of storm seasons, concentrating demand in the 3000W-5000W band for whole-home circuit coverage.
- Construction Sites:OSHA ground-fault protection and ventilation protocol compliance elevate specification requirements for contractor-grade units. Diesel platforms above 25 horsepower face Tier 4 particulate filter cost burdens that compress margins on long-runtime job sites.
- Event Power:Inverter technology with harmonic distortion reduction serves noise-restricted festival and outdoor entertainment venues.
- Recreational Use:Sub-3000W portability and quiet operation drive RV and camping channel demand.
Emergency backup leads on revenue concentration; event power leads on specification premium capture.
End User:
Procurement scale and maintenance capability determine whether buyers favor ownership versus rental models.
- Contractors:National construction firms consolidate fleet purchases through branded rental chains with standardized spec sheets and volume purchasing leverage. These buyers prioritize runtime reliability and OSHA compliance documentation over first-cost minimization.
- Residential Users:Dispersed individual purchasers across coastal states drive seasonal demand spikes, with repeat purchase cycles accelerating following major grid failure events.
- Event Organizers:Festival operators specify inverter units for noise-sensitive outdoor entertainment deployments.
- Campsites:RV dealers represent underpenetrated distribution for sub-3000W solar generator SKUs.
Contractors lead on procurement volume consolidation; residential users lead on cyclical demand volatility.
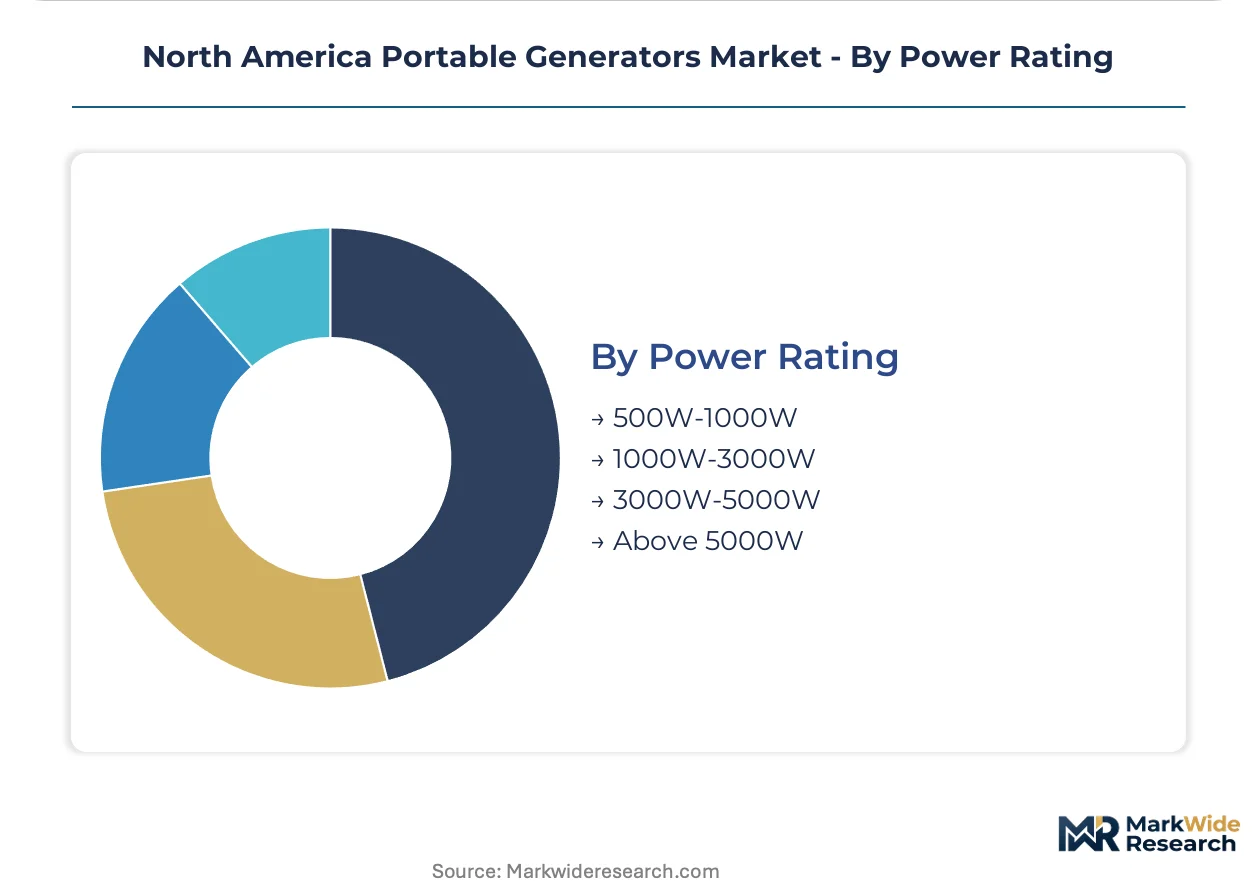
Power Rating:
Transportability constraints and load diversity requirements shape wattage band selection across mobile versus stationary applications.
- 3000W-5000W:This band balances contractor runtime requirements with transportability constraints, capturing the dominant margin pool. National rental houses concentrate replacement cycles and fleet standardization in this range.
- 1000W-3000W:Recreational vehicle and camping applications favor these lighter units where noise restrictions and portability outweigh extended runtime needs.
- 500W-1000W:Compact personal electronics charging dominates this entry tier.
- Above 5000W:Stationary standby systems and heavy commercial applications occupy this upper band.
The 3000W-5000W band leads on margin concentration; sub-3000W segments lead on channel expansion velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled small-engine technicians and emissions calibration specialists concentrate in the Great Lakes manufacturing corridor and southeastern dealer networks, anchoring North America's portable generator supply base.
United States
Texas, Florida, and Louisiana residential buyers accelerate repeat purchase cycles ahead of hurricane seasons, concentrating demand in the 3000W-5000W band. EPA Tier 4 standards constrain small-engine designs and elevate compliance costs for gasoline architectures. Houston and Miami serve as primary distribution hubs where national rental chains standardize fleet specifications.
Canada
Remote resource extraction camps and northern indigenous communities drive diesel generator procurement for off-grid reliability. Health Canada and Environment Canada enforce emissions standards aligned with EPA baselines, reducing SKU complexity for cross-border manufacturers. Alberta's oil sands region and Ontario's mining belt anchor commercial-grade demand concentration.
Mexico
Construction sector expansion in Mexico City and Monterrey metro areas elevates contractor-grade unit imports from US assembly plants. PROFEPA environmental enforcement remains less stringent than CARB thresholds, enabling federal-compliant SKU distribution without California-grade modifications. Baja California and Sonora border states experience cross-border retail leakage from US dealer networks.
North America Portable Generators Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the North America Portable Generators Market, creating a tiered structure where scale-driven manufacturers anchor volume segments and niche specialists capture specification premiums. The vendor base separates into three strategic archetypes: integrated power systems conglomerates with multi-fuel portfolios, dedicated portable equipment specialists with concentrated distribution, and diversified engine manufacturers leveraging vertical component control. Competitive moves concentrate on M&A-driven portfolio expansion and strategic partnerships with national rental chains to secure fleet standardization contracts.
Within the integrated power systems tier, Generac Holdings Inc. and Cummins Inc. exemplify scale-driven positioning through extensive dealer network density and commercial-grade platform breadth. Honda Motor Co. Ltd anchors the specialist archetype with technology-focused differentiation. These three companies represent the dominant competitive anchors shaping procurement standards across residential, contractor, and recreational application segments.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Caterpillar Inc. |
| Cummins Inc. |
| Briggs & Stratton Corporation |
| Honda Motor Co. Ltd |
| Kohler Co. |
| Yamaha Motor Co. Ltd |
| Champion Power Equipment Inc |
| Atlas Copco AB |
| Others |
Supply Flow & Price Mechanics
CARB-federal SKU bifurcation creates parallel cost structures that manufacturers must navigate through dual inventory pipelines and separate certification investments. This regulatory divergence concentrates pricing power with incumbents who can absorb compliance overhead while compressing margins for smaller players forced to choose between California exclusion or federal-only positioning.
Pricing Analysis
Capacity additions in Southeast Asian carburetor manufacturing are reshaping price floors for gasoline generator architectures. Three-tier pricing structure across CARB-certified premium, federal-compliant standard, and economy import levels reflects certification investment recovery and warranty bundling differentiation. Pricing pressure stems from lithium-ion battery cost compression eroding gasoline unit cost advantages in California zero-emission zones. Residential buyers in hurricane-prone coastal states exhibit highest price sensitivity, while national contractors prioritize runtime reliability over first-cost minimization.
Supply Chain Analysis
Freight cost volatility from Southeast Asian component hubs to US assembly plants elevates working capital requirements for just-in-time carburetor and ignition system sourcing. Manufacturing concentrates in China, Vietnam, and Thailand for small-engine components, with final assembly anchored in US Great Lakes and southeastern states. Raw material dependencies span aluminum castings, copper windings, and rare-earth magnets for alternator assemblies. Single-source vulnerability concentrates in specialized emissions calibration testing capacity. Distribution runs through dealer networks, national rental chains, and direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers can exploit the eighteen-to-twenty-four-month CARB certification timeline differential by pre-positioning federal-compliant inventory ahead of California mandate expansion.
For Market Incumbents: To counter lithium-ion battery platform displacement in California public procurement, anchor defensive positioning through captive control over EPA-certified small-engine production capacity in the Great Lakes corridor. Prioritize certification investment acceleration to compress California-bound SKU development timelines. Secure exclusive fleet standardization contracts with national rental chains to lock in contractor-grade volume commitments before solar generator bid eligibility expands. For New Entrants and Emerging Players: Solar-electric inverter technology offers the most penetrable wedge for California contractor market entry ahead of zero-emission mandate enforcement expansion. Target underpenetrated RV dealer distribution channels for sub-3000W lithium-iron-phosphate SKUs where incumbent gasoline generator shelf presence remains dominant. Pursue direct-to-consumer digital-native positioning with integrated solar charging bundles to bypass established dealer network barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-SKU inventory complexity strains working capital for mid-tier manufacturers lacking California certification infrastructure. Long-term viability favors vertically integrated engine producers with captive emissions testing capabilities and multi-fuel platform portfolios. Acquisition target archetype: regional specialists with established CARB certification pipelines and underutilized southeastern dealer networks. Monitor California Air Resources Board zero-emission equipment mandate expansion timelines as primary inflection indicator for gasoline generator demand displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Certification Pipeline Investment | Accelerates California market access ahead of zero-emission mandate expansion. |
| Lithium-Iron-Phosphate Platform Development | Positions manufacturers for Los Angeles and San Diego public works bid eligibility. |
| National Rental Chain Partnership | Secures fleet standardization contracts in the 3000W-5000W contractor segment. |
| RV Dealer Channel Expansion | Captures underpenetrated recreational demand for sub-3000W solar generator SKUs. |
| Dual-Fuel Architecture Launch | Hedges fuel supply disruption risk for Texas and Florida hurricane corridor buyers. |
Methodological Framework
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The approach combines structured interviews with generator manufacturer product managers, national rental chain procurement directors, EPA and CARB compliance consultants, and southeastern US dealer network operators. Secondary validation draws from EPA certification databases, CARB executive orders, EIA electricity reliability reports, and SEC filings of publicly traded power equipment manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Granularity-level framing applies separate modeling for gasoline, solar, diesel, and dual-fuel product architectures. Segmentation dimensions include power rating bands, application contexts, and end-user procurement models. CAGRs derive from regression analysis of historical replacement cycle data and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate hurricane season grid failure frequency indices and lithium-ion battery cost decline curves.
The model holds under stable EPA Tier 4 enforcement and gradual CARB zero-emission mandate expansion; deviation in federal environmental policy rollback or accelerated California mandate timelines would shift demand trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Industrial Generator Market
Generators
Heat Recovery System Generator Market
Generators
Generator Rental Market
Generators
China Generator Sets Market
Generators
Europe Gas Turbine Market
Generators
South America Diesel Generator Market
Generators
North America Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Europe Gas Generator Market
Generators
Gas Generator Market
Generators
Portable Inverter Generators Market
Generators
Telecom Generator Market
Generators
Global Diesel Gensets Market
Generators
China Gas Generator Market
Generators
North West Europe Diesel Generator Market
Generators
Railway Generators Market